
 Nanoelectronics Market | 2026-2036
Nanoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoelectronics Market Outlook
ISO 14644 cleanroom certification is collapsing the supplier base for advanced node production, leaving only capital-intensive operators capable of sustained compliance. Intel Corporation leverages its IDM model to anchor wafer fabrication and packaging within controlled environments. IBM competes through materials science leadership in gate-all-around transistor architectures. STMicroelectronics specializes in automotive-grade nanoelectronics where qualification cycles extend beyond consumer timelines.
Nanoelectronics encompasses devices and systems engineered with feature dimensions below 100 nanometers, typically fabricated through extreme ultraviolet lithography operating at 13.5nm wavelength to pattern silicon wafers with atomic-scale precision. These structures enable higher transistor density, reduced power leakage, and faster switching speeds essential for computational workloads. Nanochips dominate current revenue as logic and memory manufacturers push process nodes toward physical limits, while nanosensors capture expanding share in biomedical and environmental monitoring where sensitivity thresholds improve with scale reduction. Quantum dots represent the fastest-growing product category as display manufacturers adopt cadmium-free formulations for quantum-enhanced color volume.
The EPA regulates perfluorinated compound emissions from semiconductor etching processes, forcing fabs to install abatement systems or reformulate chemistries. REACH restricts hazardous substances in nanomaterial supply chains, affecting EU-based packaging and interconnection vendors. FDA oversight of nanoelectronic medical devices creates dual-track approval requirements for healthcare applications. Stakeholders must weigh sovereign subsidy conditions against the technical constraints of existing equipment ecosystems when committing to new fabrication geography.
Market Dynamics
Sub-3nm node migration is concentrating capital among operators capable of sustaining EUV lithography ecosystems, while sovereign subsidy programs rewire geographic deployment of fabrication capacity.
Growth Catalysts
- AI Accelerator Demand:Hyperscale data centers in Taiwan and South Korea are commissioning dedicated foundry capacity for transformer-optimized silicon, pulling forward node transitions.
- EU Chips Act:The subsidy framework is redirecting European capital toward domestic 2nm pilot lines, with Dresden and Grenoble emerging as qualification hubs for automotive-grade output.
- Gate-All-Around Transistors:This architecture reduces leakage current at atomic scales, enabling foundries to extend Moore's Law scaling without radical material substitutions.
Market Restraints
- EUV Tool Scarcity:ASML's annual output of high-NA lithography systems caps at single-digit units, creating multi-year order backlogs for sub-2nm production.
- Perfluorinated Compound Abatement:EPA emissions rules force fabs to install thermal scrubbers or reformulate etch chemistries, adding operational complexity without yield improvement.
- Neuromorphic Architectures:Analog in-memory computing approaches threaten to displace digital nanoelectronics in edge inference workloads where power budgets are absolute constraints.
Strategic Opportunities
- India Semiconductor Mission:The PLI scheme and Dholera fab cluster offer greenfield entry for mature-node packaging and heterogeneous integration services.
- Cadmium-Free Quantum Dots:Display manufacturers are qualifying indium phosphide formulations for quantum-enhanced color volume in premium television panels.
- Biomedical Nanosensors:Glucose monitoring and liquid biopsy applications are driving demand for CMOS-compatible electrochemical sensors with femtomolar sensitivity thresholds.
Industry Challenges
- Atomic-Scale Metrology Talent:The intersection of cryogenic microscopy and computational lithography requires specialists trained at fewer than twelve global institutions.
- ISO 14644 Cleanroom Certification:Qualification timelines for Class 1 environments extend eighteen to twenty-four months, gating capacity expansion regardless of capital availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoelectronics Market |
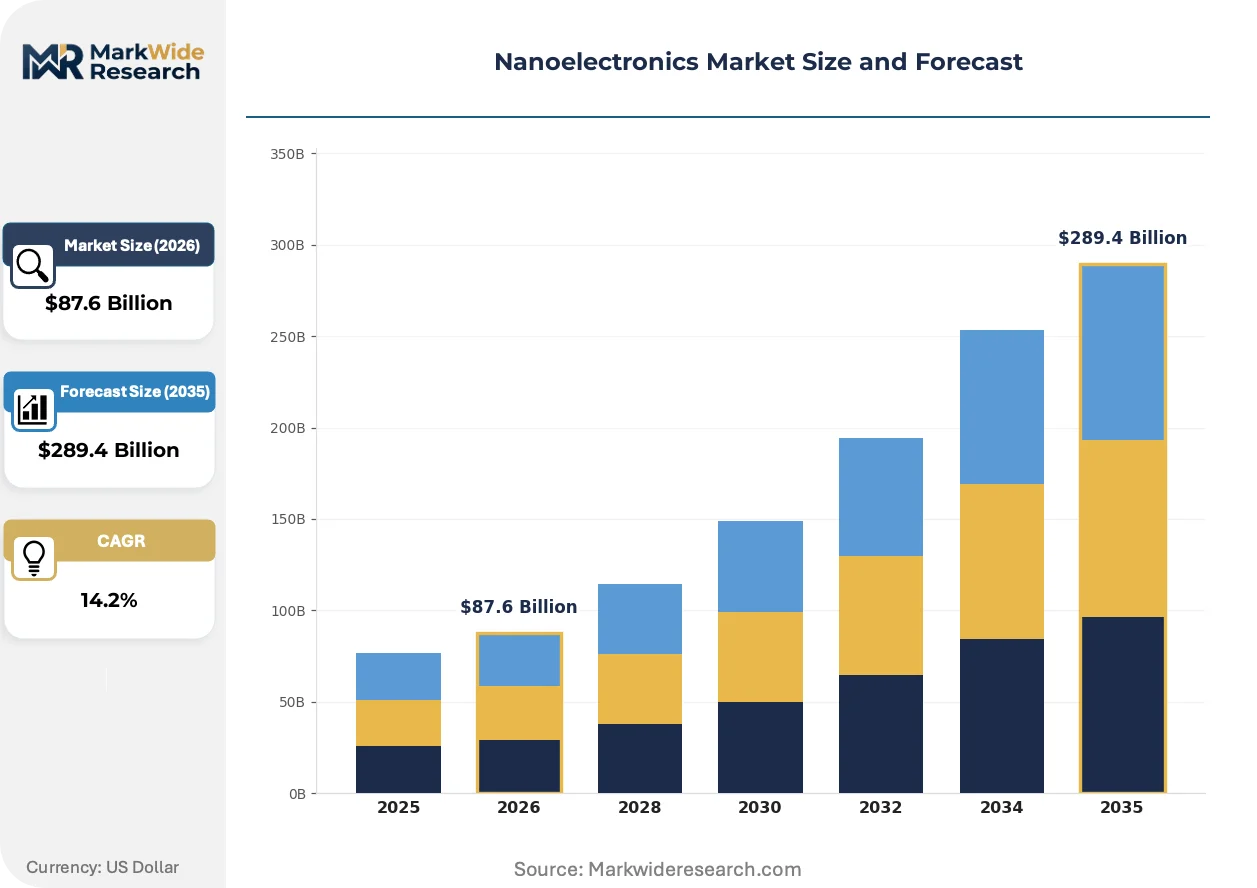
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanochips, Quantum Dots, Nanosensors, Nanotransistors Technology: Electron Beam Lithography, Photolithography, Nanoimprint Lithography, Molecular Beam Epitaxy End User: Consumer Electronics, Healthcare, Telecommunications, Automotive Application: Data Storage, Communication Systems, Imaging Systems, Energy Harvesting |
| Companies Covered | Intel Corporation, IBM, STMicroelectronics, Infineon Technologies AG, Koninklijke Philips N.V, Siemens AG, Robert Bosch GmbH, Everspin Technologies Inc., HP Development Company L.P., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoelectronics Market Strategic Shifts
Process-material convergence and sovereign production mandates are restructuring how nanoelectronics capability is distributed geographically and technologically.
Hybrid bonding is supplanting solder microbumps in advanced packaging architectures. Memory and logic manufacturers in South Korea and Taiwan are adopting copper-to-copper direct bonding for 3D stacking at sub-10 micron pitch. This interconnect approach is compressing power-performance-area metrics for high-bandwidth memory integration with AI accelerators.
REACH substance restrictions are forcing reformulation of nanomaterial supply chains for EU-based packaging vendors. The ECHA authorization requirements affect indium tin oxide alternatives and silver nanowire transparent conductors. Automotive display and sensor manufacturers are accelerating qualification of compliant formulations to avoid market exclusion.
Consolidated procurement by hyperscale cloud operators is compressing foundry negotiation cycles from annual to quarterly cadences. Tier-one semiconductor buyers in the United States are demanding dedicated capacity reservations with penalty clauses for volume shortfalls. This contract structure is most visible in AI training chip procurement where supply security outweighs unit cost optimization.
Nanoelectronics Market Segmentation
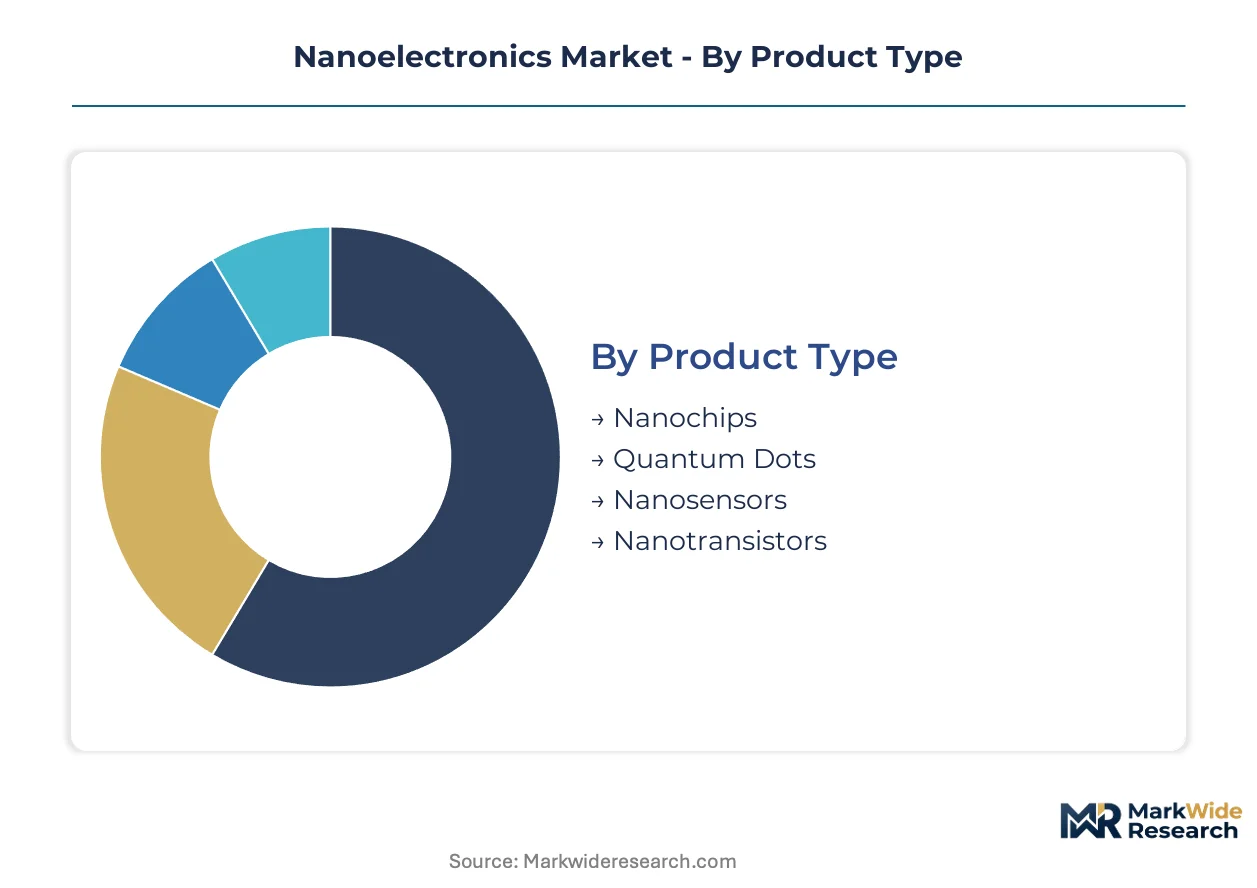
Nanoelectronics segmentation reveals how fabrication complexity and application requirements split demand across distinct procurement channels. Each dimension—product architecture, patterning technology, end-use sector, and functional application—creates separate qualification hurdles and margin structures.
Product Type:
Channel flow varies sharply: nanochips and nanotransistors move through foundry-direct contracts with hyperscale buyers, while quantum dots and nanosensors distribute through specialty chemical distributors and medical device component suppliers.
- Nanochips:Logic and memory devices fabricated at sub-3nm nodes through EUV lithography enable transistor densities exceeding 200 million per square millimeter. Hyperscale data centers in Taiwan and South Korea now contract dedicated foundry capacity for transformer-optimized silicon, pulling forward node transitions and compressing procurement cycles to quarterly cadences.
- Quantum Dots:Semiconductor nanocrystals with tunable emission spectra engineered through colloidal synthesis or vapor-phase deposition. Display manufacturers in South Korea are qualifying cadmium-free indium phosphide formulations for premium television panels, driven by REACH substance restrictions and consumer electronics sustainability mandates.
- Nanosensors:CMOS-compatible electrochemical and optical transducers with femtomolar sensitivity thresholds serve biomedical and environmental monitoring applications. FDA oversight of nanoelectronic medical devices creates dual-track approval requirements for glucose monitoring and liquid biopsy implementations.
- Nanotransistors:Gate-all-around and finFET architectures reduce leakage current at atomic scales, extending Moore's Law scaling without radical material substitutions for AI accelerator workloads.
By volume, nanochips lead procurement across all channels. By growth pace, quantum dots are climbing the fastest as display manufacturers pivot to cadmium-free formulations.
Technology:
Cost tier separation is pronounced: electron beam and molecular beam epitaxy systems serve research and prototype volumes at premium pricing, while photolithography and nanoimprint handle high-volume manufacturing at depreciated capital cost structures.
- Electron Beam Lithography:Direct-write patterning using focused electron beams achieves sub-10nm resolution without photomasks, essential for photonic device prototyping and academic research. ASML's single-digit annual output of high-NA EUV systems has extended lead times for production-scale alternatives, preserving e-beam's role in early-stage development despite throughput limitations.
- Photolithography:Optical patterning at 193nm immersion and 13.5nm EUV wavelengths dominates logic and memory fabrication. Taiwan Semiconductor Manufacturing and Samsung Foundry have locked multi-year capacity reservations for high-NA EUV tools, capping availability for secondary buyers and concentrating sub-2nm production among capital-intensive operators.
- Nanoimprint Lithography:Mechanical pattern transfer through embossed templates offers cost advantages for photonic and display applications where defect tolerance exceeds semiconductor standards.
- Molecular Beam Epitaxy:Ultra-high vacuum deposition of single-crystal films enables precise heterostructure engineering for quantum dot and high-electron-mobility transistor fabrication.
Photolithography commands the largest installed base. Nanoimprint is gaining share fastest in non-semiconductor applications where throughput economics favor template-based replication.
End User:
Customer type determines qualification intensity: consumer electronics demands rapid iteration cycles, while automotive and healthcare impose extended certification timelines that favor established suppliers with ISO 14644 cleanroom credentials.
- Consumer Electronics:Smartphones, tablets, and wearables drive volume demand for advanced node logic and memory. Apple and Samsung Electronics compress foundry negotiation cycles through consolidated procurement, demanding dedicated capacity reservations with penalty clauses for volume shortfalls.
- Healthcare:Implantable devices, diagnostic equipment, and drug delivery systems require biocompatible packaging and FDA 510(k) or PMA approvals. STMicroelectronics has specialized in automotive-grade nanoelectronics where qualification cycles extend beyond consumer timelines, leveraging this capability for medical device partnerships.
- Telecommunications:Baseband processors and optical transceivers for 5G and 6G infrastructure require RF-optimized process nodes and heterogeneous integration of compound semiconductors with silicon.
- Automotive:ADAS processors, battery management systems, and in-vehicle networking demand AEC-Q100 qualification and zero-defect traceability through ISO 26262 functional safety frameworks.
Consumer electronics generates the highest unit volumes. Healthcare is expanding most quickly as remote patient monitoring and point-of-care diagnostics drive sensor integration.
Application:
Maturity gradient separates established from emerging demand: data storage and communication systems operate at scale with depreciated process technology, while imaging systems and energy harvesting push toward novel materials and architectures.
- Data Storage:NAND flash and emerging resistive RAM technologies exploit three-dimensional stacking through hybrid bonding to achieve terabit-scale densities. South Korean memory manufacturers have adopted copper-to-copper direct bonding for 3D stacking at sub-10 micron pitch, compressing power-performance-area metrics.
- Communication Systems:RF front-ends, baseband processors, and optical transceivers integrate silicon photonics with CMOS logic for bandwidth expansion. Intel Corporation leverages its IDM model to anchor wafer fabrication and packaging within controlled environments for this segment.
- Imaging Systems:CMOS image sensors with backside illumination and stacked architectures enable computational photography and machine vision. Sony and OmniVision compete through pixel-scale innovations in quantum efficiency and dynamic range.
- Energy Harvesting:Thermoelectric and piezoelectric nanogenerators convert ambient thermal and mechanical energy to electrical power for wireless sensor networks.
Data storage leads by wafer consumption. Energy harvesting is advancing most rapidly as IoT deployment creates demand for battery-free operation in remote monitoring applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data centers in Taiwan and South Korea commission dedicated foundry capacity for transformer-optimized silicon, while sovereign subsidy programs redirect European capital toward domestic pilot lines.
United States
Intel Corporation anchors wafer fabrication and packaging within controlled environments for AI accelerator workloads. The EPA regulates perfluorinated compound emissions from semiconductor etching processes, forcing fabs to install thermal scrubbers. Greater Phoenix and Hillsboro host advanced node production facilities where gate-all-around transistor architectures extend Moore's Law scaling.
Taiwan
Semiconductor foundries scale production of sub-3nm node chips for artificial intelligence accelerators, pulling forward node transitions. The absence of domestic emissions regulations comparable to REACH allows faster chemistry iteration. Hsinchu Science Park concentrates EUV lithography ecosystems where TSMC has locked multi-year capacity reservations for high-NA tools.
South Korea
Memory and logic manufacturers adopt copper-to-copper direct bonding for 3D stacking at sub-10 micron pitch. The MFDS maintains oversight of nanoelectronic medical devices, creating dual-track approval requirements. Pyeongtaek and Hwaseong host heterogeneous integration facilities where Samsung Foundry compresses power-performance-area metrics for high-bandwidth memory.
Germany
Automotive-grade nanoelectronics demand extends qualification cycles beyond consumer timelines, favoring established suppliers. REACH restricts hazardous substances in nanomaterial supply chains, affecting packaging and interconnection vendors. Dresden emerges as a qualification hub for automotive-grade output under the EU Chips Act subsidy framework.
India
The PLI scheme and Dholera fab cluster offer greenfield entry for mature-node packaging and heterogeneous integration services. BIS certification requirements apply to imported semiconductor manufacturing equipment. Gujarat and Karnataka host emerging design centers where domestic talent pools support CMOS-compatible electrochemical sensor development.
Nanoelectronics Market Competitive Environment
Player mix skews toward integrated device manufacturers and capital-intensive foundry operators capable of sustaining EUV lithography ecosystems. The supplier base collapses under ISO 14644 cleanroom certification requirements, leaving only operators with eighteen-to-twenty-four-month qualification timelines. Strategic archetypes include IDM-anchored full-stack providers, automotive-grade specialists with extended qualification cycles, and materials-science leaders in gate-all-around architectures. Dominant competitive moves center on multi-year capacity reservations with penalty clauses and sovereign subsidy capture for domestic pilot line deployment.
Among US-based technology conglomerates, Intel Corporation and IBM occupy positions at opposite ends of the value chain archetype spectrum. Intel exemplifies the IDM-anchored model through captive wafer fabrication and packaging integration. IBM represents materials-science leadership in transistor architecture innovation. STMicroelectronics, a Geneva-registered semiconductor company, sits within the automotive-grade specialist tier where qualification cycles extend beyond consumer electronics timelines. These three entities collectively illustrate how competitive positioning fragments across fabrication scale, materials IP, and end-market certification intensity.
| Leading Market Players |
|---|
| Intel Corporation |
| IBM |
| STMicroelectronics |
| Infineon Technologies AG |
| Koninklijke Philips N.V |
| Siemens AG |
| Robert Bosch GmbH |
| Everspin Technologies Inc. |
| HP Development Company L.P. |
| Others |
Value Chain & Pricing Dynamics
Copper-to-copper hybrid bonding substitution for solder microbumps simultaneously redraws supply geography toward South Korean and Taiwanese memory manufacturers while compressing power-performance-area pricing premiums at sub-10 micron pitch. This interconnect transition concentrates advanced packaging procurement among operators with locked high-NA EUV capacity reservations, amplifying cost pass-through power for capital-intensive foundries.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate foundry-direct procurement for AI accelerator silicon. Three-tier pricing structure across premium node, standard node, and mature node levels separates hyperscale buyers with dedicated capacity reservations from spot-market purchasers. Pricing pressure stems from ASML's single-digit annual high-NA EUV output capping sub-2nm availability. Consumer electronics buyers exhibit highest price sensitivity, while automotive-grade procurement accepts extended qualification timelines for supply security.
Supply Chain Analysis
Strategic stockpiling of EUV photoresists and high-purity gases supersedes just-in-time preferences as fabs buffer against ASML tool delivery volatility. Concentration in Taiwan, South Korea, and the United States anchors wafer fabrication, with Germany emerging under EU Chips Act subsidies. Supply chains draw from neon gas extraction in Ukraine, fluorinated chemistries from Japan, and silicon wafers from Japan and Germany. Single-source vulnerability around high-NA lithography systems creates multi-year order backlogs. Distribution runs through foundry-direct contracts with hyperscale cloud operators and specialty chemical distributors for quantum dot formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analog neuromorphic architectures threaten displacement of digital nanoelectronics in edge inference workloads, forcing incumbents to defend process-node value propositions against in-memory computing substitutes.
For Market Incumbents: Fortify gate-all-around transistor IP positions through materials science partnerships, and secure multi-year high-NA EUV capacity reservations with penalty clauses before secondary buyers enter queue. Prioritize ISO 14644 Class 1 cleanroom qualification timelines to collapse competitor supply base.
For New Entrants and Emerging Players: Differentiate on cadmium-free quantum dot formulations for REACH-compliant display supply chains, and target India's Dholera fab cluster for mature-node packaging services. Pursue biomedical nanosensor applications where FDA dual-track approval requirements favor specialized entrants over diversified incumbents.
For Investors and Strategic Acquirers: EU Chips Act subsidy disbursement milestones reshape the acquisition landscape toward automotive-grade specialists with Dresden or Grenoble qualification credentials. Five-to-ten-year viability hinges on sovereign production mandate durability. Target IDM-anchored operators with captive packaging integration. Watch for ASML high-NA tool delivery acceleration as inflection signal for sub-2nm capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| High-NA EUV Capacity Reservation | TSMC and Samsung Foundry lock multi-year tool allocations, capping competitor access to sub-2nm production. |
| Cadmium-Free Quantum Dot Qualification | Display manufacturers adopt indium phosphide formulations to satisfy REACH substance restrictions in EU markets. |
| Automotive-Grade Cleanroom Certification | STMicroelectronics leverages ISO 14644 Class 1 credentials for extended qualification cycle capture in ADAS silicon. |
| Heterogeneous Integration Facility Buildout | Intel Corporation anchors wafer fabrication and advanced packaging within controlled environments for AI accelerators. |
| Sovereign Subsidy Capture | Dresden and Grenoble emerge as EU Chips Act qualification hubs for domestic 2nm pilot line deployment. |
Study Parameters
Operator-level perspectives from foundry process engineers, EUV tool procurement directors, automotive semiconductor qualification leads, and nanomaterial supply chain managers anchored the qualitative base. Secondary validation drew from SEC filings of capital equipment manufacturers, ECHA REACH authorization databases, hyperscaler capex disclosures, and customs records of fluorinated gas imports. Bottom-up wafer demand modeling triangulated against top-down semiconductor capital expenditure tracking.
Sensitivity analysis tested node transition velocity, EUV tool delivery schedules, and sovereign subsidy disbursement timing across the analysis window. Segmentation dimensions included product architecture, patterning technology, end-use sector, and functional application. CAGRs derived from installed base depreciation curves and replacement demand cycles. Forecast inputs incorporated ASML order backlog data and EPA perfluorinated compound emission trajectory assumptions.
Decision-makers should treat outputs as directional under sustained EUV lithography ecosystem concentration and REACH compliance cost pass-through assumptions; material deviation would warrant model refresh. Revision becomes warranted when neuromorphic architecture commercialization crosses volume production thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Roll to Roll Flexible Electronics Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market