
 North America Wigig Market | 2026-2036
North America Wigig Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wigig Market Analytics
North American semiconductor fabs is realigning output toward millimeter-wave front-end modules as enterprise and carrier buyers lock in multi-year supply agreements. Qualcomm Technologies Inc. leverages its integrated modem-RF platform to dominate chipset design wins for indoor small cells. Broadcom Inc. sustains captive demand through backward integration into gallium arsenide substrate sourcing for 60 GHz power amplifiers. Intel Corporation anchors enterprise-class WiGig adapter volumes with channel partnerships across Dell and HP workstation lines.
WiGig denotes the IEEE 802.11ad/ay wireless standard operating in the unlicensed 60 GHz band, delivering multi-gigabit throughput across approximately 7 GHz of contiguous spectrum with beamforming-based link maintenance. The technology serves high-density indoor environments requiring cable-equivalent latency for wireless docking, AR/VR tethering, and server rack backhaul. Chipset and adapter segments command the deepest margin pools as OEMs consolidate around Qualcomm and Broadcom reference designs. Beamforming technology outpaces Ultra-Broadband in deployment velocity across North American data centers, while MIMO configurations remain concentrated in carrier trial networks awaiting full commercialization.
FCC Part 15 rules governing 60 GHz unlicensed operation shape transmit power and out-of-band emission limits across the United States, while ISED RSS-210 in Canada harmonizes equipment certification timelines with FCC test reports. The FCC further expanded 64-71 GHz access through recent rulemakings, pressuring manufacturers to retest existing SKUs for extended band compliance. Stakeholders must weigh spectrum fragmentation risk against the capital intensity of dual-certification strategies for cross-border product lines.
Market Dynamics
Enterprise data center interconnect builds across Northern Virginia, Dallas-Fort Worth, and Toronto are compressing deployment timelines as beamforming architectures displace legacy millimeter-wave backhaul solutions.
Growth Catalysts
- FCC Part 15 rules:Unlicensed 60 GHz band allocations in the United States eliminate spectrum licensing costs and accelerate indoor wireless backhaul deployment cycles.
- Data center interconnect:Hyperscale facility builds in Northern Virginia and Toronto metro corridors are absorbing early WiGig volume for server rack backhaul applications.
- Beamforming architectures:MIMO configurations with phased-array antennas are extending link reliability beyond legacy millimeter-wave alternatives in high-density indoor environments.
Market Restraints
- Gallium arsenide substrate concentration:Captive sourcing constraints for 60 GHz power amplifier substrates create supply bottlenecks concentrated among integrated device manufacturers.
- Dual-certification capital intensity:FCC Part 15 and ISED RSS-210 testing divergence forces manufacturers to maintain parallel compliance tracks for cross-border product lines.
- Line-of-sight propagation limits:Oxygen absorption at 60 GHz restricts outdoor deployment viability, constraining addressable market scope to indoor and short-range applications.
Strategic Opportunities
- AR/VR tethering applications:Wireless headset docking for enterprise training and design visualization represents an underpenetrated use case awaiting commercial scale.
- ISED spectrum harmonization:Canadian equipment certification timeline alignment with FCC test reports reduces barrier-to-entry for US-based suppliers expanding north.
- 802.11ay standard convergence:Channel bonding and improved modulation schemes are unifying chipset roadmaps across consumer and enterprise segments.
Industry Challenges
- Millimeter-wave RF engineering talent scarcity:Specialized design capabilities for phased-array antenna integration remain concentrated among a limited pool of experienced practitioners.
- Legacy Wi-Fi coexistence complexity:Enterprise IT departments face integration friction when deploying WiGig alongside existing 2.4/5 GHz infrastructure without seamless handoff protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wigig Market |
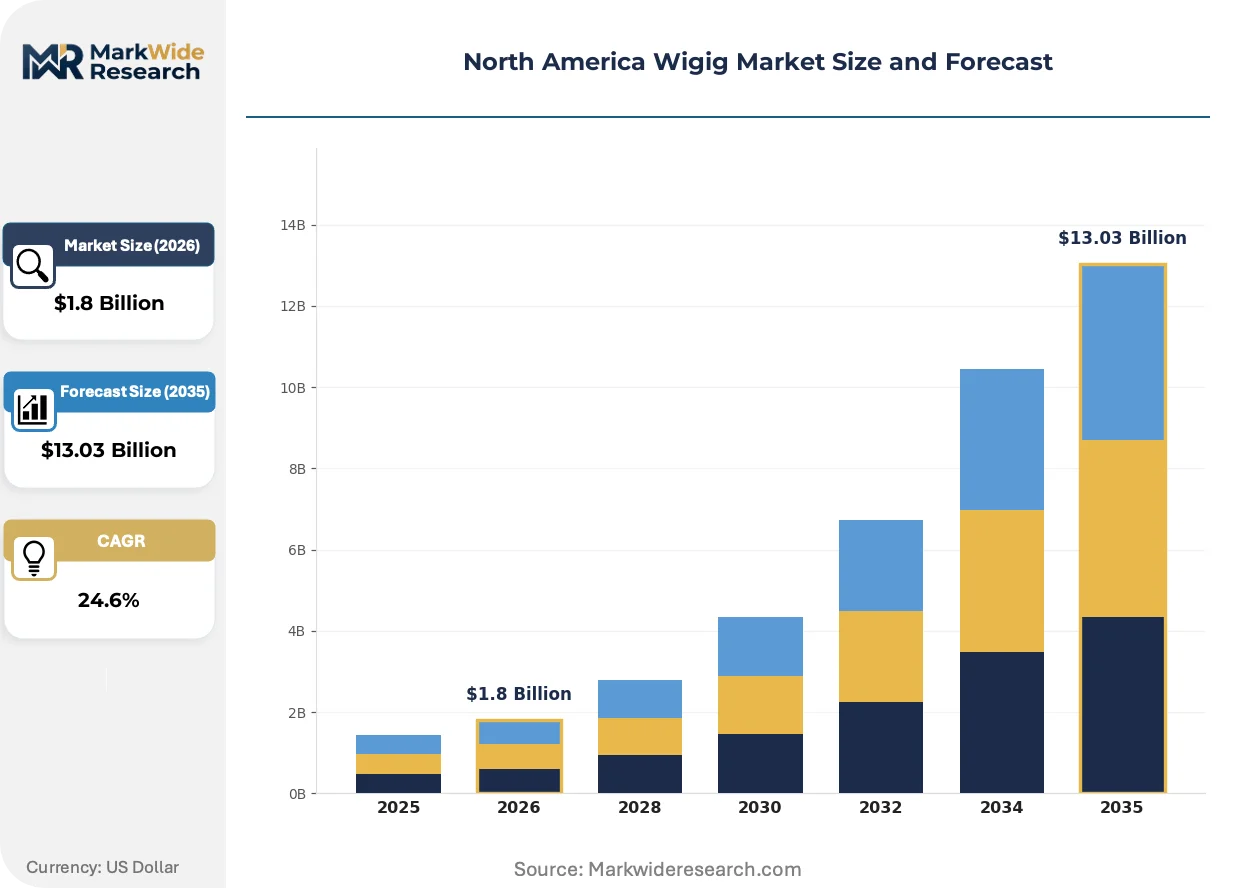
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Points, Routers, Chipsets, Adapters Technology: Wave 60 GHz, Ultra-Broadband, MIMO, Beamforming Application: Networking, Streaming, Virtual Reality, Data Centers End User: Consumer Electronics, Enterprises, Telecommunications, Healthcare |
| Companies Covered | Qualcomm Technologies Inc., Intel Corporation, Broadcom Inc., Cisco Systems Inc., Peraso Technologies Inc., MediaTek Inc., Texas Instruments Incorporated, Marvell Technology Group, Lattice Semiconductor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wigig Market Evolving Landscape
Beamforming and MIMO architectures are compressing the performance gap between wired and wireless backhaul, while regulatory harmonization efforts reshape cross-border equipment certification workflows.
802.11ay chipsets with 16QAM and 64QAM modulation schemes are unifying enterprise and consumer reference designs under common platform architectures. Dell and HP workstation lines are embedding these adapters for wireless docking deployments. This convergence is collapsing the historical segmentation between premium enterprise silicon and mass-market consumer variants.
FCC rulemakings expanding 64-71 GHz access are pressuring manufacturers to retest existing SKUs for extended band compliance. Equipment vendors must weigh spectrum fragmentation risk against the engineering cost of dual-band front-end modules. The United States market is absorbing the bulk of retooling costs as Canadian ISED policy lags by approximately one certification cycle.
Enterprise procurement teams are consolidating vendor relationships around integrated modem-RF platforms rather than discrete component sourcing. Channel partnerships between semiconductor suppliers and OEM workstation lines are displacing traditional distribution models for adapter volumes. This concentration is most visible across Northern Virginia and Dallas-Fort Worth data center corridors where multi-year supply agreements lock in chipset allocation priority.
North America Wigig Market Segmentation
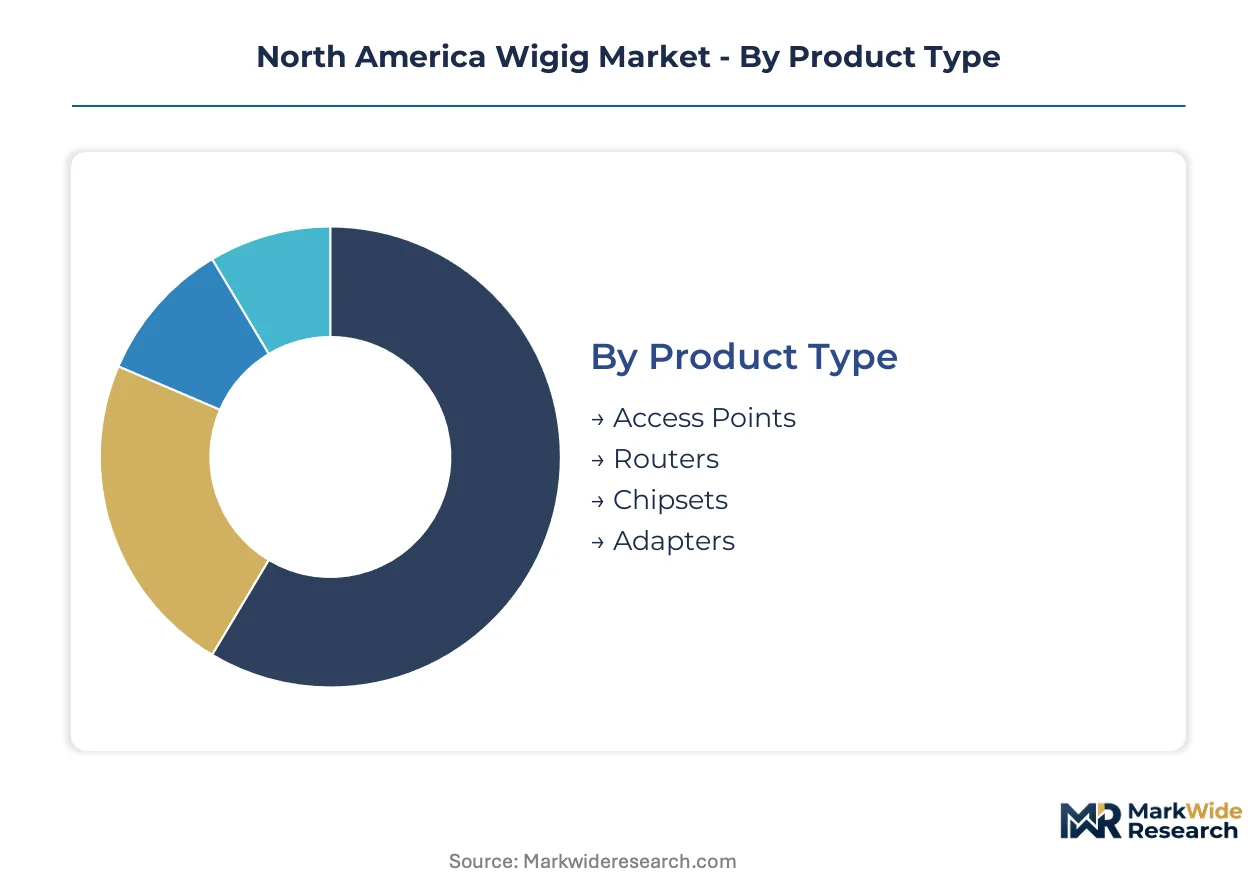
WiGig market segmentation reveals how capital deployment priorities diverge across hardware layers, RF architectures, use cases, and buyer categories. Each dimension carries distinct margin profiles and regulatory exposure that shape vendor strategy across the United States and Canada.
Product Type:
Capital intensity peaks at the semiconductor layer where gallium arsenide substrate sourcing and millimeter-wave front-end module fabrication demand the heaviest upfront investment.
- Chipsets:Integrated modem-RF platforms combine baseband processing with phased-array antenna control logic in single-die or multi-chip configurations. Northern Virginia hyperscale data center builds are locking in multi-year allocation agreements for these components as server rack backhaul demand compresses procurement timelines. Qualcomm and Broadcom reference designs dominate enterprise sockets through backward integration into substrate sourcing.
- Adapters:Peripheral modules embed 802.11ay PHY/MAC silicon with compact antenna arrays for workstation docking and AR/VR tethering. Dell and HP channel partnerships across Dallas-Fort Worth enterprise corridors are absorbing adapter volumes as wireless docking displaces Thunderbolt and USB-C cable infrastructure.
- Access Points:Indoor small cell infrastructure combining beamforming antennas with Ethernet backhaul for high-density coverage zones.
- Routers:Consumer and SOHO gateway devices integrating WiGig alongside legacy 2.4/5 GHz Wi-Fi for segmented spectrum operation.
Chipsets absorb the bulk of installed capacity; adapters are expanding most quickly through OEM workstation line partnerships.
Technology:
Deployment velocity varies sharply by RF architecture sophistication, with phased-array solutions commanding premium pricing against simpler Ultra-Broadband alternatives.
- Beamforming:Phased-array antenna systems dynamically steer 60 GHz signals to maintain link integrity despite physical obstructions. Data center interconnect builds across Toronto metro corridors are standardizing on beamforming for server rack backhaul as oxygen absorption limits drive indoor concentration.
- MIMO:Multiple-input multiple-output configurations exploit spatial multiplexing across independent RF chains for peak spectral efficiency. Carrier trial networks in the United States await full commercialization as FCC Part 15 power limits constrain outdoor propagation viability.
- Wave 60 GHz:Legacy single-carrier implementations predating 802.11ay channel bonding standardization.
- Ultra-Broadband:Lower-complexity alternatives for short-range consumer applications with relaxed latency requirements.
Beamforming captures dominant share in enterprise deployments; MIMO is climbing the fastest as carrier infrastructure trials advance toward commercial launch.
Application:
Latency tolerance thresholds segment the addressable market, with sub-millisecond requirements concentrating demand in data center and enterprise networking verticals.
- Data Centers:Server rack-to-rack and row-to-row backhaul demanding cable-equivalent latency with wireless flexibility. Northern Virginia and Dallas-Fort Worth hyperscale clusters are compressing deployment timelines as beamforming architectures displace legacy millimeter-wave solutions.
- Networking:Enterprise indoor wireless backhaul for campus and branch connectivity with deterministic throughput guarantees.
- Virtual Reality:Untethered headset docking for enterprise training and design visualization with high-resolution video transport.
- Streaming:Consumer wireless display and local content distribution with relaxed latency constraints.
Data centers absorb the bulk of installed capacity; virtual reality is gaining share fastest as commercial training applications scale.
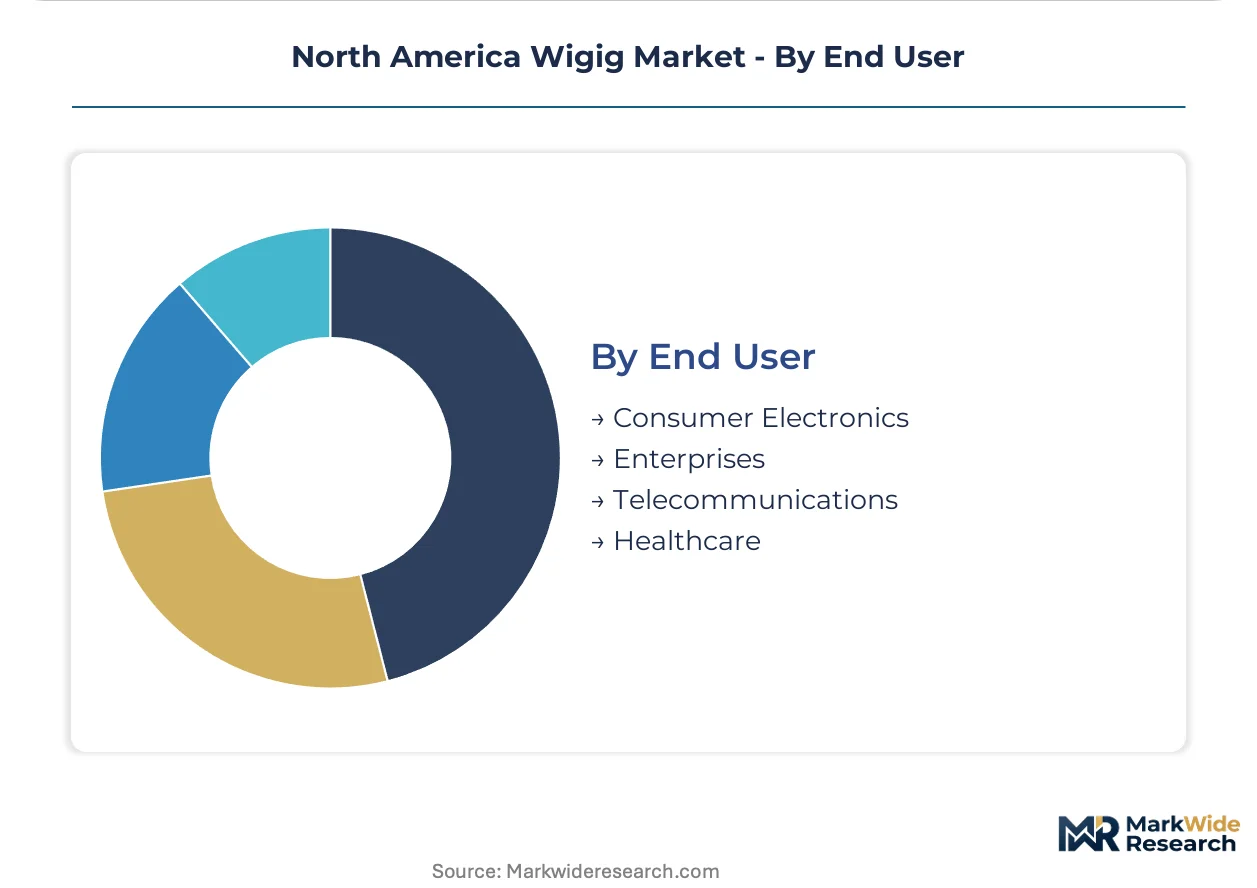
End User:
Procurement sophistication separates enterprise buyers with multi-year supply agreements from consumer electronics OEMs with spot-market component sourcing.
- Enterprises:Hyperscale operators and Fortune 500 IT departments with dedicated RF engineering teams and vendor consolidation strategies. Toronto and Northern Virginia data center corridors are locking in chipset allocation priority through direct semiconductor partnerships.
- Telecommunications:Carrier infrastructure divisions evaluating WiGig for indoor small cell densification and fixed wireless access trials.
- Consumer Electronics:OEM workstation and peripheral manufacturers embedding WiGig for wireless docking differentiation.
- Healthcare:Medical imaging and surgical visualization applications with stringent electromagnetic compatibility requirements.
Enterprises absorb the bulk of installed capacity; telecommunications is expanding most quickly as carrier trial networks mature toward commercial deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide substrate sourcing concentrates in the United States and Canada, with Canadian mineral processing facilities supplying raw material inputs for 60 GHz power amplifier fabrication across North American semiconductor fabs.
United States
FCC Part 15 rules governing unlicensed 60 GHz operation eliminate spectrum licensing costs and compress indoor wireless backhaul deployment timelines. Recent FCC rulemakings expanded 64-71 GHz access, pressuring manufacturers toward extended band compliance. Northern Virginia hyperscale data center clusters are locking in multi-year chipset allocation agreements for server rack backhaul applications.
Canada
ISED RSS-210 equipment certification harmonizes with FCC test reports, reducing barrier-to-entry for US suppliers expanding north. Toronto metro corridor data center builds are absorbing early WiGig volume as beamforming architectures displace legacy millimeter-wave solutions. Canadian policy lags US certification cycles by approximately one cycle, concentrating retooling cost absorption in American facilities.
Mexico
Nearshoring trends in electronics manufacturing are drawing WiGig adapter assembly operations to border states as OEMs diversify production geography. Mexican telecommunications regulator IFT maintains equipment certification pathways aligned with FCC technical standards. Tijuana and Monterrey industrial corridors are emerging as assembly nodes for workstation docking peripherals bound for US enterprise channels.
North America Wigig Market Competitive Landscape
Global majors compete with regional champions across integrated modem-RF platform supply, with the vendor base consolidating around three to four dominant semiconductor suppliers. Market structure tilts toward captive sourcing strategies and backward integration into substrate supply. Two archetypes dominate: integrated platform vendors controlling full stack design and specialized RF component suppliers. Competitive moves center on multi-year supply agreement lock-ins and channel partnership consolidation with OEM workstation lines.
Among integrated platform specialists, Qualcomm Technologies Inc. and Broadcom Inc. occupy positions anchoring enterprise socket dominance through reference design consolidation. Intel Corporation sits within the adapter-tier vector, exemplifying channel partnership strategies across Dell and HP workstation lines. These three entities represent the concentration point where procurement teams are consolidating vendor relationships away from discrete component sourcing.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| Intel Corporation |
| Broadcom Inc. |
| Cisco Systems Inc. |
| Peraso Technologies Inc. |
| MediaTek Inc. |
| Texas Instruments Incorporated |
| Marvell Technology Group |
| Lattice Semiconductor Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up semiconductor specialists have consolidated gallium arsenide substrate sourcing across North American fabs, tightening pricing discipline through captive supply agreements with enterprise buyers in Northern Virginia and Toronto data center corridors. This ownership pattern ties component pricing directly to multi-year allocation locks, compressing spot-market flexibility for adapter-tier purchasers.
Pricing Analysis
Warranty and multi-year service bundling separate enterprise procurement contracts from spot-market adapter sales, with FCC Part 15 certification tiering creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on beamforming sophistication and ISED RSS-210 dual-certification status, with cost compression in economy adapters intensifying because of Thunderbolt displacement pressure. Hyperscale data center operators show least price sensitivity, while SOHO router channels face acute margin squeeze.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese gallium arsenide wafer foundries feeding Broadcom and Qualcomm captive substrate operations. Supply draws from Taiwan, South Korea, and United States for front-end module fabrication, with raw material dependencies spanning high-purity gallium, germanium substrates, and advanced packaging ceramics. Tariff exposure on cross-border component flows compounds risk, while distribution runs through direct semiconductor-OEM channel partnerships displacing traditional adapter distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward integration into gallium arsenide sourcing anchors margin defense, while forward control over Dell and HP workstation socket allocation determines volume priority.
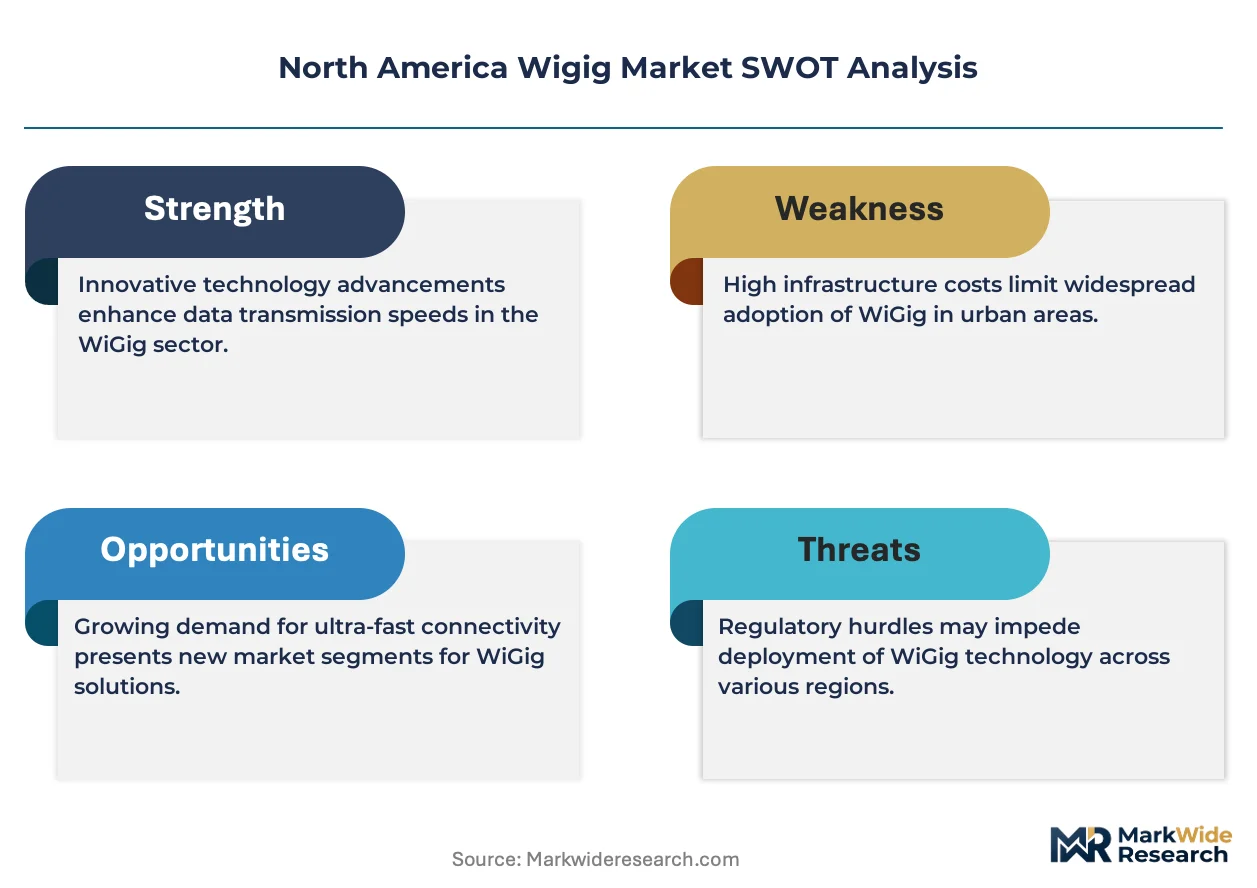
For Market Incumbents: Hedge against MIMO carrier trial commercialization by locking multi-year supply agreements with Toronto and Northern Virginia hyperscale operators before 802.11ay standard convergence collapses chipset tiering. Defend beamforming socket dominance through captive substrate sourcing expansion, as Intel's adapter-tier channel partnerships threaten discrete component supplier relevance. For New Entrants and Emerging Players: Launch via AR/VR tethering white-space targeting enterprise training verticals in Dallas-Fort Worth corridor, where wireless docking penetration remains below data center interconnect saturation. Target healthcare electromagnetic compatibility certification as a premium entry wedge, exploiting stringent FDA and Health Canada device clearance requirements that incumbent platform vendors underweight. For Investors and Strategic Acquirers: ISED timeline harmonization announcements are the leading indicator that Canadian certification lag compression will unlock US supplier margin expansion north of the border. Long-term viability centers on integrated modem-RF platform consolidation, with acquisition focus on phased-array antenna design boutiques holding millimeter-wave RF engineering talent pools. Watch FCC 64-71 GHz extended band retooling cost disclosures as the signal for supply chain restructuring intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Sourcing | Broadcom's gallium arsenide captive supply locks 60 GHz power amplifier allocation priority against Qualcomm. |
| Channel Partnership Consolidation | Intel's Dell and HP workstation embedding displaces traditional adapter distribution in Dallas-Fort Worth corridor. |
| Dual-Certification Investment | FCC Part 15 and ISED RSS-210 parallel compliance opens cross-border product line expansion for US suppliers. |
| Beamforming Architecture Standardization | Phased-array antenna control logic unification collapses historical enterprise-consumer chipset segmentation. |
| AR/VR Tethering Application Development | Enterprise training wireless docking builds volume foundation before consumer VR headset commercial scale. |
Research Methodology
Document review covered FCC Part 15 rulemakings, ISED RSS-210 certification databases, and hyperscaler capex disclosures, complemented by interviews with semiconductor procurement directors, RF engineering leads at data center operators, and OEM workstation product managers. Secondary sources included SEC 10-K filings, Dell and HP supply chain disclosures, and Canadian mineral processing trade data. Bottom-up chipset shipment triangulation against top-down enterprise networking spend validated market sizing.
Installed base projections and revenue forecasts emerged from segment-level modeling across product type, technology architecture, application vertical, and end-user procurement sophistication. CAGRs were derived from elasticity-adjusted adoption curves tied to beamforming deployment velocity and MIMO carrier trial progression. Key inputs spanned gallium arsenide substrate allocation constraints, FCC 64-71 GHz retooling cost absorption, and ISED harmonization timeline assumptions.
Regulatory rulemaking acceleration, carrier trial commercialization delays, and gallium arsenide supply disruption are the dominant revision risks that could compress or extend the forecast trajectory. Forecasts reflect documented assumptions about standard convergence timing and certification cost pass-through rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Flexible PV Cell Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market