
 Septic Tanks Market | 2026-2036
Septic Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Septic Tanks Market Outlook
Project finance for municipal decentralized wastewater programs is tilting competitive dynamics toward vendors with balance-sheet capacity for long-term service contracts. Infiltrator Water Technologies leverages its thermoformed plastic manufacturing scale to dominate the residential replacement channel. Kingspan Group anchors its position through backward integration into raw resin supply and captive distribution networks across North America and Europe. Orenco Systems, Inc. differentiates via advanced treatment system bundling that extends its value proposition beyond passive tank sales.
Septic tanks are watertight underground vessels, typically constructed from concrete, plastic, fiberglass, or steel, designed to receive and partially treat domestic wastewater through sedimentation and anaerobic digestion before effluent disperses to drain fields. Concrete products retain the largest installed base due to decades of building code grandfathering and contractor familiarity, though plastic segments gain ground from lighter transport logistics and corrosion immunity in acidic soil conditions. Below-ground installation types generate the majority of revenue, while precast concrete configurations command premium positioning in commercial and government specifications where structural load ratings and traffic-bearing requirements apply.
EPA oversight through the Clean Water Act and state environmental agencies shape product standards, installation certification, and effluent monitoring protocols that dictate market access. The International Association of Plumbing and Mechanical Officials publishes tank structural and performance benchmarks adopted by multiple U.S. jurisdictions. NSF International certification requirements for specific treatment levels filter competitor participation in premium specification tiers. Stakeholders must monitor evolving nutrient-reduction mandates in Chesapeake Bay and Great Lakes watersheds, as these geographies signal regulatory templates likely to propagate to other sensitive drainage basins.
Market Dynamics
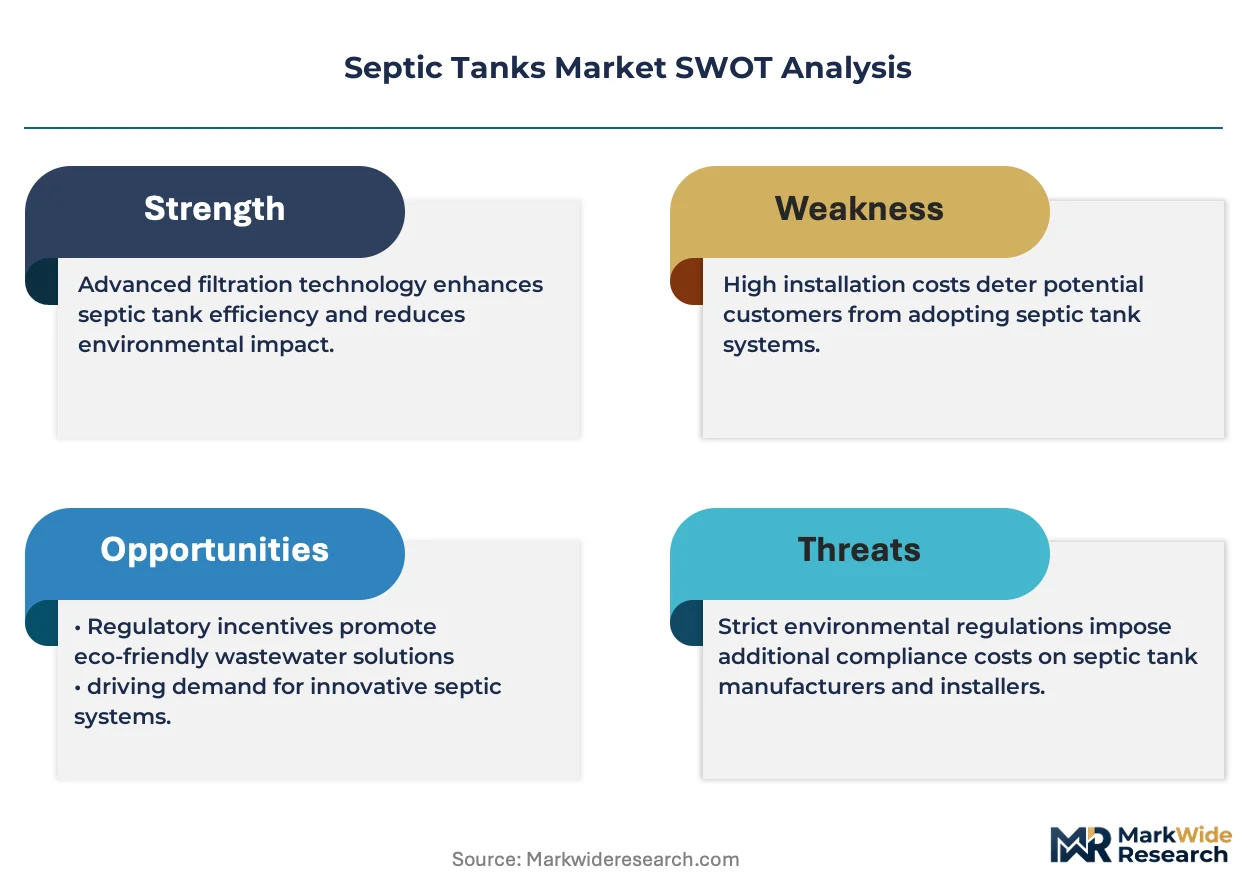
Decentralized wastewater infrastructure in rural America faces intensifying EPA nutrient-reduction mandates that force passive tank replacement with advanced treatment systems, compressing replacement cycles and elevating specification complexity for contractors and municipalities.
Growth Catalysts
- EPA Clean Water Act enforcement:State environmental agencies in Chesapeake Bay watersheds now mandate nitrogen and phosphorus effluent limits that obsolete conventional single-chamber tanks.
- Clay-heavy soil geographies:Southeastern United States counties with impermeable subsoil conditions default to mound systems and aerobic treatment units that expand addressable equipment spend per installation.
- Homebuilder code adoption:International Association of Plumbing and Mechanical Officials standards for traffic-bearing precast concrete tanks penetrate commercial and light-industrial specifications previously served by plastic alternatives.
Market Restraints
- Petrochemical resin volatility:Thermoformed polyethylene tank manufacturers face margin compression when propylene feedstock prices spike, disadvantaging plastic segments versus concrete in bid situations.
- Licensed installer scarcity:State-level certification requirements for advanced treatment system commissioning create bottleneck capacity in rural counties where trained technicians concentrate around metropolitan peripheries.
- Gravity-fed sewer competition:USDA Rural Development grant programs for centralized collection infrastructure in communities above 2,500 population permanently remove addressable septic demand in qualifying geographies.
Strategic Opportunities
- Internet-of-Things telemetry integration:Remote effluent monitoring sensors bundled with aerobic treatment units capture recurring revenue streams from property managers and municipal compliance officers.
- Great Lakes nutrient mandates:Wisconsin and Michigan regulatory templates for phosphorus reduction in sensitive watersheds signal adoption patterns likely to propagate to Minnesota and Ohio markets.
- Direct-to-contractor e-commerce:Bypassing traditional two-step distribution through specialized building material platforms reduces working capital requirements and accelerates specification capture.
Industry Challenges
- NSF International certification timelines:Advanced treatment system validation protocols require 18-24 month field-testing cycles that delay product launch windows and freeze R&D amortization.
- Legacy drain field remediation:Failed absorption bed replacement projects demand soil science expertise that general excavation contractors lack, fragmenting project execution and extending completion schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Septic Tanks Market |
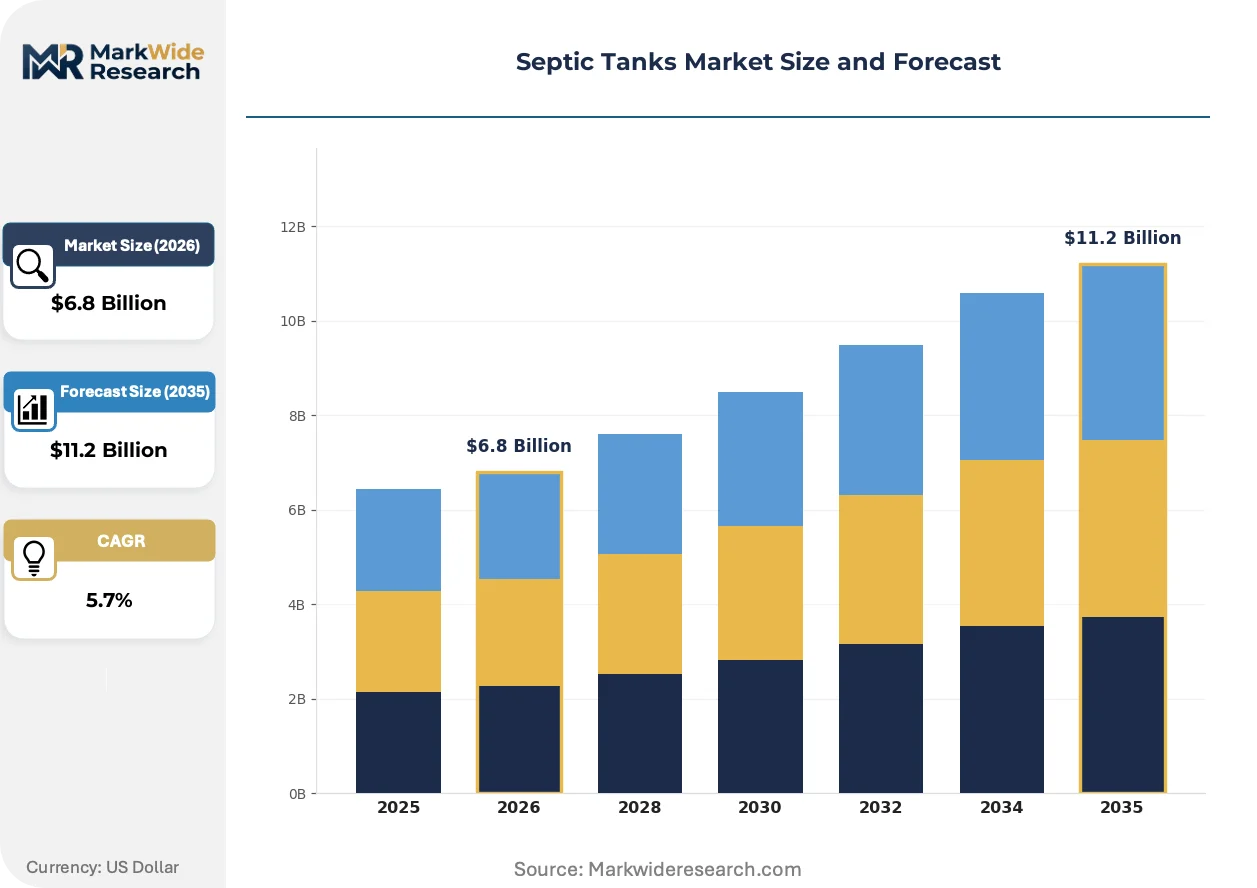
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete, Plastic, Fiberglass, Steel End User: Residential, Commercial, Industrial, Government Installation Type: Above Ground, Below Ground, Partial Installation, Precast Maintenance Type: Pumping, Inspection, Repair, Replacement |
| Companies Covered | Orenco Systems, Inc., Norwesko, LLC, Advanced Drainage Systems, Cultec, Inc., Oldcastle Infrastructure Inc., Kingspan Group, Infiltrator Water Technologies, LLC, Otto Graf GmbH Kunststofferzeugnisse, Snyder Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Septic Tanks Market Strategic Shifts
Sensor-enabled treatment systems and modular precast configurations are compressing installation timelines while elevating compliance transparency for regulators and property owners.
Continuous effluent quality monitoring via cloud-connected dissolved oxygen and turbidity sensors is digitizing how municipalities enforce permit compliance, shifting enforcement from scheduled inspections to real-time violation alerts. Rural water districts in Vermont and Maryland pilot these networks to reduce field-staff deployment costs. The data architecture compresses liability exposure for system owners while creating subscription revenue attachments for equipment vendors.
REACH chemical restrictions in European Union member states now limit certain concrete admixtures used in sulfate-resistant tank formulations, forcing precast manufacturers to reformulate with alternative corrosion inhibitors. German and French environmental agencies coordinate enforcement timelines that synchronize product recertification across contiguous markets. Tank exporters serving multiple EU jurisdictions consolidate SKUs to reduce compliance fragmentation costs.
Property developers in exurban Atlanta and Phoenix now specify packaged treatment plants with 20-year service contracts rather than conventional passive tanks, transferring operational risk to equipment vendors. This performance-guarantee model displaces lump-sum capital expenditure with annualized payments that improve project financing metrics. Municipalities in fast-growing Sun Belt counties favor these arrangements to defer public infrastructure bond issuance.
Septic Tanks Market Segmentation
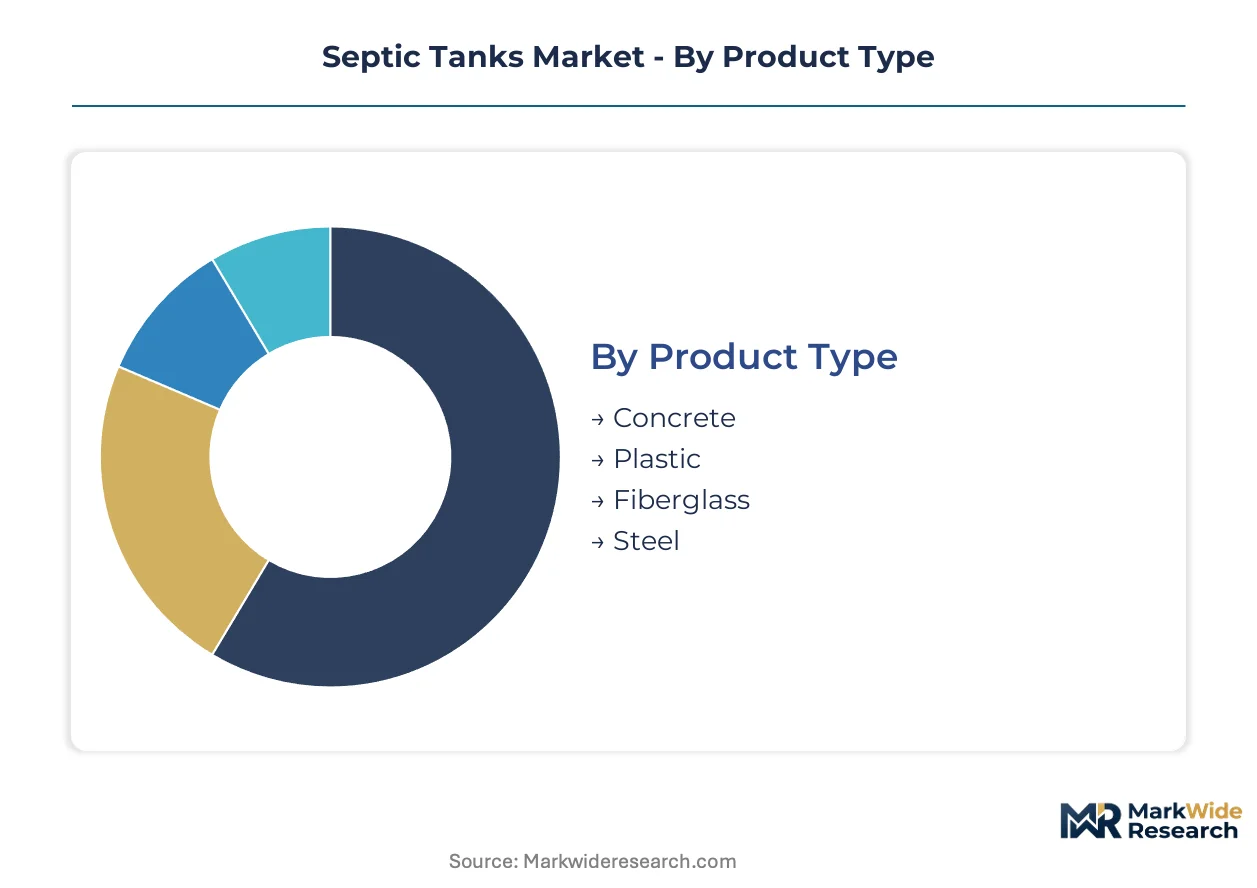
Septic tank segmentation reveals divergent replacement cycles and margin profiles across material, installation, and service dimensions. Contractors and municipalities prioritize segments based on soil corrosivity, load-bearing requirements, and regulatory compliance horizons rather than upfront capital cost alone.
Product Type:
Concrete tanks turn over slowest with 40-60 year lifespans in neutral pH soils, while plastic and fiberglass segments accelerate replacement frequency in acidic geographies and coastal zones.
- Concrete:Precast reinforced concrete dominates commercial and government specifications due to structural load ratings and traffic-bearing capacity. Demand concentrates in the American Southeast where clay-heavy soils and grandfathered building codes preserve contractor familiarity with poured and precast configurations.
- Plastic:Thermoformed polyethylene and polypropylene tanks displace concrete in residential replacement channels where transport logistics and corrosion immunity in acidic soil conditions outweigh premium pricing. Rural counties in Florida and coastal Georgia show fastest adoption as saltwater intrusion accelerates concrete degradation.
- Fiberglass:Composite resin construction offers intermediate durability with lighter handling than concrete and superior chemical resistance versus thermoplastics.
- Steel:Galvanized and coated metal configurations retain niche positioning in temporary construction site applications and industrial holding tank scenarios where mobility overrides longevity concerns.
Concrete anchors the volume base while plastic gains share at the steepest rate.
End User:
Residential installations generate the highest absolute unit volumes, though commercial and government segments concentrate margin through specification complexity and bonded performance guarantees.
- Residential:Single-family and small multi-family dwellings drive replacement cycles tied to home resale inspections and failed drain field remediation. Exurban Atlanta and Phoenix property developers increasingly specify packaged treatment plants with long-term service contracts rather than conventional passive tanks.
- Commercial:Restaurants, retail strips, and office complexes require traffic-rated precast concrete and advanced aerobic treatment units to meet municipal pretreatment ordinances. Wisconsin and Michigan regulatory templates for phosphorus reduction in sensitive watersheds elevate specification complexity for commercial applicants.
- Industrial:Food processing and light manufacturing facilities deploy holding tanks and sequencing batch reactors for high-strength wastewater streams.
- Government:Municipal decentralized wastewater programs and federal rural development projects favor vendors with balance-sheet capacity for long-term service contracts and EPA compliance documentation.
Residential commands absolute unit volume while commercial delivers the highest average project value per installation.
Installation Type:
Below-ground configurations dominate revenue as gravity-fed drainage and aesthetic concealment requirements eliminate above-ground alternatives for permanent structures.
- Below Ground:Buried concrete and plastic tanks constitute the default configuration for residential and commercial permanent structures, with depth determined by frost line and groundwater table. Vermont and Maryland rural water districts pilot sensor-enabled networks to reduce field-staff deployment costs for below-ground system monitoring.
- Precast:Factory-cured concrete segments with standardized lifting hardware compress on-site construction timelines and enable traffic-bearing specifications for parking lot and roadway applications.
- Above Ground:Elevated holding tanks serve temporary construction camps, recreational vehicle parks, and emergency response scenarios where excavation is impractical.
- Partial Installation:Hybrid configurations with above-ground pump chambers and below-ground treatment zones accommodate high water table conditions in coastal plains.
Below-ground installation anchors the revenue base while precast configurations climb the fastest in commercial and municipal specifications.
Maintenance Type:
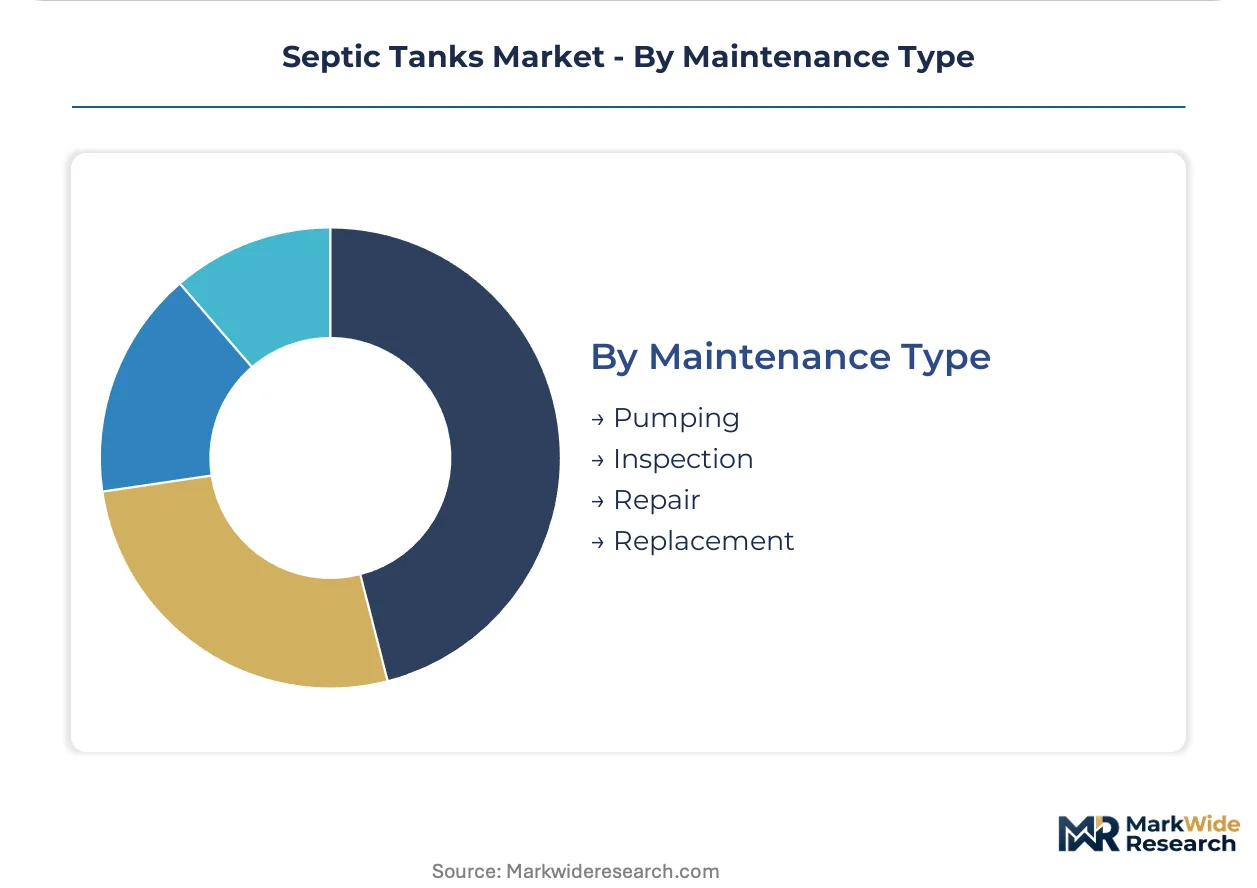
Pumping intervals drive recurring revenue predictability, while inspection mandates create compliance-driven entry points for full replacement and upgrade sales.
- Pumping:Scheduled sludge and scum removal every 3-5 years constitutes the baseline service attachment for tank owners, with frequency determined by household size and tank capacity. EPA and state environmental agencies mandate regular inspection intervals that compel tank upgrades and replacement cycles.
- Inspection:Visual and camera-assisted assessments trigger replacement decisions when structural integrity, baffle condition, or effluent quality fail regulatory thresholds. Internet-of-Things telemetry integration captures recurring revenue streams from property managers and municipal compliance officers.
- Repair:Baffle replacement, riser installation, and inlet/outlet rehabilitation extend functional lifespans without full system replacement.
- Replacement:Failed tank removal and new system installation represent the highest-margin service category, particularly where advanced treatment unit mandates obsolete conventional single-chamber designs.
Pumping delivers the most predictable recurring revenue while replacement generates the steepest expansion trajectory from regulatory-driven upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of thermoformed polyethylene tanks from European fabricators balance against concrete precast exports from the American Southeast, creating a bilateral trade pattern shaped by soil chemistry and regulatory divergence rather than labor cost differentials.
United States
Rural counties across Florida and Georgia deploy mound systems and aerobic treatment units where clay-heavy subsoils block conventional drain fields. EPA Clean Water Act enforcement through state environmental agencies now mandates nitrogen and phosphorus effluent limits in Chesapeake Bay watersheds. Exurban Atlanta property developers increasingly specify packaged treatment plants with long-term service contracts, transferring operational risk from homeowners to equipment vendors.
Canada
Provincial building codes in Ontario and Quebec grandfather concrete installations while accelerating plastic adoption in coastal Atlantic provinces where saltwater intrusion degrades traditional materials. Health Canada coordinates with provincial environment ministries on effluent monitoring protocols for decentralized wastewater systems. Rural water districts in Vermont and Maryland pilot sensor-enabled telemetry networks to reduce field-staff deployment costs for below-ground system monitoring.
Germany
REACH chemical restrictions now limit certain concrete admixtures used in sulfate-resistant tank formulations, forcing precast manufacturers to reformulate with alternative corrosion inhibitors. ECHA enforcement timelines synchronize product recertification across contiguous EU markets. German fabricators consolidate SKUs to reduce compliance fragmentation costs when serving multiple European jurisdictions with divergent environmental standards.
France
ANSM and CNIL coordinate data governance for IoT-enabled effluent monitoring systems that digitize compliance enforcement. French environmental agencies align with German counterparts on REACH implementation schedules for tank construction materials. Manufacturers in the Rhine-Ruhr industrial cluster adapt formulations to meet corrosion-resistance specifications without prohibited chemical additives.
Australia
State-level plumbing codes in New South Wales and Victoria prioritize fiberglass and plastic configurations in acidic soil geologies where concrete degradation accelerates. The country's national environmental regulator mandates inspection intervals that compress replacement cycles for aging installations. Perth metropolitan expansion into sandy coastal plains drives demand for advanced treatment units that exceed passive tank performance standards.
Septic Tanks Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying raw resin, precast forms, and telemetry hardware. The vendor base spans multinational building-material conglomerates with captive distribution networks alongside regional precast fabricators serving single-state contractor relationships. Two strategic archetypes dominate: vertically integrated resin-to-tank manufacturers exploiting feedstock cost advantages, and advanced treatment system bundlers capturing recurring service revenue. Competitive moves concentrate on backward integration into raw material supply and strategic partnerships for IoT sensor deployment.
Within the platform-integrator tier, Kingspan Group and Infiltrator Water Technologies occupy positions defined by manufacturing scale and channel control. Orenco Systems, Inc. exemplifies the advanced-treatment archetype through system bundling that extends value propositions beyond passive tank sales. Among European specialists, Otto Graf GmbH represents the regional fabrication model anchored in German-speaking markets with localized regulatory expertise.
| Leading Market Players |
|---|
| Orenco Systems, Inc. |
| Norwesko, LLC |
| Advanced Drainage Systems |
| Cultec, Inc. |
| Oldcastle Infrastructure Inc. |
| Kingspan Group |
| Infiltrator Water Technologies, LLC |
| Otto Graf GmbH Kunststofferzeugnisse |
| Snyder Industries |
| Others |
Value Chain & Pricing Dynamics
The American Southeast's precast concrete fabrication cluster around Atlanta and Birmingham shapes downstream pricing power through captive resin supply and traffic-rated specification dominance. Kingspan Group's backward integration into raw polyethylene feedstock compresses plastic tank margins when propylene volatility spikes, forcing competitors to absorb cost pass-through or surrender bid share to concrete alternatives.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across municipal decentralized wastewater programs, with three-tier pricing stratification separating NSF-certified advanced treatment units from standard passive tanks and economy-grade polyethylene configurations. Price differentiation hinges on certification grade and geographic delivery cost, with Chesapeake Bay watershed nitrogen mandates compressing margins on conventional single-chamber designs. Pricing pressure stems from petrochemical resin volatility disadvantaging plastic segments versus concrete in competitive bid situations. Residential replacement channels exhibit highest price sensitivity, while government specifications prioritize bonded performance guarantees over upfront capital cost.
Supply Chain Analysis
Thermoformed tank contract manufacturers concentrate capacity in Ohio, Indiana, and Ontario, with German fabricators Otto Graf GmbH anchoring European sulfate-resistant formulation expertise. Raw material dependencies center on polypropylene resin, precast concrete admixtures, and corrosion inhibitor chemicals. Supply chain risk rests on REACH chemical restrictions forcing reformulation cycles across EU export markets. Distribution runs through specialized building material platforms and two-step distribution networks serving licensed installer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gravity-fed sewer infrastructure subsidized by USDA Rural Development grants poses a permanent substitution threat that incumbents must navigate through service-contract differentiation and regulatory compliance bundling.
For Market Incumbents: Harden specification capture through IoT telemetry integration that creates recurring revenue attachments and raises switching costs for municipal compliance officers. Deepen upstream control over raw resin supply to insulate margin compression from propylene feedstock volatility. Anchor position in Chesapeake Bay and Great Lakes watersheds where nutrient-reduction mandates obsolete conventional tank designs and compress replacement cycles.
For New Entrants and Emerging Players: Pursue direct-to-contractor e-commerce channels in rural Southeastern counties where licensed installer scarcity creates specification bottlenecks. Target Florida and coastal Georgia residential replacement segments where saltwater intrusion accelerates concrete degradation and plastic adoption climbs fastest. Enter through advanced treatment system bundling that transfers operational risk to equipment vendors via long-term service contracts.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EPA Clean Water Act enforcement and state-level nutrient mandates create irreversible upgrade cycles across aging installed bases. Acquisition targets should concentrate on vendors with captive distribution networks and balance-sheet capacity for municipal performance guarantees. Monitor Wisconsin and Michigan regulatory templates for phosphorus reduction as signals of geographic propagation patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Kingspan Group's captive polyethylene production insulates margin compression from propylene feedstock volatility. |
| IoT Sensor Platform Partnership | Orenco Systems captures recurring telemetry revenue from Vermont and Maryland rural water district pilots. |
| NSF Certification Investment | Advanced treatment system validation filters competitor participation in premium specification tiers. |
| Direct-to-Contractor E-Commerce | Infiltrator Water Technologies reduces working capital requirements through specialized building material platforms. |
| Long-Term Service Contract Bundling | Exurban Atlanta developers transfer operational risk to vendors via 20-year performance guarantees. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through primary interviews with municipal wastewater directors, licensed septic installers, precast concrete plant managers, and thermoformed tank procurement leads at national distributors. Secondary validation drew from EPA enforcement records, state environmental agency permit databases, International Association of Plumbing and Mechanical Officials code adoption tracking, and NSF International certification registries. Bottom-up unit economics triangulated against top-down infrastructure spend projections across rural county building permit data.
Calibration anchored volume and value outputs to observed replacement cycles, regulatory compliance horizons, and material substitution elasticities across the projection horizon. Segmentation dimensions spanned material type, installation configuration, end-user category, and maintenance service attachment. CAGRs were derived from fitted growth curves applied to county-level housing stock demographics and watershed-specific nutrient mandate implementation timelines. Forecast inputs incorporated petrochemical resin price volatility indices and USDA Rural Development grant allocation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated resin-to-tank manufacturers or municipal performance-guarantee specialists would shift outcomes beyond modeled ranges. Quarterly review of state-level nutrient mandate adoption, propylene feedstock price movements, and licensed installer certification expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
Silt Curtain Market