
 Singapore Data Center Construction Market | 2026-2036
Singapore Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Data Center Construction Market Insights
Market Context
IMDA's revised data center energy efficiency framework is rebalancing the cost-of-entry calculus for new facility approvals in Singapore. Digital Realty leverages its established land positions and power allocations to sustain development momentum under tighter regulatory thresholds. NTT Ltd. anchors its regional hub strategy with specialized liquid-cooled designs that navigate the stricter power usage effectiveness requirements. ST Telemedia Global Data Centres competes through integrated utility partnerships that secure priority grid access for expansion phases.
Technical Definition and Segment Structure
Singapore data center construction encompasses the engineering, procurement, and construction of mission-critical facilities housing servers, storage systems, and network equipment, typically requiring power densities exceeding 15 kilowatts per rack and tier III or tier IV redundancy certifications for uninterrupted operations. The construction type dimension splits sharply between new build projects capturing premium valuations and retrofit assignments where legacy facilities upgrade cooling and power infrastructure to remain competitive. End user segmentation shows hyperscalers driving the largest capacity commitments, while colocation providers occupy the margin-intensive middle tier serving enterprises unable to justify captive facility investments.
Regulatory Frame and Outlook
IMDA's sustainability standards, BCA Green Mark certification requirements, and PUB water efficiency mandates collectively shape facility design specifications and operational compliance obligations for all market participants. The Energy Market Authority coordinates grid interconnection protocols that determine project viability timelines and capital deployment sequencing. Stakeholders must monitor land release schedules from JTC Corporation and power allocation announcements to align construction pipelines with infrastructure availability windows.
Market Dynamics
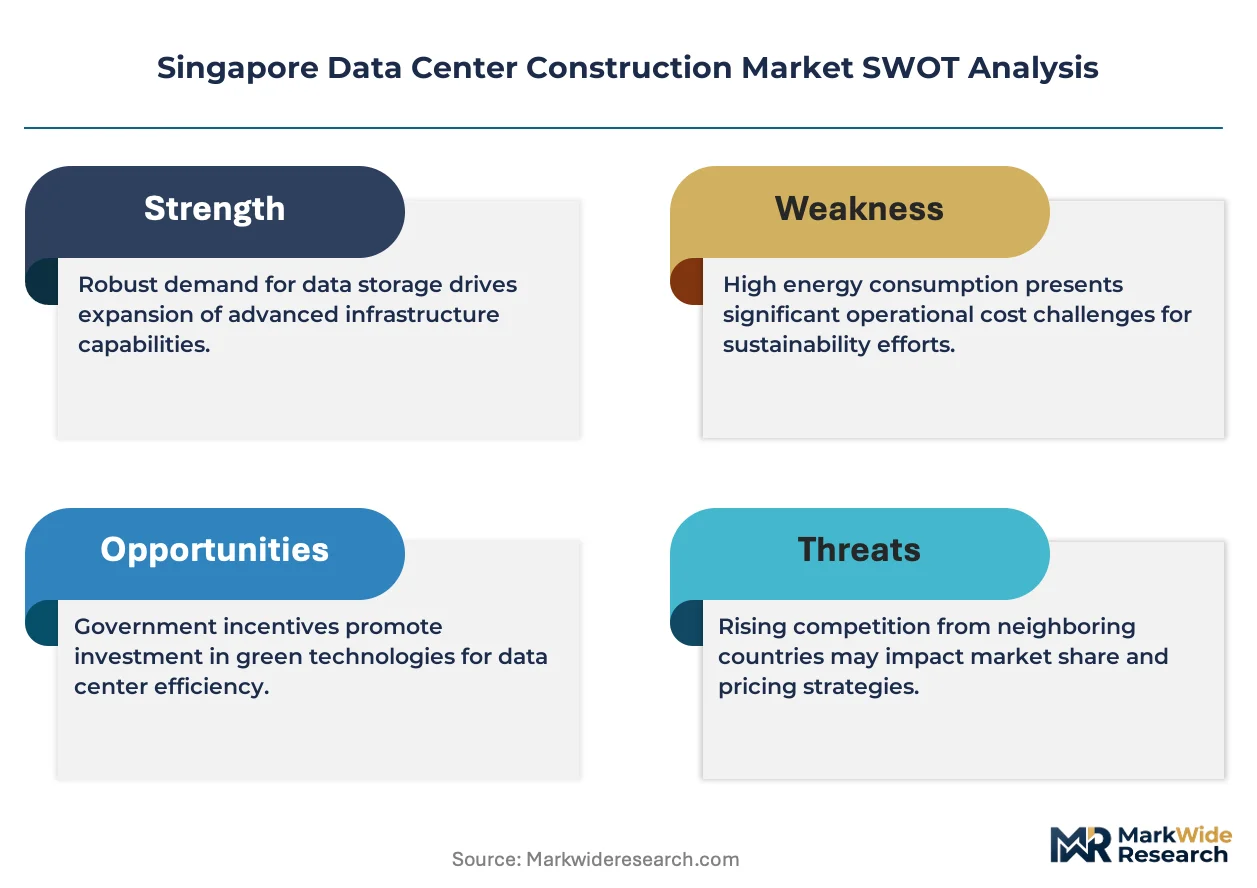
IMDA's tightened power usage effectiveness thresholds are compressing development timelines and forcing design recalculations for every new facility proposal in Singapore. Developers must secure power allocations before finalizing engineering specifications, reversing traditional construction sequencing.
Growth Catalysts
- Hyperscaler Expansion:Cloud computing and artificial intelligence operators are accelerating commissioning schedules to capture limited land and substation capacity in the Jurong Lake District and Changi North corridor.
- Liquid Cooling Adoption:Specialized immersion and direct-to-chip cooling systems are enabling higher rack densities while maintaining compliance with stricter thermal efficiency mandates under the revised framework.
- Grid Modernization:Energy Market Authority coordination of interconnection protocols is streamlining priority access for digital infrastructure projects with integrated utility partnerships.
Market Restraints
- Land Scarcity:JTC Corporation controlled releases in designated zones create allocation bottlenecks that extend pre-construction phases by multiple quarters.
- Power Density Ceilings:Substation capacity reservations in existing corridors limit total megawatt deployment regardless of developer capital availability.
- Water Efficiency Mandates:PUB requirements for cooling system performance add engineering complexity and capital cost layers to facility designs.
Strategic Opportunities
- Tier IV Certification Gap:Premium redundancy specifications remain undersupplied relative to financial services and healthcare tenant requirements.
- Retrofit Modernization:Legacy facilities in older industrial zones present conversion potential for upgraded cooling and power infrastructure.
- Integrated Energy Systems:On-site solar generation paired with battery storage aligns with BCA Green Mark certification pathways and reduces grid dependency.
Industry Challenges
- Specialized Engineering Talent:Mission-critical facility design expertise for high-density liquid-cooled environments commands premium compensation and extended recruitment cycles.
- Certification Timeline Compression:Simultaneous IMDA, BCA, and PUB approval processes require parallel documentation streams that strain project management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Data Center Construction Market |
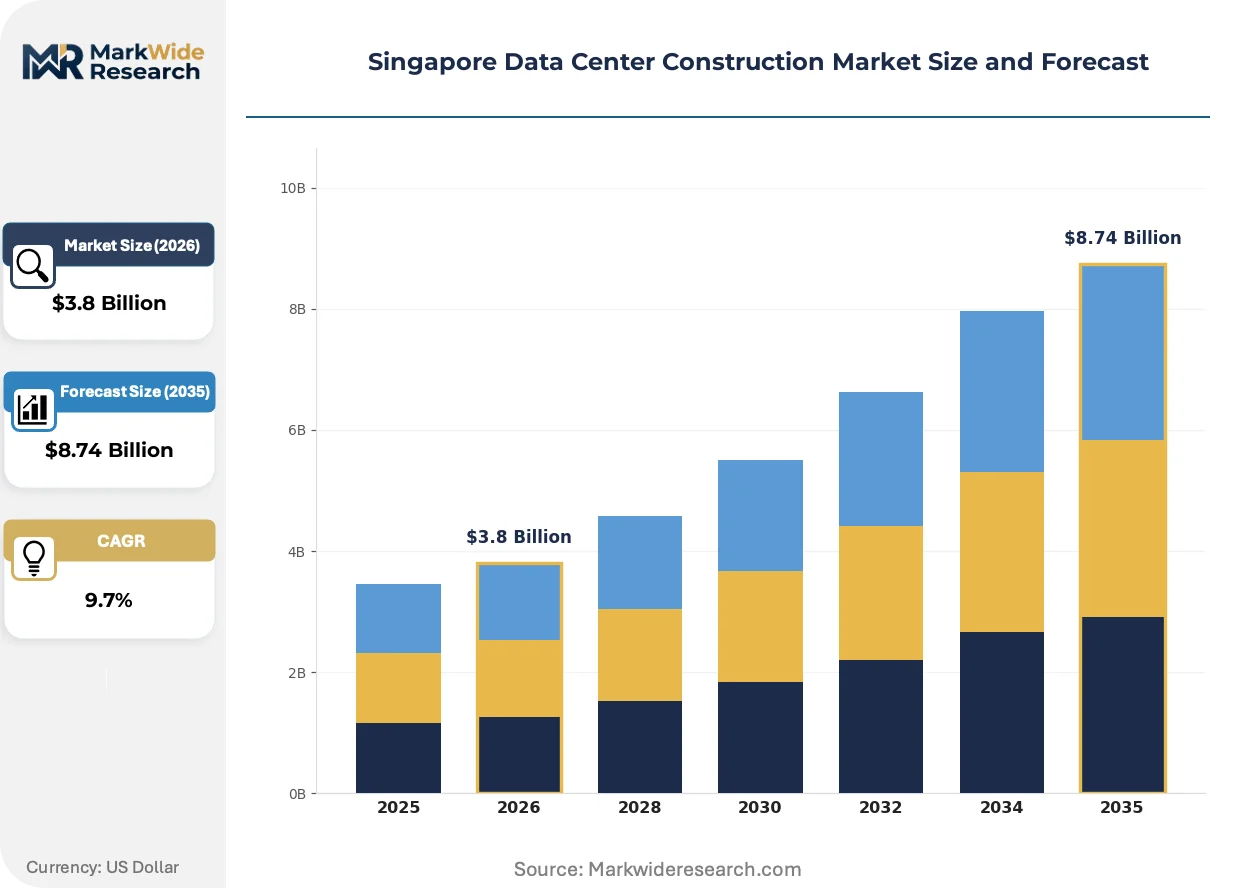
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: New Build, Expansion, Renovation, Retrofit End User: Hyperscalers, Enterprises, Colocation Providers, Government Power Source: Renewable Energy, Conventional Power, Backup Generators, Hybrid Systems Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Free Cooling |
| Companies Covered | Digital Realty, NTT Ltd., AECOM, Schneider Electric SE, DayOne, ST Telemedia Global Data Centres, Fortis Construction, Turner Construction Co., Equinix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Data Center Construction Market Trends and Innovations
Facility engineering is pivoting from air-cooled conventions to thermal architectures that sustain artificial intelligence training workloads. Design specifications now prioritize heat rejection capacity over traditional redundancy hierarchies.
Immersion cooling is overtaking raised-floor air distribution as the default specification for racks exceeding 30 kilowatts. Hyperscalers deploying graphics processing unit clusters are mandating dielectric fluid systems in new build tenders. This transition is compressing mechanical infrastructure footprints by forty percent while redirecting capital toward specialized containment and fluid management systems.
IMDA's sustainability standards now require operational power usage effectiveness reporting with third-party verification. Facility operators must submit annual efficiency metrics to maintain operating licenses. Colocation providers serving enterprise tenants are absorbing compliance costs into base pricing structures to preserve margin.
Enterprise procurement teams are consolidating vendor relationships around operators with pre-certified green building credentials. Single-source agreements are replacing multi-provider strategies to simplify sustainability auditing and reduce contractual overhead. Financial services tenants in the central business district are driving this concentration most aggressively.
Singapore Data Center Construction Market Segmentation
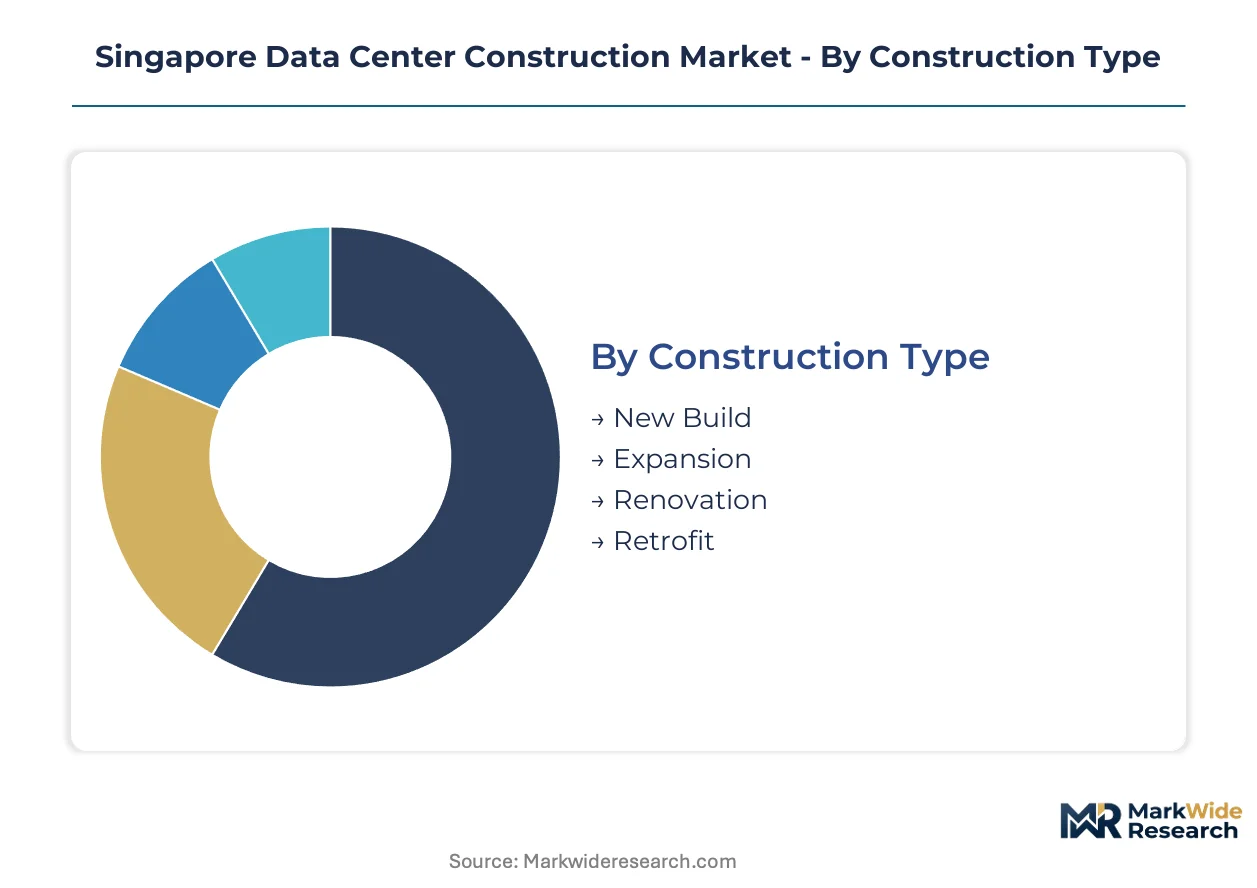
Segmentation in Singapore's data center construction market reveals how regulatory pressure and tenant specifications reshape capital allocation across project types and technical systems. Construction type and cooling technology decisions now precede land acquisition in development sequencing.
Construction Type:
New build deployments command premium valuations and extended approval timelines, while retrofit assignments occupy the volume-intensive base serving legacy facility upgrades.
- New Build:Ground-up facilities on JTC Corporation land parcels in Jurong Lake District and Changi North corridor target tier III or tier IV certifications with power densities exceeding 15 kilowatts per rack. Hyperscalers from cloud computing and artificial intelligence sectors are compressing commissioning schedules to secure limited substation capacity allocations.
- Expansion:Adjacent facility additions leverage existing power infrastructure and grid interconnection protocols coordinated by the Energy Market Authority. Colocation providers pursue phased construction to match tenant commitment timelines against IMDA's tightened power usage effectiveness thresholds.
- Renovation:Structural upgrades to operational facilities address BCA Green Mark certification requirements without full reconstruction.
- Retrofit:Legacy cooling and power infrastructure replacements in older industrial zones enable competitive positioning under stricter thermal efficiency mandates.
Mature deployment sits with retrofit assignments preserving operational continuity. Newer deployment is concentrated in new build projects capturing premium tenant commitments.
End User:
Hyperscaler capital commitments drive capacity absorption, while enterprise and government segments shape specification diversity across redundancy tiers.
- Hyperscalers:Cloud computing and artificial intelligence operators mandate specialized liquid-cooled designs sustaining graphics processing unit cluster densities. Facility tenders from this segment specify dielectric fluid systems and third-party verified power usage effectiveness reporting.
- Enterprises:Financial services and healthcare tenants in the central business district prioritize tier IV redundancy certifications and pre-certified green building credentials for simplified sustainability auditing.
- Colocation Providers:Margin-intensive operators serving enterprises absorb IMDA compliance costs into base pricing structures.
- Government:Public sector procurement emphasizes integrated utility partnerships and priority grid access secured through Energy Market Authority coordination.
Volume concentration aligns with hyperscaler procurement. Premium specification diversity clusters with enterprise tenants in regulated sectors.
Power Source:
Renewable integration attracts BCA Green Mark certification pathways, while hybrid architectures address grid dependency constraints in capacity-constrained corridors.
- Renewable Energy:On-site solar generation paired with battery storage reduces grid dependency and aligns with PUB water efficiency mandates through reduced thermal load.
- Conventional Power:Grid-sourced electricity from Energy Market Authority coordinated interconnection protocols remains the baseline for substation-reserved capacity in designated zones.
- Backup Generators:Diesel and natural gas systems provide tier III and tier IV uninterrupted operations certification compliance.
- Hybrid Systems:Combined renewable, conventional, and storage configurations optimize capital deployment against IMDA sustainability standards and operational license requirements.
Established deployment relies on conventional power with backup redundancy. Expanding deployment is concentrating in hybrid systems with renewable integration.
Cooling Technology:
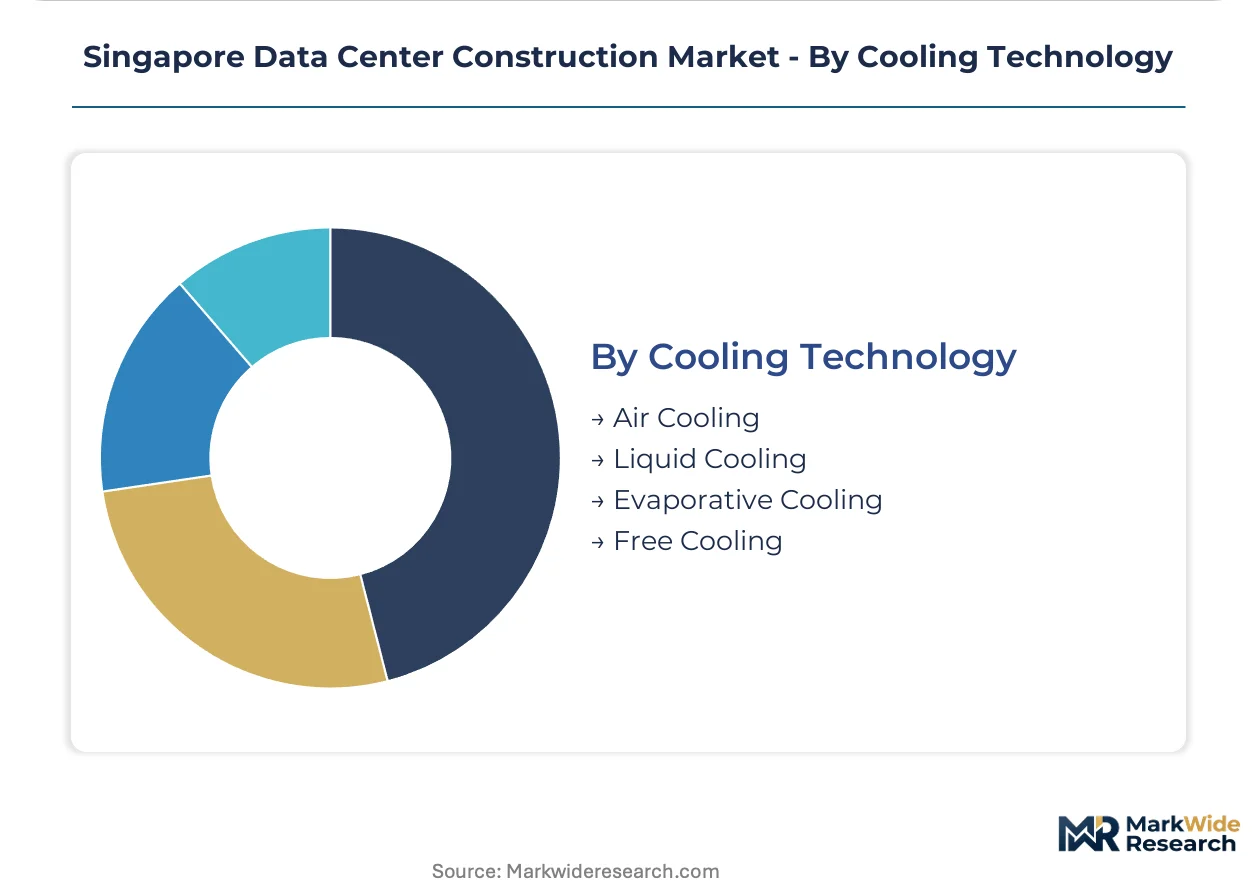
Liquid architectures displace air-cooled conventions for high-density workloads, while free cooling and evaporative systems address water efficiency mandates.
- Liquid Cooling:Immersion and direct-to-chip systems sustain rack densities exceeding 30 kilowatts while compressing mechanical infrastructure footprints. Hyperscalers deploying artificial intelligence training workloads mandate dielectric fluid specifications in new build tenders.
- Air Cooling:Raised-floor distribution persists in legacy facilities and lower-density enterprise deployments where retrofit capital is constrained.
- Evaporative Cooling:Water-based heat rejection adds engineering complexity under PUB water efficiency mandates but enables operational power usage effectiveness compliance.
- Free Cooling:Ambient air utilization reduces energy consumption for compatible workload profiles and thermal envelopes.
Legacy deployment remains with air cooling systems. Steepest expansion trajectory is occurring in liquid cooling as default specification for artificial intelligence infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler demand concentrates in Singapore's Jurong Lake District and Changi North corridor, where JTC Corporation has reserved land and substation capacity for digital infrastructure deployment. The Energy Market Authority coordinates grid interconnection protocols that determine project viability timelines across these zones.
Jurong Lake District
Cloud computing operators drive capacity absorption in this western corridor, commissioning specialized liquid-cooled facilities for artificial intelligence training workloads. IMDA's revised power usage effectiveness thresholds govern all new build approvals in this zone. Digital Realty and NTT Ltd. anchor development activity where substation reservations enable phased megawatt deployment.
Changi North Corridor
Colocation providers pursue expansion assignments adjacent to existing facilities to leverage established power infrastructure. BCA Green Mark certification requirements shape renovation specifications for legacy buildings in this eastern cluster. ST Telemedia Global Data Centres competes through integrated utility partnerships securing priority grid access for facility additions.
Tuas Industrial Zone
Retrofit modernization opportunities attract capital to older industrial buildings requiring cooling and power infrastructure upgrades. PUB water efficiency mandates add engineering complexity to facility designs in this southwestern area. Specialized contractors target conversion projects that enable competitive positioning under stricter thermal efficiency standards.
One-North and Buona Vista
Research and technology tenants generate enterprise demand for tier IV redundancy certifications in this central innovation district. Government procurement emphasizes integrated utility partnerships through Energy Market Authority coordination. DayOne and Equinix occupy positions serving financial services and healthcare tenants requiring pre-certified green building credentials.
Singapore Data Center Construction Market Competitive Landscape
Singapore-based developers anchor the premium tier; international engineering specialists hold design and equipment supply positions. The market structure concentrates around established landholders with secured power allocations and specialized contractors with mission-critical facility expertise. Three archetypes dominate: integrated real estate operators with JTC land positions, engineering-procurement-construction firms with liquid cooling credentials, and technology providers with thermal management systems. Competitive moves center on securing priority grid access through utility partnerships and compressing certification timelines through parallel regulatory submissions.
Within the integrated operator tier, Digital Realty, NTT Ltd., and ST Telemedia Global Data Centres exemplify archetypes that leverage established infrastructure positions. Digital Realty represents the land-anchored real estate model with secured JTC parcels. NTT Ltd. occupies a position emphasizing specialized thermal designs for high-density workloads. ST Telemedia Global Data Centres exemplifies the utility-integrated expansion strategy. Among engineering and construction specialists, AECOM, Turner Construction Co., and Fortis Construction sit within the mission-critical facility build segment. Equipment and technology providers include Schneider Electric SE with power and cooling systems. DayOne and Equinix represent colocation operators serving enterprise tenants with compliance-heavy procurement requirements.
| Leading Market Players |
|---|
| Digital Realty |
| NTT Ltd. |
| AECOM |
| Schneider Electric SE |
| DayOne |
| ST Telemedia Global Data Centres |
| Fortis Construction |
| Turner Construction Co. |
| Equinix |
| Others |
Pricing and Supply Chain Analysis
Tier IV certification premiums against standard tier III deployments create a bifurcated pricing architecture that simultaneously concentrates supply chain sourcing around mission-critical engineering specialists and fragments procurement across liquid cooling component vendors. IMDA's power usage effectiveness thresholds compress margins on commodity builds while amplifying pricing power for facilities meeting stricter thermal efficiency mandates.
Pricing Analysis
Volume concentration in hyperscaler tenders compresses per-megawatt construction margins, while tier IV redundancy premiums for financial services tenants sustain pricing power at the certification apex. Three-tier pricing structure across premium certification, standard colocation, and retrofit modernization levels differentiates by IMDA compliance grade and thermal performance guarantees. Cost compression in air-cooled legacy segments intensifies as liquid cooling becomes default for artificial intelligence workloads. Enterprise procurement teams show highest price sensitivity, absorbing compliance overhead into consolidated vendor relationships.
Supply Chain Analysis
Domestic-content mandates under BCA Green Mark certification reshape sourcing toward Singapore-based contractors with mission-critical facility expertise. Engineering and procurement draws from Japan, Germany, and the United States for precision cooling systems and uninterruptible power supply equipment. Specialized dielectric fluids, high-density rack infrastructure, and advanced switchgear constitute critical input dependencies. Single-source vulnerability concentrates in liquid cooling containment systems from limited qualified vendors. Distribution runs through integrated engineering-procurement-construction firms with established JTC Corporation land positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's data center construction sector occupies a technology-transition phase where liquid cooling architectures displace legacy air-cooled designs under IMDA's tightened efficiency framework. Stakeholders must calibrate capital deployment against substation capacity scarcity and specialized engineering talent bottlenecks.
For Market Incumbents: Deepen utility partnerships securing priority grid access through Energy Market Authority coordination to defend against emerging engineering-procurement-construction specialists without established power allocations. Expand backward integration into liquid cooling system design capabilities to capture margin migrating from mechanical contractors. Prioritize parallel certification submissions compressing IMDA, BCA, and PUB approval timelines.
For New Entrants and Emerging Players: Begin with retrofit modernization assignments in Tuas Industrial Zone legacy facilities where cooling infrastructure upgrades face less substation competition than greenfield corridors. Target tier IV certification gaps in One-North and Buona Vista serving financial services and healthcare tenants with premium redundancy requirements. Lead with specialized thermal engineering credentials distinguishing from commodity construction bids.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated operators possessing secured JTC land positions and established power allocations given hyperscaler demand compression against limited substation capacity. Long-term viability hinges on alignment with IMDA sustainability trajectories and artificial intelligence workload growth curves. Monitor JTC Corporation land release schedules and Energy Market Authority interconnection announcements as inflection indicators for construction pipeline viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling System Integration | Dielectric fluid architectures enable IMDA compliance for artificial intelligence rack densities exceeding 30 kilowatts. |
| Utility Partnership Expansion | Energy Market Authority coordination secures priority grid access in capacity-constrained Jurong and Changi corridors. |
| Tier IV Certification Investment | Redundancy premiums capture financial services and healthcare tenants in central business district proximity zones. |
| Retrofit Modernization Capability | Legacy facility upgrades in Tuas Industrial Zone address BCA Green Mark requirements without greenfield land competition. |
| Integrated Energy System Deployment | On-site solar generation with battery storage aligns BCA certification pathways with reduced grid dependency. |
Research Methodology
Independent corroboration across data center development executives, mission-critical facility engineering directors, and Energy Market Authority planning officers underwrites the qualitative findings. Primary interviews with JTC Corporation land allocation specialists, IMDA regulatory affairs leads, and hyperscaler infrastructure procurement teams combined with secondary validation from BCA certification databases, PUB water efficiency filings, and utility interconnection protocols. Bottom-up project pipeline assessment and top-down sector expenditure analysis triangulate market sizing.
Rate-of-change decomposition separates hyperscaler capacity commitments, enterprise colocation absorption, and retrofit modernization velocity across the projection horizon. Segmentation dimensions modeled include construction type, cooling technology architecture, end user procurement profile, and power source configuration. CAGRs derive from facility commissioning timelines against substation capacity release schedules and IMDA approval throughput. Forecast inputs incorporate hyperscaler capital expenditure disclosures and JTC land parcel allocation announcements.
Regulatory threshold revisions, substation capacity reservation delays, and specialized engineering talent availability constitute the dominant revision risks. Forecasts reflect documented assumptions regarding IMDA enforcement consistency and hyperscaler demand continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Prefabricated Construction Market
Building Construction
China Modular Construction Market
Building Construction
Vietnam Construction Market
Building Construction
India Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Africa Construction Market
Building Construction
China Prefabricated Buildings Market
Building Construction
Poland Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
North America Construction Market
Building Construction
GCC Construction Market
Building Construction
South Korea Data Center Construction Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
Indonesia Construction Market
Building Construction
France Prefab Wood Building Market