
 Europe Prefabricated Buildings Market | 2026-2036
Europe Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Prefabricated Buildings Market Foresight
Housing associations and municipal developers are unwinding the historical dominance of speculative private builders in European prefabricated procurement. Skanska AB leverages its integrated design-build platform to capture large-scale social infrastructure contracts across Nordic cities. Goldbeck GmbH anchors German industrial demand through standardized steel-frame halls engineered for rapid assembly. Huf Haus specializes in premium timber-glass modular homes that occupy the high-performance residential niche.
Prefabricated buildings are structures manufactured in factory conditions and transported to site for assembly, typically achieving dimensional tolerances of ±2 millimetres and incorporating insulation, electrics, and finishes before delivery. These systems reduce on-site construction duration by 30-50% compared with traditional methods while minimizing weather exposure and waste generation. Modular construction dominates European volume for multi-storey residential and healthcare projects where repetitive bay designs maximize factory throughput. Panelized systems lead in commercial and educational applications where façade customization and open-plan flexibility carry premium value. Steel and cross-laminated timber materials are capturing share from concrete as embodied-carbon accounting intensifies under EU taxonomy rules.
CE marking under the Construction Products Regulation governs structural safety and fire performance across EU member states, while national building codes in Germany and France impose additional energy efficiency thresholds that factory-controlled assembly satisfies more reliably than site-built equivalents. The EU Green Deal and national retrofit mandates are redirecting public procurement budgets toward low-carbon construction methods. Stakeholders must monitor how the EU AI Act and evolving digital building logbook requirements reshape quality assurance protocols and competitive positioning in factory-based fabrication.
Market Dynamics
The EU Green Deal's embodied-carbon limits are compressing procurement timelines and forcing developers toward factory-controlled fabrication methods that guarantee compliance documentation from point of manufacture.
Growth Catalysts
- EU Green Deal carbon thresholds:Tightening limits on construction material emissions are disqualifying traditional site-cast concrete in favor of precision-manufactured timber and steel systems that ship with verified environmental product declarations.
- Social housing procurement:Municipal tenders in France and the Netherlands now mandate off-site fabrication to minimize neighborhood disruption and accelerate delivery schedules for urgent housing stock.
- Cross-laminated timber maturation:Engineered wood products with fire-rated performance certifications are capturing multi-storey residential applications previously reserved for concrete and steel frames.
Market Restraints
- Specialized transport infrastructure:Oversized module dimensions require escorted convoys and route surveys that inflate logistics costs and restrict viable site radii from manufacturing plants.
- Skilled assembly labor scarcity:Crane operators and module-sealing technicians with factory-to-site coordination experience command wage premiums that erode labor savings from reduced on-site duration.
- CE marking complexity:National building code variations across EU member states force manufacturers to maintain multiple certification portfolios, increasing compliance overhead without harmonization prospects.
Strategic Opportunities
- Healthcare facility retrofit mandates:Hospital energy efficiency directives in Germany and Scandinavia are opening procurement channels for rapid-assembly modular wings that minimize operational disruption during expansion.
- Student accommodation volume contracts:University housing offices are consolidating vendor relationships around repeatable bay designs that factory production can deliver at compressed lead times.
- Digital building logbook integration:The EU AI Act's quality assurance requirements are creating first-mover advantages for fabricators with integrated sensor and documentation platforms embedded at manufacture.
Industry Challenges
- Design-to-factory workflow reconfiguration:Architects and engineers accustomed to site-adjustable construction must adopt rigid dimensional tolerances and early-stage design freeze protocols that conflict with traditional project phases.
- Module-to-legacy system integration:Utility connections between factory-built volumes and existing site infrastructure require specialized interface engineering that extends commissioning timelines and generates defect liability disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Prefabricated Buildings Market |
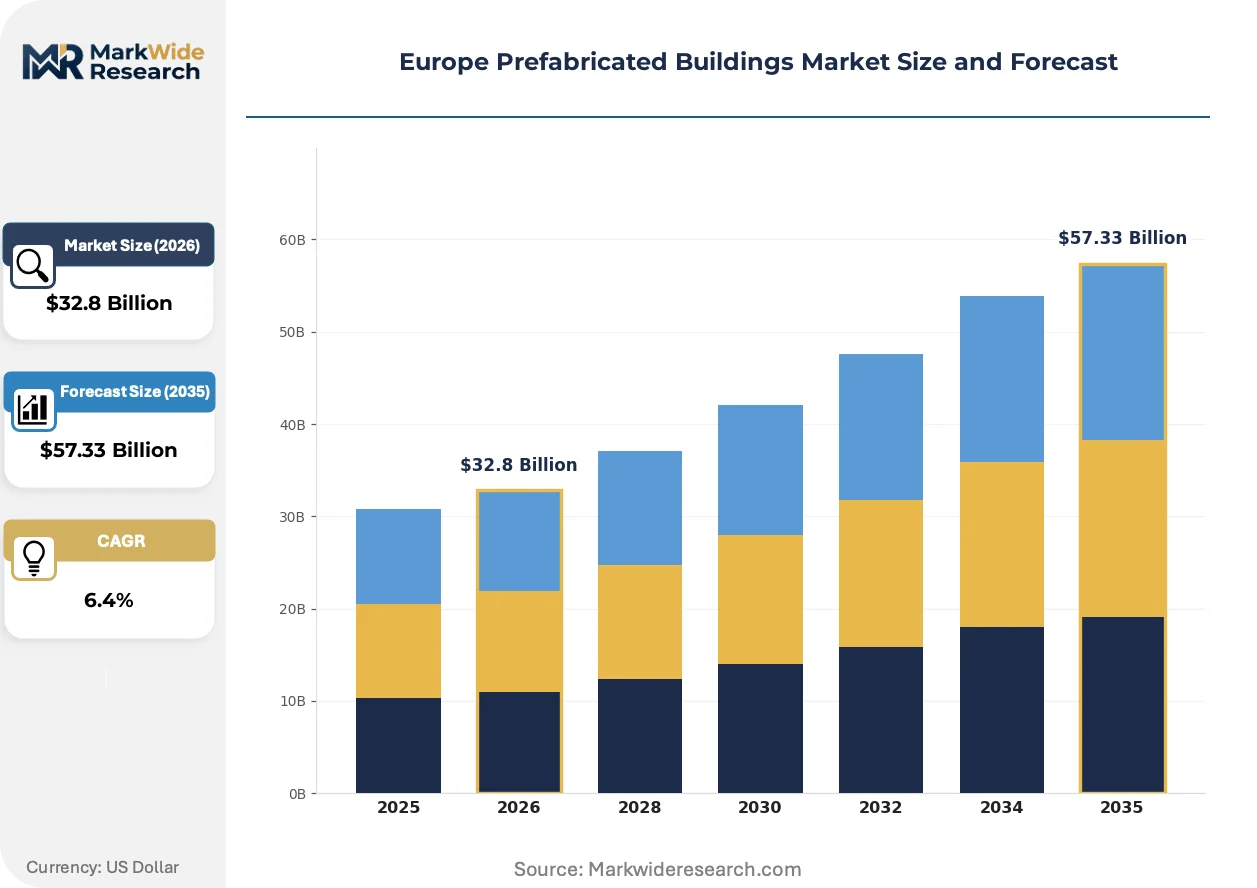
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Panelized, Hybrid, Pre-cut End User: Residential, Commercial, Educational, Industrial Construction Method: Off-site, On-site, Lean, Traditional Material: Wood, Steel, Concrete, Composite |
| Companies Covered | Portakabin Ltd, Bouygues Construction, Skanska AB, Danwood S.A., Laing O’Rourke, Modulaire Group, Huf Haus, Goldbeck GmbH, Lindbäcks Bygg, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Prefabricated Buildings Market Shifts & Advancements
Factory fabrication methods are splitting into divergent technical paths as carbon accounting precision and digital traceability requirements reshape competitive capabilities across the European construction sector.
Cross-laminated timber is bifurcating the structural materials market as German and Austrian manufacturers scale automated CNC cutting lines for complex geometries. Housing associations in Scandinavia specify timber systems for projects above four storeys, a height threshold concrete dominated until 2020. The technology is bifurcating project pipelines into carbon-accounted timber streams and legacy concrete streams with diverging margin profiles and certification requirements.
CE marking under the Construction Products Regulation now requires factory-audited quality management systems for structural safety declarations. German and French national codes impose additional energy performance thresholds that off-site assembly satisfies more reliably than site-built equivalents. Panelized system manufacturers serving educational and commercial clients are restructuring production lines to capture documentation advantages for public procurement scoring.
Public sector buyers are consolidating vendor panels around integrated design-build contracts that transfer liability for dimensional accuracy and weather-tightness to fabricators. Municipal housing authorities in the Netherlands now specify fixed-price, fixed-duration delivery models that penalize schedule overruns. This concentration is visible in social housing and student accommodation verticals where procurement offices have reduced approved supplier lists from dozens to single-digit rosters.
Europe Prefabricated Buildings Market Segmentation
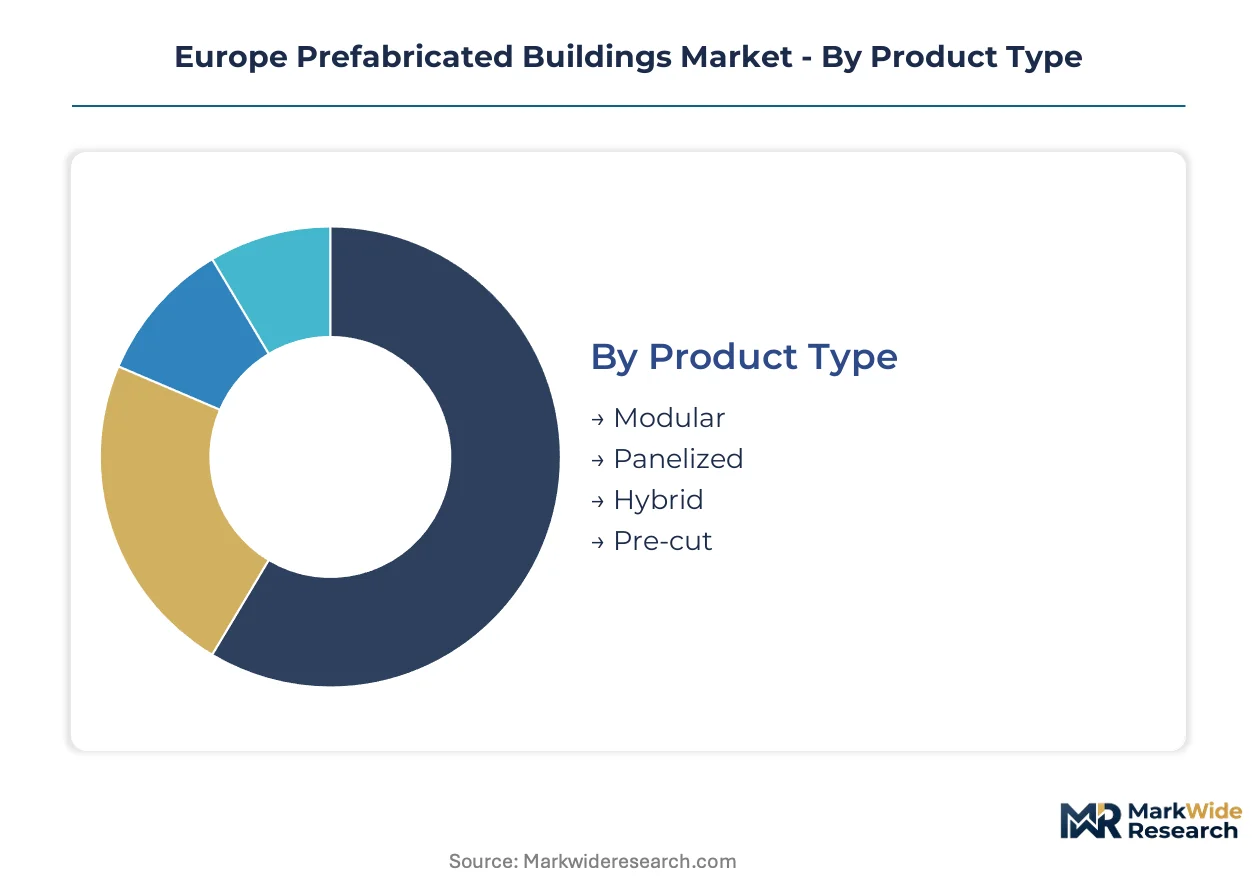
Segmentation in the Europe Prefabricated Buildings Market reveals how regulatory pressure and carbon accounting reshape procurement priorities across distinct technical categories. Factory-controlled fabrication methods carry divergent compliance burdens under EU Green Deal thresholds and national building codes.
Product Type:
CE marking requirements under the Construction Products Regulation create divergent certification pathways for each fabrication approach.
- Modular:Three-dimensional volumetric units manufactured complete with MEP systems and interior finishes achieve dimensional tolerances of ±2 millimetres. Demand concentrates in French and Dutch social housing tenders where municipal procurement mandates off-site fabrication to compress delivery schedules and minimize site disruption.
- Panelized:Two-dimensional wall, floor, and roof components shipped flat for on-site assembly permit façade customization and open-plan flexibility. German educational and commercial developers specify these systems where architectural variation carries premium value and factory throughput benefits from standardized panel dimensions.
- Hybrid:Combined volumetric and panelized approaches balance speed with design flexibility for complex multi-use projects.
- Pre-cut:Precision-cut timber or steel components requiring on-site assembly serve cost-sensitive residential applications.
Established volume favors modular systems for repetitive multi-storey residential; emerging adoption favors panelized approaches where customization commands pricing premiums.
End User:
Public procurement budgets redirect toward carbon-accounted construction methods across distinct vertical applications.
- Residential:Housing associations in Germany and Scandinavia scale procurement of timber-framed prefabricated units as EU Green Deal embodied-carbon limits disqualify traditional site-cast concrete. Municipal tenders in the Netherlands specify fixed-price, fixed-duration delivery models that penalize schedule overruns.
- Commercial:Office and retail developers prioritize speed-to-market in urban infill projects where site disruption restrictions limit conventional construction windows.
- Educational:School districts in France specify panelized systems for classroom expansion projects requiring rapid occupancy.
- Industrial:German manufacturing clients demand standardized steel-frame halls engineered for rapid assembly and future reconfiguration.
Residential commands the dominant revenue share; commercial applications are climbing the fastest as urban density intensifies site constraints.
Construction Method:
Labor scarcity and weather exposure drive differential adoption of factory-centric versus site-centric workflows.
- Off-site:Factory-controlled fabrication reduces on-site construction duration by 30-50% while eliminating weather-related delays and waste generation. Scandinavian hospital energy efficiency directives open procurement channels for rapid-assembly modular wings that minimize operational disruption during expansion.
- On-site:Traditional stick-built methods persist where transport infrastructure cannot accommodate oversized module dimensions or where local content requirements apply.
- Lean:Waste-minimization protocols borrowed from manufacturing integrate with prefabrication to reduce material loss below 5%.
- Traditional:Conventional construction retains share in heritage-sensitive districts where aesthetic continuity overrides speed considerations.
Off-site methods dominate new public procurement; lean construction principles are gaining share fastest among private developers seeking operational efficiency.
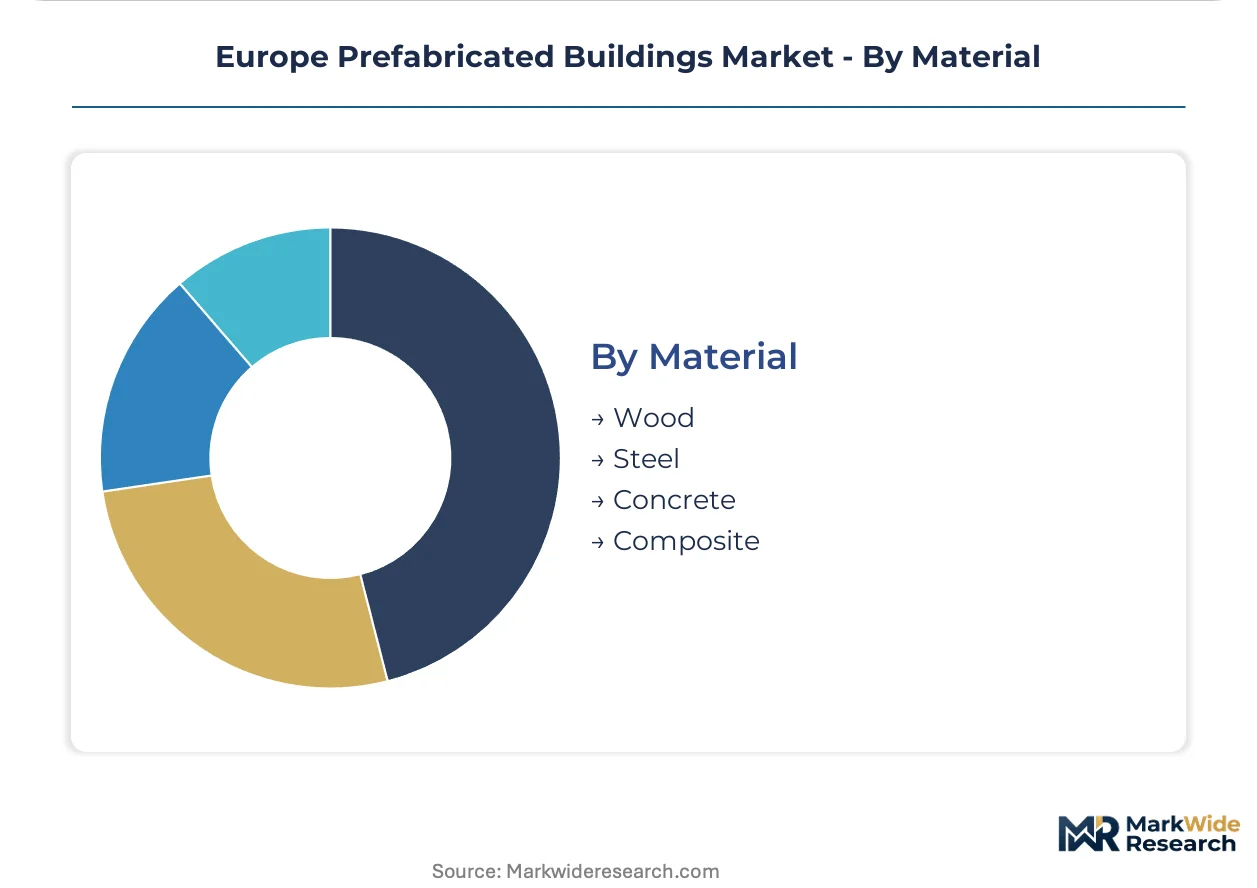
Material:
EU taxonomy rules on embodied-carbon accounting restructure competitive positioning across structural material categories.
- Wood:Cross-laminated timber with fire-rated performance certifications captures multi-storey residential applications previously reserved for concrete and steel frames. Austrian manufacturers scale automated CNC cutting lines for complex geometries as housing associations in Scandinavia specify timber systems above four storeys.
- Steel:Recycled-content steel framing dominates German industrial hall construction where rapid assembly and future reconfiguration carry operational value.
- Concrete:Site-cast concrete faces procurement exclusion under tightening carbon thresholds; precast concrete retains niche applications where thermal mass and acoustic isolation are prioritized.
- Composite:Hybrid material systems combining timber and steel optimize strength-to-weight ratios for transport-constrained projects.
Steel maintains established volume in industrial applications; engineered wood products are expanding most quickly as carbon-accounted procurement proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German prefabricated building exports flow primarily into Scandinavian and Benelux markets, where municipal procurement offices prioritize CE-marked timber systems for social housing density targets. This trade corridor reflects broader European supply patterns where factory-controlled fabrication concentrates in industrial clusters with established cross-laminated timber supply chains and escorted transport infrastructure for oversized modules.
Germany
Housing associations in North Rhine-Westphalia and Bavaria are scaling timber-framed procurement as the EU Green Deal tightens embodied-carbon limits on construction materials. The national building code imposes energy efficiency thresholds that factory-controlled assembly satisfies more reliably than site-built equivalents. Goldbeck GmbH anchors industrial demand from its Bielefeld base through standardized steel-frame halls engineered for rapid assembly.
France
Municipal tenders in Île-de-France and Auvergne-Rhône-Alpes now mandate off-site fabrication to minimize neighborhood disruption and accelerate delivery schedules for urgent social housing stock. The country's national building regulator enforces additional fire performance certifications that modular manufacturers serving public procurement must maintain. Bouygues Construction leverages its integrated design-build platform to capture large-scale infrastructure contracts across Parisian metropolitan expansion zones.
Netherlands
University housing offices in Randstad cities are consolidating vendor relationships around repeatable bay designs that factory production can deliver at compressed lead times. Municipal procurement scoring prioritizes documentation advantages from panelized system manufacturers with factory-audited quality management systems. Modulaire Group occupies a central position in student accommodation volume contracts through its standardized module configurations.
Sweden
Hospital energy efficiency directives in Stockholm and Gothenburg corridors open procurement channels for rapid-assembly modular wings that minimize operational disruption during expansion. Scandinavian housing associations specify timber systems for projects above four storeys, a height threshold concrete dominated until 2020. Skanska AB captures Nordic social infrastructure contracts through its integrated design-build platform serving municipal developers.
United Kingdom
Laing O'Rourke directs procurement toward off-site methods in Greater London and Midlands urban infill projects where site disruption restrictions limit conventional construction windows. The UK's national building regulations impose CE marking requirements under retained EU law that structural safety declarations must satisfy. Portakabin Ltd serves temporary and permanent modular demand from its York base through standardized volumetric units for education and healthcare applications.
Europe Prefabricated Buildings Market Competitive Landscape
Player mix skews toward integrated design-build specialists and regional timber-frame fabricators rather than pure-play module manufacturers. The vendor base separates into three functional tiers: multinational construction groups with factory assets, mid-cap specialists in engineered wood systems, and industrial hall fabricators serving manufacturing clients. Consolidation pressure operates through municipal procurement concentration that reduces approved supplier lists from dozens to single-digit rosters, while technology licensing agreements spread CNC cutting capabilities across Austrian and German timber clusters.
Among Nordic-based fabricators, Skanska AB and Lindbäcks Bygg exemplify the integrated design-build archetype that transfers liability for dimensional accuracy to factory-controlled operations. Huf Haus occupies a distinctive position in the premium residential tier through its timber-glass modular configurations. These named entities anchor industry-level patterns without constituting an exhaustive competitive map.
| Leading Market Players |
|---|
| Portakabin Ltd |
| Bouygues Construction |
| Skanska AB |
| Danwood S.A. |
| Laing O'Rourke |
| Modulaire Group |
| Huf Haus |
| Goldbeck GmbH |
| Lindbäcks Bygg |
| Others |
Supply & Pricing Matrix
Cross-laminated timber displacing concrete as the dominant structural material redistributes manufacturing capacity toward Austrian and German forest belt clusters while compressing margin structures for legacy precast concrete producers unable to certify embodied-carbon compliance.
Pricing Analysis
Technology-generation pricing gaps separate CNC-milled timber systems commanding premium certification value from standardized panelized steel-frame halls and legacy concrete modules facing procurement exclusion. Three-tier pricing structure across premium timber-glass configurations, mid-market steel-frame systems, and economy pre-cut timber kits reflects CE marking tier and factory-audited quality management investment. Pricing pressure stems from municipal fixed-price contracting in Dutch and French social housing tenders that transfers schedule risk to fabricators. Housing associations exhibit highest price sensitivity; premium residential buyers absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Escorted convoy requirements for oversized volumetric modules inflate inbound logistics costs along Rhine corridor routes and restrict viable site radii from manufacturing plants to roughly 300 kilometers. Factory-controlled fabrication draws from German steel rolling capacity, Austrian laminated timber feedstock, and Scandinavian engineered wood adhesive chemistry. Single-source vulnerability concentrates in specialized crane operators and module-sealing technicians with factory-to-site coordination experience. Distribution runs through municipal procurement panels that have consolidated approved supplier lists from dozens to single-digit rosters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-to-site coordination expertise represents the critical scarcity that separates viable scale operators from stranded capacity, as EU Green Deal documentation requirements and CE marking complexity filter out underinvested competitors.
For Market Incumbents: Secure captive supply of cross-laminated timber feedstock through backward integration into Austrian and German forest belt milling capacity. Defend municipal panel positions by embedding sensor platforms that satisfy EU AI Act digital building logbook requirements before tender scoring updates.
For New Entrants and Emerging Players: Anchor in Scandinavian hospital energy efficiency retrofit mandates where rapid-assembly modular wing demand outpaces established vendor capacity. Student accommodation volume contracts in Randstad cities offer the most penetrable entry channel through repeatable bay design specialization.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated design-build specialists with factory assets and certified timber supply chains. Long-term viability hinges on carbon-accounted procurement permanence under EU taxonomy rules. Watch for CE marking harmonization proposals as the inflection signal that would recalibrate compliance overhead economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Feedstock | Austrian CNC milling capacity secures carbon-certified supply chains for German housing association tenders. |
| Digital Building Logbook Platform Deployment | Integrated sensor documentation captures EU AI Act first-mover advantages in municipal procurement scoring. |
| Healthcare Facility Retrofit Specialization | Modular wing expertise addresses Scandinavian hospital energy directives with minimal operational disruption. |
| Student Accommodation Volume Contracting | Repeatable bay designs compress lead times for Dutch university housing consolidation strategies. |
| CE Marking Portfolio Harmonization | Multi-national certification streamlining reduces compliance overhead across German and French building codes. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with prefabricated building procurement officers at housing associations, municipal tender managers, factory operations directors, and crane logistics coordinators; and secondary validation through EU Construction Products Regulation filings, national building code amendments, municipal tender databases, and timber industry trade statistics. Bottom-up volume estimates triangulated against top-down construction spend allocations across residential, commercial, and infrastructure verticals.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end-user vertical, construction method, and structural material category. CAGRs derived from fitted growth curves incorporating EU Green Deal implementation pace, cross-laminated timber fire-rating certification expansion, and municipal procurement panel consolidation rates. Industry-specific inputs included embodied-carbon accounting threshold trajectories and escorted transport infrastructure capacity constraints.
Material uncertainties — regulatory harmonization delays, skilled assembly labor availability shocks, and laminated timber adhesive supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about CE marking continuity and municipal procurement preference stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
France Prefab Homes Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
El Salvador Construction Market
Building Construction
Tanzania Construction Market
Building Construction
Scandinavia Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
GCC Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
Africa Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Mezzanine Floor Market
Building Construction
Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
India Construction Market
Building Construction
Ireland Data Center Construction Market