
 Indonesia Infrastructure Market | 2026-2036
Indonesia Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Infrastructure Market Insights
The capital-intensity divergence between state-owned giants and mid-tier contractors is unwinding competitive dynamics across Indonesian infrastructure. PT Hutama Karya (Persero) leverages its government-backed balance sheet to dominate toll road construction in Sumatra. PT Waskita Karya (Persero) Tbk anchors its position through integrated engineering capabilities spanning design-build contracts. PT Jasa Marga (Persero) Tbk controls operational concessions on Java's busiest arterial highways.
Indonesia infrastructure encompasses civil engineering assets including roads, bridges, ports, water treatment facilities, and power transmission systems built to withstand seismic loads exceeding 0.3g peak ground acceleration. These assets enable domestic logistics, urban water security, and grid connectivity across an archipelago of 17,000 islands. Transportation projects draw the largest funding pools, while renewable energy installations represent the fastest-expanding construction phase as geothermal and solar capacity targets escalate. Public-private partnership structures concentrate margin pools in long-term concession arrangements, whereas government-funded maintenance contracts offer stable but thinner returns.
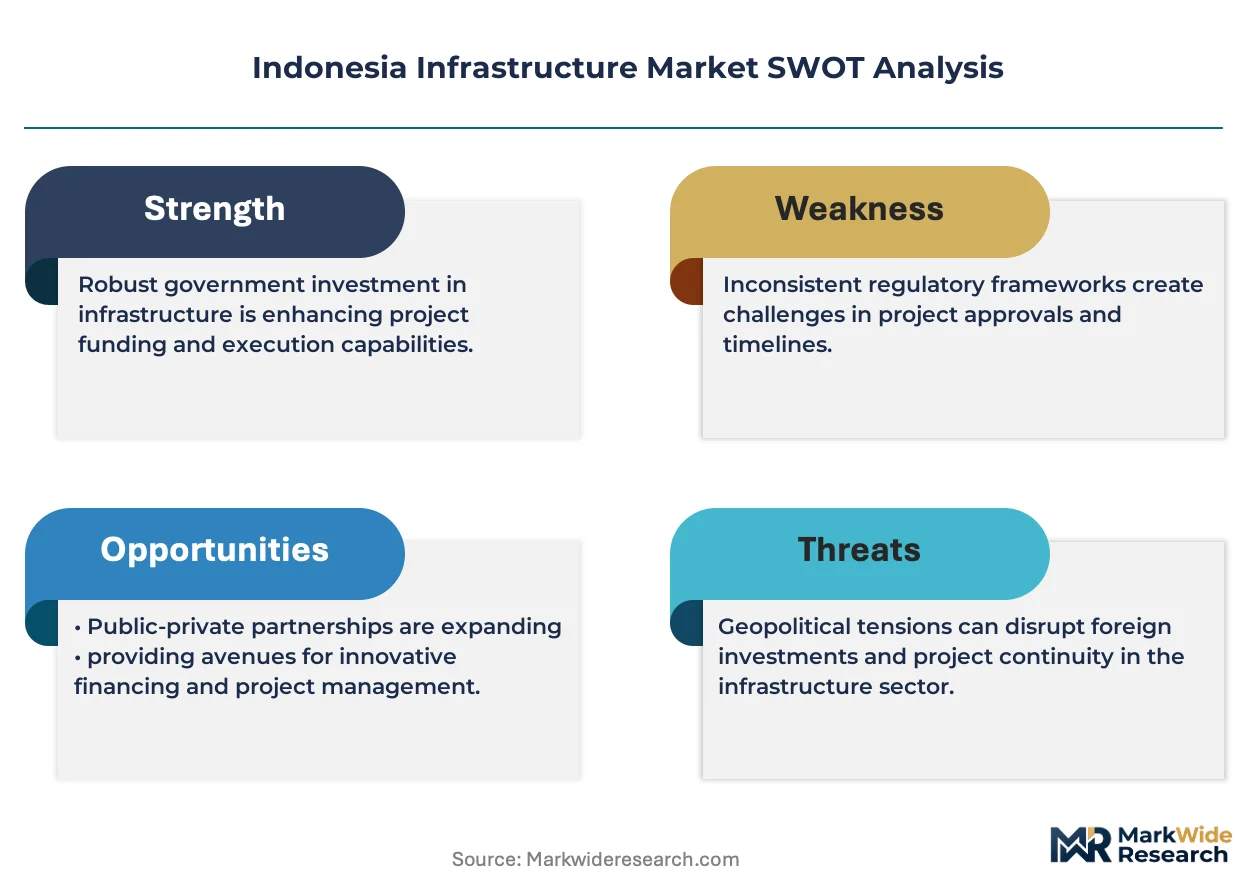
Bappenas, the Ministry of Public Works and Housing, and PT Sarana Multi Infrastruktur collectively shape project pipelines through masterplan allocation, SNI technical standards, and blended finance structuring. The national infrastructure acceleration program prioritizes earthquake resilience and climate adaptation in procurement criteria. Stakeholders must monitor regulatory shifts around land acquisition reform and local content requirements that determine contractor eligibility and project economics.
Market Dynamics
The convergence of seismic resilience mandates with archipelagic logistics demands is restructuring Indonesia infrastructure procurement. Bappenas allocation criteria now weight earthquake-resistant design above cost minimization, redirecting contractor capability investments toward advanced geotechnical engineering.
Growth Catalysts
- Geothermal expansion targets:The national energy transition roadmap mandates substantial renewable capacity additions. Utility-scale geothermal drilling contracts are accelerating civil works demand across the volcanic corridor from Sumatra to Sulawesi.
- SNI seismic codes:Mandatory peak ground acceleration standards of 0.3g for public structures are expanding retrofit markets. Building owners in Jakarta and Surabaya face compliance deadlines that compress project timelines.
- Trans-Java toll integration:The arterial highway network linking industrial zones is consolidating freight efficiency. Logistics operators are relocating distribution centers to corridor nodes, amplifying last-mile infrastructure requirements.
Market Restraints
- Steel rebar cost volatility:Domestic billet supply fluctuations expose contractors to margin compression. State-owned smelters control over sixty percent of feedstock, limiting price negotiation leverage for mid-tier builders.
- Land acquisition friction:The 2012 Land Acquisition Law implementation gaps stall right-of-way clearances. Toll road projects in Central Java average eighteen-month delays between environmental permits and groundbreaking.
- Imported heavy equipment dependency:Excavators and pile drivers sourced from Japanese and Korean manufacturers face currency-driven cost escalation. Rupiah depreciation against the yen compresses equipment procurement budgets.
Strategic Opportunities
- Eastern Indonesia connectivity:The maritime highway program targets port modernization across Maluku and Papua. Underdeveloped inter-island shipping infrastructure offers first-mover concession opportunities.
- Blended finance structures:PT Sarana Multi Infrastruktur risk-sharing mechanisms reduce sovereign exposure. Pension fund co-investment vehicles are unlocking institutional capital for water treatment assets.
- Smart tolling convergence:Integration of RFID gantries with dynamic pricing algorithms is enabling revenue optimization. PT Jasa Marga operational data feeds are attracting fintech partnerships for traffic-flow monetization.
Industry Challenges
- Geotechnical engineering talent scarcity:Universities produce insufficient seismic design specialists. Contractors compete for limited professionals certified in soil-structure interaction modeling.
- Legacy asset integration complexity:Pre-2010 structures lack digital as-built documentation. Retrofit projects require costly subsurface investigation before SNI compliance upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Infrastructure Market |
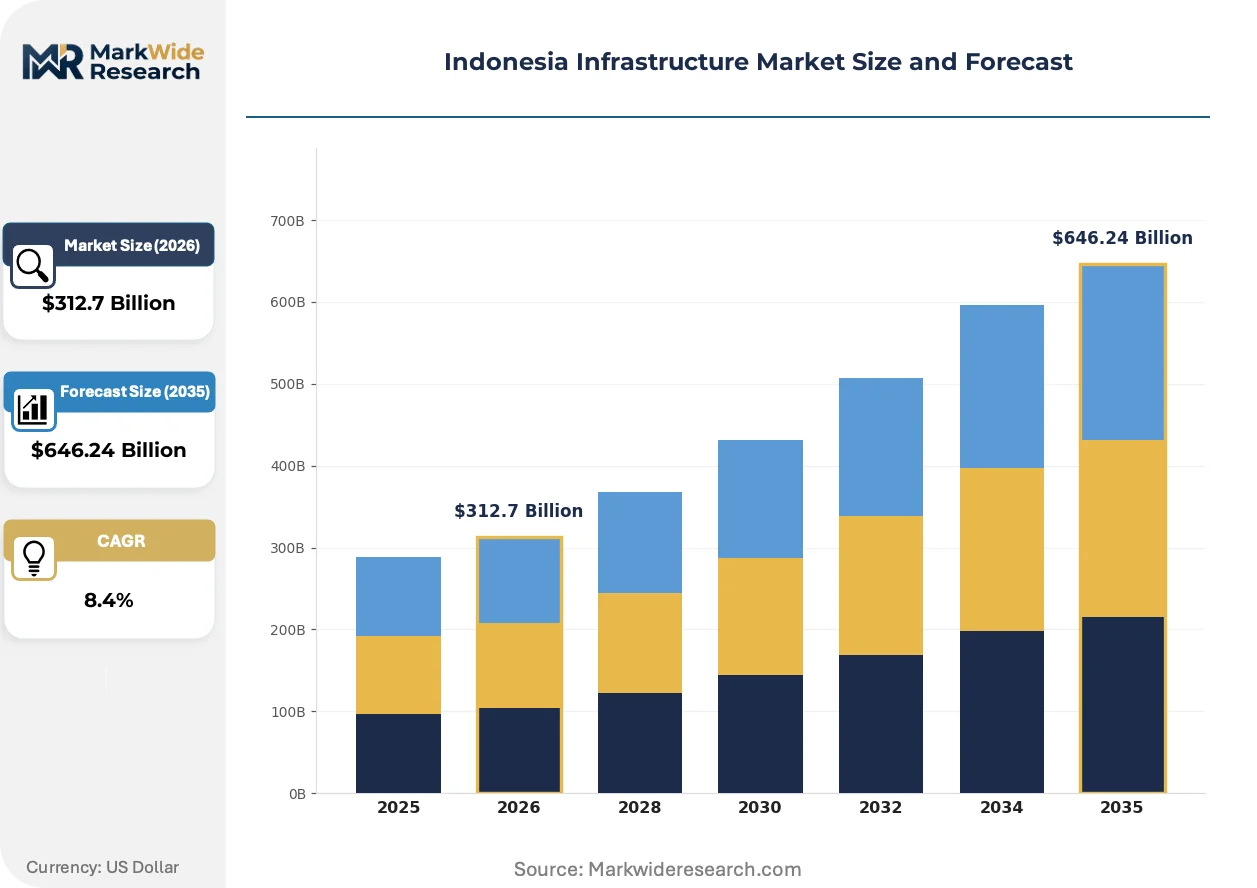
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Transportation, Water Supply, Renewable Energy, Telecommunications Funding Source: Government, Private Investment, Development Banks, Public-Private Partnership Construction Phase: Planning, Design, Construction, Maintenance End User: Government Agencies, Contractors, Developers, Utility Providers |
| Companies Covered | PT Hutama Karya (Persero), PT Waskita Karya (Persero) Tbk, PT Nusantara Infrastructure Tbk, PT Pembangunan Perumahan (Persero) Tbk, PT Jasa Marga (Persero) Tbk, PT Adhi Karya (Persero) Tbk, PT Wijaya Karya (Persero) Tbk, PT Indonesia Pondasi Raya Tbk, PT Brantas Abipraya (Persero), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Infrastructure Market Trends and Innovations
Digital twin deployment is compressing design-validation cycles across Indonesian megaprojects. Real-time structural monitoring systems are displacing periodic inspection regimes. These shifts are reshaping contractor capability requirements and owner-operator maintenance strategies.
Building Information Modeling is miniaturizing design iteration costs for complex bridge geometries. State-owned contractors in Sumatra are adopting cloud-based clash detection to accelerate pre-construction phases. This compression is enabling competitive bidding on shorter timelines without sacrificing seismic resilience verification.
Bappenas carbon accounting requirements are tightening procurement eligibility criteria. Infrastructure bids must now document embodied carbon in concrete and steel selections. Transportation projects in Java face the strictest thresholds, with contractors substituting fly ash blends to meet emission intensity caps.
Consortium-based bidding is displacing single-contractor submissions for billion-dollar packages. International engineering firms are partnering with domestic state-owned enterprises to satisfy local content rules. This pattern concentrates most visibly in geothermal and hydropower tenders where technology transfer mandates apply.
Indonesia Infrastructure Market Segmentation
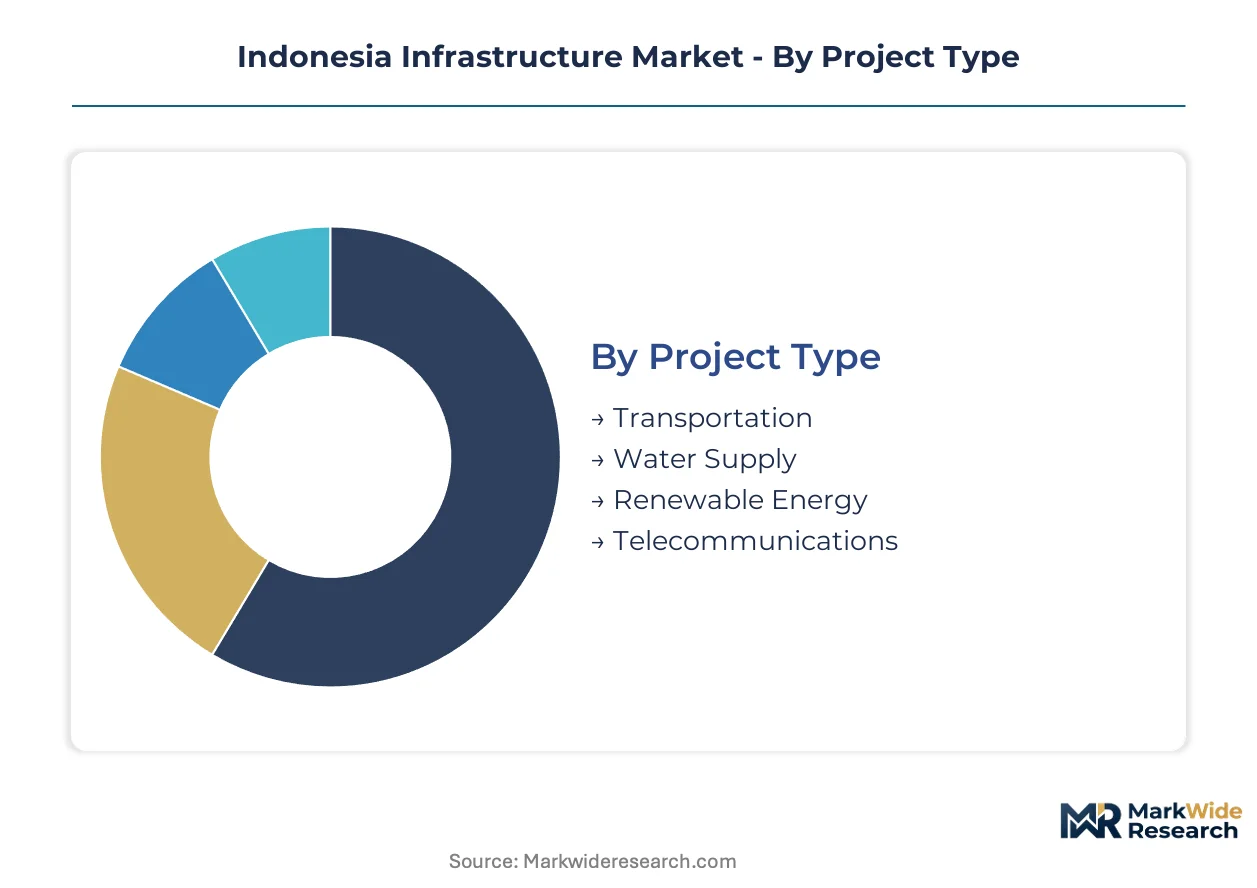
Indonesia's infrastructure segmentation reflects divergent risk-return profiles across project lifecycles. Procurement channels and construction phases determine capital deployment timelines and contractor capability requirements.
Project Type:
Bappenas masterplan allocation criteria weight seismic resilience differently across asset classes, redirecting technical specifications and contractor eligibility.
- Transportation:Toll roads, bridges, and port terminals dominate capital allocation. The Trans-Java arterial network and Sumatra toll corridors concentrate civil engineering demand, with SNI seismic codes mandating 0.3g peak ground acceleration compliance for all public structures.
- Renewable Energy:Geothermal drilling and solar farm construction represent the steepest expansion trajectory. Utility-scale projects across the volcanic corridor from Sumatra to Sulawesi require specialized geotechnical capabilities and technology transfer partnerships.
- Water Supply:Treatment facilities and distribution networks address urban water security. Jakarta and Surabaya retrofit deadlines compress project timelines for aging infrastructure upgrades.
- Telecommunications:Fiber backbone and 5G tower installations enable archipelagic connectivity. Undersea cable landing stations and rural network extensions attract blended finance structures.
Transportation handles the majority of throughput; Renewable Energy is the fastest mover on share.
Funding Source:
Capital cost tiers separate sovereign-backed vehicles from commercial risk-bearing instruments, shaping contractor margin structures and concession lengths.
- Government:State budget allocations through the Ministry of Public Works and Housing fund maintenance contracts and priority corridors. These channels offer stable but thinner returns with limited negotiation leverage on pricing.
- Public-Private Partnership:Long-term concession arrangements concentrate margin pools in operational phases. PT Sarana Multi Infrastruktur risk-sharing mechanisms reduce sovereign exposure while attracting institutional co-investment.
- Private Investment:Domestic conglomerates and infrastructure funds deploy equity into revenue-generating assets. Toll road operational concessions and port modernization projects draw the largest private capital commitments.
- Development Banks:Multilateral financing structures support Eastern Indonesia connectivity and climate adaptation projects. Maritime highway programs across Maluku and Papua leverage concessional lending terms.
Government channels anchor volume throughput; Public-Private Partnership structures are climbing the fastest on deployment speed.
Construction Phase:
Project maturity stages determine digital tool adoption intensity and talent specialization requirements across contractor portfolios.
- Construction:Physical execution of civil works commands the largest workforce deployment. State-owned contractors dominate through integrated design-build capabilities and government-backed balance sheets.
- Planning:Feasibility studies and environmental permitting face land acquisition friction. Central Java toll projects average extended delays between permit approval and groundbreaking.
- Design:Building Information Modeling adoption miniaturizes iteration costs for complex bridge geometries. Cloud-based clash detection accelerates pre-construction phases without sacrificing seismic verification.
- Maintenance:Legacy asset retrofit markets expand under SNI compliance deadlines. Real-time structural monitoring systems displace periodic inspection regimes for critical infrastructure.
Construction absorbs the dominant share of contractor capacity; Maintenance is expanding most quickly on retrofit-driven demand.
End User:
Customer type segmentation aligns procurement authority with technical specification control across the project value chain.
- Government Agencies:Bappenas and the Ministry of Public Works and Housing set masterplan priorities and SNI technical standards. Carbon accounting requirements now tighten procurement eligibility for transportation bids.
- Contractors:State-owned enterprises anchor project execution through consortium-based bidding. PT Hutama Karya and PT Waskita Karya leverage integrated capabilities to satisfy local content rules.
- Developers:Mixed-use and industrial zone developers drive last-mile infrastructure requirements. Logistics operators relocate distribution centers to Trans-Java corridor nodes, amplifying connectivity demand.
- Utility Providers:PLN and regional water utilities specify performance standards for grid and treatment assets. Geothermal capacity targets escalate civil works demand across volcanic regions.
Government Agencies control the primary procurement pipeline; Utility Providers are gaining share fastest on renewable energy transition mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry separates Java's mature toll corridors from Eastern Indonesia's emerging port zones. State-backed contractors command premium rates on Sumatra's Trans-Sumatra Highway where land acquisition friction remains manageable. Eastern archipelago projects absorb higher risk premiums due to logistics complexity and seismic engineering demands.
Java
The Trans-Java toll network anchors national freight efficiency with 0.3g seismic compliance mandates across arterial corridors. Bappenas prioritizes corridor integration under the national infrastructure acceleration program. Industrial clusters around Jakarta, Surabaya, and Semarang drive last-mile distribution center construction.
Sumatra
Geothermal drilling contracts across the volcanic corridor from Aceh to Lampung accelerate civil works demand. The Ministry of Public Works and Housing mandates SNI seismic retrofit deadlines for pre-2010 structures. Medan and Palembang concentrate toll road expansion where PT Hutama Karya dominates state-backed construction.
Sulawesi
Nickel processing industrial zones amplify port modernization requirements across the northern and eastern coasts. Development bank financing structures support maritime highway connectivity under blended finance mechanisms. Makassar anchors inter-island shipping infrastructure where concession opportunities attract first-mover investment.
Kalimantan
New capital city relocation drives greenfield urban infrastructure demand in East Kalimantan. Carbon accounting requirements under Bappenas procurement criteria tighten eligibility for transportation bids. Balikpapan and Samarinda concentrate construction workforce deployment for integrated city-building packages.
Papua and Maluku
Maritime highway programs target underdeveloped inter-island shipping infrastructure across the eastern archipelago. Concessional lending terms from multilateral development banks reduce sovereign exposure on remote projects. Jayapura and Ambon represent nascent operational bases where geotechnical engineering talent scarcity compresses project timelines.
Indonesia Infrastructure Market Competitive Landscape
Concentration sits with state-owned enterprises wielding government-backed balance sheets and integrated design-build capabilities. The contractor base stratifies across three tiers: capital-intensive state giants, mid-tier private builders, and specialized geotechnical firms. Competitive positioning hinges on consortium formation for technology transfer compliance and land acquisition execution speed rather than pure cost minimization. Dominant moves include strategic partnerships with international engineering firms and backward integration into quarried materials supply.
Within the state-owned tier, PT Hutama Karya (Persero), PT Waskita Karya (Persero) Tbk, and PT Jasa Marga (Persero) Tbk occupy anchor positions. These Persero entities exemplify the integrated capability model spanning financing, construction, and operational concessions. PT Hutama Karya represents the toll road specialization archetype, PT Waskita Karya exemplifies diversified engineering-procurement-construction positioning, and PT Jasa Marga occupies the operational concession niche with traffic-flow monetization partnerships.
| Leading Market Players |
|---|
| PT Hutama Karya (Persero) |
| PT Waskita Karya (Persero) Tbk |
| PT Nusantara Infrastructure Tbk |
| PT Pembangunan Perumahan (Persero) Tbk |
| PT Jasa Marga (Persero) Tbk |
| PT Adhi Karya (Persero) Tbk |
| PT Wijaya Karya (Persero) Tbk |
| PT Indonesia Pondasi Raya Tbk |
| PT Brantas Abipraya (Persero) |
| Others |
Pricing and Supply Chain Analysis
Long-term concession arrangements lock in supply access for state-backed contractors while anchoring price visibility across multi-decade operational phases. These structures insulate PT Hutama Karya and PT Jasa Marga from raw material volatility while compressing margin flexibility for mid-tier builders exposed to spot-market steel rebar procurement.
Pricing Analysis
The customization-premium spread separates integrated design-build contracts from standard maintenance tenders. State-owned giants command configured-to-order pricing through consortium-based submissions that bundle geotechnical engineering with operational concessions. Standard government-funded maintenance contracts trade at thinner margins with limited negotiation leverage. Price differentiation rests on SNI seismic certification tiers and land acquisition execution speed rather than pure construction cost. Pricing pressure stems from rupiah depreciation against yen-denominated heavy equipment imports. Private developers exhibit highest price sensitivity on last-mile connectivity projects, while utility providers accept premium tiers for geothermal drilling contracts.
Supply Chain Analysis
Japan and South Korea anchor heavy equipment fabrication for Indonesian civil works. Excavators and pile drivers feed from Komatsu and Hyundai manufacturing bases. Steel rebar draws from domestic billet production where state-owned smelters control captive supply. Cement and quarried aggregates source from regional Indonesian production clusters. Supply chain risk centers on currency-driven cost escalation for imported machinery. Distribution runs through state-owned contractor procurement divisions with direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia infrastructure operates at a platform-economics inflection where smart tolling data feeds attract fintech partnerships for traffic-flow monetization. Interoperability between RFID gantries and dynamic pricing algorithms is restructuring concession value capture.
For Market Incumbents: Fortify consortium formation capabilities to satisfy technology transfer mandates in geothermal and hydropower tenders. Deepen backward integration into quarried materials supply to offset steel rebar cost volatility. State-owned giants must defend against mid-tier private builders gaining SNI seismic certification traction. For New Entrants and Emerging Players: Anchor in Eastern Indonesia connectivity gaps where maritime highway programs offer first-mover concession opportunities. Maluku and Papua port modernization presents the most penetrable geography. Pursue blended finance co-investment vehicles with PT Sarana Multi Infrastruktur to unlock institutional capital. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operational concession holders with traffic-flow monetization partnerships. Long-term viability favors contractors with integrated design-build capabilities spanning seismic resilience verification. Monitor land acquisition reform legislation as the critical inflection signal for project timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Consortium-Based Bidding | International engineering firms partner with domestic state-owned enterprises to satisfy local content rules in geothermal tenders. |
| Smart Tolling Integration | RFID gantry deployment with dynamic pricing algorithms enables revenue optimization for PT Jasa Marga operational concessions. |
| Backward Integration | Captive supply of quarried materials insulates state-owned contractors from cement and aggregate price volatility. |
| Blended Finance Structuring | Pension fund co-investment vehicles reduce sovereign exposure on water treatment assets across Eastern Indonesia. |
| Digital Twin Deployment | Real-time structural monitoring systems displace periodic inspection regimes for SNI compliance verification. |
Research Methodology
Desk research of Bappenas masterplan allocations, Ministry of Public Works and Housing procurement databases, and PT Sarana Multi Infrastruktur financing disclosures preceded structured interviews with toll road concession managers, geotechnical engineering directors, state-owned enterprise procurement leads, and development bank infrastructure officers. Secondary validation drew from SNI seismic code documentation, land acquisition permit records, and contractor financial filings. Bottom-up project pipeline enumeration triangulated against top-down macroeconomic allocation forecasts.
Variance decomposition across project type, funding source, construction phase, and end user segmentation anchors the analytical framework throughout the projection horizon. CAGRs derive from weighted capacity deployment timelines and concession award trajectories. Modeled inputs include geothermal capacity targets, Trans-Java toll integration milestones, and SNI retrofit compliance deadlines.
Material uncertainties — regulatory shifts around land acquisition reform, rupiah volatility against equipment import currencies, and geotechnical engineering talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about Bappenas allocation continuity and state-owned enterprise dominance. Recalibration cycles align with material shifts in procurement eligibility criteria and blended finance mechanism adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Tanzania Construction Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Egypt Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
Vietnam Construction Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
UAE Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Oman Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
US Offsite Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Malaysia Construction Market