
 Middle East Building Construction Market | 2026-2036
Middle East Building Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Building Construction Market Analytics
Islamic project finance and sukuk-based infrastructure funding is reshaping capital access for contractors across the Gulf. ALEC Engineering and Contracting leverages its Dubai headquarters to anchor large-scale commercial and residential portfolios. CSCEC sustains competitive positioning through manufacturing scale and integrated EPC capabilities. Khansaheb Civil Engineering specializes in heritage-sensitive restoration and high-specification finishing across UAE landmark sites.
Middle East building construction encompasses the assembly of reinforced concrete and steel structural frames, facade integration, and mechanical-electrical-plumbing installation for commercial, residential, and institutional occupancy. Concrete grade specifications typically range from C40 to C60 for high-rise cores, with curtain wall systems engineered for thermal performance exceeding 2.5 W/m²K in Gulf climates. Residential Properties and Commercial Buildings dominate end-user value pools, though Green Building Initiatives within the application dimension are attracting premium-margin contracts as Pearl and LEED certification thresholds tighten. Structural Components and MEP Systems command disproportionate share in project cost breakdowns, while Smart Building Solutions represents the fastest-expanding technology category as Gulf utilities mandate demand-response readiness.
Saudi Arabia's Saudi Building Code Authority, the UAE's Estidama Pearl Rating System, and Qatar's GSAS standards collectively dictate energy performance, material sourcing, and labor safety compliance across the region. These frameworks are elevating specification thresholds for imported MEP equipment and locally manufactured structural elements. Stakeholders must monitor regulatory divergence between Gulf Cooperation Council states as procurement rules and sustainability mandates continue to differentiate national construction environments.
Market Dynamics
Saudi Arabia's Saudi Building Code Authority enforcement is compressing project timelines while elevating specification thresholds for structural concrete and MEP systems across the Gulf. Contractors face simultaneous pressure to certify heritage-sensitive restoration capabilities and deploy demand-responsive smart building infrastructure.
Growth Catalysts
- Estidama Pearl Rating System:UAE mandates for minimum Pearl certification are expanding green building contract pipelines and premium-margin renovation scopes.
- Hospitality Megaproject Corridors:Dubai and Abu Dhabi are accelerating hotel and entertainment complex construction ahead of major international event cycles.
- Sukuk Infrastructure Funding:Islamic project finance instruments are unlocking capital access for contractors previously constrained by conventional lending limits.
Market Restraints
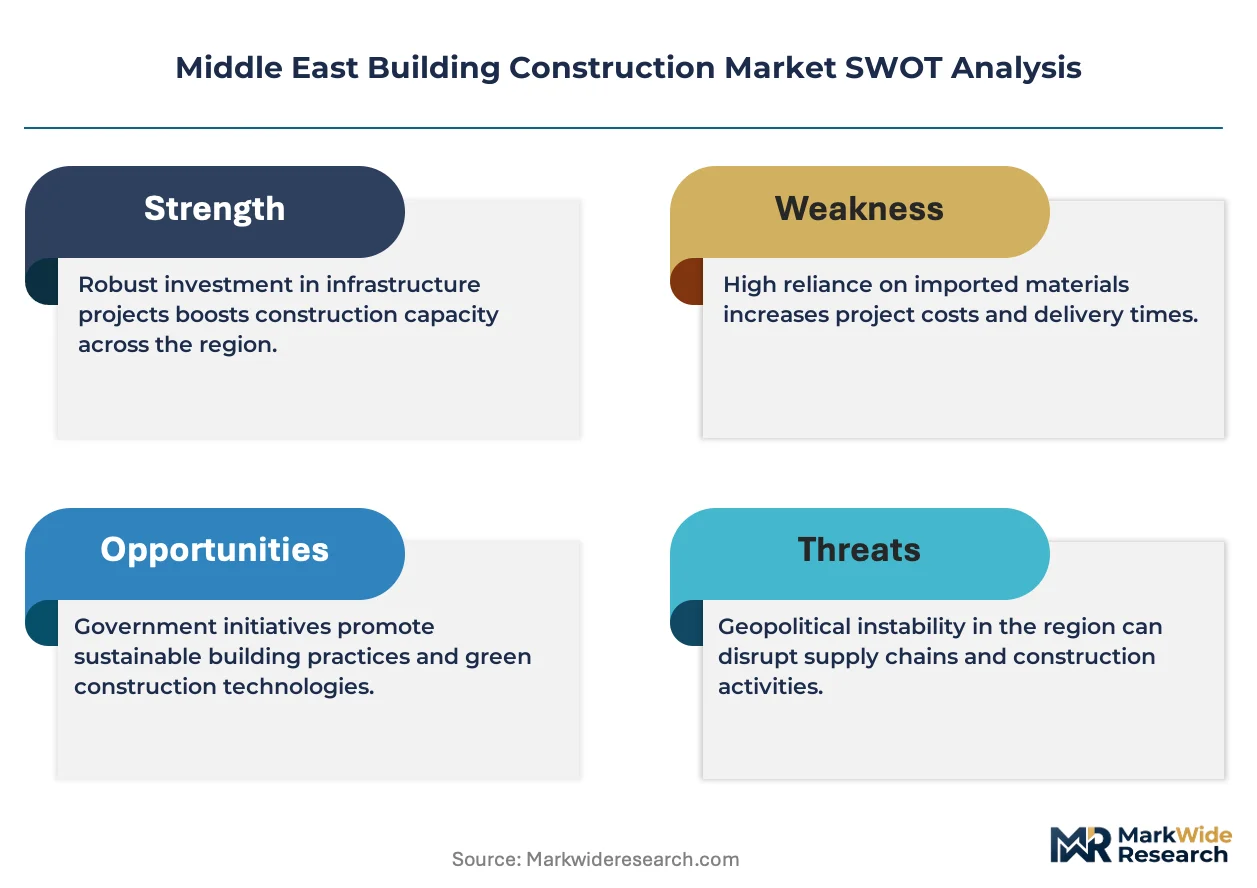
- Steel Input Volatility:Reinforcement bar and structural steel pricing fluctuations from East Asian suppliers compress fixed-price contract margins.
- MEP Equipment Import Concentration:European and East Asian HVAC and electrical component sourcing creates supply chain vulnerability for Gulf-based contractors.
- GSAS Certification Complexity:Qatar's green building standards diverge from UAE and Saudi frameworks, fragmenting regional contractor qualification requirements.
Strategic Opportunities
- Heritage Restoration Specialization:UAE landmark preservation contracts reward contractors with demonstrated capability in traditional building techniques and high-specification finishing.
- Smart Building-Demand Response Convergence:Integration of building automation systems with Gulf utility grid-interactive programs opens new technology service revenue streams.
- Saudi Secondary City Expansion:Building code enforcement outside Riyadh and Jeddah is stimulating construction demand in underpenetrated provincial markets.
Industry Challenges
- Skilled Craft Labor Scarcity:Certified welders, facade installers, and heritage restoration specialists command premium wages and extended recruitment cycles.
- Multi-Certification Compliance Burden:Contractors operating across Saudi Arabia, UAE, and Qatar must maintain parallel quality assurance systems for divergent national standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Building Construction Market |
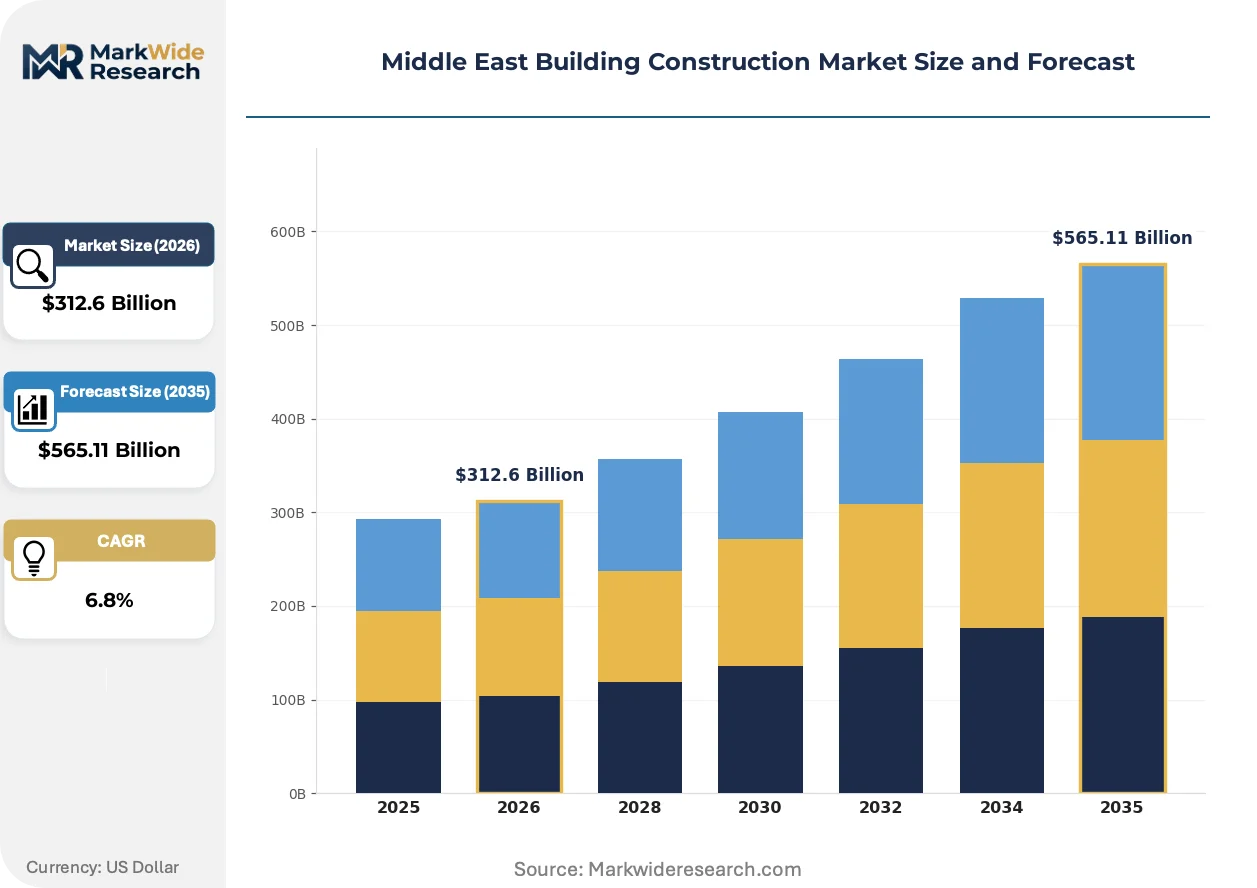
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Components, Finishing Materials, MEP Systems, Facades End User: Commercial Buildings, Residential Properties, Educational Institutions, Healthcare Facilities Application: New Construction, Renovation Projects, Infrastructure Development, Green Building Initiatives Technology: Building Information Modeling, Prefabrication, Smart Building Solutions, Sustainable Materials |
| Companies Covered | Sobha Constructions, Wade Adams Contracting, China State Construction Engineering Corporation (CSCEC), Arabian Construction Company (ACC), Trojan Construction Group, AMANA Group, ALEC Engineering and Contracting, ASGC Construction, Khansaheb Civil Engineering, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Building Construction Market Evolving Landscape
Building information modeling and prefabricated structural systems are compressing traditional construction timelines while Gulf regulators mandate tighter energy performance thresholds. These shifts favor contractors with integrated design-build capabilities and captive manufacturing assets.
Modular concrete core construction is rendering obsolete conventional cast-in-place methods for high-rise residential towers. UAE and Saudi developers are specifying precast structural elements for projects exceeding 40 stories, compressing floor-cycle times from fourteen days to eight days and reducing on-site labor exposure to extreme summer temperatures.
Estidama Pearl Rating System Version 2.0 implementation is tightening thermal performance requirements for curtain wall assemblies. Developers in Abu Dhabi must now specify facade systems exceeding 1.8 W/m²K U-values, forcing specification upgrades from standard aluminum systems to thermally broken composite configurations and expanding demand for specialized glazing contractors.
Developer procurement teams are consolidating vendor panels and demanding extended warranty packages spanning structural, MEP, and smart building systems. Large-scale mixed-use projects in Dubai now require single-point accountability for ten-year performance guarantees, displacing fragmented subcontractor arrangements and favoring integrated EPC contractors with captive commissioning capabilities.
Middle East Building Construction Market Segmentation
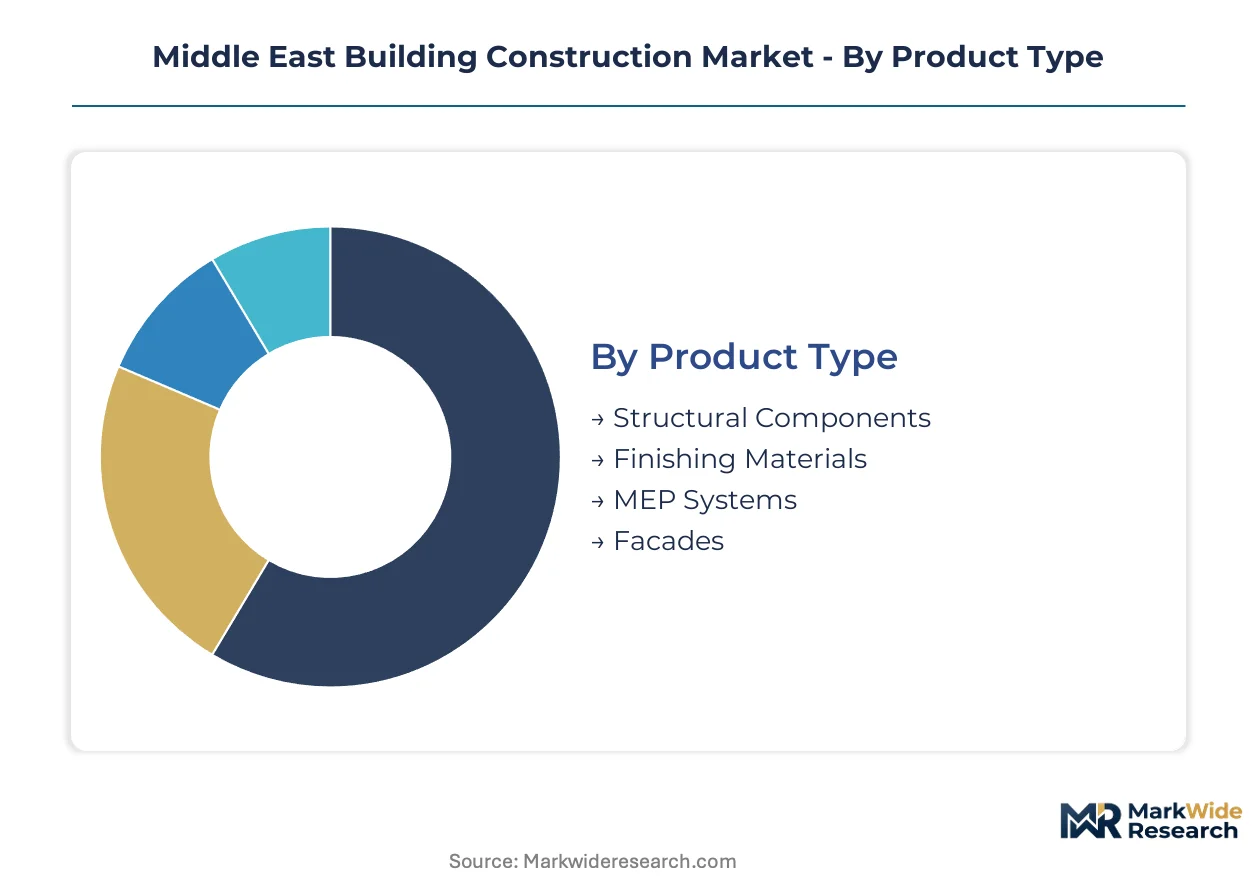
Middle East building construction segmentation reveals how specification requirements diverge across project types. Procurement patterns in the Gulf reward contractors who align capabilities with distinct regulatory and performance thresholds.
Product Type:
Structural demands span reinforced concrete cores to intelligent facade systems across the project lifecycle.
- Structural Components:Reinforced concrete and steel frames form the load-bearing skeleton of high-rise towers. Demand concentrates in Saudi Arabia's secondary city expansion, where the Saudi Building Code Authority mandates C50-C60 concrete grades for structures exceeding 20 stories.
- MEP Systems:Mechanical, electrical, and plumbing infrastructure integrates HVAC, power distribution, and water management. Abu Dhabi's Estidama Pearl Rating System Version 2.0 is forcing specification upgrades to European-imported equipment with enhanced efficiency ratings.
- Finishing Materials:Interior surface treatments and fit-out elements complete occupant-ready spaces. Heritage restoration contracts in Dubai reward specialists in traditional plaster and stone techniques.
- Facades:Curtain wall and cladding systems manage thermal performance and aesthetic expression. Qatar's GSAS certification complexity creates procurement friction for contractors operating across multiple Gulf markets.
The dominant share belongs to Structural Components, while MEP Systems is closing the gap fastest.
End User:
Occupancy types dictate divergent specification intensities and certification burdens.
- Commercial Buildings:Office towers, retail complexes, and mixed-use developments demand integrated smart building infrastructure. Dubai's megaproject corridors are accelerating hotel and entertainment complex construction ahead of international event cycles.
- Residential Properties:High-rise apartments and villa compounds constitute volume demand. Saudi Arabia's building code enforcement outside Riyadh and Jeddah is stimulating provincial market entry.
- Educational Institutions:Schools and university campuses require specialized safety and accessibility compliance. UAE federal procurement mandates extended warranty packages for institutional occupancy.
- Healthcare Facilities:Hospitals and clinics demand infection-control-grade MEP and structural redundancy. MOHAP regulations in the UAE govern medical construction standards separately from general building codes.
Commercial Buildings command the largest project value, though Residential Properties shows the steepest expansion trajectory.
Application:
Project delivery modes reflect capital cycle timing and regulatory incentive structures.
- New Construction:Ground-up development of towers, campuses, and infrastructure. Sukuk-based infrastructure funding is unlocking capital access for contractors previously constrained by conventional lending limits.
- Green Building Initiatives:Certification-driven construction and renovation targeting sustainability thresholds. Estidama Pearl mandates in Abu Dhabi are expanding premium-margin renovation scopes.
- Renovation Projects:Adaptive reuse and upgrade of existing structures. UAE landmark preservation contracts reward heritage-sensitive restoration capabilities.
- Infrastructure Development:Transportation, utilities, and public works construction. Saudi secondary city expansion is stimulating demand in underpenetrated provincial markets.
New Construction retains the dominant share, while Green Building Initiatives is gaining share fastest.
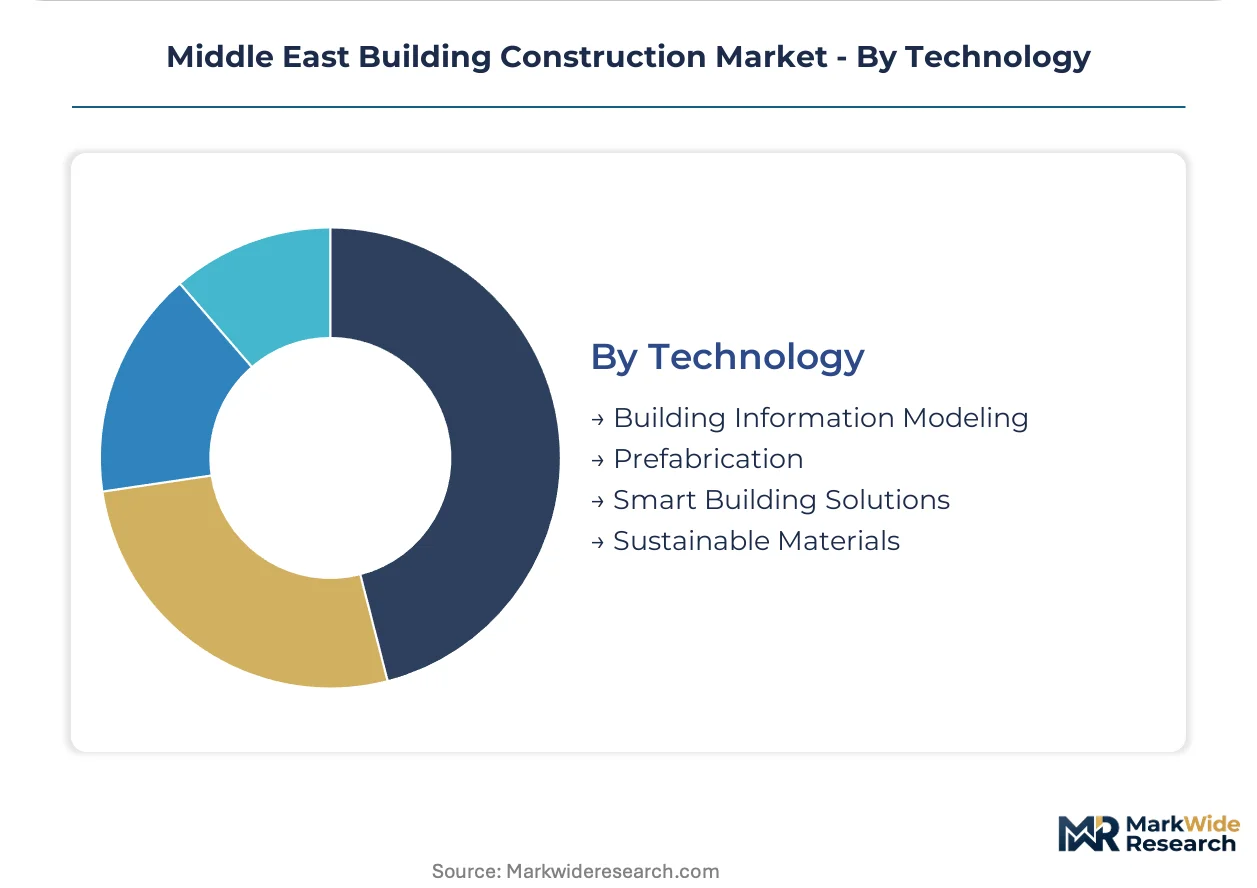
Technology:
Digital and manufacturing capabilities are compressing timelines while elevating performance accountability.
- Smart Building Solutions:Integrated automation systems enabling demand-response grid interaction. Gulf utilities mandate demand-response readiness for new commercial developments.
- Building Information Modeling:Digital twin construction and clash detection platforms. Large-scale mixed-use projects in Dubai now require single-point accountability for ten-year performance guarantees.
- Prefabrication:Off-site manufacturing of structural and MEP elements. UAE and Saudi developers specify precast concrete cores for towers exceeding 40 stories.
- Sustainable Materials:Low-carbon concrete, recycled steel, and bio-based insulation. GSAS standards in Qatar diverge from UAE and Saudi frameworks, fragmenting material qualification requirements.
Building Information Modeling holds the dominant deployment share, while Smart Building Solutions is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saudi Building Code Authority enforcement is compressing project timelines while elevating specification thresholds across Gulf states. National regulators are fragmenting compliance requirements as Estidama Pearl, GSAS, and SBC frameworks diverge on energy performance and material sourcing mandates.
Saudi Arabia
Riyadh's secondary city expansion and NEOM giga-project development are stimulating concrete demand for structures exceeding 20 stories. The Saudi Building Code Authority mandates C50-C60 concrete grades for high-rise cores, forcing specification upgrades from regional suppliers. The Eastern Province industrial corridor around Dammam is attracting precast manufacturing investment to serve provincial market entry.
United Arab Emirates
Dubai and Abu Dhabi megaproject corridors are accelerating hotel and entertainment complex construction ahead of international event cycles. Estidama Pearl Rating System Version 2.0 implementation is tightening thermal performance requirements for curtain wall assemblies. The Dubai Design District cluster is consolidating vendor panels and demanding extended warranty packages spanning structural, MEP, and smart building systems.
Qatar
GSAS certification complexity is fragmenting regional contractor qualification requirements and creating procurement friction for multi-national operators. The country's green building standards diverge from UAE and Saudi frameworks on material sourcing and energy performance thresholds. Doha's Lusail development zone is specifying facade systems with enhanced U-values, expanding demand for specialized glazing contractors.
Kuwait
Public infrastructure renewal and residential tower development are sustaining project pipelines despite financing constraints from conventional lending limits. The national building code is adopting Gulf Cooperation Council harmonization measures while retaining local fire safety and seismic provisions. Kuwait City's waterfront regeneration is rewarding contractors with heritage-sensitive restoration capabilities and high-specification finishing expertise.
Middle East Building Construction Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base organizes around three strategic archetypes: integrated EPC contractors with captive manufacturing assets, heritage-sensitive restoration specialists, and scale-driven international operators with sukuk funding access. Competitive moves concentrate on portfolio diversification into smart building solutions and strategic partnerships with European MEP equipment suppliers.
Within the integrated EPC tier, China State Construction Engineering Corporation and ALEC Engineering and Contracting exemplify scale-driven positioning through manufacturing depth and regional headquarters leverage. Khansaheb Civil Engineering occupies a heritage-specialist position, anchoring high-specification finishing demand across UAE landmark preservation contracts. Sobha Constructions represents the premium-tier residential developer-contractor model, consolidating single-point accountability for extended performance guarantees.
| Leading Market Players |
|---|
| Sobha Constructions |
| Wade Adams Contracting |
| China State Construction Engineering Corporation (CSCEC) |
| Arabian Construction Company (ACC) |
| Trojan Construction Group |
| AMANA Group |
| ALEC Engineering and Contracting |
| ASGC Construction |
| Khansaheb Civil Engineering |
| Others |
Value Network & Pricing Analysis
Jebel Ali Port freight corridors anchor cost dynamics for Gulf contractors, linking East Asian steel concentration to downstream price spreads between integrated EPC operators and fragmented finishing specialists. Certification burden divergence across Saudi Building Code Authority, Estidama Pearl, and GSAS frameworks compounds logistics cost allocation, forcing tiered contractor positioning based on compliance capital depth.
Pricing Analysis
Certification level creates the primary spread between premium integrated contractors and commodity finishing subcontractors. Three-tier pricing structure across Pearl-certified, SBC-compliant, and baseline-grade project portfolios reflects divergent warranty obligations and MEP equipment specification intensity. Cost compression in standard-grade residential towers is intensifying because East Asian reinforcement bar volatility transmits directly to fixed-price contract margins. Developer procurement teams show lowest price sensitivity on heritage restoration and smart building integration scopes, while provincial Saudi residential projects exhibit highest bid competition.
Supply Chain Analysis
European and East Asian export control classifications on high-efficiency HVAC and building automation components restrict flow availability for Gulf utilities mandating demand-response readiness. Manufacturing concentration in China, South Korea, and Germany for curtain wall glazing and MEP control systems creates procurement friction when GSAS certification requires divergent material qualification. Reinforcement bar, structural steel, and precast concrete elements rest on East Asian smelter output and regional Emirates-based precast yards. Single-source vulnerability runs through European HVAC component suppliers serving Abu Dhabi's Estidama Pearl Version 2.0 upgrades. Distribution runs through developer-consolidated vendor panels demanding ten-year single-point accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building automation platform interoperability is reshaping competitive boundaries as Gulf utilities mandate grid-interactive demand response, creating ecosystem lock-in effects for contractors with captive commissioning capabilities.
For Market Incumbents: Pre-empt modular construction technology displacement by acquiring precast manufacturing capacity in Saudi Arabia's Eastern Province industrial corridor. Anchor position against emerging scale-driven Chinese entrants by deepening Estidama Pearl Version 2.0 certification depth ahead of Abu Dhabi's thermal performance mandate escalation. Prioritize backward integration into MEP equipment distribution to capture margin compression from European import concentration.
For New Entrants and Emerging Players: Saudi Arabia's secondary city provincial markets outside Riyadh and Jeddah offer lowest incumbent certification density and compressed bidding competition. Target heritage-sensitive restoration capabilities in Dubai landmark preservation contracts where specialist scarcity commands premium positioning. Deploy sukuk-funded project finance access as differentiated capital structure against conventional lending-constrained competitors.
For Investors and Strategic Acquirers: Heritage-specialist contractors with demonstrated GSAS-Estidama dual certification capability represent asymmetric acquisition targets given multi-market qualification fragmentation. Long-term viability hinges on regulatory divergence persistence across Gulf Cooperation Council states rather than harmonization. Monitor Saudi Building Code Authority enforcement intensity in provincial markets as inflection signal for secondary city construction acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precast Manufacturing Scale-Up | Compresses floor-cycle times for towers exceeding 40 stories while reducing summer labor exposure. |
| Dual Certification Investment | Captures cross-border contracts as GSAS, Estidama Pearl, and SBC frameworks diverge on compliance thresholds. |
| Smart Building Platform Integration | Locks in ten-year performance guarantee contracts with Dubai developer procurement consolidation. |
| Sukuk Infrastructure Funding Access | Unlocks capital for contractors constrained by conventional lending limits on giga-project pipelines. |
| Heritage Restoration Capability Buildout | Secures UAE landmark preservation contracts rewarding traditional plaster and stone technique specialization. |
Research Methodology
Initial hypotheses were tested against primary input from EPC contractor procurement directors, MEP equipment specification engineers, developer project finance officers, and Saudi Building Code Authority compliance consultants and refined through secondary validation. Construction project databases, Gulf Cooperation Council customs trade records, Estidama Pearl certification registries, and sukuk issuance filings anchored quantitative segmentation. Bottom-up project pipeline aggregation and top-down macro construction spend estimates were triangulated to resolve variance.
Demand-supply balance modeling across the projection horizon incorporated new construction versus renovation project mix, green building certification penetration by emirate, and smart building technology adoption curves mandated by utility grid-interactive programs. Segmentation dimensions spanned structural component intensity, MEP system specification grade, end-user occupancy type, and technology integration depth. CAGRs were derived from project value aggregation across disclosed contract awards and pipeline announcements, cross-referenced against regulatory enforcement timelines for building code implementation.
The forecast holds incumbent behavior within observed patterns; aggressive precast manufacturing investment by China State Construction Engineering Corporation or accelerated sukuk funding deployment by regional Islamic banks would shift outcomes. Material shifts in Saudi Building Code Authority provincial enforcement intensity, Estidama Pearl Version 3.0 thermal performance threshold escalation, or Gulf utility demand-response mandate timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Indonesia Infrastructure Market
Building Construction
Italy Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
Egypt Residential Construction Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
GCC Cement Market
Building Construction
China Modular Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Cold Storage Construction Market
Building Construction
UK Construction Market
Building Construction
UAE Facade Market
Building Construction
Singapore Data Center Construction Market
Building Construction
India Prefabricated Buildings Market
Building Construction
GCC Construction Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
Modular and Portable Building Market