
 Liquid Masking Film Market | 2026-2036
Liquid Masking Film Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Masking Film Market Foresight
The split between premium-grade solvent-based films and commodity water-based alternatives is hardening as bake-cycle temperatures and peel-cleanliness standards diverge across end-use tiers. PPG Industries leverages its automotive OEM relationships to sustain formulation leadership in high-performance segments. Axalta Coating Systems anchors its position through captive supply of resin intermediates for UV-cured masking systems. BASF competes on geographic reach, extending its solvent-based portfolio across European industrial coatings channels where REACH compliance adds technical barriers to entry.
Liquid masking film comprises a peelable, temporary coating applied by spray, brush, or dip to shield surfaces from paint overspray, chemical exposure, or mechanical abrasion during manufacturing and refinishing operations; typical formulations incorporate acrylic or rubber-based polymers with controlled elongation of 200-400% to ensure clean removal without substrate damage. Water-based variants are gaining share in automotive refinishing as VOC regulations tighten, though solvent-based grades retain margin concentration in aerospace and heavy-equipment applications requiring chemical resistance above 150°C. UV-cured films represent the fastest-growing technology segment, driven by electronics manufacturers seeking instant cure cycles for circuit board masking, while all-purpose formulations occupy the volume tier through hardware and online retail channels serving maintenance and arts markets.
EPA VOC regulations in the United States and REACH chemical restrictions in Europe are reshaping formulation chemistry, compelling suppliers to reformulate solvent systems or shift toward water-based and UV-curable platforms to maintain market access. Japan's METI industrial chemical standards and China's GB coating limits add further compliance layers for multinational suppliers serving cross-border automotive supply chains. Stakeholders must monitor regulatory divergence between jurisdictions while deciding whether to specialize in premium compliant formulations or compete on scale in regions with slower environmental rule adoption.
Market Dynamics
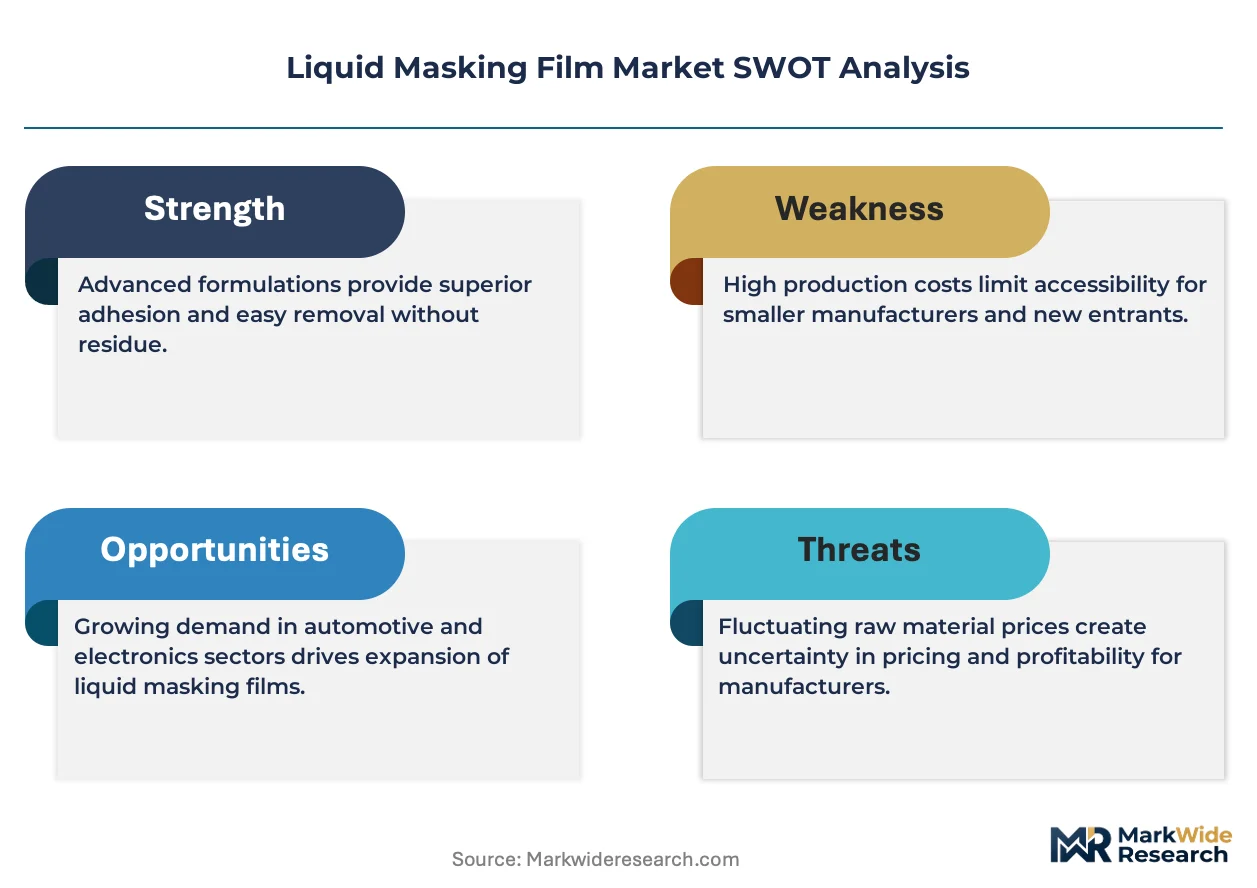
EPA VOC regulations and REACH chemical restrictions are bifurcating formulation strategies, forcing suppliers to choose between reformulating solvent systems for high-temperature aerospace applications or pivoting to water-based platforms for automotive refinishing compliance.
Growth Catalysts
- EPA VOC Phase-Out Deadlines:Automotive refinishing shops across the United States are accelerating water-based film adoption to meet tightening emission limits on spray-applied coatings.
- Electronics Miniaturization:Circuit board manufacturers in East Asia are scaling UV-cured masking systems for instant-cure precision in high-density assembly lines.
- German Industrial Coatings Cluster:OEM concentration in Stuttgart and Wolfsburg sustains solvent-based demand for bake-cycle applications above 150°C.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and rubber-based polymer costs fluctuate with crude oil derivatives, compressing margin stability for commodity-grade producers.
- Specialty Resin Supply Concentration:UV-curable oligomer production concentrates among a handful of European and Japanese chemical suppliers, creating bottleneck risk for masking film formulators.
- Water-Based Performance Ceiling:Water-based films fail to achieve the chemical resistance and peel-cleanliness standards required for aerospace turbine masking and heavy-equipment coating lines.
Strategic Opportunities
- India Automotive Manufacturing:PLI scheme incentives for domestic vehicle production are expanding coating line infrastructure where masking film penetration remains below Western levels.
- Battery Cell Assembly:Electric vehicle manufacturers are testing dielectric masking films for thermal management coating of battery housings and module enclosures.
- Online Hardware Retail:Maintenance and arts markets are shifting toward direct-to-consumer channels, bypassing traditional industrial distributor markups for all-purpose formulations.
Industry Challenges
- Formulation Chemist Scarcity:Cross-functional expertise spanning polymer chemistry, regulatory compliance, and application engineering is concentrated among senior specialists nearing retirement.
- Multi-Jurisdiction Certification Timelines:Suppliers must navigate simultaneous EPA, REACH, and METI approval processes, extending product launch cycles by 18-24 months for global formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Masking Film Market |
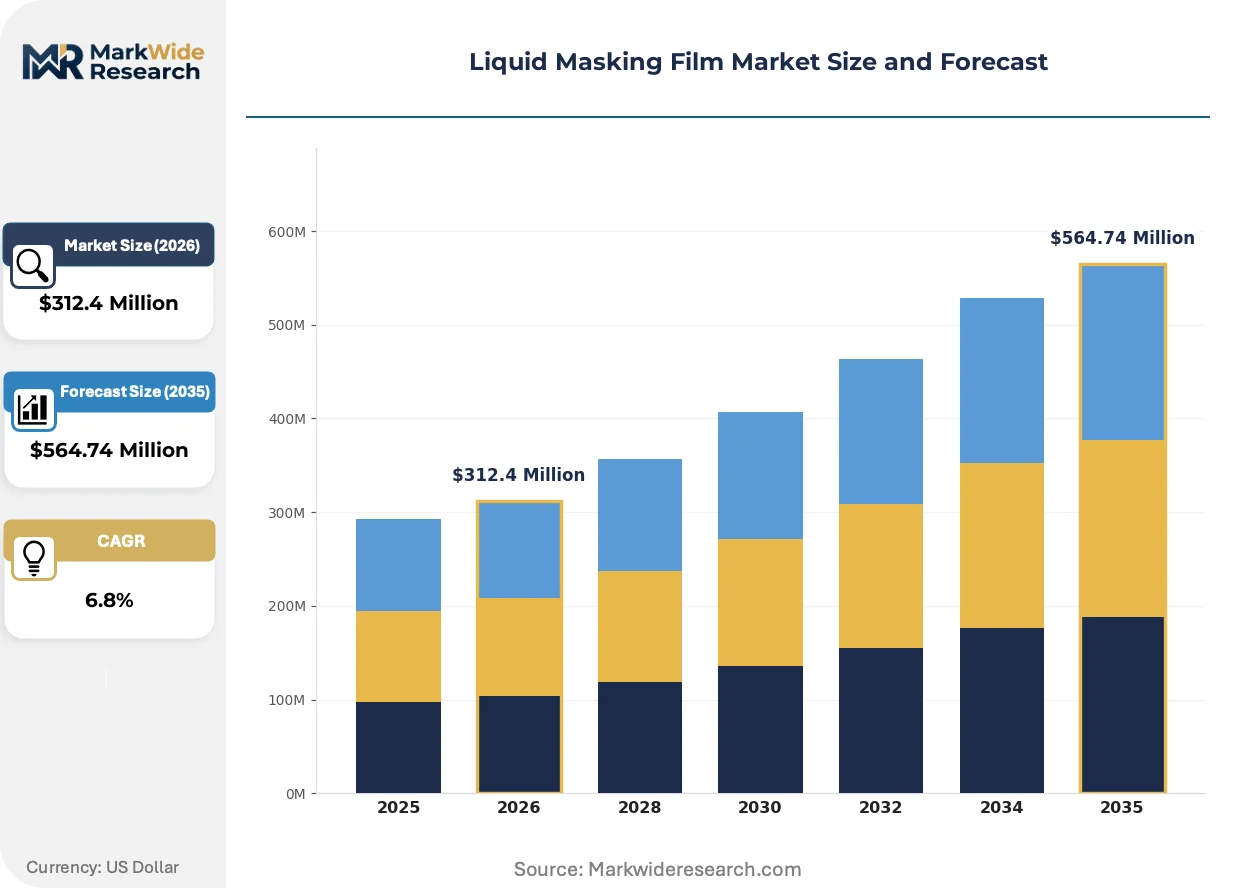
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Solvent-based, UV-cured, All-purpose End User: Automotive, Electronics, Construction, Arts & Crafts Application: Surface Protection, Paint Masking, Temporary Coating, Adhesive Shielding Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesalers |
| Companies Covered | 3M, PPG Industries, Axalta Coating Systems, Sherwin-Williams, BASF, Nippon Paint, HMG Paints Ltd., Masking Solutions Inc., SEM Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Masking Film Market Shifts & Advancements
Formulation chemistry and curing technology are diverging across end-use tiers, with electronics and automotive pulling toward instant-cure platforms while aerospace and heavy equipment retain thermal-cure precision requirements.
UV-cured liquid masking film is converging with inkjet deposition systems for selective area coating in printed circuit board manufacturing. Electronics assemblers in South Korea and Taiwan are retrofitting production lines with integrated spray-and-cure stations. This convergence is compressing masking cycle times from hours to minutes while eliminating solvent handling infrastructure.
REACH authorization requirements for specific solvent chemistries are forcing reformulation of legacy high-performance masking systems. Industrial coatings suppliers serving European aerospace OEMs must substitute restricted substances without sacrificing peel elongation or thermal stability. German and French formulators are investing in bio-based acrylic alternatives to maintain market access under evolving ECHA substance evaluations.
Maintenance procurement teams are consolidating vendor relationships and demanding technical documentation bundles for compliance auditing. Automotive refinishing chains are replacing spot-buy masking supplies with annual framework agreements specifying VOC content thresholds and peel-test certifications. This consolidation is most visible in United States multi-shop operators seeking to standardize inventory across state regulatory boundaries.
Liquid Masking Film Market Segmentation
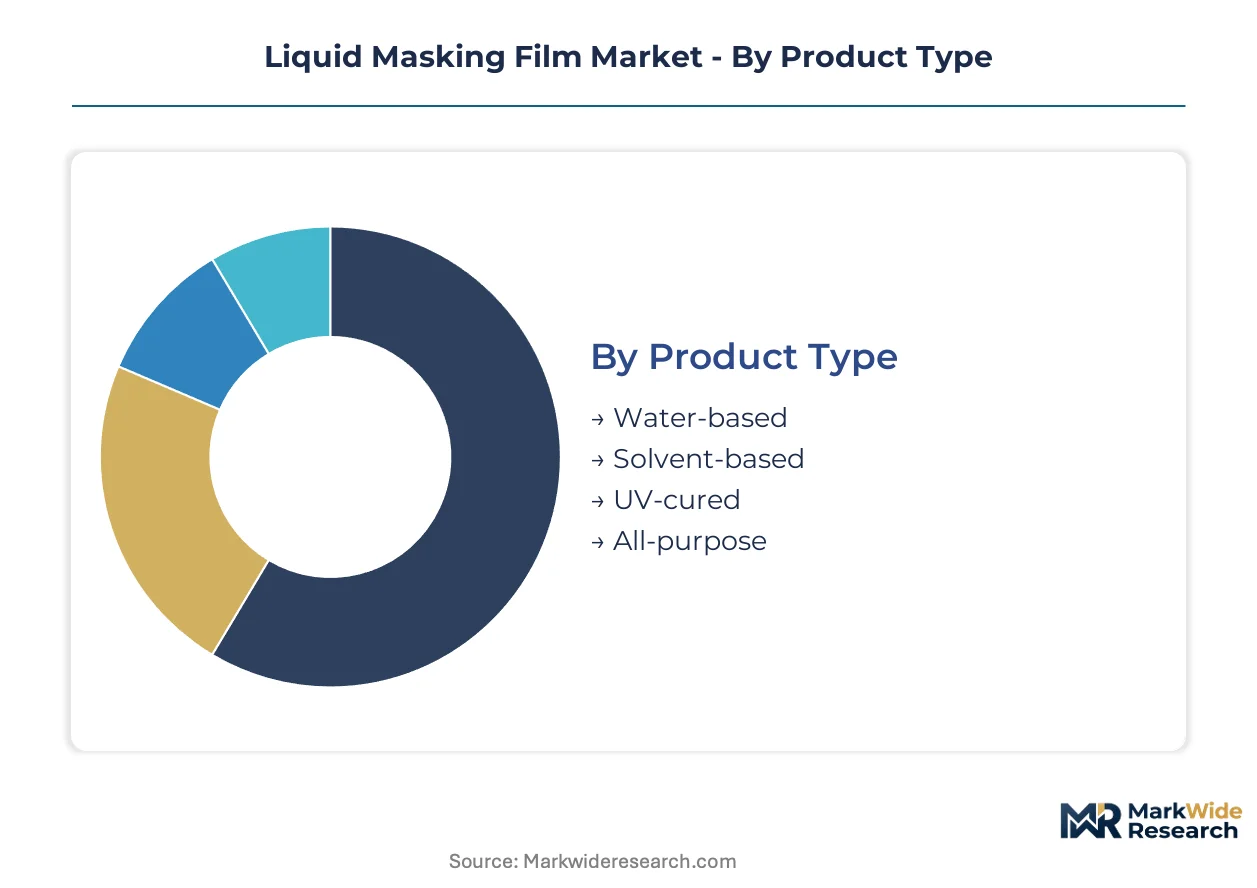
Liquid masking film segmentation reveals how formulation chemistry, end-use thermal requirements, and channel economics create distinct competitive battlegrounds. Each dimension carries divergent margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Standalone spray applications dominate volume, while UV-cured systems embed into automated production lines with captive curing infrastructure.
- Solvent-based:Acrylic and rubber polymer formulations deliver 200-400% elongation with thermal stability above 150°C. German automotive OEMs in Stuttgart and Wolfsburg specify these grades for high-temperature bake cycles where peel-cleanliness failures halt production lines. REACH authorization requirements for specific solvent chemistries force continuous reformulation without sacrificing performance benchmarks.
- UV-cured:Oligomer-based systems cure instantly under 365-405 nm LED arrays, eliminating solvent handling infrastructure. South Korean and Taiwanese electronics assemblers retrofit lines with integrated spray-and-cure stations for circuit board masking, compressing cycle times from hours to minutes.
- Water-based:Acrylic emulsion formulations meet EPA VOC phase-out deadlines for automotive refinishing shops across the United States, though chemical resistance ceilings exclude aerospace turbine applications.
- All-purpose:Hybrid polymer blends serve maintenance crews and hobbyists through hardware retail channels, prioritizing convenience over specialized performance.
Volume placements concentrate in solvent-based grades; the faster expansion belongs to UV-cured systems.
End User:
Customer scale ranges from billion-unit electronics manufacturers to fragmented individual consumers, with procurement sophistication determining pricing power.
- Automotive:OEM coating lines and refinishing shops generate the largest absolute demand, split between high-temperature bake applications and compliance-driven water-based conversions. United States multi-shop operators consolidate vendors under annual framework agreements specifying VOC thresholds.
- Electronics:Miniaturization trends in East Asian assembly plants drive precision masking requirements. Dielectric formulations for battery cell thermal management coating represent emerging testing programs among electric vehicle manufacturers.
- Construction:Temporary surface protection during infrastructure projects favors all-purpose formulations applied by generalist contractors with minimal specification oversight.
- Arts & Crafts:Individual consumers purchase through online retail channels, bypassing traditional industrial distributor markups for small-volume applications.
Revenue concentration sits with automotive; electronics climbs fastest on unit volume expansion.
Application:
Functional requirements separate precision-demanding processes from tolerance-forgiving temporary coverage.
- Paint Masking:Spray-applied films shield adjacent surfaces during automotive refinishing and industrial coating operations, where edge definition and residue-free removal determine rework costs.
- Surface Protection:Mechanical abrasion resistance during manufacturing, shipping, and installation protects high-value substrates from cosmetic damage.
- Temporary Coating:Dip or brush application for short-duration chemical exposure control in maintenance and construction settings.
- Adhesive Shielding:Selective area protection preventing unwanted bonding during assembly processes, common in electronics manufacturing.
Paint masking commands premium pricing; surface protection generates the highest unit volumes across construction and logistics applications.
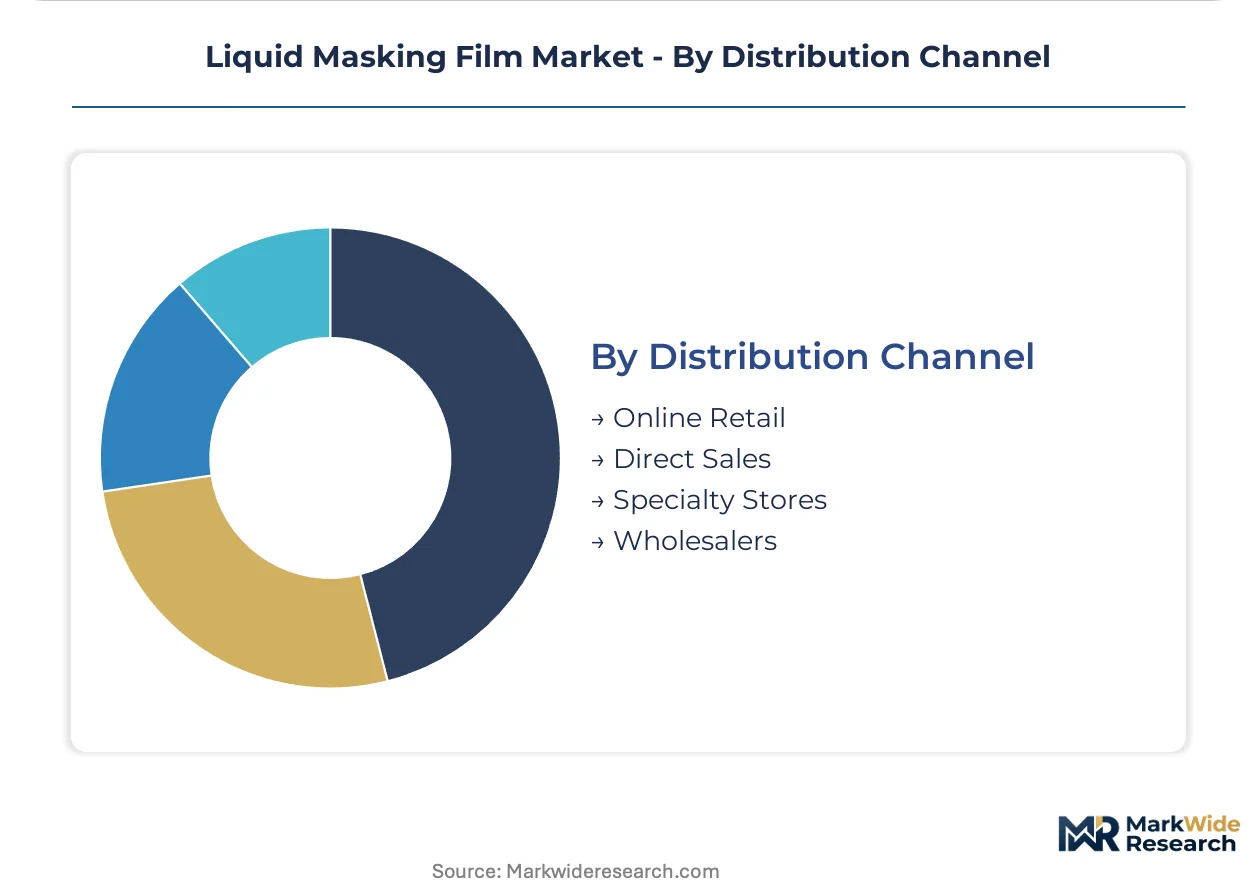
Distribution Channel:
Channel selection reflects buyer scale, specification complexity, and regulatory documentation requirements.
- Direct Sales:Automotive OEMs and aerospace manufacturers negotiate multi-year supply agreements with technical documentation bundles for compliance auditing, including peel-test certifications and VOC content attestations.
- Online Retail:Maintenance teams and arts consumers shift toward direct-to-consumer platforms, fragmenting purchase patterns and compressing available margin for intermediaries.
- Specialty Stores:Regional industrial distributors serve mid-tier automotive refinishing shops with inventory stocking programs and application technical support.
- Wholesalers:Bulk volume aggregation for construction sector procurement, where price sensitivity outweighs formulation specification precision.
Direct sales capture the highest margin transactions; online retail expands most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global solvent-based liquid masking film demand through its dense automotive OEM coating infrastructure. Wolfsburg, Munich, and Ingolstadt form a contiguous industrial corridor where high-temperature bake cycles sustain premium-grade formulation requirements. This German concentration shapes supplier investment patterns across three continents.
United States
Automotive refinishing chains in California, Texas, and the Southeast are consolidating vendors under annual framework agreements. EPA VOC phase-out deadlines are accelerating water-based film conversions in collision repair networks. Detroit's OEM coating lines maintain solvent-based specifications for powertrain and chassis applications above 150°C.
Germany
Stuttgart and Wolfsburg sustain Europe's densest concentration of high-temperature bake-cycle demand. REACH authorization requirements for specific solvent chemistries force continuous reformulation without sacrificing peel-cleanliness benchmarks. BASF leverages its Ludwigshafen resin intermediates position to serve industrial coatings channels across Baden-Württemberg and Lower Saxony.
China
Shanghai and Guangdong electronics assemblers are retrofitting lines with UV-cured masking systems for circuit board production. GB coating limits and dual carbon goals are tightening formulation standards for domestic automotive refinishing. Ningbo and Suzhou industrial zones concentrate dielectric masking film testing for battery cell thermal management applications.
Japan
Nagoya and Osaka electronics manufacturers drive precision masking demand for miniaturized component assembly. METI industrial chemical standards add compliance layers for multinational suppliers serving cross-border automotive supply chains. Yokohama coating equipment specialists are integrating spray-and-cure stations for instant-cure film deposition.
South Korea
Suwon and Seoul semiconductor packaging facilities are scaling UV-cured masking for high-density interconnect substrates. MFDS chemical safety assessments overlap with automotive OEM specifications for battery enclosure coatings. Busan industrial distributors are consolidating inventory positions for maintenance-grade all-purpose formulations.
Liquid Masking Film Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation chemistry and application engineering. The supplier base stratifies into three tiers: integrated chemical conglomerates controlling resin intermediates, specialized coatings formulators serving single end-use verticals, and regional distributors private-labeling commodity grades. Consolidation pressure concentrates among mid-scale European formulators facing simultaneous REACH compliance costs and feedstock volatility. Dominant competitive moves include backward integration into acrylic oligomer production and geographic expansion through distributor acquisition in Asian electronics corridors.
Within the integrated chemical tier, BASF and PPG Industries exemplify archetypes of resin-captive formulation leadership. BASF extends its solvent-based portfolio across European industrial coatings channels where ECHA substance evaluations create technical barriers. PPG leverages automotive OEM relationships to sustain specification control in high-performance segments. Axalta Coating Systems anchors a middle position through captive supply positions in UV-curable resin systems. Among specialized formulators, 3M represents the diversified technology conglomerate archetype with cross-industry masking applications.
| Leading Market Players |
|---|
| 3M |
| PPG Industries |
| Axalta Coating Systems |
| Sherwin-Williams |
| BASF |
| Nippon Paint |
| HMG Paints Ltd. |
| Masking Solutions Inc. |
| SEM Products, Inc. |
| Others |
Supply & Pricing Matrix
Backward integration into acrylic oligomer production anchors supplier pricing power across UV-cured and solvent-based formulation tiers. PPG Industries and BASF leverage captive resin positions to defend margin structures against commodity-grade competitors serving automotive refinishing shops under EPA VOC compliance pressure.
Pricing Analysis
Yield-based pricing anchors premium-grade solvent-based films serving German automotive OEM bake cycles above 150°C, where peel-cleanliness failures halt production lines. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant formulations from water-based alternatives and all-purpose hardware grades. Cost compression in water-based tiers is intensifying because acrylic emulsion feedstock costs fluctuate with crude oil derivatives. Automotive refinishing chains exhibit highest price sensitivity through consolidated annual framework agreements, while aerospace turbine applications show lowest sensitivity due to specification-locked supply relationships.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Wolfsburg automotive clusters, while specialty distributors serve mid-tier refinishing shops with technical support. Acrylic and rubber polymer production concentrates in Germany, the United States, and Japan, with UV-curable oligomer synthesis anchored in European and Japanese chemical corridors. Formulation chemistry draws from petrochemical derivatives, specialty resin intermediates, and LED curing equipment. Single-source vulnerability concentrates in oligomer supply for UV-cured systems. Distribution runs through direct sales for compliance-intensive aerospace accounts, online retail for maintenance crews, and regional wholesalers for construction sector volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization requirements and EPA VOC phase-out deadlines erect compliance moats that favor incumbents with established regulatory affairs infrastructure and reformulation R&D capacity.
For Market Incumbents: Lock in specification control at German automotive OEMs through continuous reformulation investment that maintains peel-elongation benchmarks under evolving ECHA substance evaluations. Deepen captive supply positions in UV-curable resin systems to offset feedstock volatility in acrylic polymer markets. Emerging Asian electronics assemblers pose substitution threats through integrated spray-and-cure station deployments that bypass traditional film formulations. For New Entrants and Emerging Players: Capture battery cell thermal management coating programs at Ningbo and Suzhou industrial zones where dielectric masking film testing remains underpenetrated by established suppliers. Target India's PLI-scheme automotive manufacturing corridors where coating line infrastructure expansion outpaces masking film supplier presence. Lead with water-based formulation expertise to serve United States refinishing chains facing EPA compliance deadlines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking UV-curable technology positions or automotive OEM channel access. Five-to-ten-year viability favors suppliers with dual water-based and solvent-based formulation capabilities spanning regulatory jurisdictions. Watch for inflection signals in battery enclosure coating specifications at electric vehicle manufacturers testing dielectric masking alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oligomer Production | Captive resin supply insulates Axalta and BASF from European-Japanese supplier bottlenecks. |
| REACH-Compliant Reformulation Program | Bio-based acrylic alternatives preserve German aerospace OEM market access under ECHA evaluations. |
| UV-Cure Line Retrofit Partnership | South Korean electronics assemblers compress masking cycle times through integrated spray-and-cure stations. |
| Direct-to-Consumer Platform Launch | Online hardware retail bypasses distributor markups for maintenance and arts market volume. |
| India Distribution Network Acquisition | PLI-scheme automotive expansion creates coating line infrastructure demand ahead of Western supplier presence. |
Research Methodology
Document review covered EPA regulatory filings, ECHA substance authorization databases, and automotive OEM technical specifications, complemented by interviews with formulation chemists, industrial coatings procurement managers, and specialty chemical distribution executives. Secondary validation drew from customs trade data, SEC 10-K disclosures, and industry association reports. Bottom-up segment sizing triangulated against top-down market estimates derived from production capacity and end-use demand modeling.
Historical volume trajectories cross-referenced against expert panel inputs from plant managers and technical R&D directors shaped the analytical framework. Segmentation dimensions modeled include formulation chemistry, end-use thermal requirements, and distribution channel economics across the projection horizon. CAGRs were derived from regression analysis of correlated industrial coatings demand indicators and regulatory compliance timelines. Forecast inputs incorporated bake-cycle temperature specifications and peel-test certification requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction expansions and petrochemical feedstock volatility. Forecasts reflect assumptions about regulatory phase-out schedules and OEM specification stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
USA Barrier Coated Paper Market