
 USA Stretch Hood Films Market | 2026-2036
USA Stretch Hood Films Market Size, Share, and Industry Trends Forecast 2026-2036
USA Stretch Hood Films Market Analytics
Skilled polymer compounding expertise is reorganizing competitive dynamics as converters face acute shortages of technicians fluent in multilayer coextrusion controls. Berry Global leverages captive resin relationships and vertical integration to secure supply continuity across volatile feedstock cycles. Sigma Plastics Group sustains cost leadership through high-volume blown film operations concentrated in the Ohio River Valley. Novolex Holdings differentiates via food-contact certification depth that satisfies major CPG audit protocols.
Stretch hood films are elastic polyethylene-based sleeves, typically 80–150 microns thick, that deploy mechanical memory to grip palletized loads without heat application, replacing shrink wrap in high-throughput distribution environments. LLDPE formulations dominate film type segmentation due to puncture resistance and load containment balance, while HDPE grades gain traction in beverage packaging for stiffness at reduced gauge. Application segmentation tilts toward industrial packaging where automated palletizing lines demand consistent cling and release coefficients, with food packaging representing the fastest margin pool as shelf-life extension requirements tighten.
EPA regulations on plastic waste generation and OSHA workplace exposure standards for resin dust shape product design and facility investment decisions across domestic manufacturing. FDA food-contact substance notifications govern migration limits for palletized food and pharmaceutical shipments, filtering supplier qualification at major end users. Stakeholders must monitor state-level extended producer responsibility legislation advancing in California and New York for preemptive compliance architecture.
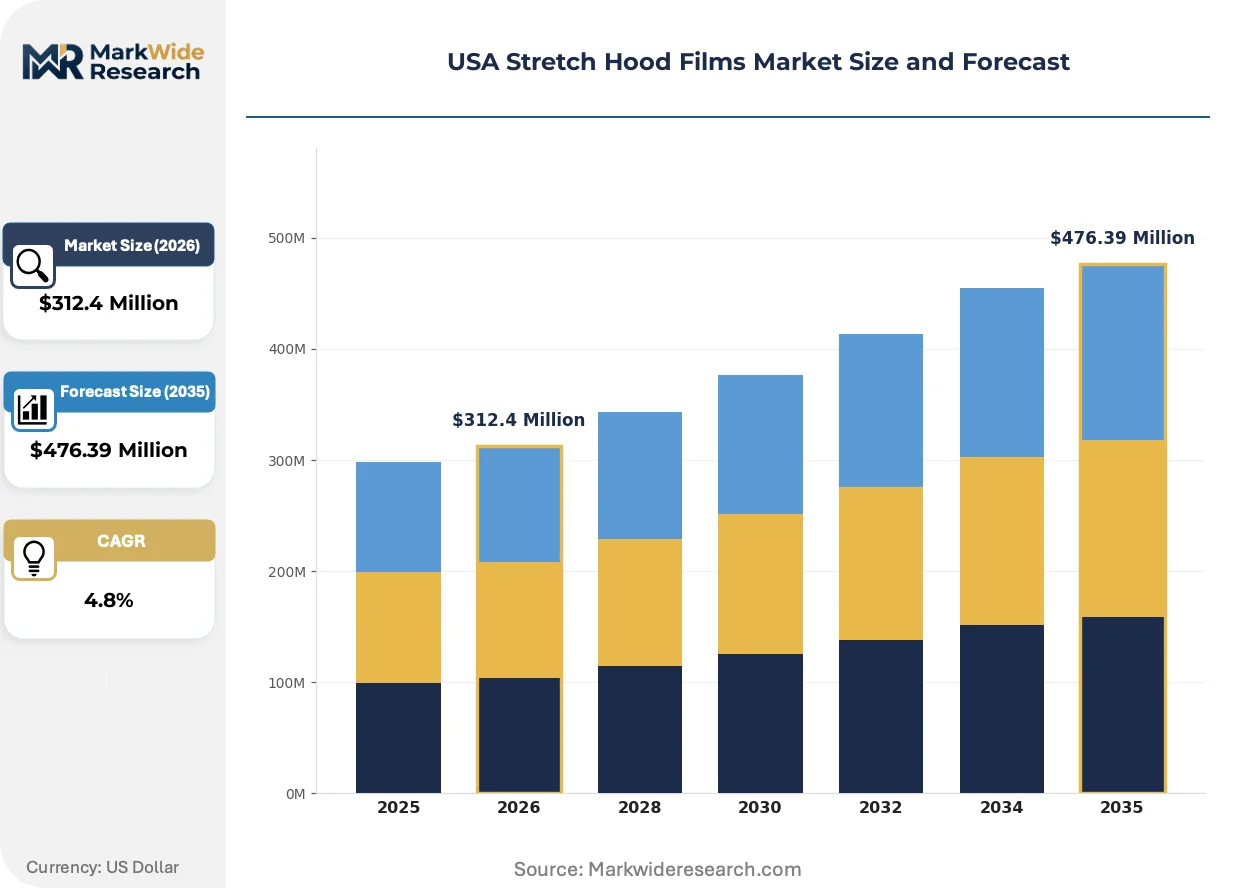
Market Dynamics
Polymer feedstock volatility is compressing converter margins while forcing rapid qualification of post-consumer resin streams across the Midwest manufacturing belt.
Growth Catalysts
- OSHA workplace exposure standards:Automated stretch hood systems reduce manual handling injuries in high-volume distribution centers, accelerating capital deployment in the Ohio River Valley logistics corridor.
- Food packaging shelf-life extension:Modified atmosphere compatibility of multilayer LLDPE formulations satisfies FDA migration limits for palletized produce shipments.
- Midwest manufacturing belt concentration:Chicago-Detroit freight density creates scale economies for film converters serving just-in-time automotive component supply chains.
Market Restraints
- Ethylene feedstock volatility:Gulf Coast petrochemical supply disruptions transmit directly to blown film resin costs, eroding fixed-price contract profitability.
- Multilayer coextrusion technician scarcity:The Great Lakes region lacks sufficient polymer compounding programs to replenish retiring skilled operators.
- Mechanical pallet strapping substitution:Heavy-load beverage and building materials sectors revert to polypropylene banding when film gauge reduction compromises load containment.
Strategic Opportunities
- California extended producer responsibility mandates:State-level post-consumer content requirements create first-mover advantage for converters with qualified PCR supply chains.
- Pharmaceutical cold-chain palletization:Temperature-stable HDPE hood grades penetrate vaccine distribution networks requiring validated thermal protection.
- Industrial IoT integration:RFID-embedded stretch hoods enable real-time load tracking for automotive Tier 1 suppliers operating cross-dock facilities.
Industry Challenges
- FDA food-contact substance notification timelines:New resin additive approvals delay product launches by 18-24 months, freezing formulation innovation pipelines.
- Legacy blown film asset retrofit costs:Post-consumer resin processing requires screw and die modifications that strand capital in depreciated equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Stretch Hood Films Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: LDPE, LLDPE, HDPE, Others Application: Food Packaging, Industrial Packaging, Retail Packaging, Beverage Packaging End User: Food & Beverage, Consumer Goods, Pharmaceuticals, Electronics Distribution Channel: Direct Sales, Online Sales, Retail Stores, Distributors |
| Companies Covered | Sigma Plastics Group, Berry Global, Novolex Holdings, RKW Group, Tex-Trude, INDEVCO Plastics, Paragon Films, Intertape Polymer Group, Megaplast USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Stretch Hood Films Market Evolving Landscape
Material science advances and regulatory pressure on plastic waste are converging to redefine film architecture and converter competitive positioning across domestic supply chains.
Metallocene-catalyzed LLDPE resins are decomposing the traditional trade-off between puncture resistance and clarity in high-performance stretch hood applications. Beverage bottlers in the Great Lakes region are adopting these grades at accelerating rates for retail-ready pallet presentation. The technology is decomposing incumbent Ziegler-Natta resin market share while enabling downgauging without load containment sacrifice.
EPA sustainable packaging guidelines are pressuring converters to document recycled content percentages and end-of-life pathways. The industrial packaging segment faces the steepest compliance burden as major CPG audit protocols incorporate Scope 3 emissions disclosure. Midwest converters are responding by securing mass-balance certifications and investing in optical sorting infrastructure for PCR stream purification.
CPG procurement teams are consolidating stretch hood suppliers to reduce qualification overhead and secure volume-based resin indexing. Direct converter relationships are displacing distributor intermediaries in the food packaging segment. This concentration is most visible in the Chicago metropolitan area, where multinational food manufacturers have reduced qualified supplier pools from twelve to four primary partners.
USA Stretch Hood Films Market Segmentation
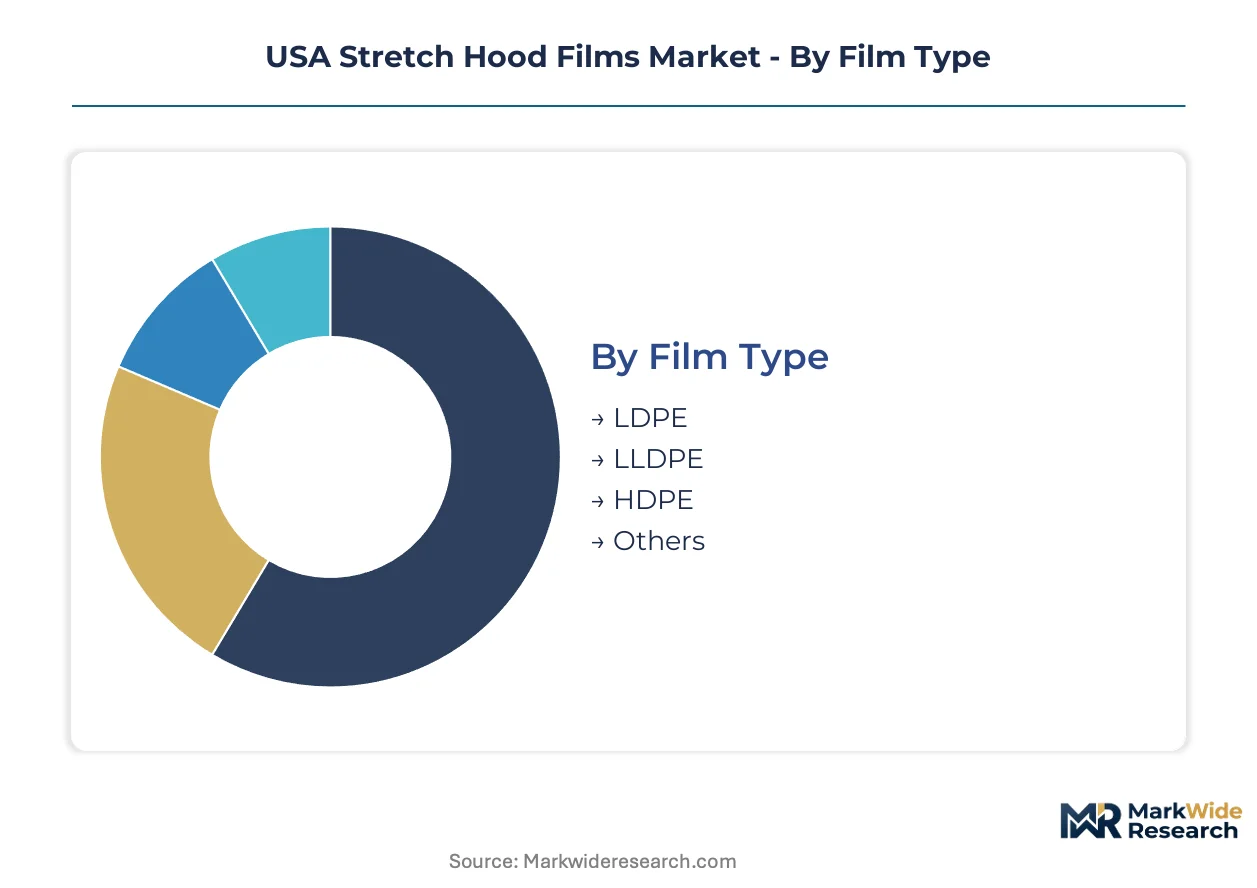
Segmentation in stretch hood films reveals how resin chemistry, application requirements, and channel economics intersect to determine converter profitability. Understanding these splits exposes where specification premiums justify formulation investment versus where commoditization pressures dominate.
Film Type:
Channel mix varies sharply by resin grade, with LLDPE and HDPE flowing predominantly through direct converter relationships while LDPE and specialty grades move more heavily through distributor networks serving smaller volume accounts.
- LLDPE:Linear low-density polyethylene formulations deliver optimal puncture resistance and load containment balance through metallocene-catalyzed molecular architecture. Demand concentrates in the Chicago-Detroit automotive corridor where just-in-time palletizing lines require consistent cling coefficients across temperature swings. FDA food-contact certifications for these grades command specification premiums at major CPG audit protocols.
- HDPE:High-density polyethylene grades provide stiffness at reduced gauge, enabling downgauging without sacrificing pallet integrity in beverage stacking applications. Ohio River Valley converters supply Great Lakes bottlers seeking retail-ready pallet presentation with optical clarity. Cold-chain pharmaceutical networks are adopting temperature-stable HDPE hoods for validated thermal protection in vaccine distribution.
- LDPE:Low-density polyethylene serves cost-sensitive industrial applications where load containment demands are moderate and gauge flexibility matters more than puncture resistance.
- Others:Specialty copolymers and bio-based alternatives occupy niche positions where EPR compliance mandates or brand sustainability commitments override resin cost considerations.
LLDPE dominates installed base. HDPE is where expansion concentrates.
Application:
Margin structure inverts across these segments, with industrial packaging trading volume for thin margins while food and beverage applications capture specification premiums through audit-intensive qualification requirements.
- Industrial Packaging:Automated palletizing lines in Midwest manufacturing facilities demand consistent release coefficients to prevent film tailing at high speeds. Automotive Tier 1 suppliers operating cross-dock facilities specify RFID-embedded hoods for real-time load tracking. OSHA workplace exposure standards favor automated stretch hood deployment over manual shrink wrapping in high-volume distribution centers.
- Food Packaging:Modified atmosphere compatibility of multilayer LLDPE formulations satisfies FDA migration limits for palletized produce shipments. Shelf-life extension requirements are tightening qualification standards at multinational food manufacturers. Direct converter relationships are displacing distributor intermediaries as CPG procurement teams consolidate supplier pools.
- Beverage Packaging:Great Lakes bottlers are adopting metallocene-catalyzed grades for retail-ready pallet presentation, decomposing incumbent Ziegler-Natta resin market share.
- Retail Packaging:Point-of-sale visibility requirements drive clarity specifications that trade off against downgauging economics in big-box retail distribution.
Industrial packaging anchors volume throughput. Food packaging is climbing the fastest.
End User:
Customer scale and qualification intensity determine whether accounts flow through direct sales teams or distributor intermediaries, with pharmaceutical and electronics buyers demanding dedicated technical service relationships.
- Food & Beverage:Pallet stability requirements intensify as distribution networks extend shelf-life expectations. Major manufacturers have reduced qualified supplier pools from twelve to four primary partners in the Chicago metropolitan area.
- Consumer Goods:Scope 3 emissions disclosure in CPG audit protocols drives recycled content verification requirements that strain distributor-based supply chains.
- Pharmaceuticals:Temperature-stable HDPE hood grades penetrate vaccine distribution networks requiring validated thermal protection and FDA food-contact substance notification compliance.
- Electronics:Static-dissipative formulations serve semiconductor and component manufacturers with cleanroom-compatible palletization requirements.
Food and beverage commands the largest addressable base. Pharmaceuticals shows the steepest expansion trajectory.
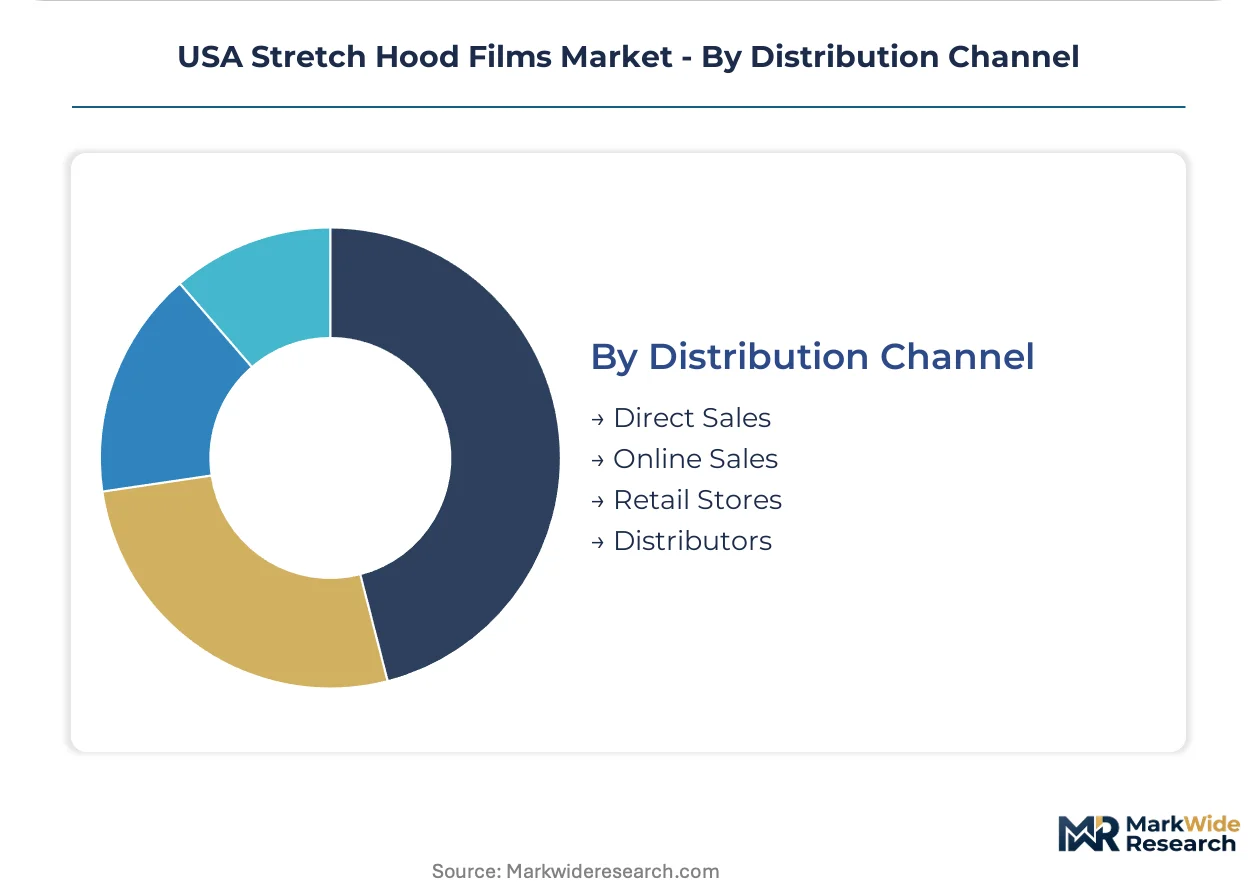
Distribution Channel:
Channel selection reflects order fragmentation and technical service intensity, with direct sales capturing consolidated CPG accounts while distributors serve geographic dispersion and smaller volume requirements.
- Direct Sales:Volume-based resin indexing and qualification overhead reduction drive consolidation toward direct converter relationships. Multinational food manufacturers in the Chicago-Detroit corridor have concentrated purchasing through four primary partners.
- Distributors:Geographic coverage and working capital provision serve smaller Midwest manufacturers lacking procurement scale for direct mill relationships.
- Online Sales:Digital procurement platforms gain traction for standardized industrial grades where technical consultation requirements are minimal.
- Retail Stores:Limited to emergency replenishment and small-lot specialty applications with minimal market presence.
Direct sales captures the highest-value accounts. Distributor relationships are gaining share fastest among mid-tier manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace exposure standards and EPA sustainable packaging guidelines anchor demand concentration across the Midwest manufacturing belt. The Chicago-Detroit logistics corridor generates scale economies for film converters serving automated palletizing lines. State-level extended producer responsibility legislation in California and New York is reshaping compliance architecture for post-consumer resin integration.
Midwest Manufacturing Belt
Automotive Tier 1 suppliers operating cross-dock facilities specify RFID-embedded stretch hoods for real-time load tracking. OSHA regulations favor automated deployment over manual shrink wrapping in high-volume distribution centers. The Ohio River Valley hosts blown film operations concentrated around Cincinnati and Louisville serving just-in-time component supply chains.
California
Extended producer responsibility mandates create first-mover advantage for converters with qualified PCR supply chains. The state's Department of Resources Recycling and Recovery enforces post-consumer content requirements that filter supplier qualification. Central Valley food processors drive modified atmosphere compatibility specifications for palletized produce shipments.
Texas Gulf Coast
Ethylene feedstock proximity attracts resin producers and converters seeking supply continuity across volatile cycles. EPA regulations on plastic waste generation shape facility investment decisions for Gulf Coast petrochemical integration. Houston-area logistics hubs serve beverage distribution networks adopting metallocene-catalyzed grades.
Southeast Automotive Corridor
BMW, Mercedes-Benz, and Volkswagen assembly plants in South Carolina and Alabama generate demand for pallet stability in component inbound logistics. OSHA workplace exposure standards accelerate capital deployment in automated stretch hood systems. Atlanta distribution centers anchor freight density for converters serving southeastern CPG networks.
New York Metro
State-level extended producer responsibility legislation advances preemptive compliance architecture for pharmaceutical cold-chain palletization. FDA food-contact substance notifications govern migration limits for palletized shipments through Port of New York and New Jersey. Northern New Jersey warehouses concentrate demand for temperature-stable HDPE hood grades in vaccine distribution.
USA Stretch Hood Films Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on formulation flexibility and regional service density. The upper tier secures captive resin relationships to buffer feedstock volatility, while mid-cap specialists concentrate on food-contact certification depth and audit protocol compliance. Three archetypes dominate: vertically integrated resin-to-film producers, high-volume blown film operators, and certification-focused food-contact specialists. Competitive moves concentrate on securing mass-balance certifications for post-consumer resin streams and consolidating supplier relationships with multinational CPG procurement teams.
Among domestic integrated producers, Berry Global exemplifies the resin-captive archetype through upstream control over feedstock supply. Sigma Plastics Group occupies a position within the high-volume tier concentrated in the Ohio River Valley. Novolex Holdings represents the certification-focused specialist model, anchoring food-contact depth that satisfies major CPG audit protocols.
| Leading Market Players |
|---|
| Sigma Plastics Group |
| Berry Global |
| Novolex Holdings |
| RKW Group |
| Tex-Trude |
| INDEVCO Plastics |
| Paragon Films |
| Intertape Polymer Group |
| Megaplast USA |
| Others |
Value Network & Pricing Analysis
FDA food-contact substance notification requirements gate both supplier qualification and price differentiation simultaneously, creating a bifurcated market where certified converters command specification premiums while uncertified competitors compete on resin cost indexing alone.
Pricing Analysis
Midwest converters serving the Chicago-Detroit corridor price at a 15-20% premium to Ohio River Valley peers due to freight density advantages and just-in-time service capabilities. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified multilayer grades from industrial commodity formulations and downgauged beverage specifications. Cost compression in standard industrial tiers is intensifying because CPG procurement teams consolidate supplier pools and demand volume-based resin indexing. Small Midwest manufacturers lacking direct mill relationships exhibit the highest price sensitivity, while pharmaceutical cold-chain buyers prioritize thermal validation over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive and food packaging segments, while strategic resin stockpiling persists among Gulf Coast-integrated converters buffering ethylene feedstock volatility. Domestic supply concentrates in Texas, Louisiana, and the Ohio River Valley, with critical LLDPE and HDPE resin streams drawing from Gulf Coast petrochemical complexes. Raw material dependencies center on ethylene monomer, metallocene catalysts, and post-consumer resin feedstocks. Single-source vulnerability runs through specialized multilayer coextrusion equipment suppliers concentrated in Germany and Italy. Distribution runs through direct converter relationships for consolidated CPG accounts and regional distributor networks serving fragmented industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where FDA certification entrenchment and CPG audit protocol switching costs protect incumbent positioning against commodity resin competitors.
For Market Incumbents: Compound defensive positioning through captive PCR supply chain investments and optical sorting infrastructure that satisfies California extended producer responsibility mandates ahead of compliance deadlines. Secure mass-balance certifications now to preempt competitor qualification of post-consumer resin streams. Threats from mechanical pallet strapping substitution in heavy-load beverage applications demand formulation innovation in downgauged HDPE grades that maintain load containment. For New Entrants and Emerging Players: Technical service gaps in pharmaceutical cold-chain palletization present the most penetrable white space, where incumbent converters under-invest in temperature validation protocols and FDA notification support. Target regional food processors in the Central Valley and upstate New York lacking direct converter relationships with multinational suppliers. Go-to-market leverage rests on optical clarity specifications for retail-ready beverage presentation combined with rapid FDA food-contact certification turnaround. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed blown film operators in the Ohio River Valley possessing high-volume capacity but lacking food-contact certification depth for CPG audit compliance. Long-term viability favors converters with backward integration into resin supply or forward integration into automated stretch hood system deployment. The signal to watch is state-level extended producer responsibility legislation adoption rates, which will accelerate PCR qualification timelines and strand non-compliant capacity.| Strategic Initiative | Industry Significance |
|---|---|
| PCR Supply Chain Qualification | Mass-balance certification secures California and New York market access ahead of EPR enforcement. |
| Multilayer Coextrusion Capacity Expansion | Metallocene-catalyzed LLDPE lines capture beverage bottler demand for retail-ready optical clarity. |
| Automated System Integration Partnership | OSHA compliance positioning captures Midwest distribution center capital deployment cycles. |
| Pharmaceutical Cold-Chain Certification | FDA thermal validation protocols penetrate vaccine distribution networks requiring documented protection. |
| RFID-Embedded Film Development | Industrial IoT integration serves automotive Tier 1 suppliers operating real-time cross-dock tracking. |
Research Methodology
Desk research of trade association filings, customs records, and EPA regulatory dockets preceded structured interviews with blown film plant managers, CPG procurement directors, polymer compounding technicians, and automotive Tier 1 supply chain executives. Primary fieldwork combined with secondary validation from SEC filings, American Chemistry Council reports, and state-level extended producer responsibility legislative tracking. Bottom-up capacity estimates triangulated against top-down demand modeling across resin grade, application segment, and regional manufacturing cluster dimensions.
Variance decomposition across the projection horizon isolates feedstock price volatility, regulatory compliance timeline shifts, and substitution elasticity as primary forecast drivers. Segmentation modeling incorporates film type chemistry, end-use industry requirements, distribution channel economics, and geographic freight density patterns. CAGRs derive from installed base growth rates, replacement demand cycles, and penetration assumptions for emerging applications including pharmaceutical cold-chain and RFID-embedded industrial formats. Ethylene feedstock cost curves and PCR stream availability constraints inform supply-side boundary conditions.
Underlying assumptions cover stable OSHA enforcement intensity and incremental EPR adoption across coastal states, with deviation risk concentrated in Gulf Coast petrochemical supply disruptions and multilayer coextrusion technician shortage severity. Forecasts reflect these assumptions with explicit sensitivity bands around resin cost pass-through rates and CPG supplier consolidation velocity. Revision becomes warranted when FDA food-contact notification timelines extend beyond historical 18-24 month baselines or when mechanical strapping substitution rates in beverage applications exceed modeled thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Barrier Foil Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Global Medical Packaging Films Market