
 Active and Modified Atmosphere Packaging Market | 2026-2036
Active and Modified Atmosphere Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Active and Modified Atmosphere Packaging Market Outlook
Foodservice distribution channels is tilting toward case-ready meat formats that extend retail shelf life without preservatives. Amcor leverages multi-layer coextrusion capabilities to dominate high-barrier tray supply for protein processors. Sealed Air Corporation sustains R&D intensity in vacuum skin packaging systems that reduce purge and improve case presentation. Mondi Group anchors European flexible MAP volumes through integrated kraft paper and plastic film operations.
Active and modified atmosphere packaging encloses perishable products in gas-flushed environments where oxygen, carbon dioxide, and nitrogen ratios are precisely controlled to retard microbial growth and enzymatic degradation, typically achieving residual oxygen levels below 1% in high-barrier structures. Flexible packaging leads material demand due to its lightweight profile and compatibility with form-fill-seal automation, while rigid trays capture premium margin pools in case-ready meat applications where structural integrity and retail visibility command higher unit economics. The fresh produce application segment shows accelerated technical development as breathable films with laser-perforated microholes balance respiration rates for climacteric fruits.
The FDA regulates MAP systems under food contact substance notifications that validate migration limits and gas safety for oxygen scavengers and emitters, while the EU Green Deal's packaging and packaging waste regulation tightens recyclability quotas that reshape substrate selection across export-oriented suppliers. ISO 22000 food safety management frameworks govern hazard control in modified atmosphere operations from gas blending through final seal integrity testing. Stakeholders must monitor evolving extended producer responsibility schemes that transfer end-of-life collection costs upstream to packaging converters and brand owners.
Market Dynamics
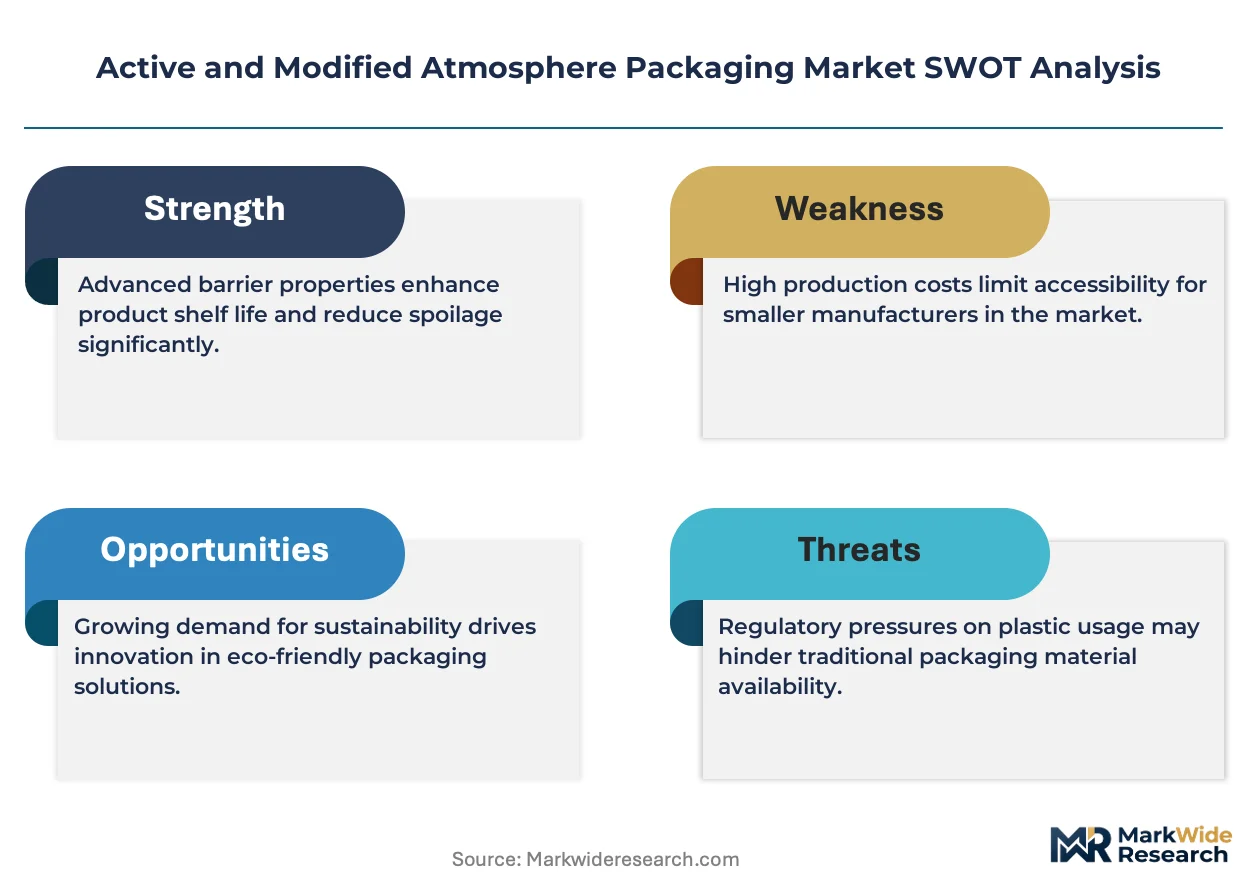
EU Green Deal packaging waste directives are forcing substrate transitions across the supply base, converting multi-layer barrier films into recyclable mono-material structures while preserving oxygen transmission rates below 1 cc/m²/day.
Growth Catalysts
- Breathable film micro-perforation:Laser-drilled films with 50-200 micron holes balance respiration rates for climacteric fruits, extending berry shelf life from 5 to 12 days in refrigerated distribution.
- German retail concentration:Centralized procurement by discounter chains creates volume pull for high-barrier tray contracts, consolidating specification power with three national retailers.
- EU Green Deal recyclability mandates:Packaging and Packaging Waste Regulation quotas accelerate mono-PE and mono-PP substrate adoption, eliminating non-recyclable multi-layer structures from export-oriented production.
Market Restraints
- Ethylene-vinyl alcohol resin concentration:Asian petrochemical suppliers control 70% of global EVOH capacity, exposing European converters to feedstock volatility and ocean freight cost spikes.
- High-barrier mono-material technical ceiling:Current polyethylene formulations cannot match EVOH oxygen barrier performance below 5 cc/m²/day, limiting full substitution in ultra-low oxygen applications.
- Extended producer responsibility cost transfer:Germany's VerpackG and France's Citeo schemes impose end-of-life collection fees on converters, compressing margins on standard barrier film grades.
Strategic Opportunities
- India cold chain infrastructure buildout:FSSAI mandated temperature-controlled distribution for dairy and meat creates first-mover positioning for MAP equipment suppliers in Mumbai and Delhi NCR processing clusters.
- Carbon-based oxygen scavenger integration:Iron-free scavenger systems enable microwaveable packaging formats, opening ready-meal segments previously blocked by metal detector interference.
- Direct-to-consumer protein subscription channels:E-commerce meat delivery services in London and Paris require case-ready formats with 21-day shelf life, bypassing traditional retail distribution markups.
Industry Challenges
- Gas blending technician scarcity:Certified operators for nitrogen-carbon dioxide-oxygen mixture calibration remain concentrated in Netherlands and Italy, creating recruitment bottlenecks for Eastern European plant expansions.
- ISO 22000 audit timeline compression:Third-party certification bodies in Germany report 14-week backlogs for modified atmosphere operation validation, delaying new product launches.
- Legacy form-fill-seal retrofit complexity:Converting 1990s-era equipment for mono-material sealing temperatures requires mechanical rebuilds exceeding €180,000 per line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active and Modified Atmosphere Packaging Market |
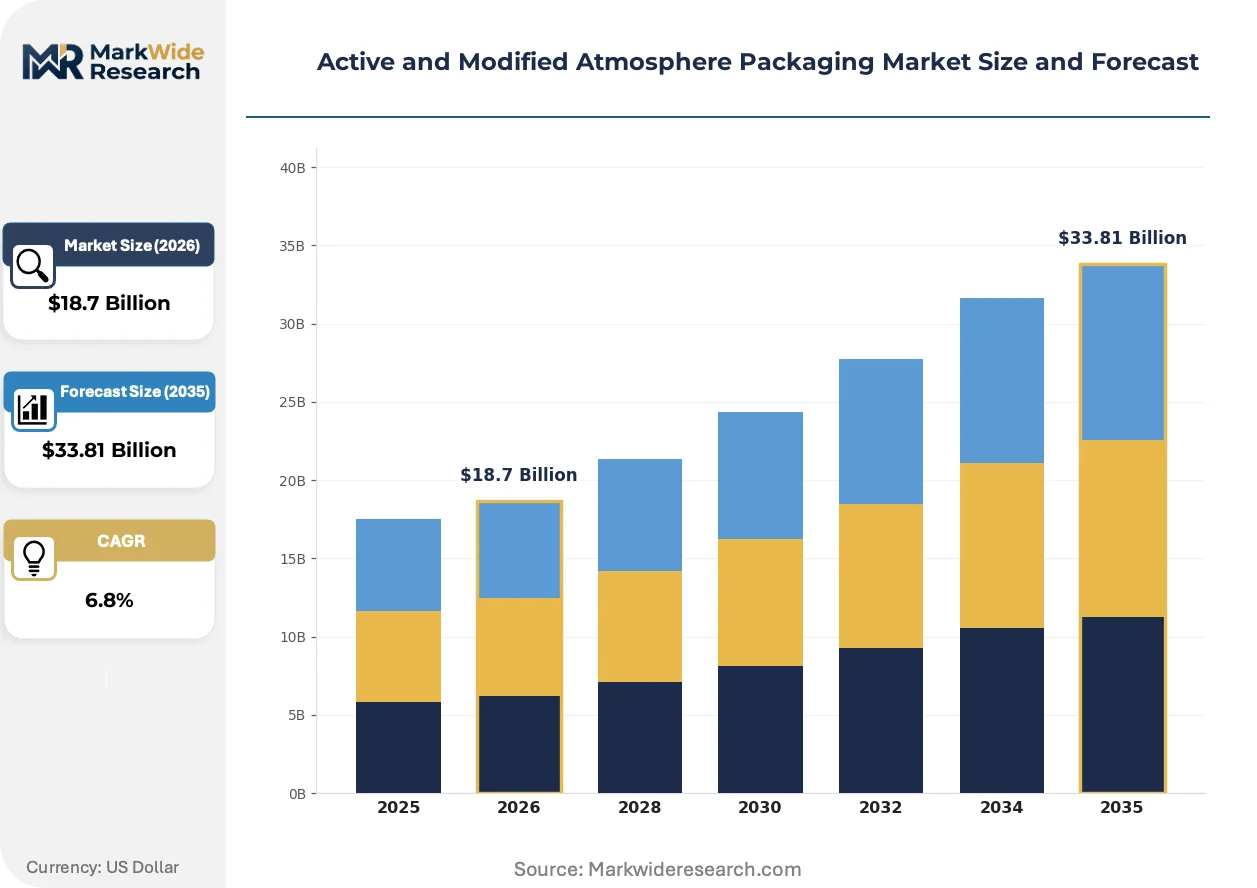
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Semi-Rigid Packaging, Bags Material: Plastic, Metal, Paper, Composites End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Application: Fresh Produce, Dairy Products, Meat & Poultry, Snacks |
| Companies Covered | Berry Global, Linde AG, Amcor, Klöckner Pentaplast, Air Products and Chemicals Inc., Sealed Air Corporation, Winpak Ltd., ProAmpac, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active and Modified Atmosphere Packaging Market Strategic Shifts
Active packaging chemistry and digital traceability systems are converging to create intelligent barrier solutions that communicate shelf-life status directly to retail scanners and consumer smartphones.
Water-based oxygen scavenger coatings are collapsing the cost structure of active packaging integration. Food processors in Spain and Portugal are adopting these coatings at twice the 2022 rate, eliminating the need for separate sachet insertion and reducing line complexity by 40%.
EU F-Gas Regulation phase-down schedules are accelerating CO₂ recovery system investments at gas blending facilities. Industrial gas suppliers in Belgium and the Netherlands are retrofitting beverage-grade recovery units for food-contact CO₂ purification, tightening supply security for high-volume meat packers.
Retail procurement consolidation is compressing supplier negotiation cycles. French and German supermarket chains now mandate 18-month price locks with volume guarantees, forcing film converters to hedge resin exposure through fixed-term ethylene contracts rather than spot market purchases.
Active and Modified Atmosphere Packaging Market Segmentation
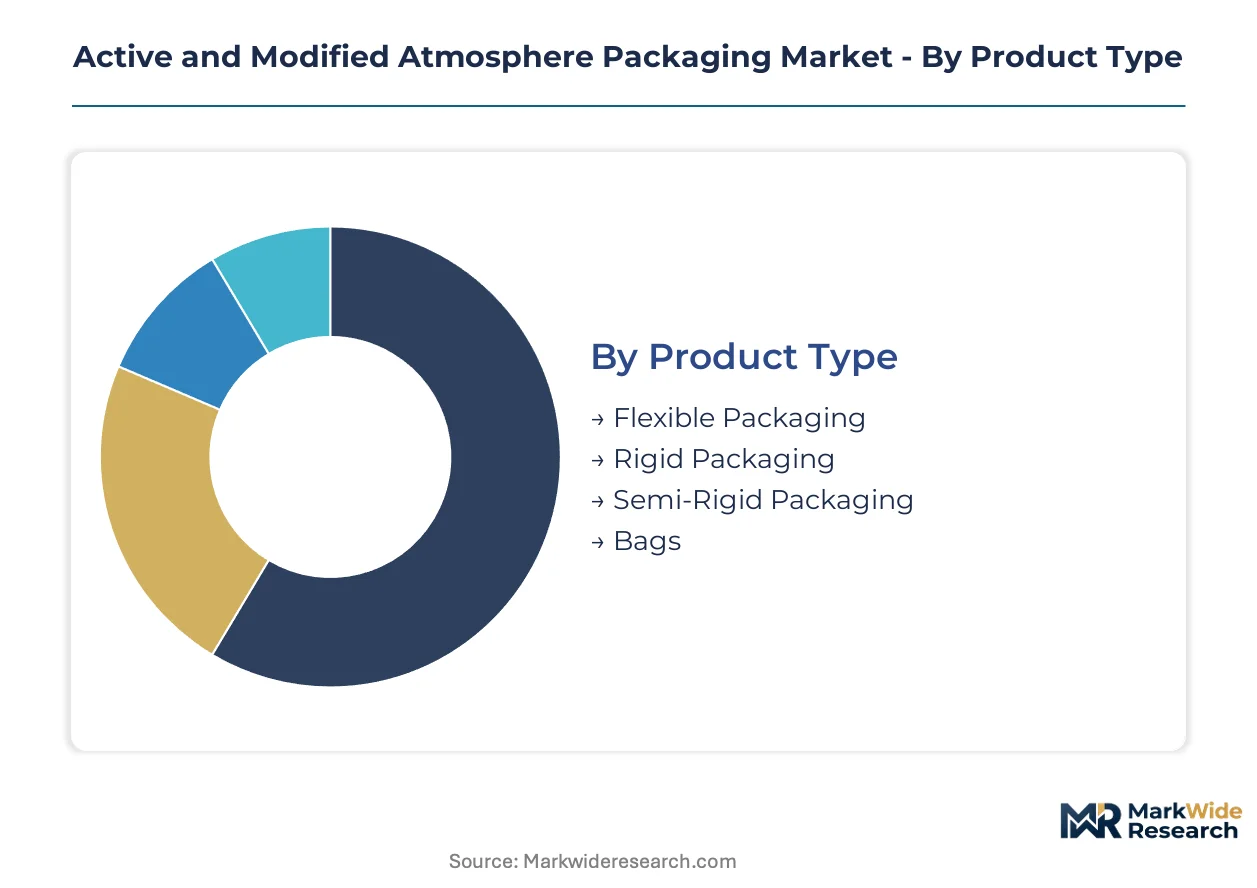
Segmentation in the Active and Modified Atmosphere Packaging market reveals distinct technical requirements across substrate formats and end-use applications. Equipment service intervals, gas calibration protocols, and barrier film replacement cycles vary sharply by product category, creating divergent aftermarket revenue streams for suppliers.
Product Type:
After-sales service intensity escalates with equipment complexity and barrier performance requirements. High-barrier systems demand quarterly gas analyzer calibration and annual seal integrity validation, while standard flexible formats require minimal field intervention beyond film replenishment.
- Flexible Packaging:Multi-layer coextruded films with EVOH or PA cores achieve oxygen transmission rates below 1 cc/m²/day. Form-fill-seal automation lines in Germany's Ruhr Valley meat processing clusters consume the highest volumes, driven by discounter chain consolidation into case-ready formats.
- Rigid Packaging:Thermoformed trays with integrated lidding films provide structural integrity for retail display. French and German supermarket chains specify these for premium meat and poultry segments where presentation quality commands shelf price premiums.
- Semi-Rigid Packaging:Hybrid structures combining rigid bases with flexible lids serve modified atmosphere applications requiring resealability. Dutch dairy processors favor these for cheese formats.
- Bags:Pre-made gusseted pouches with one-way valves suit bulk produce and bakery applications. Spanish fresh produce exporters deploy these for climacteric fruit shipments to Northern Europe.
By volume, Flexible Packaging leads. By growth pace, Rigid Packaging is ahead.
Material:
Cost tier stratification separates commodity substrates from engineered barrier structures. Mono-material formulations command resin premiums of 15-25% over multi-layer alternatives but unlock compliance with EU Green Deal recyclability mandates.
- Plastic:Polyethylene, polypropylene, and PET dominate with tunable barrier properties. German converters are pivoting toward mono-PE and mono-PP structures to meet Packaging and Packaging Waste Regulation quotas.
- Metal:Aluminum lidding foils and metallized films provide near-zero oxygen transmission for ultra-low oxygen applications. Italian cured meat producers specify these for extended shelf-life requirements.
- Paper:Kraft-based barrier papers with polymer coatings serve sustainability-positioned retail formats. Mondi Group's integrated operations anchor European supply.
- Composites:Multi-layer structures combining plastic, paper, and aluminum deliver maximum barrier performance. These face phase-out pressure under extended producer responsibility schemes.
Plastic substrates dominate volume throughput. Paper-based alternatives are climbing fastest as brand owners execute sustainability transitions.
End User:
Application maturity varies sharply by sector compliance burden and spoilage cost structure. Food processors accept premium packaging costs given finished goods value concentration, while pharmaceutical adopters remain limited by validation overhead.
- Food & Beverage:Meat, dairy, produce, and bakery applications constitute the core demand base. Centralized retail procurement in Germany and France drives specification standardization across protein processing.
- Pharmaceuticals:Blister packs and vial systems for oxygen-sensitive APIs employ nitrogen flushing and scavenger integration. EMA stability testing requirements slow adoption relative to food sector pace.
- Personal Care:Cosmetic and skincare formats utilize modified atmosphere to extend natural preservative-free formulations. Niche positioning limits volume scale.
- Electronics:Moisture and oxygen protection for semiconductors and sensors employs similar barrier engineering. Dutch and Belgian industrial gas suppliers serve this crossover demand.
Food & Beverage commands absolute volume. Pharmaceuticals shows steepest expansion trajectory as biologics packaging requirements tighten.
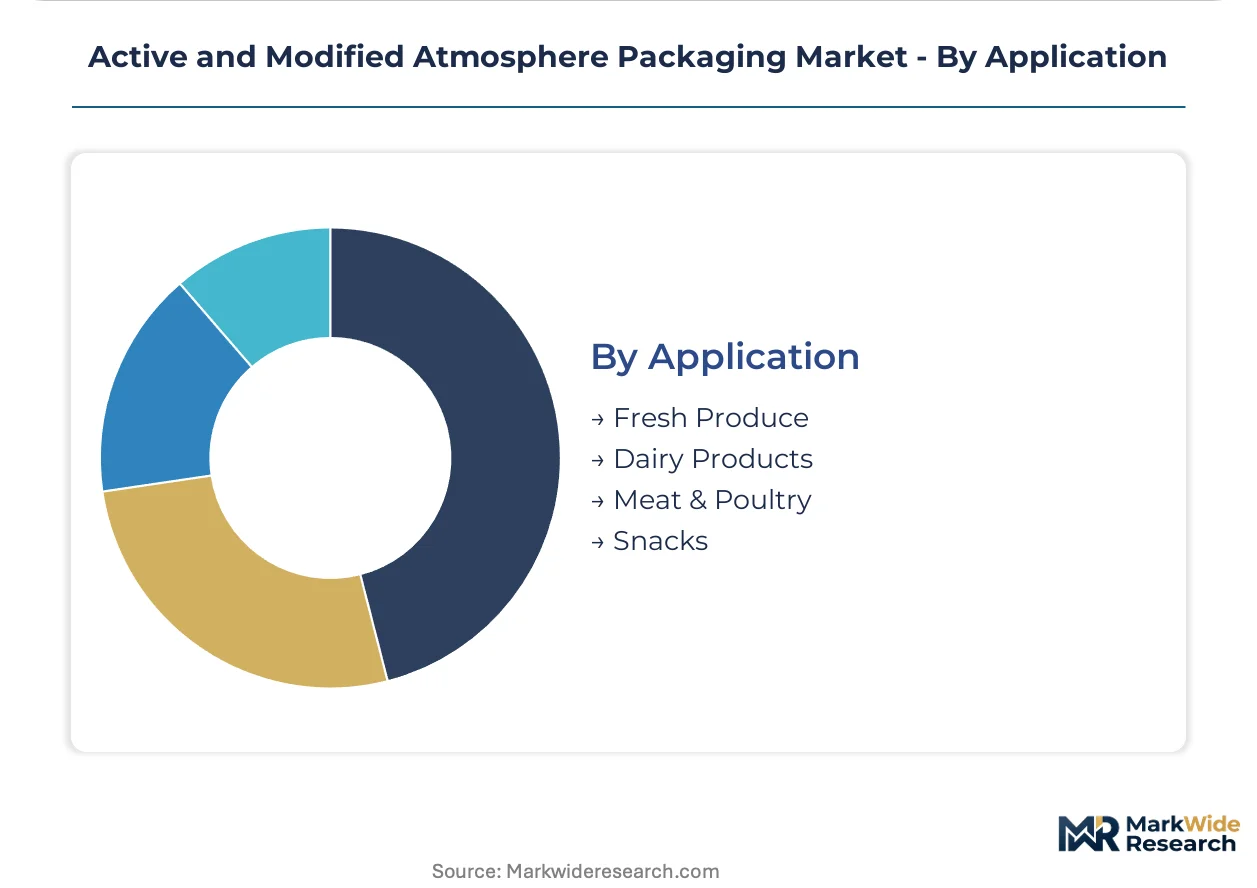
Application:
Respiration rate differentials dictate film engineering complexity. Climacteric fruits require breathable micro-perforated structures, while processed meats demand absolute barrier integrity.
- Fresh Produce:Laser-perforated films with 50-200 micron holes balance oxygen and carbon dioxide exchange. Berry producers in Spain and Portugal are adopting these at accelerated rates to extend refrigerated distribution windows.
- Dairy Products:Hard cheese and fresh pasta formats require elevated carbon dioxide levels to inhibit mold. Italian and French processors specify high-barrier lidding with anti-fog coatings.
- Meat & Poultry:Ultra-low oxygen or high-oxygen modified atmospheres preserve color and retard microbial growth. Case-ready tray formats dominate German retail meat counters.
- Snacks:Nitrogen flushing displaces oxygen to maintain crispness and prevent rancidity. Coffee and nut applications in Belgium and Netherlands utilize vertical form-fill-seal lines with integrated gas flushing.
Meat & Poultry leads by revenue contribution. Fresh Produce is gaining share fastest as breathable film technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retail concentration extracts 15-20% price premiums on high-barrier tray contracts versus Spanish fresh produce exporters negotiating spot film purchases. This pricing-power asymmetry reflects centralized procurement power in Northern Europe against fragmented Mediterranean supplier bases.
Germany
Discounter chains Aldi and Lidl consolidate 65% of national meat case-ready procurement into multi-year barrier film contracts. The country's VerpackG extended producer responsibility scheme transfers end-of-life collection costs upstream to converters. The Ruhr Valley meat processing cluster around Dortmund and Essen operates Europe's densest form-fill-seal automation corridor.
France
Hypermarket chains Carrefour and Auchan mandate 18-month price locks with volume guarantees for premium meat tray specifications. The national Citeo EPR scheme imposes packaging recovery fees that compress margins on standard barrier grades. The Brittany dairy processing belt around Rennes deploys modified atmosphere lidding for hard cheese export formats.
Spain
Berry producers in Huelva and Almería accelerate laser-perforated film adoption to extend refrigerated distribution windows for Northern European export. The national waste framework law transposes EU Green Deal recyclability mandates into binding converter obligations. The Valencia fresh produce export hub specializes in climacteric fruit breathable film engineering.
Netherlands
Dutch dairy processors favor semi-rigid resealable formats for cheese applications requiring repeated consumer access. The country's industrial gas suppliers retrofit beverage-grade CO₂ recovery systems to secure food-contact gas supply under EU F-Gas Regulation phase-down schedules. The Rotterdam port logistics cluster handles bulk barrier film resin imports for Benelux converter networks.
India
FSSAI-mandated temperature-controlled distribution for dairy and meat creates first-mover positioning for MAP equipment suppliers. The national food safety regulator's cold chain directives force processor upgrades in Mumbai and Delhi NCR clusters. Maharashtra's dairy cooperatives pilot modified atmosphere bulk milk pouch formats to reduce spoilage in monsoon-season distribution.
Active and Modified Atmosphere Packaging Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in film extrusion and gas supply niches. The market structure tilts toward consolidation at the packaging converter level while remaining fragmented among industrial gas blenders and equipment fabricators. Three archetypes dominate: multinational film converters with integrated R&D, regional specialists in breathable laser-perforation, and industrial gas majors with captive CO₂ recovery. Capacity expansion and mono-material substrate transitions constitute the dominant competitive moves.
Within the multinational converter tier, Amcor, Sealed Air Corporation, and Mondi Group exemplify scale-driven platform positioning. Amcor's multi-layer coextrusion capabilities anchor high-barrier tray supply for protein processors. Sealed Air Corporation occupies the vacuum skin packaging specialist position with sustained R&D intensity in purge-reduction systems. Mondi Group's integrated kraft paper and plastic film operations secure European flexible MAP volume leadership through backward integration into fiber supply.
| Leading Market Players |
|---|
| Berry Global |
| Linde AG |
| Amcor |
| Klöckner Pentaplast |
| Air Products and Chemicals Inc. |
| Sealed Air Corporation |
| Winpak Ltd. |
| ProAmpac |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp barge freight corridors carry EVOH resin and barrier film substrates from Benelux ports to German meat processing clusters, where centralized retail procurement extracts volume discounts that Mediterranean fresh produce exporters cannot match, creating a north-south price spread that widens during ocean freight spikes.
Pricing Analysis
The customization-premium spread separates configured-to-order high-barrier tray specifications from standard flexible film grades. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance tiers and ISO 22000 certification status. Cost compression in standard flexible grades is intensifying because Germany's VerpackG extended producer responsibility fees transfer end-of-life collection costs upstream. Discounter chains exhibit lowest price sensitivity due to multi-year volume guarantees, while Spanish fresh produce exporters negotiate spot purchases with highest sensitivity to resin volatility.
Supply Chain Analysis
Supplier-financing facilities from German chemical distributors extend 90-day payment terms to small converters, easing working capital strain during mono-material transition investments. EVOH resin supply concentrates in Japan, Taiwan, and South Korea, while barrier film extrusion clusters in Germany, France, and Italy process these inputs. Feedstock volatility in Asian petrochemical markets creates margin squeeze risk for European converters locked into fixed-price retail contracts. Distribution runs through centralized procurement desks at three German retail conglomerates that specify technical standards across their supplier bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified gas blending technicians capable of calibrating nitrogen-carbon-dioxide-oxygen mixtures remain concentrated in Netherlands and Italy, creating recruitment bottlenecks that constrain Eastern European plant expansions and inflate labor costs for new market entrants.
For Market Incumbents: Entrench barrier film supply relationships with German discounter chains through multi-year price locks that hedge resin exposure via fixed-term ethylene contracts. Invest in mono-material coextrusion R&D to preserve oxygen transmission performance below regulatory thresholds before EU Green Deal recyclability mandates phase out multi-layer structures. Backward integration into laser-perforation equipment manufacturing secures breathable film capacity for fresh produce segment expansion. For New Entrants and Emerging Players: Establish a beachhead in India's Mumbai and Delhi NCR dairy processing clusters where FSSAI cold chain mandates force equipment upgrades and local MAP supplier penetration remains limited. Target carbon-based oxygen scavenger integration for ready-meal segments blocked by legacy iron-scavenger metal detector interference. Pursue direct equipment-leasing models with gas calibration training bundles to bypass incumbent converter relationships. For Investors and Strategic Acquirers: Regional specialists in laser-perforated breathable film engineering command scarcity premiums as berry shelf-life extension demand accelerates across Mediterranean export corridors. Long-term viability hinges on mono-material substrate transition execution speed and captive CO₂ recovery system ownership under EU F-Gas Regulation phase-down schedules. Watch Germany's ISO 22000 audit backlog duration as an inflection indicator for new product launch velocity and aftermarket service revenue timing.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Substrate Transition | EU Green Deal Packaging and Packaging Waste Regulation quotas force EVOH substitution with recyclable PE and PP structures. |
| CO₂ Recovery System Investment | Belgian and Dutch industrial gas suppliers retrofit beverage-grade units to secure food-contact gas supply under F-Gas phase-down. |
| Laser-Perforation Capacity Expansion | Spanish and Portuguese berry producers adopt breathable films to extend refrigerated distribution windows for Northern Europe. |
| Gas Blending Technician Certification Programs | Netherlands and Italy training centers address scarcity bottlenecks constraining Eastern European plant expansions. |
| Direct-to-Consumer Protein Format Development | London and Paris e-commerce meat delivery services require case-ready formats with extended shelf life bypassing retail markups. |
Study Parameters
Initial hypotheses were tested against primary input from gas blending technicians, barrier film procurement managers at German meat processors, laser-perforation equipment engineers, and retail category buyers at French hypermarket chains, and refined through secondary validation against EU F-Gas Regulation implementation schedules, FSSAI cold chain directive filings, and SEC disclosures from multinational packaging converters. Bottom-up volume estimates from equipment installation databases and film resin consumption figures were triangulated against top-down market sizing from retail procurement value aggregation.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling volume trajectories by substrate format, end-use application, barrier performance tier, and regional regulatory cluster. CAGRs were derived from segmented growth rate reconciliation and cross-referenced with industrial gas supplier capacity expansion announcements and retail chain format conversion timelines. Forecast inputs included EVOH resin price elasticity coefficients and mono-material substitution technical feasibility curves.
Stress conditions across Asian petrochemical feedstock volatility, EU extended producer responsibility fee escalation, and certified technician availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Heat Sensitive Cups Market
Active & Intelligent Packaging
Intelligent Packaging Market
Active & Intelligent Packaging
Active Packaging Market
Active & Intelligent Packaging
Europe Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Active and Intelligent Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Connected Packaging Market
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
Asia Pacific Active and Intelligent Packaging Market
Active & Intelligent Packaging
Latin America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Ambient Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
Middle East and Africa Active and Intelligent Packaging Market