
 Ultra-High Barrier Films Market | 2026-2036
Ultra-High Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-High Barrier Films Market Outlook
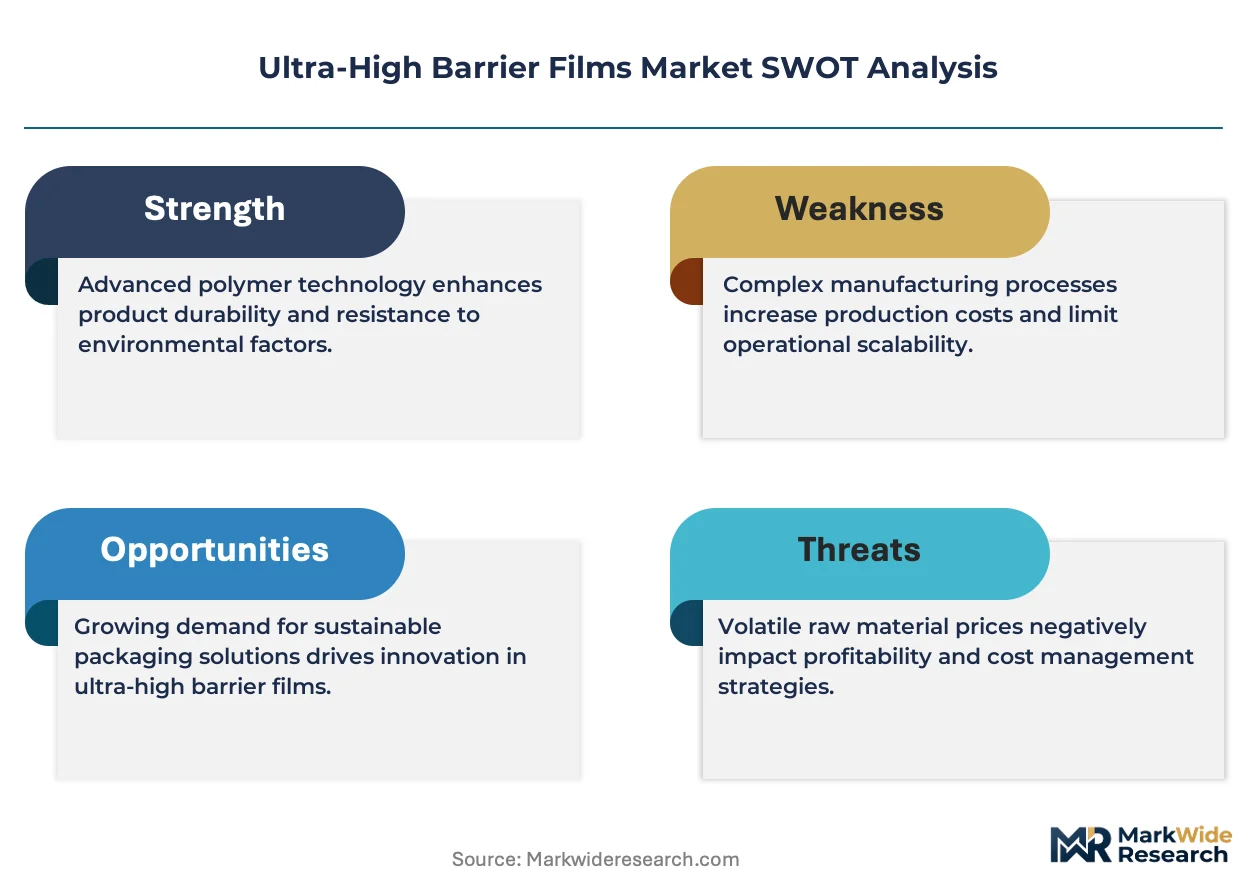
Aftermarket technical service revenue for film calibration and barrier performance testing is reconfiguring how suppliers capture lifetime value from packaging buyers. Amcor plc leverages its integrated R&D network across polymer science to sustain technology leadership in oxygen transmission rate reduction. Klöckner Pentaplast anchors European pharmaceutical barrier supply through specialized cleanroom extrusion capabilities. Mondi competes by controlling fiber-based substrate integration with high-barrier polymer layers.
Ultra-high barrier films are multi-layer polymer structures, typically achieving oxygen transmission rates below 0.1 cc/m²/day through vacuum deposition of aluminum oxide or silicon oxide onto polyester or polyamide substrates, engineered to prevent moisture, oxygen, and volatile gas ingress in sensitive product environments. Polyamide films dominate pharmaceutical and medical device packaging where puncture resistance couples with barrier performance, while coated films represent the fastest-growing technology segment as water-based and solvent-free coating chemistries displace conventional metallization for recyclability compliance. Vacuum deposition occupies the premium tier of the technology spectrum, commanding higher margins due to capital intensity and exacting process control requirements.
The FDA enforces stringent stability testing protocols for pharmaceutical packaging that mandate documented barrier performance across temperature and humidity extremes, while REACH restricts certain phthalate plasticizers and halogenated flame retardants used in legacy film formulations. EMA guidelines on primary packaging materials for medicinal products further shape European product development roadmaps. Stakeholders must monitor evolving extended producer responsibility frameworks and recyclability targets that will determine which barrier technologies retain market access across major economies.
Market Dynamics
Pharmaceutical packaging procurement is consolidating around multi-layer co-extruded films as biologics manufacturers demand oxygen transmission rates below 0.1 cc/m²/day, forcing extrusion houses to retool for vacuum deposition capabilities.
Growth Catalysts
- EU F-Gas Regulation:The European framework restricting fluorinated greenhouse gases accelerates substitution of conventional metallized barriers with aluminum oxide vacuum-deposited alternatives across German and French pharmaceutical clusters.
- Biologics cold chain expansion:Cell and gene therapy manufacturers in Basel and Boston are specifying polyamide-based barrier structures that combine puncture resistance with ultra-low moisture vapor transmission.
- Cleanroom extrusion infrastructure:Specialized polymer processing facilities around Düsseldorf and Hamburg anchor European supply security for medical device barrier films requiring ISO 14644 compliance.
Market Restraints
- Capital intensity of vacuum deposition:Roll-to-roll plasma coating equipment requires seven-figure euro investments, concentrating production among integrated polymer converters with captive metallization lines.
- Ethylene-vinyl alcohol supply concentration:EVOH resin production clusters in Japan and the United States expose European film laminators to currency and shipping cost volatility.
- REACH substance restrictions:ECHA classification of certain phthalate plasticizers as substances of very high concern forces reformulation of legacy adhesive tie layers in multi-barrier structures.
Strategic Opportunities
- Water-based coating chemistry:Solvent-free barrier coatings enable recyclability compliance under extended producer responsibility frameworks emerging in France and Italy.
- Pharmaceutical serialization integration:Track-and-trace mandates under the EU Falsified Medicines Directive create demand for barrier films with embedded authentication features.
- Indian biopharma manufacturing:CDSCO approval pathways for imported packaging materials position vacuum-deposited films for penetration into Mumbai and Hyderabad formulation facilities.
Industry Challenges
- Vacuum deposition process control:Maintaining sub-nanometer oxide layer uniformity across 2-meter web widths requires specialized plasma physics expertise scarce in conventional extrusion operations.
- Barrier performance certification timelines:FDA stability testing protocols for pharmaceutical primary packaging demand 24-month documentation cycles that delay new film commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-High Barrier Films Market |
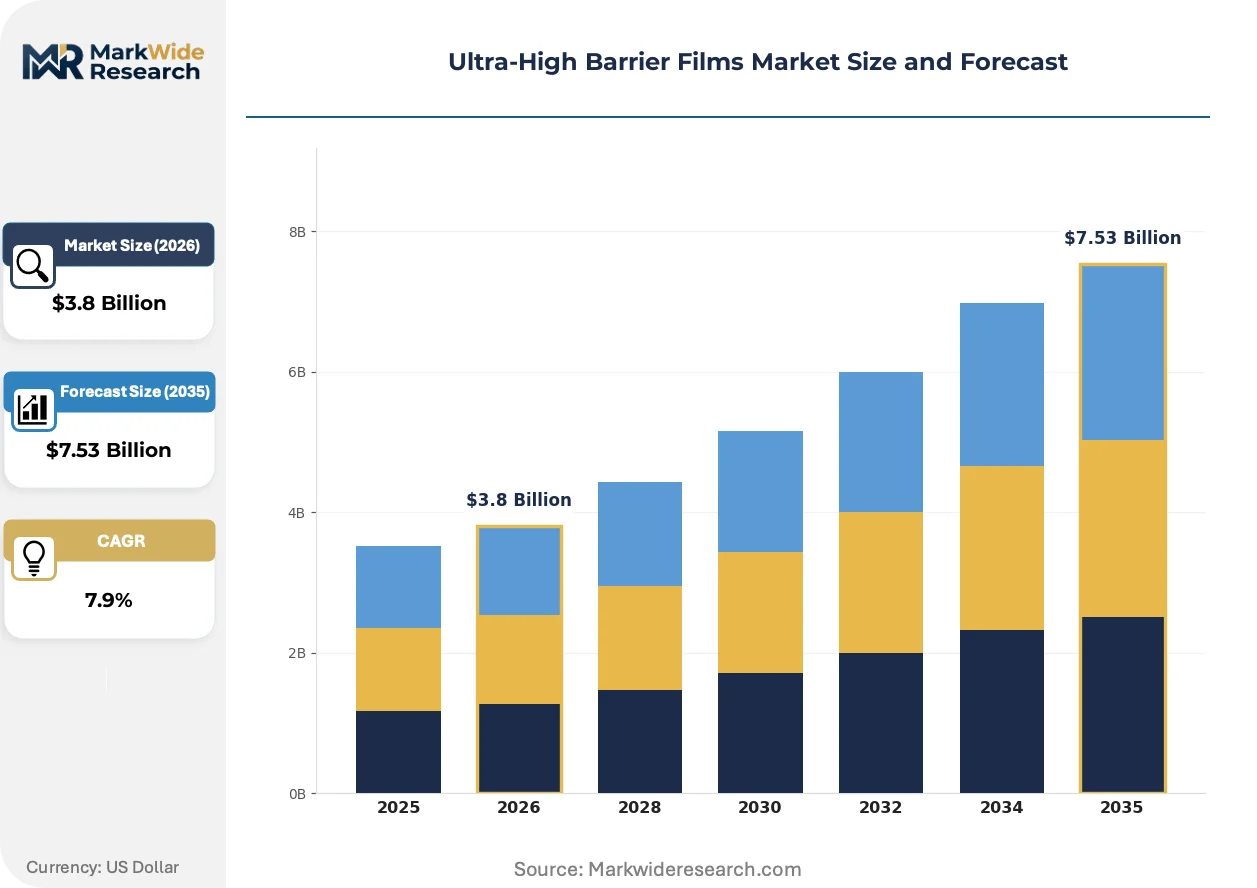
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyamide Films, Polyester Films, Polypropylene Films, Coated Films Application: Food Packaging, Pharmaceutical Packaging, Electronics Packaging, Industrial Applications End Use Industry: Consumer Goods, Healthcare, Electronics, Automotive Technology: Nanotechnology, Biodegradable Films, Vacuum Deposition, Co-extrusion |
| Companies Covered | Klöckner Pentaplast, Constantia Flexibles, Amcor plc, Coveris, Berry Global, Sealed Air, Mondi, Sonoco Products Company, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-High Barrier Films Market Strategic Shifts
Barrier film technology is bifurcating between premium vacuum-deposited structures and recyclable coated alternatives, with regulatory pressure on carbon footprints and circularity mandates determining which pathway gains procurement preference.
Atomic layer deposition of silicon oxide onto biaxially oriented polyamide substrates is collapsing the performance gap between metallized and transparent barrier films. Pharmaceutical blister pack manufacturers in Germany and Switzerland are qualifying these structures for moisture-sensitive oncology APIs. The technology is collapsing traditional tiering between high-barrier and medium-barrier price bands as single-layer ALD coatings match multi-layer laminate performance.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant barrier coatings used in medical device pouches. The European Chemicals Agency restriction roadmap is eliminating C6 fluorochemistry options by 2026. Converters in Northern Italy are accelerating migration to bio-based barrier coatings certified under OK Compost INDUSTRIAL standards.
Aftermarket technical service contracts for barrier performance testing and calibration are unbundling from film supply agreements. Pharmaceutical packaging engineers in Basel and Copenhagen are procuring oxygen transmission rate validation as separate line items rather than bundled quality assurance. This shift is most visible in Nordic markets where centralized procurement functions demand transparent cost allocation across material and service components.
Ultra-High Barrier Films Market Segmentation
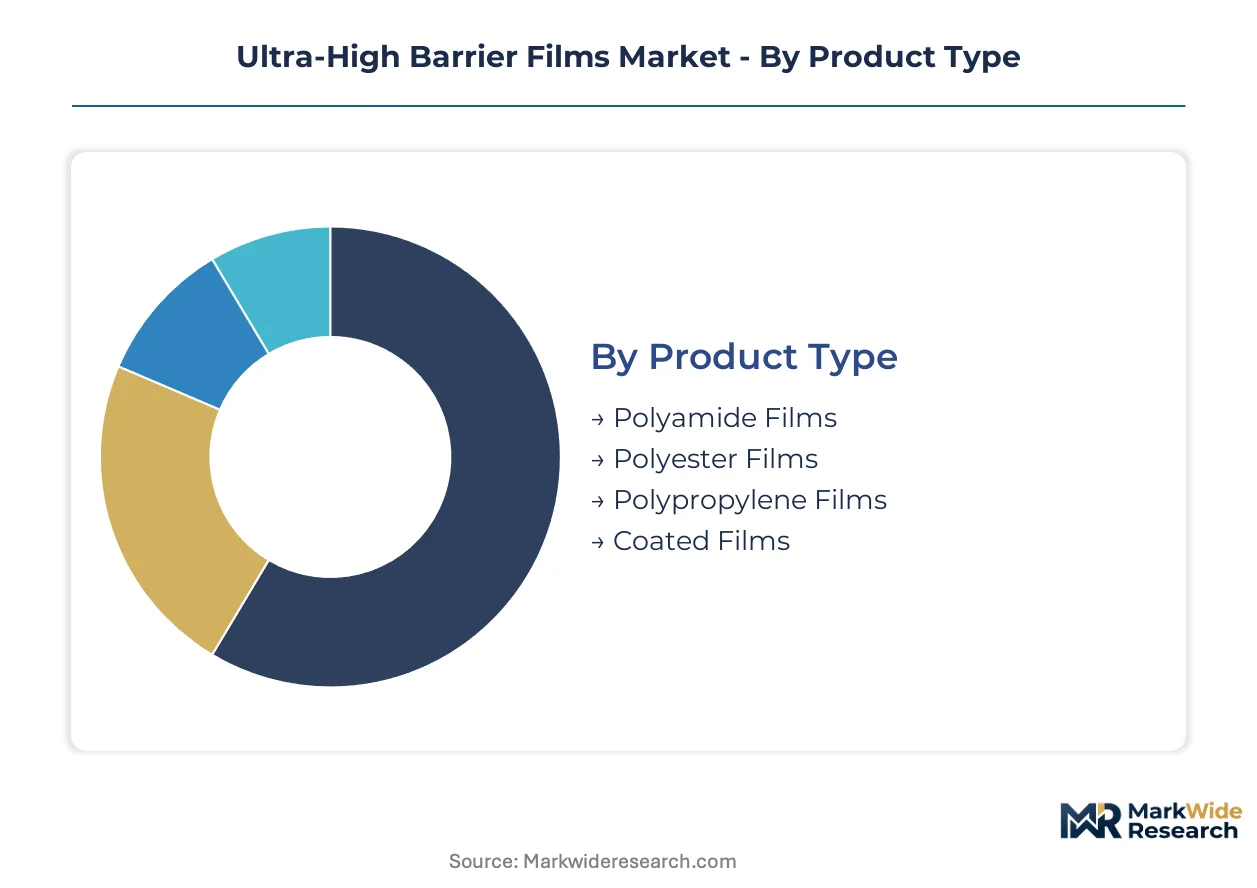
Ultra-high barrier films fragment across material chemistry, deposition technology, and end-use specifications that determine oxygen transmission rates and moisture protection levels. Procurement teams match film architecture to product sensitivity requirements, creating distinct competitive arenas with divergent margin structures and technical barriers.
Product Type:
Mature polymer substrates anchor established packaging applications while emerging film chemistries address recyclability mandates and cold-chain logistics.
- Polyamide Films:Biaxially oriented polyamide substrates deliver puncture resistance combined with ultra-low moisture vapor transmission rates. Pharmaceutical blister pack manufacturers in Germany and Switzerland specify these structures for oncology APIs requiring protection across temperature extremes.
- Polyester Films:Biaxially oriented polyethylene terephthalate provides dimensional stability and optical clarity for transparent barrier applications. Electronics packaging engineers in Japan and South Korea favor PET substrates for display component protection where visual inspection matters.
- Polypropylene Films:Oriented polypropylene offers cost-efficient moisture barriers for less sensitive food applications.
- Coated Films:Water-based and solvent-free barrier coatings enable circular economy compliance under emerging extended producer responsibility frameworks.
Polyamide films retain volume leadership in pharmaceutical specifications; coated films hold the steepest expansion curve as recyclability regulations tighten across European markets.
Application:
End-use requirements diverge sharply between shelf-life extension needs and active pharmaceutical ingredient protection protocols.
- Pharmaceutical Packaging:Multi-layer co-extruded and vacuum-deposited structures achieve oxygen transmission rates below 0.1 cc/m²/day for biologics protection. Cell and gene therapy manufacturers in Basel and Boston drive specification tightening for cold-chain distribution.
- Food Packaging:Modified atmosphere packaging for fresh proteins and ready meals employs medium-barrier structures with cost-optimized layer counts. European retail chains in France and Italy are qualifying recyclable barrier alternatives under packaging waste directives.
- Electronics Packaging:Flexible circuit boards and display components require static-dissipative barrier films with precise moisture control.
- Industrial Applications:Chemical and agricultural product packaging utilizes puncture-resistant structures with moderate barrier performance.
Pharmaceutical packaging commands premium pricing tiers; food packaging applications are expanding most quickly as clean-label and extended shelf-life demands converge.
End Use Industry:
Customer procurement sophistication varies from centralized pharmaceutical engineering functions to fragmented consumer goods converters.
- Healthcare:Medical device and pharmaceutical manufacturers enforce ISO 15378 quality management systems with documented barrier performance across 24-month stability protocols. FDA and EMA primary packaging guidelines shape material selection roadmaps for sterile barrier systems.
- Electronics:Semiconductor and display manufacturers specify ultra-low outgassing films with ionic contamination controls. South Korean and Japanese electronics clusters drive specification innovation for foldable device protection.
- Consumer Goods:Personal care and household product brands balance barrier performance with shelf presence and sustainability credentials.
- Automotive:Battery component and sensor packaging requires thermal stability combined with moisture exclusion for electric vehicle electronics.
Healthcare retains the most stringent certification requirements; automotive applications are gaining share fastest as electrification accelerates component protection needs.
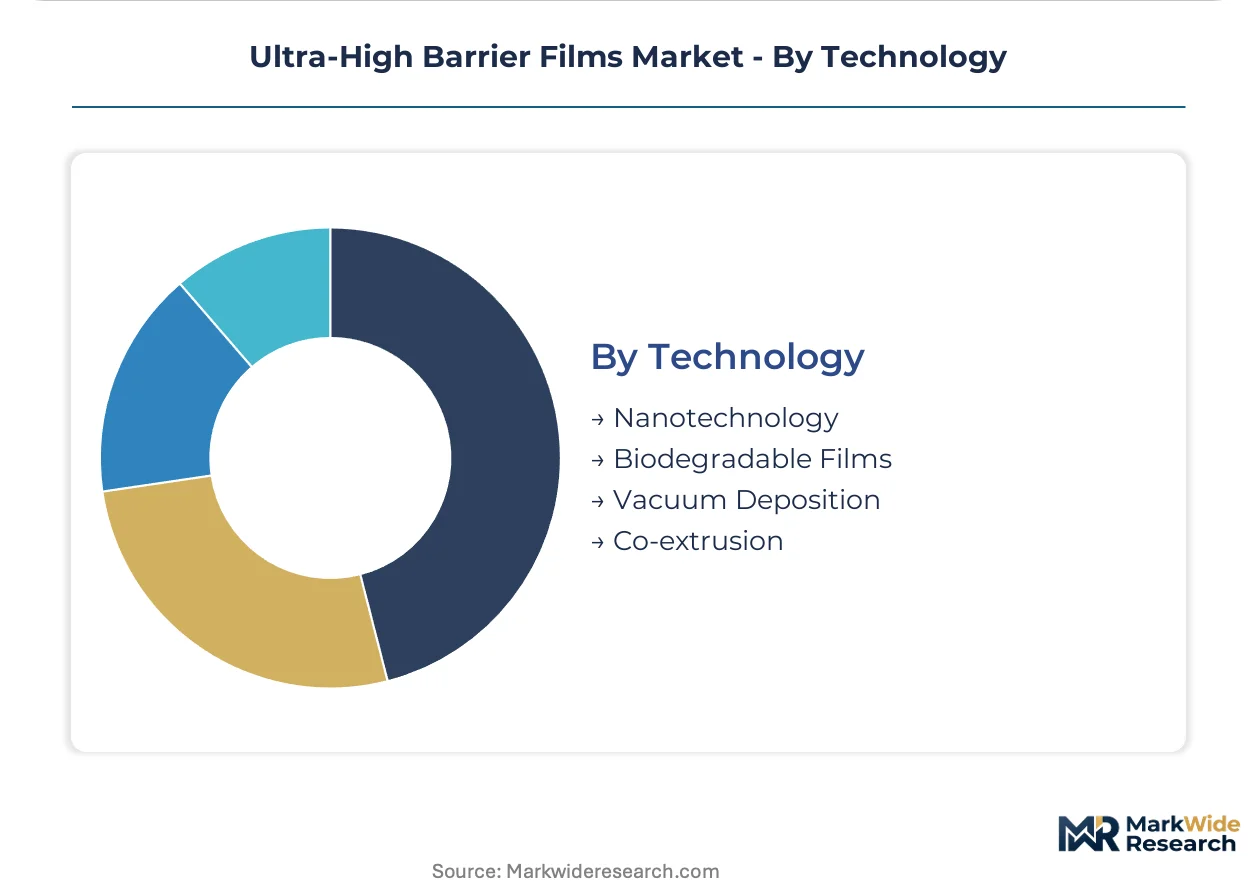
Technology:
Deposition and extrusion methods separate premium performance tiers from cost-optimized alternatives with divergent capital intensity profiles.
- Vacuum Deposition:Roll-to-roll plasma coating of aluminum oxide or silicon oxide achieves transparent ultra-barrier performance with sub-nanometer thickness control. German and Swiss pharmaceutical packaging clusters concentrate capacity around Düsseldorf and Hamburg industrial zones.
- Co-extrusion:Multi-layer melt processing combines polyamide, EVOH, and tie layers in single-pass operations for medium-barrier applications. European converters are retooling lines to accommodate bio-based feedstocks under EU Green Deal circularity targets.
- Nanotechnology:Atomic layer deposition of silicon oxide onto polymer substrates collapses performance gaps between metallized and transparent barriers.
- Biodegradable Films:Bio-based barrier structures certified under industrial composting standards address single-use packaging restrictions.
Vacuum deposition holds technology leadership in pharmaceutical specifications; biodegradable films are climbing the fastest as regulatory deadlines for packaging waste reduction approach across France, Italy, and Germany.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical buyers in Switzerland and Germany absorb premium pricing for vacuum-deposited films without volume elasticity, while food packaging converters in Southern Europe demand cost-engineered alternatives that sacrifice barrier performance for recyclability compliance.
Germany
Biologics manufacturers around Düsseldorf and Hamburg specify oxygen transmission rates below 0.1 cc/m²/day for cold-chain distribution. The EU F-Gas Regulation accelerates substitution of conventional metallized barriers with aluminum oxide vacuum-deposited alternatives. Industrial clusters in North Rhine-Westphalia anchor European pharmaceutical barrier supply through ISO 14644-compliant cleanroom extrusion facilities.
United States
FDA stability testing protocols mandate 24-month documentation cycles for primary packaging materials, concentrating procurement among established converters with validated quality systems. Cell and gene therapy manufacturers in Greater Boston drive specification tightening for moisture-sensitive APIs. The EPA oversees chemical safety in adhesive tie layers as REACH-equivalent substance restrictions emerge at state level.
Switzerland
Swissmedic guidelines on primary packaging materials shape development roadmaps for sterile barrier systems in Basel's pharmaceutical corridor. Oncology API producers specify polyamide-based structures combining puncture resistance with ultra-low moisture vapor transmission. The country's precision manufacturing heritage supports sub-nanometer oxide layer uniformity requirements for premium pharmaceutical specifications.
India
CDSCO approval pathways for imported packaging materials position vacuum-deposited films for penetration into Mumbai and Hyderabad formulation facilities. Domestic biopharma manufacturing expansion creates demand for barrier films with embedded authentication features under track-and-trace mandates. The PLI scheme for pharmaceuticals indirectly supports packaging localization as global CDMOs establish Indian manufacturing footprints.
Japan
PMDA quality management requirements for medical device packaging enforce documented barrier performance across temperature and humidity extremes. Electronics manufacturers in Kanto specify static-dissipative barrier films with precise moisture control for flexible circuit board protection. METI supports advanced materials R&D through national technology programs targeting foldable device packaging applications.
Ultra-High Barrier Films Market Competitive Environment
Capability concentration sits with integrated polymer converters possessing captive vacuum deposition lines; scale advantage sits with diversified packaging conglomerates with global extrusion networks. The market structures around three tiers: premium specialists commanding technology leadership in pharmaceutical specifications, mid-scale regional converters serving food and industrial applications, and emerging coating technology providers addressing recyclability mandates. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with biologics manufacturers for co-development of application-specific barrier structures.
Within the integrated converter tier, Klöckner Pentaplast and Amcor plc exemplify archetypes of European pharmaceutical barrier supply and global polymer science R&D networks respectively. Mondi occupies a position bridging fiber-based substrate integration with high-barrier polymer layer control. These three anchors demonstrate how geographic clustering around Düsseldorf, Basel, and Vienna shapes competitive positioning through proximity to pharmaceutical manufacturing corridors.
| Leading Market Players |
|---|
| Klöckner Pentaplast |
| Constantia Flexibles |
| Amcor plc |
| Coveris |
| Berry Global |
| Sealed Air |
| Mondi |
| Sonoco Products Company |
| Huhtamaki |
| Others |
Value Chain & Pricing Dynamics
North Rhine-Westphalia's cleanroom extrusion cluster around Düsseldorf concentrates vacuum deposition capacity for pharmaceutical-grade barrier films, granting integrated converters pricing leverage over biologics manufacturers with limited alternative sourcing. This geographic concentration amplifies margin capture for multi-layer co-extruded structures serving moisture-sensitive APIs.
Pricing Analysis
Long-term offtake contracts dominate procurement between biologics manufacturers and integrated film converters, with pricing stratifying across premium, standard, and economy tiers based on oxygen transmission rate certification and ISO 14644 cleanroom compliance. Vacuum-deposited aluminum oxide films command substantial premiums over coated alternatives due to capital intensity and sub-nanometer process control requirements. Cost compression in standard-tier co-extruded films is intensifying as European converters retool for bio-based feedstocks. Food packaging converters in Southern Europe exhibit highest price sensitivity, while Basel and Boston pharmaceutical clusters absorb premium pricing without volume elasticity.
Supply Chain Analysis
Roll-to-roll plasma coating equipment manufacturers in Germany, Japan, and the United States control critical vacuum deposition capacity, with German and Swiss converters holding captive metallization lines for pharmaceutical specifications. EVOH resin production clusters in Japan and the United States expose European laminators to currency and shipping cost volatility. Single-source vulnerability concentrates in specialized plasma physics expertise for sub-nanometer oxide layer uniformity. Distribution runs through direct technical service relationships with pharmaceutical packaging engineers rather than commodity intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as biologics cold-chain expansion drives specification tightening for moisture-sensitive APIs, reversing prior margin compression in standard-tier segments.
For Market Incumbents: Pre-empt coating technology displacement by accelerating atomic layer deposition qualification for transparent barrier structures before REACH fluorochemistry restrictions eliminate legacy options. Lock in backward integration into EVOH resin compounding to neutralize Japanese and American supply concentration risk. Secure ISO 15378 certification investments ahead of FDA stability testing protocol updates.
For New Entrants and Emerging Players: Indian biopharma manufacturing corridors around Mumbai and Hyderabad offer underpenetrated entry points where CDSCO approval pathways for imported packaging materials remain navigable. Target pharmaceutical serialization integration requirements under the EU Falsified Medicines Directive as a wedge for embedded authentication feature development. Partner with Northern Italian converters migrating to OK Compost INDUSTRIAL certified bio-based coatings.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because pharmaceutical barrier certification creates durable moats around qualified converter relationships. Acquisition focus should center on mid-scale European converters with captive vacuum deposition lines and existing FDA master file documentation. Watch for inflection in Indian PLI scheme pharmaceutical manufacturing localization as signal for packaging import substitution pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Atomic Layer Deposition Scale-Up | Collapses performance gaps between metallized and transparent barriers for oncology APIs. |
| Backward Integration into EVOH Resin | Neutralizes currency exposure from Japanese and American supply concentration. |
| Water-Based Coating Chemistry Migration | Enables recyclability compliance under France and Italy extended producer responsibility frameworks. |
| Pharmaceutical Serialization Integration | Captures EU Falsified Medicines Directive track-and-trace mandate value. |
| Indian Manufacturing Footprint Establishment | Positions for CDSCO approval pathway localization as PLI scheme expands. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical packaging engineers, cleanroom extrusion facility managers, biologics supply chain directors, and barrier film R&D leads. Secondary validation drew from EMA primary packaging guidelines, FDA stability testing protocols, EU F-Gas Regulation filings, and REACH substance restriction roadmaps. Bottom-up capacity assessments across Düsseldorf and Hamburg industrial clusters were triangulated against top-down pharmaceutical procurement spend analysis.
Calibration against historical oxygen transmission rate specification trends informed volume projections across the analysis window, with segmentation modeling across material chemistry, deposition technology, and end-use industry dimensions. CAGRs were derived from regression analysis of procurement intensity against biologics pipeline expansion. Forecast inputs incorporated EVOH resin price volatility indices and cleanroom extrusion capacity utilization rates from German industrial zones.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese coating technology providers or accelerated Indian domestic manufacturing localization would shift outcomes beyond modeled ranges. Quarterly review of CDSCO approval pathway timelines and EU Green Deal circularity target revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Pipe Insulation Film Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Lining Market