
 Barrier Coated Papers Market | 2026-2036
Barrier Coated Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Coated Papers Market Analysis
REACH compliance is pivoting European converters toward water-based and bio-barrier formulations that eliminate perfluorinated chemistry. Mondi Group leverages integrated pulp-to-paperboard operations to control coating substrate quality across its Central European mills. Stora Enso Oyj anchors its barrier portfolio on renewable fiber sourcing certified under forest stewardship protocols. Sappi Limited competes through specialized kraft paper grades engineered for high grease resistance in protein packaging.
Barrier coated papers are fiber-based substrates treated with functional layers such as polyethylene, PVDC, wax, or silicone to impart resistance against moisture, oxygen, grease, or aroma transmission for protective packaging applications. Polyethylene coated grades dominate current volume due to established heat-seal performance and compatibility with existing filling equipment, though margin pools are shifting toward silicone coated variants as pharmaceutical blister liner demand expands. Wax coated applications in food packaging face structural decline in Western Europe as regulators restrict petroleum-derived additives, while PVDC coated specialty papers retain niche positions in industrial corrosion-wrap segments where barrier precision outweighs sustainability premiums.
The EU Green Deal and REACH frameworks restrict fluorochemical and certain plastic laminate uses in food contact materials, redirecting R&D spending toward bio-polymer and mineral barrier coatings. FDA food contact notifications and state-level extended producer responsibility laws in California and New York impose parallel compliance burdens on exporters serving North American healthcare and consumer goods channels. Stakeholders must monitor coating chemistry registration timelines and pilot-scale validation data before committing capital to barrier line conversions.
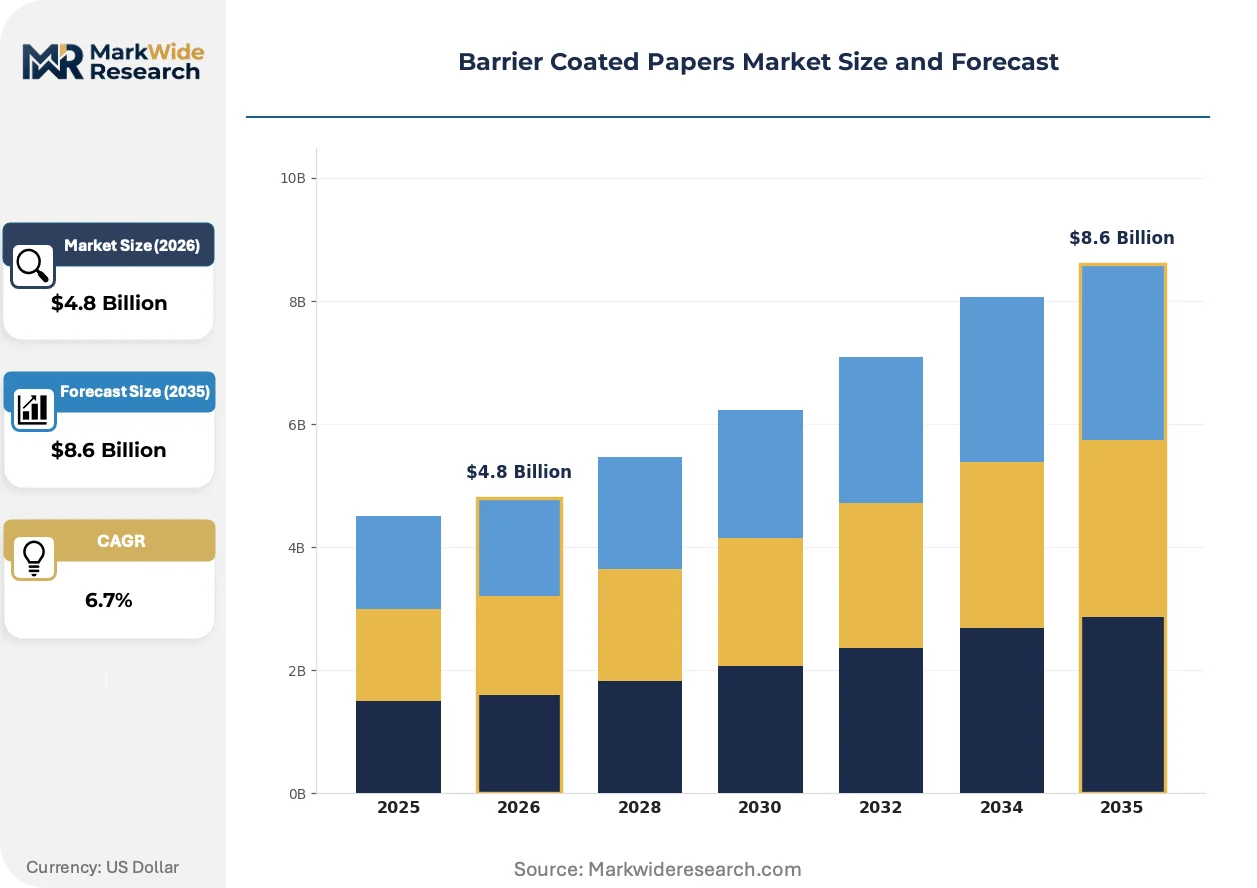
Market Dynamics
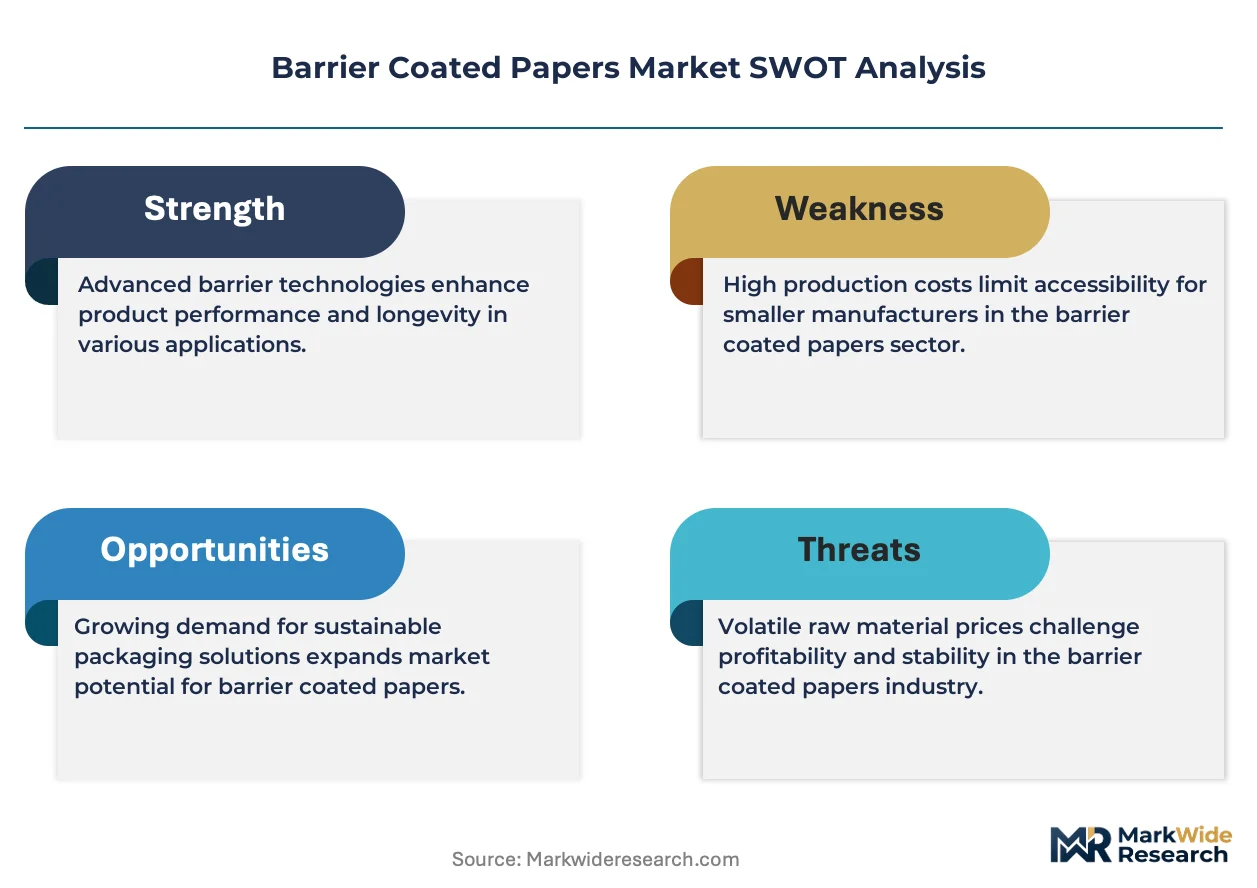
EU Green Deal packaging waste directives are forcing converters to abandon plastic laminates and fluorochemical barriers, redirecting capital toward water-based coating lines and bio-polymer formulations that meet REACH compliance without sacrificing heat-seal performance.
Growth Catalysts
- EU Green Deal packaging mandates:European regulators are phasing out single-use plastics in food contact applications, creating immediate substitution demand for fiber-based barrier solutions in ready-meal and fresh-produce segments.
- Pharmaceutical blister packaging expansion:Silicone coated papers are capturing share from aluminum-PVC laminates in cold-form blister applications where moisture barrier precision protects hygroscopic APIs.
- German converter investment concentration:Water-based coating line deployments in Baden-Württemberg and Bavaria are outpacing regional peers, establishing production clusters that serve Central European food brands.
Market Restraints
- Petroleum-derived wax input volatility:Wax coated food packaging faces structural cost pressure as crude-linked feedstock prices fluctuate, compounded by regulatory restrictions on petroleum additives in Western Europe.
- PVDC supply concentration:Specialty corrosion-wrap grades depend on chlorinated polymer supply chains concentrated in limited chemical manufacturing regions, exposing converters to single-source risk.
- Heat-seal performance gap:Bio-polymer barrier coatings remain incompatible with legacy high-speed filling equipment calibrated for polyethylene, requiring line retrofits that delay adoption.
Strategic Opportunities
- Indian food export packaging:FSSAI compliance requirements for moisture-resistant spice and ready-to-eat exports are creating demand for grease-resistant kraft grades that replace plastic pouches.
- California extended producer responsibility:State-level EPR laws are mandating fiber-based alternatives in healthcare and consumer goods channels, rewarding early movers with preferred supplier status.
- Mineral-bio hybrid coating convergence:Kaolin-clay and chitosan composite barriers are uniting oxygen blocking with compostability, opening pharmaceutical and premium food segments previously closed to fiber solutions.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise spanning polymer science, paper substrate behavior, and food contact compliance is concentrated among retiring specialists, constraining R&D velocity.
- Pilot-scale validation timelines:FDA food contact notification pathways and EU EFSA migration testing protocols extend commercialization cycles for novel bio-barrier chemistries beyond typical capital planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Coated Papers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Coated, PVDC Coated, Wax Coated, Silicone Coated Application: Food Packaging, Personal Care Products, Pharmaceutical Packaging, Industrial Uses Substrate: Paperboard, Kraft Paper, Label Stock, Specialty Papers End User: Food Industry, Healthcare Sector, Consumer Goods, Electronics |
| Companies Covered | International Paper, Mondi Group, Stora Enso Oyj, Sappi Limited, Ahlstrom-Munksjö Oyj, Cascades Inc., Gascogne Group, Schweitzer-Mauduit International, Domtar Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Coated Papers Market Emerging Trajectories
Water-based and bio-derived barrier technologies are converging with pulp-to-paperboard integration strategies, compressing the traditional multi-supplier coating value chain while regulatory chemistry restrictions eliminate legacy fluorinated options.
Mineral-bio hybrid barrier coatings are unifying oxygen transmission resistance with industrial compostability. Pharmaceutical blister liner manufacturers are adopting these formulations at pilot scale to replace aluminum-PVC laminates in moisture-sensitive drug packaging. This technology is unifying barrier performance with circular economy credentials, enabling converters to serve sustainability-mandated healthcare procurement.
REACH restrictions on perfluorinated chemistry are eliminating grease-resistant wax papers from European food service channels. ECHA substance evaluation timelines are forcing reformulation investments across Central European coating operations. Protein packaging and bakery applications are responding fastest, with brands specifying silicone and bio-polymer alternatives in supplier qualification protocols.
Healthcare procurement teams are consolidating vendor panels around certified barrier suppliers who demonstrate batch-level migration compliance. Group purchasing organizations are displacing fragmented regional converter relationships with multi-year supply agreements tied to ESG disclosure requirements. This concentration is most visible in German and Swiss hospital systems, where pharmacy directors now require coating chemistry transparency as a contract precondition.
Barrier Coated Papers Market Segmentation
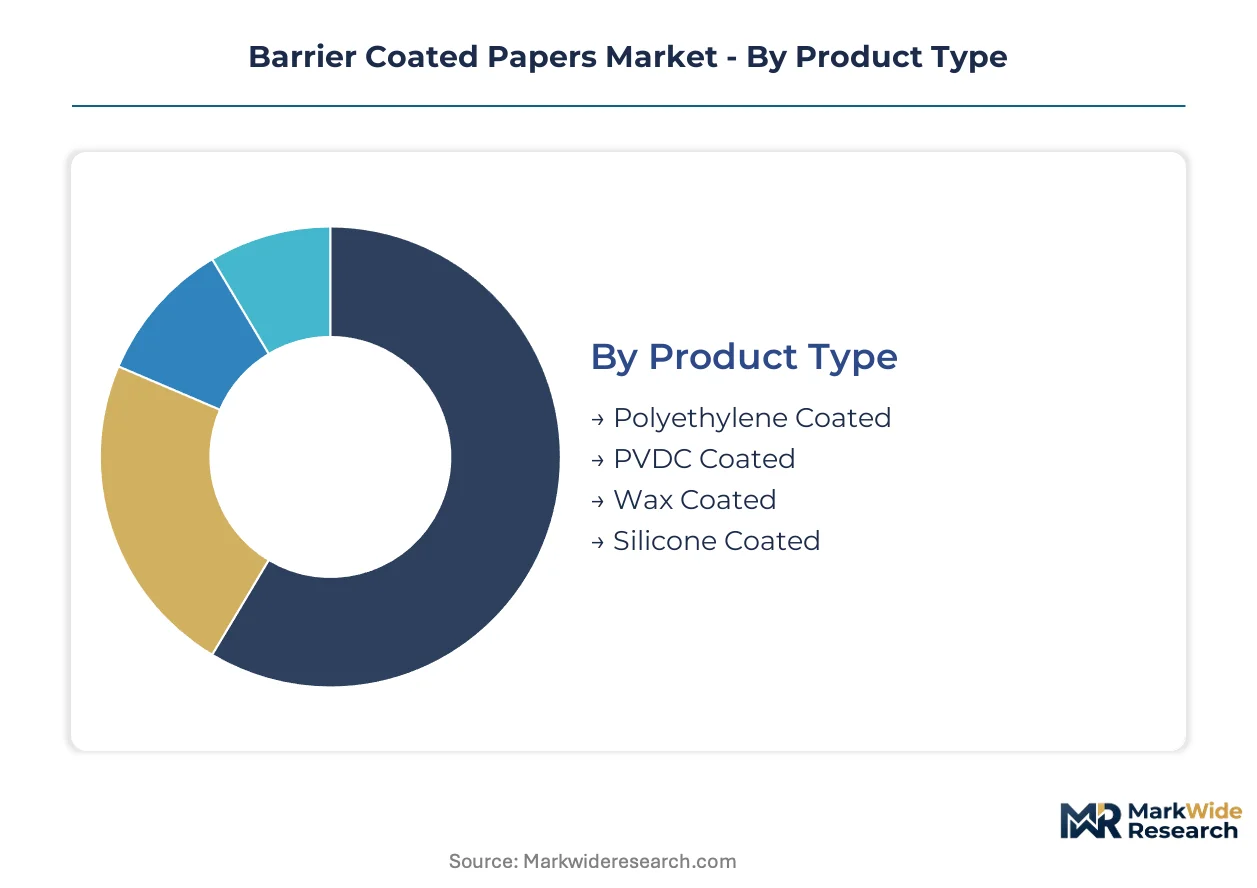
Barrier coated papers serve divergent performance requirements across food safety, pharmaceutical stability, and industrial protection. Coating chemistry selection and substrate engineering determine migration compliance, heat-seal integrity, and end-of-life pathways. Segment boundaries blur as converters develop hybrid formulations targeting multiple regulatory jurisdictions simultaneously.
Product Type:
Polyethylene coating capacity concentrates among integrated pulp-to-paperboard operators in Germany and Finland who control substrate quality upstream.
- Polyethylene Coated:These grades combine LDPE or extrusion-coated layers with bleached kraft substrates to deliver moisture vapor transmission rates below 10 g/m²/day. Demand clusters in German ready-meal packaging where brands require heat-seal compatibility with legacy filling equipment. EU Green Deal plastic reduction targets are forcing converters to defend polyethylene's position against bio-polymer challengers through downgauging and recyclability certifications.
- Silicone Coated:Platinum-cured silicone barriers provide release properties and oxygen blocking for pharmaceutical blister liners. Swiss and German healthcare procurement teams are specifying these grades to replace aluminum-PVC laminates in moisture-sensitive API packaging. EMA stability testing protocols favor silicone's inert chemistry for long-dated drug formulations.
- PVDC Coated:Chlorinated polymer barriers serve industrial corrosion-wrap segments where oxygen transmission precision outweighs sustainability premiums.
- Wax Coated:Petroleum-derived paraffin and microcrystalline wax formulations face REACH restrictions on food contact applications in Western Europe.
Today's leader: Polyethylene Coated. Tomorrow's challenger: Silicone Coated.
Application:
Application mix reflects divergent margin pools, with pharmaceutical and food channels commanding formulation premiums over industrial commodity grades.
- Food Packaging:Grease-resistant kraft papers with bio-polymer or mineral barriers protect protein, bakery, and ready-to-eat segments. FSSAI compliance requirements for Indian spice exports are redirecting converter R&D toward moisture-resistant fiber solutions that replace plastic pouches in tropical climates.
- Pharmaceutical Packaging:Cold-form blister liners and sachet materials demand batch-level migration documentation and EMA notification compliance. German hospital systems now require coating chemistry transparency as a contract precondition, consolidating procurement around certified barrier suppliers.
- Personal Care Products:Aroma barrier papers protect fragrance integrity in premium cosmetic sachets and wipes.
- Industrial Uses:VCI papers and corrosion-wrap grades serve metal protection applications with less stringent sustainability requirements.
Food Packaging commands current volume. Pharmaceutical Packaging offers the steepest expansion trajectory through ESG-mandated healthcare procurement.
Substrate:
Substrate selection determines coating adhesion, caliper consistency, and end-of-life recyclability across European fiber recovery systems.
- Paperboard:Bleached and unbleached folding boxboard grades provide dimensional stability for high-speed coating lines. Mondi Group's integrated Central European mills control substrate porosity and surface chemistry to optimize polyethylene lamination bond strength.
- Kraft Paper:Unbleached virgin and recycled kraft grades serve grease-resistant food wrap and industrial bag applications. Sappi Limited engineers specialized kraft grades with controlled fiber orientation for protein packaging in South African and European markets.
- Label Stock:One-side coated woodfree papers accept silicone barrier layers for pressure-sensitive adhesive applications.
- Specialty Papers:Glassine, parchment, and synthetic fiber blends serve niche pharmaceutical and electronics protection segments.
Paperboard dominates coating line throughput. Kraft Paper is gaining share fastest in plastic-replacement food service applications.
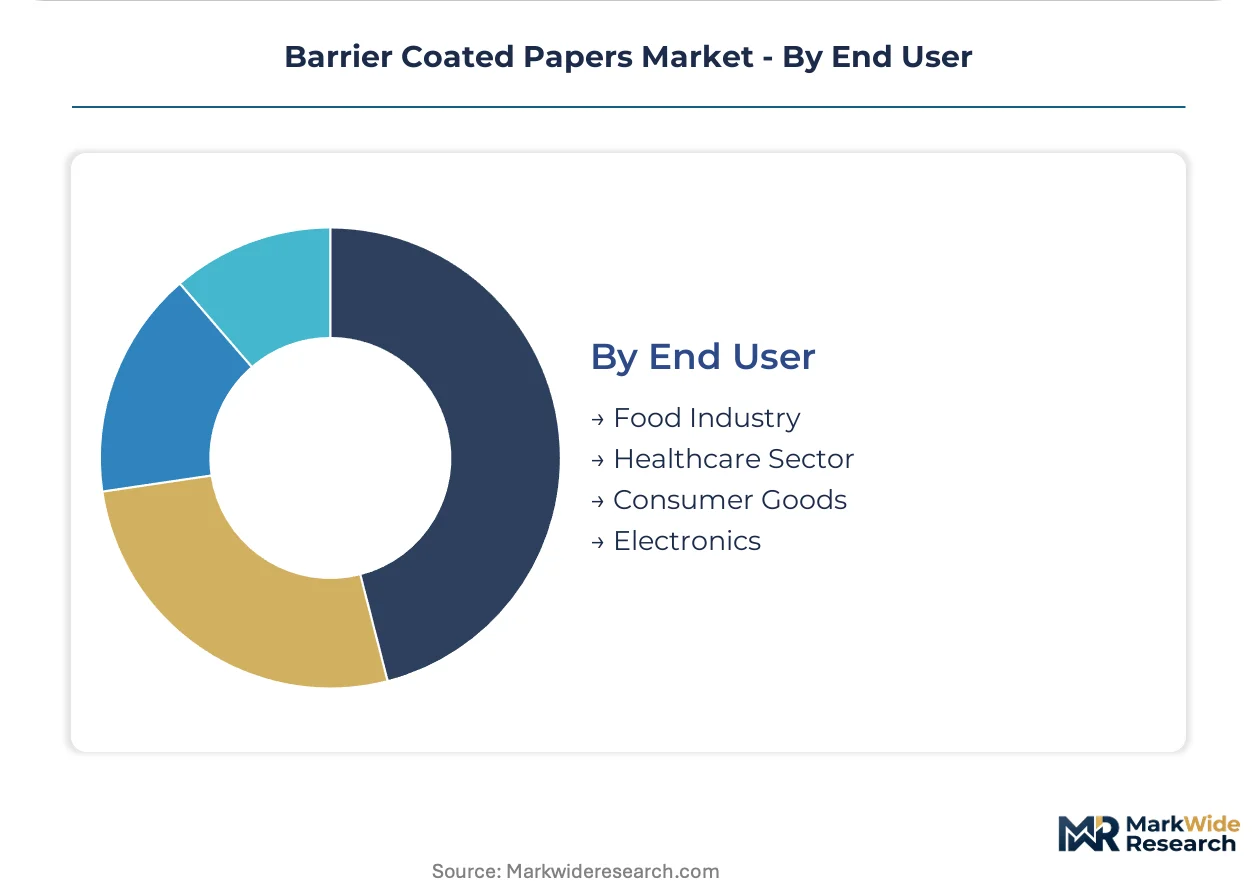
End User:
End-user procurement patterns split between compliance-driven healthcare systems and cost-sensitive food service distributors.
- Food Industry:Ready-meal brands, quick-service chains, and grocery private labels specify barrier papers meeting EU Green Deal packaging waste directives. California's extended producer responsibility laws are mandating fiber-based alternatives for brands serving North American healthcare and consumer goods channels.
- Healthcare Sector:Hospital pharmacies and pharmaceutical manufacturers prioritize batch-level migration compliance and ESG disclosure over unit cost. Swissmedic and German hospital group purchasing organizations are consolidating vendor panels around certified suppliers.
- Consumer Goods:Electronics and appliance manufacturers use barrier papers for corrosion protection and premium unboxing experiences.
- Electronics:Moisture barrier bags and VCI papers protect components during global supply chain transit.
Food Industry anchors current demand. Healthcare Sector offers the most defensible margin structure through regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating chemist expertise clusters in Germany, Switzerland, and the United States, anchoring regional R&D velocity and pilot-scale validation capacity for bio-barrier formulations.
Germany
Water-based coating line deployments in Baden-Württemberg and Bavaria outpace regional peers, serving Central European food brands with heat-seal compatible fiber solutions. REACH restrictions on perfluorinated chemistry force reformulation investments across converter operations. The Stuttgart-Munich corridor hosts integrated pulp-to-paperboard mills controlling substrate porosity for polyethylene lamination bond strength.
United States
California and New York state-level extended producer responsibility laws mandate fiber-based alternatives in healthcare and consumer goods channels. FDA food contact notification pathways extend commercialization cycles for novel bio-barrier chemistries. The Midwest paperboard belt around Wisconsin and Michigan maintains legacy polyethylene coating capacity for quick-service restaurant supply chains.
Switzerland
Swissmedic and hospital group purchasing organizations consolidate vendor panels around certified barrier suppliers with batch-level migration documentation. Healthcare procurement teams require coating chemistry transparency as contract preconditions. The Basel-Zurich corridor anchors pharmaceutical blister packaging demand for silicone coated papers replacing aluminum-PVC laminates.
India
FSSAI compliance requirements for moisture-resistant spice and ready-to-eat exports create demand for grease-resistant kraft grades replacing plastic pouches. Tropical climate conditions stress-test barrier performance in transit. The Maharashtra-Gujarat industrial corridor hosts converter investments targeting Middle East and African export markets.
Finland
Integrated pulp-to-paperboard operations control coating substrate quality through captive fiber sourcing certified under forest stewardship protocols. Renewable fiber availability supports bio-polymer barrier coating development. The Tampere region concentrates specialized kraft paper engineering for protein packaging applications.
Barrier Coated Papers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across coating chemistry and substrate integration vectors. Market structure tilts toward consolidation among integrated pulp-to-paperboard operators with captive coating lines, while regional converters fragment across application-specific niches. Three archetypes dominate: integrated fiber-coating conglomerates, specialized barrier technology licensors, and regional packaging converters. Competitive moves center on backward integration into substrate supply and strategic partnerships with bio-polymer developers to secure heat-seal performance parity.
Within the integrated conglomerate tier, Mondi Group and Stora Enso Oyj exemplify operations spanning pulp sourcing through finished barrier grades. Mondi Group anchors Central European production clusters with controlled substrate porosity for coating optimization. Stora Enso Oyj represents Nordic renewable fiber sourcing certified under forest stewardship protocols. Sappi Limited occupies a position among specialized kraft paper engineers targeting grease-resistant protein packaging in South African and European markets.
| Leading Market Players |
|---|
| International Paper |
| Mondi Group |
| Stora Enso Oyj |
| Sappi Limited |
| Ahlstrom-Munksjö Oyj |
| Cascades Inc. |
| Gascogne Group |
| Schweitzer-Mauduit International |
| Domtar Corporation |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging waste directives gate qualified supply access for converters serving European food brands, with REACH-compliant coating chemistries commanding premium-tier pricing against legacy petroleum-derived alternatives. Buyers seeking batch-level migration documentation and forest stewardship certification face contracted supplier panels with limited spot-market availability.
Pricing Analysis
Coating services split between bundled substrate-plus-barrier contracts and unbundled toll-coating arrangements for independent converters. Three-tier pricing structure across premium, standard, and economy levels separates silicone coated pharmaceutical grades from polyethylene food packaging and wax-coated industrial wraps. Cost compression in standard-tier polyethylene runs through bio-polymer substitution investments and downgauging pressures. Food service distributors exhibit highest price sensitivity, while Swiss and German hospital systems prioritize chemistry transparency over unit economics.
Supply Chain Analysis
Freight cost volatility from pulp sourcing in Finland and Sweden to coating operations in Germany compresses margin pools for non-integrated converters. Raw material flows draw from Nordic bleached kraft pulp, Saudi petrochemical feedstocks for polyethylene, and Chinese chlorinated polymer intermediates for PVDC grades. Single-source vulnerability concentrates in platinum-cured silicone precursors anchored in German chemical manufacturing clusters. Distribution runs through converter-direct relationships with multinational food brands and pharmaceutical group purchasing organizations, bypassing traditional paper merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate between German coating line investments facing REACH compliance costs and Indian converter expansions serving FSSAI-regulated export markets with lower regulatory overhead.
For Market Incumbents: Deepen captive pulp supply control through Nordic fiber sourcing partnerships that secure substrate porosity consistency for barrier optimization. Add water-based coating capacity in Baden-Württemberg to defend position against bio-polymer challengers. Accelerate EFSA notification pathways for mineral-bio hybrid formulations before coating chemist retirements constrain R&D velocity. For New Entrants and Emerging Players: Enter via FSSAI-compliant grease-resistant kraft grades targeting Maharashtra-Gujarat spice export corridors, the most penetrable segment given tropical climate stress-testing requirements. Pursue toll-coating partnerships with established paperboard mills rather than greenfield coating line investments. Qualify for California extended producer responsibility preferred supplier lists through batch-level migration documentation capabilities. For Investors and Strategic Acquirers: Roll-up economics work for regional barrier converters because coating chemist expertise scarcity prevents organic R&D scaling at sub-scale operations. Target mid-cap specialists with captive water-based lines and existing pharmaceutical customer relationships. Watch ECHA substance evaluation timelines for perfluorinated chemistry as the inflection signal determining stranded asset risk in legacy wax coating portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic fiber sourcing secures substrate quality for coating bond optimization. |
| Water-Based Coating Line Deployment | Baden-Württemberg investments serve REACH-compliant ready-meal packaging demand. |
| Mineral-Bio Hybrid Formulation Development | Kaolin-chitosan composites unlock pharmaceutical blister liner substitution opportunities. |
| FSSAI Export Certification Investment | Maharashtra-Gujarat positioning captures Indian spice packaging replacement demand. |
| Healthcare Procurement Panel Consolidation | Swissmedic compliance transparency secures multi-year supply agreements. |
Methodological Framework
Bottom-up food packaging and pharmaceutical demand modeling reconciled against top-down pulp-to-paperboard capacity tracking forms the analytical core. Primary interviews with coating line operators, converter procurement leads, pharmaceutical packaging engineers, and EU regulatory affairs specialists combined with secondary validation from ECHA substance evaluations, FDA food contact notifications, FSSAI export compliance databases, and forest stewardship certification registries. Trade flow analysis of Nordic kraft pulp exports and German polyethylene coating equipment deployments triangulated supply-side constraints.
Historical coating line investment patterns and barrier chemistry substitution rates informed projection frameworks across the modeling period. Segmentation dimensions include coating chemistry type, substrate grade tier, end-use application, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating EU Green Deal implementation pacing and pharmaceutical ESG procurement adoption curves. Bio-polymer heat-seal performance parity timelines and EFSA migration testing completion rates served as industry-specific forecast inputs.
Inputs from EMA stability testing protocols and German hospital group purchasing organization contract disclosures were available through the study window; gaps in pilot-scale bio-barrier validation data introduce uncertainty bands around silicone substitution trajectories. Forecasts reflect documented assumptions regarding REACH enforcement consistency and FSSAI export inspection intensity. A model refresh is warranted upon material change in ECHA perfluorinated substance restriction timelines or California extended producer responsibility implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Non Heat Sealable Film Market