
 Non Heat Sealable Film Market | 2026-2036
Non Heat Sealable Film Market Size, Share, and Industry Trends Forecast 2026-2036
Non Heat Sealable Film Market Analytics
Asian petrochemical producers is rebalancing regional supply of biaxially oriented polypropylene and polyester substrates. Amcor Plc leverages its integrated film-to-package operations across multiple continents. Toray Plastics Inc. anchors North American capacity for high-clarity polyester grades. SRF Limited dominates specialty film exports from India to Middle Eastern and African converters.
Non heat sealable film denotes polymer substrates—typically oriented polypropylene, polyester, or cast polyethylene—that lack a thermoplastic sealant layer and therefore require adhesive, mechanical, or solvent-based joining methods in finished packages; these films typically exhibit tensile strengths exceeding 150 MPa and oxygen transmission rates below 2 cc/m²/day, serving primarily as barrier layers, print webs, or structural plies in multi-laminate constructions. Polypropylene occupies the largest volume share due to its cost-performance ratio in snack and confectionery lidding, while polyester commands premium positioning in pharmaceutical blister alternatives where dimensional stability at elevated temperatures proves critical. Nylon retains niche dominance in industrial vacuum bagging and agricultural silage applications where puncture resistance outweighs seal functionality requirements.
The US FDA maintains material contact compliance standards under 21 CFR 177.1520 for olefin films, while the EU REACH framework restricts certain phthalate plasticizers in film formulations destined for consumer packaging. China's SAMR enforces GB standards for food-contact plastics that affect import eligibility of non-domestic film rolls. Stakeholders must monitor evolving extended producer responsibility schemes that could reclassify non-heat-sealable multilayer structures as non-recyclable, forcing substrate redesign or alternative bonding chemistry investments.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing substrate redesign across European converting operations, as converters face mandatory material recovery targets that reclassify multilayer non-heat-sealable structures as non-recyclable under emerging extended producer responsibility frameworks.
Growth Catalysts
- Pharmaceutical blister alternatives:Polyester films with dimensional stability above 150°C are displacing PVC in European pharmaceutical packaging as EMA safety guidelines tighten.
- REACH phthalate restrictions:The EU framework restricts specific plasticizers in film formulations, accelerating migration toward olefin-based barrier substrates compliant with 21 CFR 177.1520.
- Central European R&D clusters:Germany's flexible packaging innovation hubs in Baden-Württemberg and Bavaria concentrate technical expertise serving brand owners across Austria, Switzerland, and Poland.
Market Restraints
- Propylene monomer volatility:Biaxially oriented polypropylene margins compress when naphtha-cracker feedstock costs spike, particularly affecting Asian petrochemical supply.
- Adhesive bonding chemistry:Solvent-based lamination faces technical limitations in oxygen transmission rate performance below 0.5 cc/m²/day without multilayer complexity.
- Mechanical joining substitution:Ultrasonic welding and laser sealing technologies threaten non-heat-sealable film relevance in lidding applications where hermeticity requirements intensify.
Strategic Opportunities
- Indian export corridors:Specialty film producers in Gujarat and Maharashtra capture Middle Eastern and African converter demand as regional petrochemical capacity lags.
- EU Green Deal alignment:The circular economy action plan creates regulatory tailwinds for mono-material barrier designs that simplify mechanical recycling streams.
- Agricultural silage expansion:Nylon vacuum bagging films penetrate Brazilian and Argentine markets where puncture-resistant barrier properties outweigh seal functionality requirements.
Industry Challenges
- Multi-laminate delamination expertise:Converters face skill gaps in adhesive selection and curing protocols for oriented polypropylene-to-polyester bonding without heat activation.
- GB standard compliance timelines:China's SAMR food-contact certification requires 12-18 month validation cycles that delay import eligibility for non-domestic film rolls.
- Legacy equipment retrofitting:Solvent-based coating lines require capex-intensive emission control upgrades to meet MEE environmental enforcement in coastal Chinese provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non Heat Sealable Film Market |
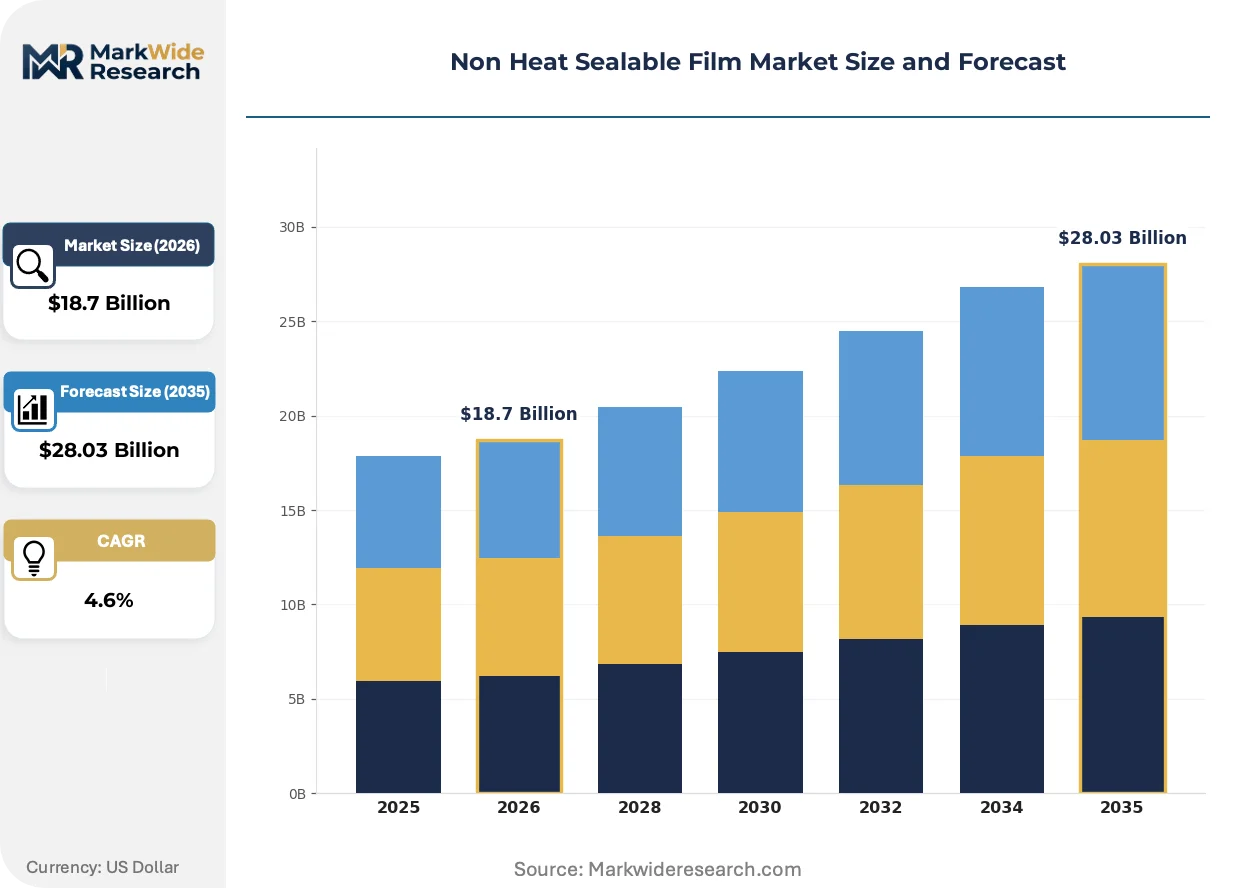
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Polyethylene, Nylon Application: Packaging, Medical, Agriculture, Industrial End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | Amcor Plc, Cosmo Films Ltd., Max Speciality Films, Toray Plastics Inc., SRF Limited, Jindal Films, Berry Global Inc., Sealed Air, Web Plastics Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non Heat Sealable Film Market Evolving Landscape
Material science advances and regulatory stringency are compressing development cycles for barrier substrates, while procurement patterns favor suppliers with integrated film-to-package capabilities and verified circularity credentials.
Water-based barrier coatings is electrifying the technical roadmap for oriented polypropylene films, enabling oxygen transmission rates below 1.5 cc/m²/day without ethylene vinyl alcohol coextrusion. Snack and confectionery brand owners in Germany and the Netherlands are piloting these substrates at commercial scale during 2024-2025 production windows. The technology is electrifying competitive positioning among European converters by eliminating solvent recovery infrastructure and reducing regulatory exposure under ECHA workplace exposure limits.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer-based grease barriers from food-contact films across EU member states. The industrial consequence forces substrate engineers to deploy clay-based nanocomposite or bio-wax alternatives with comparable oil resistance at 40-60% higher unit coating costs. Pharmaceutical and fresh-food lidding segments in France, Italy, and Spain are responding fastest, with ANSM-aligned converters already qualifying PFAS-free alternatives ahead of 2025 enforcement deadlines.
Direct mill-to-brand procurement contracts are consolidating converter relationships as multinational food processors internalize substrate specification authority previously held by regional packaging distributors. This channel compression displaces traditional film broker networks in North American and Western European markets. The pattern is most visible in German dairy and ready-meal segments, where Aldi and Lidl supplier codes now mandate single-source accountability for barrier layer performance.
Non Heat Sealable Film Market Segmentation
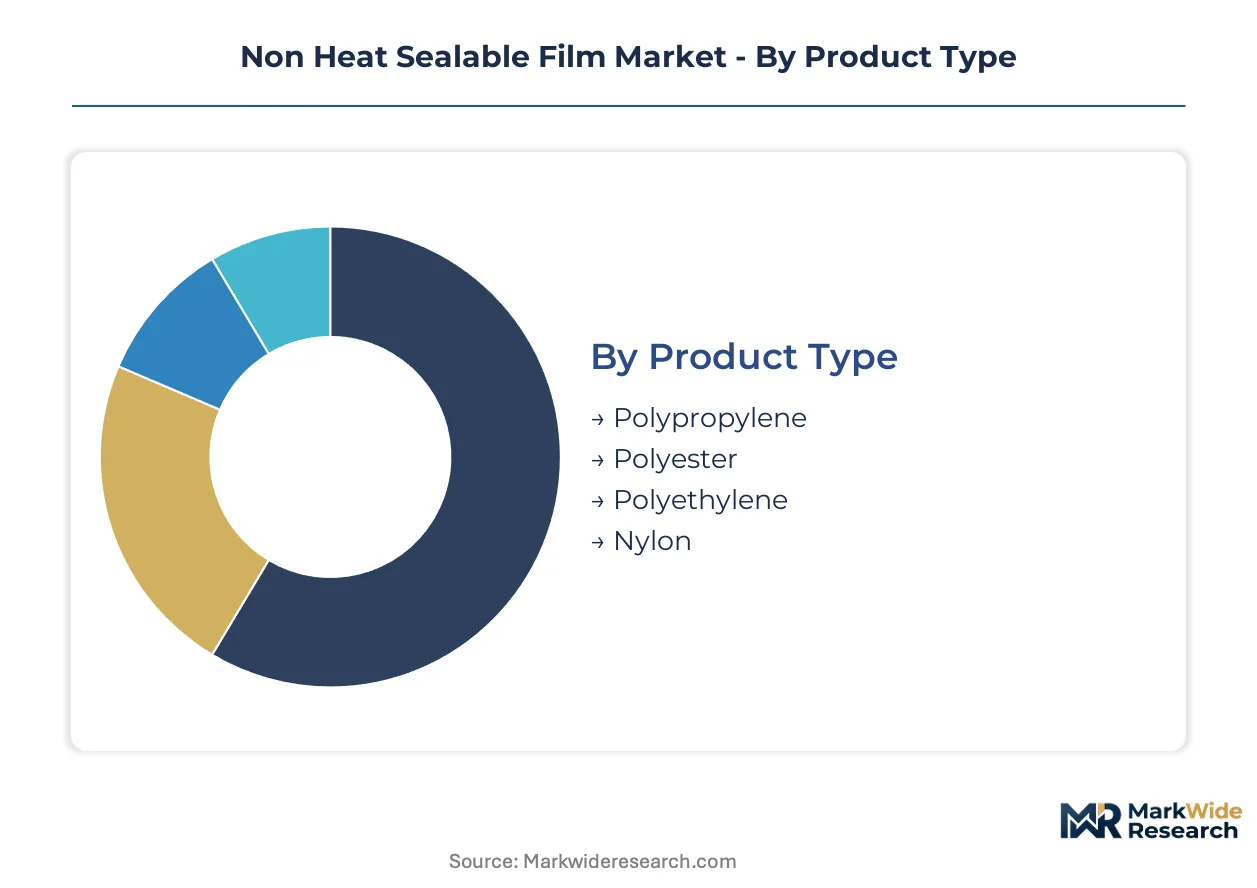
Substrate specification dictates bonding chemistry requirements, which in turn determines converter equipment investments and regulatory compliance pathways. Each segmentation axis reveals distinct procurement patterns and technical capability thresholds that separate commodity suppliers from specialty film partners.
Product Type:
Material composition defines tensile performance, barrier specifications, and thermal stability thresholds across end-use applications.
- Polypropylene:Biaxially oriented grades deliver tensile strength above 150 MPa with oxygen transmission below 2 cc/m²/day. Snack and confectionery lidding in Germany concentrates demand where cost-performance ratios dominate procurement evaluations.
- Polyester:High-clarity substrates maintain dimensional stability above 150°C, enabling pharmaceutical blister alternatives as EMA guidelines tighten PVC displacement timelines. European converters in Baden-Württemberg qualify these grades for thermoformable barrier applications.
- Polyethylene:Cast grades serve industrial vacuum bagging and protective interleaving where moderate barrier performance suffices. Agricultural silage applications in Brazil leverage puncture resistance without hermetic seal requirements.
- Nylon:Polyamide structures dominate vacuum bagging for composite manufacturing and silage preservation where puncture resistance outweighs seal functionality. Brazilian and Argentine agricultural markets absorb specialty grades from Indian exporters.
Polypropylene leads on scale; Polyester leads on momentum.
Application:
Functional requirements across use cases separate commodity film distributors from technical substrate partners with adhesive lamination expertise.
- Packaging:Lidding, barrier webs, and print substrates require oxygen transmission below 1.5 cc/m²/day for extended shelf-life applications. German dairy and ready-meal processors mandate single-source accountability for barrier performance under Aldi and Lidl supplier codes.
- Medical:Pharmaceutical blister alternatives and sterile barrier systems demand compliance with FDA 21 CFR 177.1520 and EMA stability guidelines. European converters accelerate PFAS-free qualification ahead of REACH Annex XVII enforcement.
- Agriculture:Silage preservation and vacuum bagging films prioritize puncture resistance over seal functionality. Brazilian market expansion drives nylon substrate demand where regional petrochemical capacity lags.
- Industrial:Protective interleaving, release liners, and composite manufacturing aids specify dimensional stability without heat-activation requirements. Asian petrochemical producers rebalance regional supply of oriented substrates for these applications.
Packaging commands volume concentration; Medical is climbing the fastest on regulatory displacement.
End User:
Procurement authority patterns differentiate between brand-direct specifications and distributor-mediated substrate selection.
- Food & Beverage:Multinational processors internalize substrate specification authority previously held by regional packaging distributors. Direct mill-to-brand contracts consolidate converter relationships in North American and Western European markets.
- Pharmaceuticals:EMA stability guidelines and FDA material contact standards drive polyester adoption for PVC-free blister alternatives. ANSM-aligned converters in France qualify PFAS-free barrier substrates ahead of enforcement deadlines.
- Cosmetics:Premium positioning demands high-clarity print webs with grease resistance properties. Clay-based nanocomposite coatings replace fluoropolymer barriers under REACH restrictions at elevated unit costs.
- Electronics:Protective interleaving and static-dissipative applications specify controlled surface energy without heat-seal functionality. Japanese electronics manufacturers source specialty grades through integrated film-to-package suppliers.
Food & Beverage anchors procurement volume; Pharmaceuticals shows steepest expansion trajectory on regulatory displacement.
Distribution Channel:
Channel structure reflects technical complexity of substrate specification and converter relationship depth.
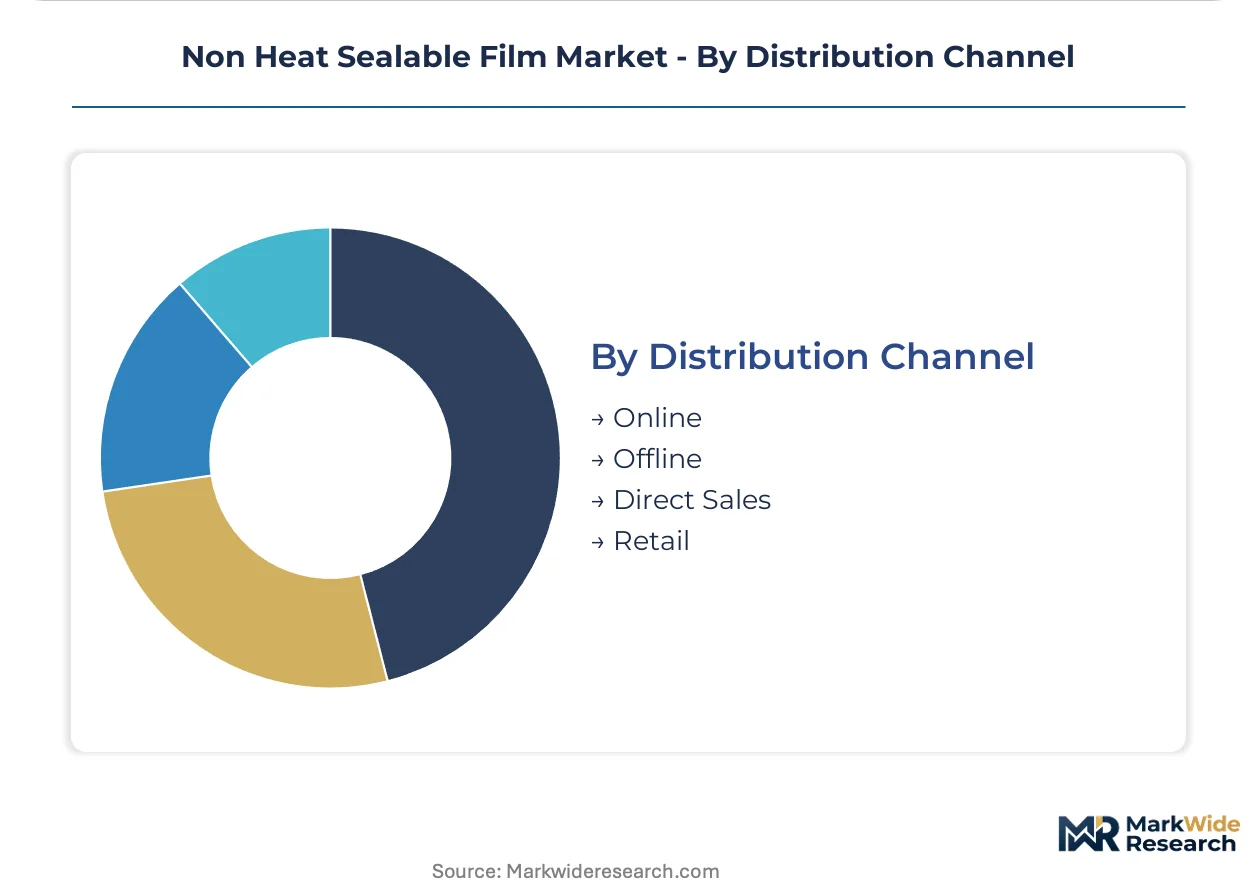
- Online:Digital procurement platforms serve commodity grades with standardized specifications and rapid replenishment cycles. Small and mid-sized converters in India leverage e-commerce channels for spot purchases.
- Offline:Traditional film broker networks retain relevance in specialty grades requiring technical consultation. Relationship-based distribution persists in pharmaceutical and medical applications where validation documentation complexity exceeds platform capabilities.
- Direct Sales:Mill-to-brand contracts eliminate intermediary margins for high-volume processors with internalized specification authority. German retail supply chains mandate single-source accountability through direct procurement frameworks.
- Retail:Small-lot availability through distribution warehouses serves prototyping and short-run converting operations. Regional packaging distributors maintain inventory positions for emergency replenishment.
Direct Sales gains share fastest on channel compression; Offline retains defensive position in validation-intensive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting non-heat-sealable film production toward jurisdictions with lower compliance costs and established petrochemical infrastructure. Converters in higher-regulation markets increasingly source substrates from specialized exporters rather than maintaining captive capacity.
Germany
Baden-Württemberg and Bavaria host Europe's densest flexible packaging R&D clusters, serving brand owners across Austria, Switzerland, and Poland. The EU Packaging and Packaging Waste Regulation forces substrate redesign as multilayer structures face reclassification under extended producer responsibility frameworks. Stuttgart-based converters pilot water-based barrier coatings for oriented polypropylene to eliminate solvent recovery infrastructure.
China
MEE environmental enforcement in coastal provinces drives solvent-based coating line retrofits costing millions per facility. GB standards administered by SAMR impose 12-18 month food-contact certification cycles that delay import eligibility for non-domestic film rolls. Yangtze River Delta petrochemical producers rebalance regional supply of biaxially oriented substrates to serve domestic converting demand.
India
Gujarat and Maharashtra specialty film exporters capture Middle Eastern and African converter demand as regional petrochemical capacity lags. BIS compliance requirements for food-contact materials create technical barriers for smaller domestic producers. Mumbai-based suppliers dominate nylon vacuum bagging film shipments to Brazilian agricultural markets.
United States
FDA 21 CFR 177.1520 standards for olefin films shape procurement specifications across pharmaceutical and food packaging segments. The Southeast and Midwest concentrate thermoforming and lidding converter operations near major brand owner headquarters. Direct mill-to-brand procurement contracts displace traditional film broker networks in dairy and ready-meal segments.
Brazil
Agricultural silage preservation drives nylon substrate demand where puncture resistance outweighs seal functionality requirements. ANVISA pharmaceutical packaging regulations accelerate polyester adoption for blister alternatives displacing PVC. São Paulo-state converters source specialty grades from Indian exporters to circumvent regional petrochemical capacity constraints.
Non Heat Sealable Film Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue water-based barrier coatings and mono-material recyclable designs. The vendor base stratifies across integrated multinational film-to-package operators, regional petrochemical-backed substrate specialists, and export-focused national champions. Three archetypes dominate: integrated converters controlling specification authority, substrate-only suppliers serving broker-mediated channels, and specialty film exporters leveraging cost-advantaged manufacturing bases. Competitive moves concentrate on backward integration into resin production and geographic expansion through distribution partnerships.
Among integrated packaging conglomerates, Amcor Plc exemplifies the film-to-package archetype with multi-continental operations. Toray Plastics Inc. anchors North American positioning for high-performance substrate grades. SRF Limited represents the export-specialist model, dominating specialty film shipments from India to Middle Eastern and African markets. These three occupy distinct competitive spaces without direct overlap in core capabilities.
| Leading Market Players |
|---|
| Amcor Plc |
| Cosmo Films Ltd. |
| Max Speciality Films |
| Toray Plastics Inc. |
| SRF Limited |
| Jindal Films |
| Berry Global Inc. |
| Sealed Air |
| Web Plastics Company |
| Others |
Value Network & Pricing Analysis
Direct mill-to-brand procurement mandates from German retail supply chains are compressing intermediary margins and forcing substrate suppliers to absorb certification costs or cede volume to integrated competitors with captive film-to-package operations.
Pricing Analysis
Distributor margin compression dominates the channel structure as Aldi and Lidl supplier codes eliminate traditional film broker networks. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and industrial commodity levels separates buyers by validation documentation burden. Cost compression in standard-grade oriented polypropylene is intensifying because Asian petrochemical producers are rebalancing regional supply toward domestic converting demand. Small and mid-sized converters exhibit highest price sensitivity, while pharmaceutical blister alternative specifications command premium positioning with limited negotiation leverage.
Supply Chain Analysis
GB standard compliance timelines administered by SAMR create 12-18 month gating periods that filter non-domestic film rolls from Chinese food-contact applications. Manufacturing concentrates in Germany, India, and China, with Gujarat and Maharashtra specialty film exporters feeding Middle Eastern and African converter demand. Raw material supply draws from naphtha-cracker propylene monomer, biaxially oriented substrate equipment, and water-based barrier coating chemistry. Single-source vulnerability persists in high-clarity polyester grades where Toray Plastics anchors North American capacity. Distribution runs through direct sales contracts for high-volume processors and offline broker networks for validation-intensive pharmaceutical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical blister alternative specifications represent a late-cycle quality story as EMA guidelines displace PVC and converters absorb 40-60% coating cost premiums for PFAS-free barrier substrates.
For Market Incumbents: Anchor defensive positioning through backward integration into water-based barrier coating chemistry and mono-material recyclable substrate R&D. Ultrasonic welding and laser sealing technologies threaten non-heat-sealable film relevance in lidding applications; incumbents must deepen specification authority through direct mill-to-brand contracts with German retail supply chains. For New Entrants and Emerging Players: Capture white-space in Brazilian and Argentine agricultural silage markets where nylon vacuum bagging demand outpaces regional petrochemical capacity. Indian export corridors offer the most penetrable geography; entrants should pursue specialty film qualification for Middle Eastern and African converters with relationship-based technical consultation as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated film-to-package operators controlling specification authority across multiple continents. Long-term viability hinges on circular economy alignment and verified mono-material recyclability credentials. Watch water-based barrier coating commercialization rates at Stuttgart-based pilot facilities as the inflection indicator for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive propylene monomer supply insulates margins from naphtha-cracker feedstock volatility. |
| Water-Based Barrier Coating Scale-Up | Elimination of solvent recovery infrastructure reduces regulatory exposure under ECHA workplace limits. |
| PFAS-Free Substrate Qualification | ANSM-aligned converters in France gain first-mover positioning ahead of REACH Annex XVII enforcement. |
| Direct Mill-to-Brand Contracting | Single-source accountability mandates from Aldi and Lidl displace traditional film broker networks. |
| Indian Export Corridor Expansion | Mumbai-based suppliers capture Brazilian agricultural demand circumventing regional petrochemical constraints. |
Research Methodology
Direct dialogue with flexible packaging R&D directors, converter procurement leads, brand owner specification engineers, and regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, FDA 21 CFR 177.1520 compliance documentation, EMA stability guideline submissions, and customs trade data for oriented substrate flows. Bottom-up volume estimates triangulated against top-down petrochemical capacity assessments.
Segment-level outputs across substrate type, application, end-use, and distribution channel were generated through the projection horizon. The analytical framework incorporated oxygen transmission rate performance tiers, adhesive bonding chemistry requirements, and certification documentation burden as industry-specific forecast inputs. CAGRs were derived from regression analysis against historical procurement patterns and regulatory displacement timelines.
Propylene monomer volatility, REACH restriction enforcement pace, and mechanical joining technology substitution are the dominant revision risks. Deviation in water-based barrier coating commercialization scale would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Insulation Film Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Biodegradable Plastic Films Market