
 Barrier Tube Packaging Market | 2026-2036
Barrier Tube Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Tube Packaging Market Outlook
Buyer concentration among pharmaceutical contract manufacturers is rebalancing as specialty skincare startups fragment the cosmetics demand pool. Albéa Group leverages its European manufacturing footprint to serve both segments. Essel Propack Limited anchors South Asian supply through dedicated laminate tube capacity. Hoffmann Neopac AG differentiates via precision dosing formats for pharmaceutical clients.
Barrier tube packaging combines multilayer coextruded or laminated structures—typically incorporating ethylene vinyl alcohol or aluminum oxide barrier layers—to prevent oxygen, moisture, and UV ingress while maintaining squeezeability. These structures protect oxygen-sensitive pharmaceuticals, retort-processed foods, and volatile cosmetic actives from degradation through shelf life. Laminated tubes command premium positioning in pharmaceutical applications where EMA migration limits apply most stringently. Plastic tubes dominate volume in cosmetics through cost-scaled production, though aluminum tubes sustain share in food paste segments requiring complete light and gas impermeability. Composite tubes occupy a narrowing mid-tier as brand owners consolidate specifications toward either full barrier performance or lowest unit cost.
EMA stability testing guidelines, FDA container closure integrity requirements, and REACH Annex XVII substance restrictions collectively elevate material qualification costs and barrier performance thresholds for market access. The EU Packaging and Packaging Waste Regulation sharpens recyclability mandates, pushing converters toward mono-material barrier structures or validated recycling streams. Stakeholders must monitor regulatory divergence between European chemical migration limits and FDA's emerging human factors requirements for elderly-accessible tube closures.
Market Dynamics
EMA's tightened migration limits under its 2023 stability testing guidelines are forcing pharmaceutical brands to abandon commodity tubes and validate high-barrier laminate structures, compressing qualification timelines and elevating converter consolidation around certified European suppliers.
Growth Catalysts
- Oxygen-sensitive biologics:Monoclonal antibody formulations and cell therapies require ethylene vinyl alcohol barrier layers to prevent oxidative degradation through 36-month shelf lives.
- REACH Annex XVII:ECHA's substance restrictions on phthalates and heavy metals in packaging materials are disqualifying conventional tube resins from pharmaceutical applications.
- Retort processing:Food paste manufacturers in Germany and Italy are adopting aluminum oxide-coated plastic tubes to replace metal cans for single-serve convenience formats.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Kuraray and Nippon Gohsei control over 80 percent of global EVOH supply, exposing converters to input cost volatility and allocation risk.
- Multi-layer coextrusion capex:Five- to seven-layer barrier tube lines require 12-18 million euro investments, freezing out mid-tier converters from pharmaceutical qualification.
- Aluminum tube substitution:Food and cosmetic brands seeking complete light and gas impermeability continue specifying collapsible aluminum despite squeezeability trade-offs.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are localizing barrier tube sourcing to serve export pharmaceutical markets.
- Mono-material barrier structures:Polyethylene-based high-barrier formulations compatible with existing recycling streams address EU Packaging and Packaging Waste Regulation mandates.
- Precision dosing formats:Metered-dose pump tubes for topical corticosteroids and hormone therapies command 40-60 percent price premiums over standard squeeze tubes.
Industry Challenges
- Migration testing capacity:EMA-compliant extractables and leachables studies require 6-9 month queues at certified laboratories, delaying product launches.
- Legacy aluminum tube integration:Pharmaceutical filling lines configured for metal tubes face mechanical retrofit costs and validation burdens when switching to plastic barrier alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Tube Packaging Market |
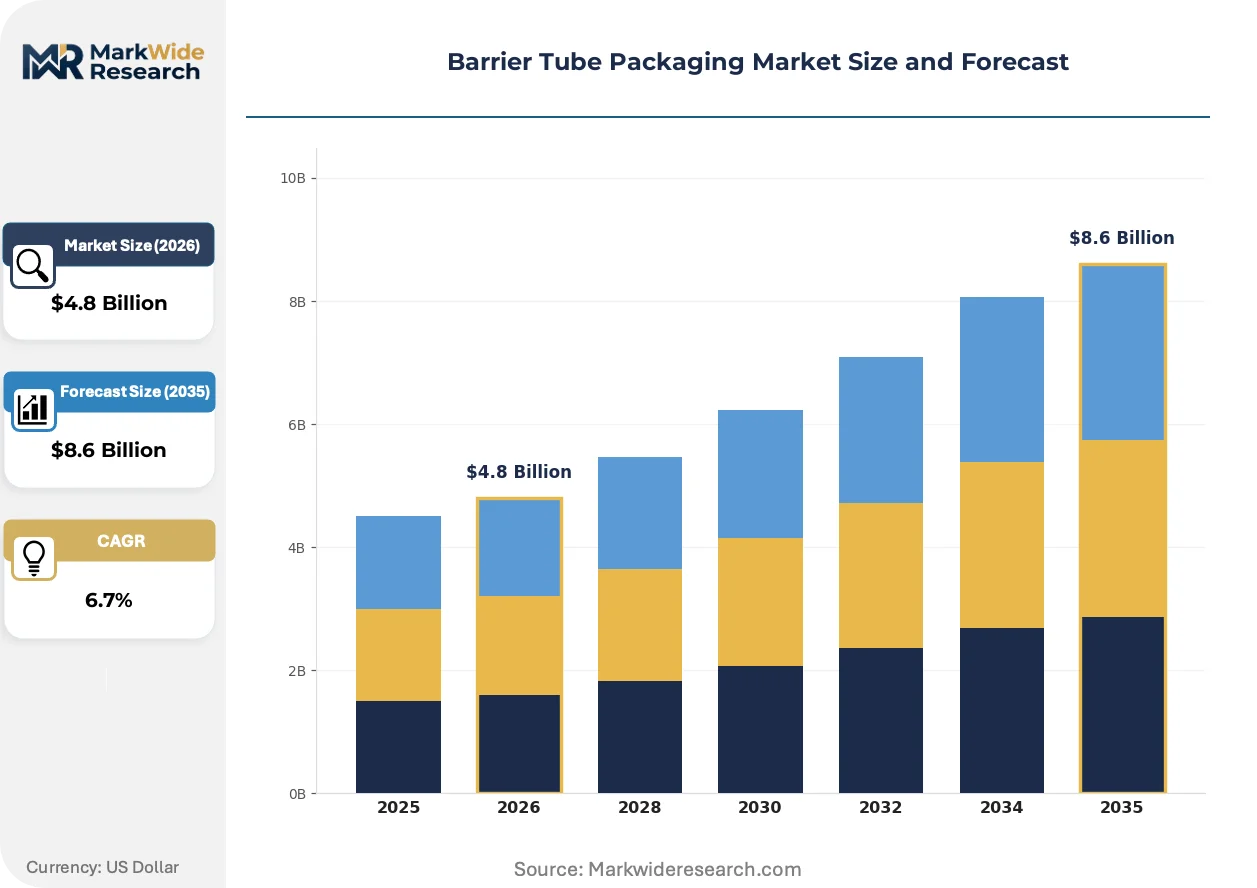
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Tubes, Aluminum Tubes, Laminated Tubes, Composite Tubes End Use Industry: Cosmetics, Food & Beverages, Pharmaceuticals, Household Products Packaging Type: Stand-Up Pouches, Squeeze Tubes, Twist Tubes, Flip Top Tubes Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Albéa Group, Essel Propack Limited, CCL Industries Inc., Montebello Packaging, Hoffmann Neopac AG, Alltub Group, Linhardt GmbH & Co. KG, World Wide Packaging LLC, ALPLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Tube Packaging Market Strategic Shifts
Active and intelligent packaging integration is reshaping how barrier tubes communicate product integrity, while sustainability mandates are compressing material complexity into recyclable mono-polymer structures without sacrificing barrier performance.
Coextruded ethylene vinyl alcohol barrier technology is consolidating pharmaceutical tube specifications around five- to seven-layer structures incorporating tie layers and sealant skins. CDMOs in Germany and Switzerland are mandating EVOH-based tubes for all new oxygen-sensitive formulations. This consolidation is eliminating commodity polyethylene tubes from premium pharmaceutical applications and concentrating converter relationships with EMA-qualified laminate specialists.
EMA's 2023 revision to stability testing guidelines for plastic primary packaging has elevated container closure integrity validation to a gatekeeping requirement. Pharmaceutical sponsors must now submit oxygen transmission rate data and accelerated aging studies for tube-drug combinations. European dermatology and ophthalmology segments are responding by pre-qualifying tube converters before formulation development begins, front-loading packaging decisions into clinical trial design.
Specialty skincare startups are fragmenting cosmetics procurement patterns away from volume-based annual contracts toward small-batch, SKU-flexible arrangements. Indie brands in France and South Korea are sourcing 10,000-50,000 unit runs direct from converter digital storefronts, bypassing traditional distributor networks. This disintermediation is most visible in Seoul's Gangnam beauty cluster, where direct-to-brand tube sourcing compresses lead times from 12 weeks to 4 weeks.
Barrier Tube Packaging Market Segmentation
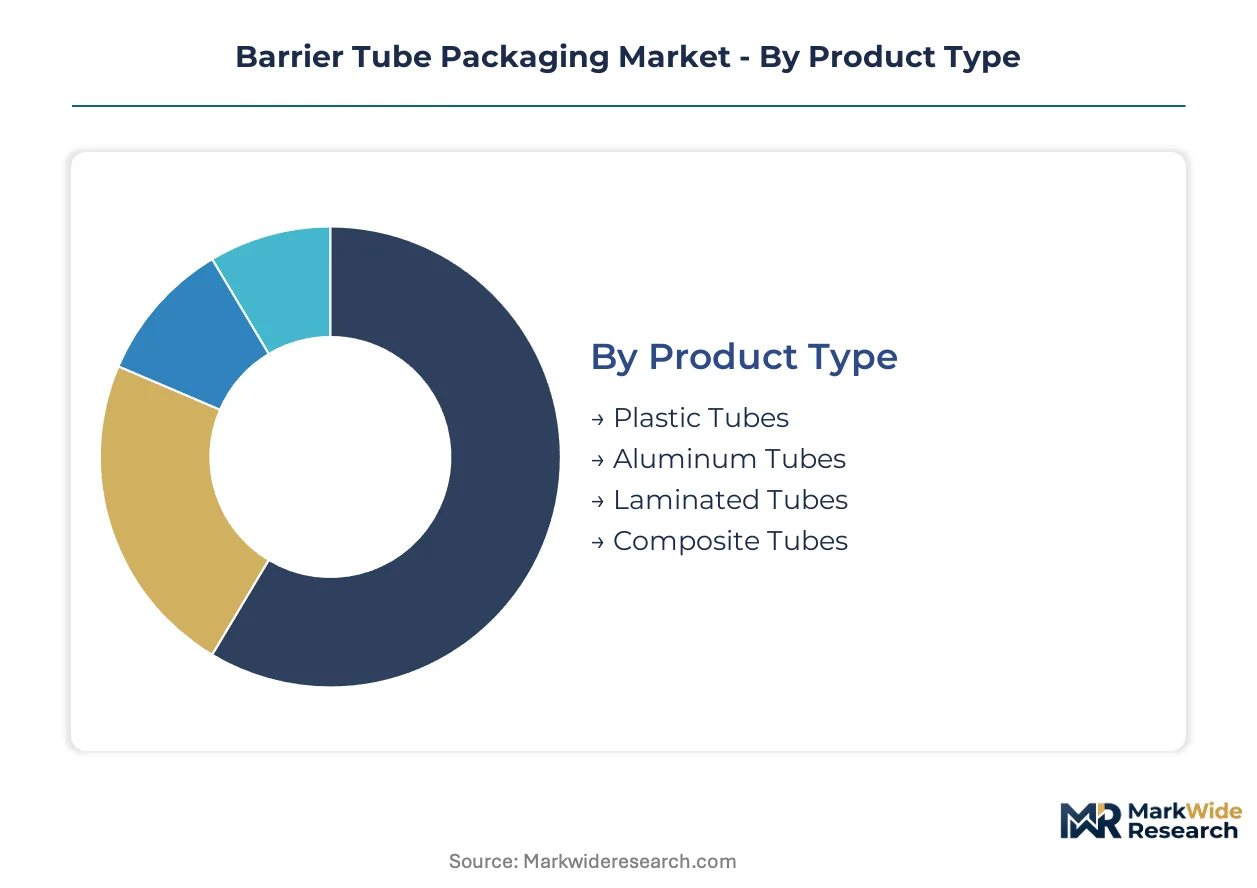
Barrier tube packaging specifications diverge sharply across end-use applications, with pharmaceutical oxygen sensitivity demanding multilayer EVOH structures while cosmetics prioritize squeezeability and printability. Understanding these segment boundaries clarifies why converter capabilities and qualification pathways cluster around specific performance tiers rather than spanning all categories.
Product Type:
Plastic tubes dominate unit volume through cost-scaled production, yet premium positioning concentrates in laminate and aluminum formats where barrier performance commands price multiples.
- Plastic Tubes:Monolayer and coextruded polyethylene or polypropylene structures serve mass-market cosmetics and household products where oxygen ingress tolerance permits commodity specifications. German drugstore chains and South Korean beauty OEMs drive procurement at scale, though REACH Annex XVII substance restrictions are disqualifying conventional resins from pharmaceutical migration limits.
- Laminated Tubes:Five- to seven-layer structures incorporating ethylene vinyl alcohol or aluminum oxide barrier layers prevent oxidative degradation in oxygen-sensitive pharmaceuticals. EMA stability testing guidelines have elevated these to the default specification for monoclonal antibody and cell therapy formulations, concentrating demand with European converters holding extractables and leachables certification.
- Aluminum Tubes:Collapsible metal construction delivers complete light and gas impermeability for food paste retort applications and select pharmaceutical ointments. Italian tomato paste manufacturers and German pharmaceutical formulators sustain demand despite squeezeability trade-offs versus plastic alternatives.
- Composite Tubes:Hybrid structures combining plastic body with aluminum shoulder or foil layer occupy narrowing mid-tier positioning as brand owners consolidate toward full barrier performance or lowest unit cost.
Today's leader: Laminated Tubes. Tomorrow's challenger: Aluminum Tubes.
End Use Industry:
Pharmaceutical qualification timelines and EMA migration limits create the steepest entry barriers, while cosmetics procurement fragments toward SKU-flexible direct sourcing.
- Pharmaceuticals:Oxygen-sensitive biologics and topical corticosteroids require validated container closure integrity under FDA and EMA guidelines. CDMOs in Frankfurt, Ludwigshafen, and Basel pre-qualify converters before formulation development, front-loading packaging decisions into clinical trial design.
- Cosmetics:Specialty skincare startups in Seoul's Gangnam cluster and Parisian indie brands are fragmenting procurement away from volume contracts toward 10,000-50,000 unit direct-to-converter orders. Digital storefronts compress lead times from 12 weeks to 4 weeks.
- Food & Beverages:Retort-processed food pastes in Germany and Italy are adopting aluminum oxide-coated plastic tubes to replace metal cans for single-serve convenience formats. Complete light and gas impermeability remains the critical specification.
- Household Products:Adhesives, sealants, and cleaning formulations tolerate monolayer polyethylene tubes where shelf life sensitivity permits lowest-cost procurement. Volume concentration in mass retail channels sustains commodity converter relationships.
Pharmaceuticals capture the steepest margin tier. Cosmetics are expanding most quickly through startup fragmentation.
Packaging Type:
Closure mechanics and dispensing precision separate premium pharmaceutical positioning from mass-market convenience formats.
- Squeeze Tubes:Standard flexible construction dominates across all end uses through manufacturing simplicity and consumer familiarity. Pharmaceutical metered-dose pump variants command 40-60 percent price premiums for topical corticosteroid and hormone therapy applications.
- Flip Top Tubes:Integrated hinged closure eliminates cap separation and improves single-handed operation for cosmetics and household products. French and German drugstore chains specify this format for travel-size personal care ranges.
- Twist Tubes:Rotating collar or base mechanisms enable precise product dispensing for high-viscosity pharmaceutical ointments and cosmetic balms. Swiss and German precision formulators favor this control.
- Stand-Up Pouches:Alternative flexible format competing for food paste and household product applications requiring larger volume capacity than conventional tubes permit. Retort compatibility varies by barrier layer specification.
Squeeze tubes anchor current volume. Metered-dose pump variants represent the fastest-climbing premium tier.
Distribution Channel:
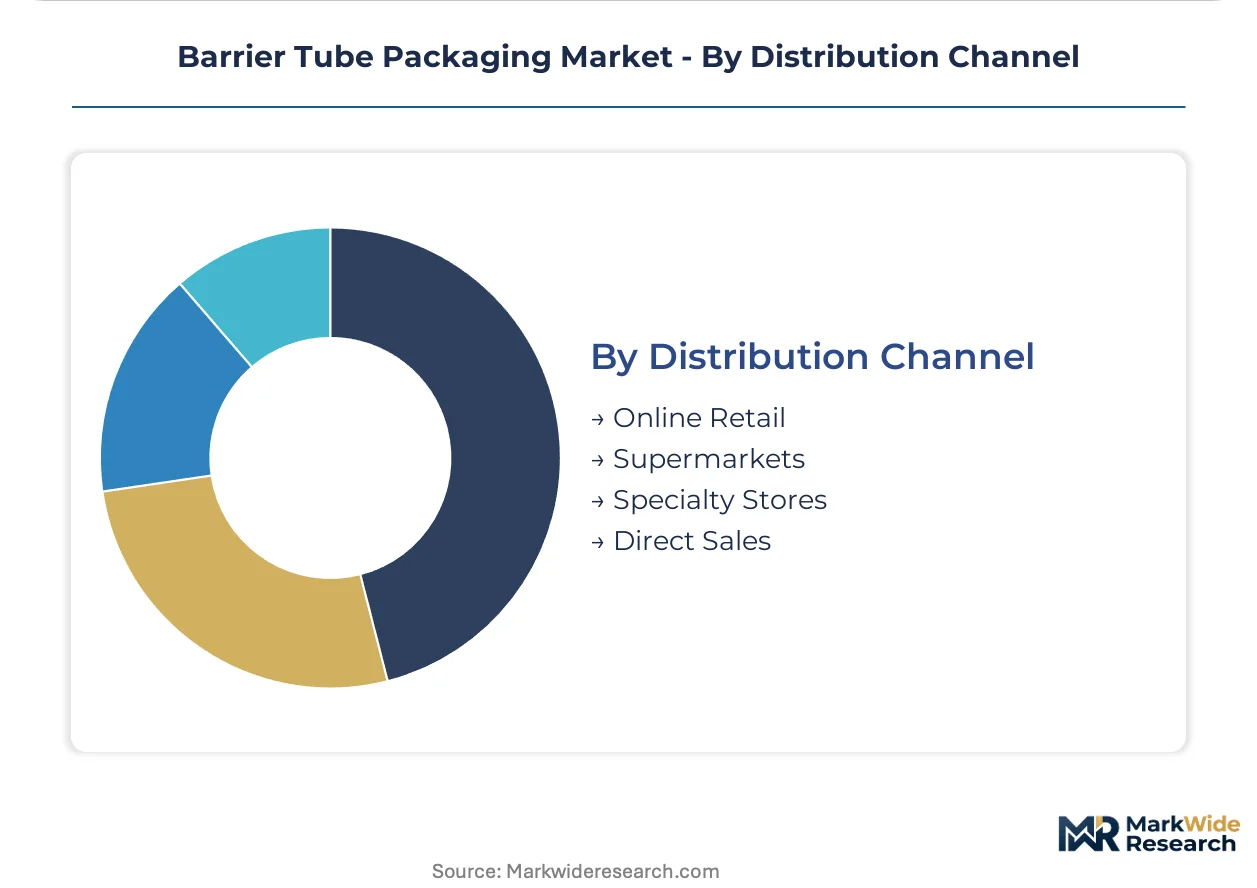
Channel selection tracks end-use concentration, with pharmaceutical direct sales requiring converter qualification depth that general retail cannot support.
- Direct Sales:Pharmaceutical sponsors and cosmetics brand owners source direct from converter for qualification control and lead time compression. EMA-certified European suppliers and Seoul-based digital storefronts both serve this channel.
- Specialty Stores:Premium cosmetics and professional hair care channels in France and South Korea specify custom tube decoration and small-batch flexibility. Indie brand proliferation sustains converter digital platforms.
- Supermarkets:Mass-market cosmetics and household products move through centralized retail procurement with annual volume contracts. German drugstore chains and Italian grocery retailers drive standardization.
- Online Retail:E-commerce fulfillment for cosmetics and household products increasingly specifies ship-ready tube formats with enhanced crush resistance. Direct-to-consumer beauty brands in South Korea lead format experimentation.
Direct sales command the qualification-intensive pharmaceutical tier. Online retail is gaining share fastest through indie brand disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and pharmaceutical packaging engineers concentrate in Germany's Rhine-Main corridor and Switzerland's Basel region, anchoring European barrier tube innovation. Indian chemical engineers and South Korean materials scientists are building comparable talent pools in Hyderabad and Seoul's industrial suburbs.
Germany
Pharmaceutical contract manufacturers in Frankfurt and Ludwigshafen drive demand for EVOH-based laminate tubes under EMA stability testing guidelines. REACH Annex XVII substance restrictions on phthalates disqualify conventional resins from medical applications. The Rhine-Main corridor hosts pre-qualification programs where CDMOs validate converters before clinical trial design begins.
Switzerland
Precision pharmaceutical formulators in Basel require metered-dose pump tubes for topical corticosteroids and hormone therapies. Swissmedic enforces container closure integrity standards matching EMA stringency. The Basel-Lörrach cross-border cluster concentrates high-barrier tube qualification capacity for monoclonal antibody formulations.
India
Contract development and manufacturing organizations in Hyderabad and Ahmedabad are localizing barrier tube sourcing to serve export pharmaceutical markets. CDSCO aligns primary packaging regulations with ICH guidelines for international market access. The Hyderabad pharma corridor is attracting laminate tube converters to bypass 12-week European lead times.
South Korea
Specialty skincare startups in Seoul's Gangnam cluster fragment procurement toward 10,000-50,000 unit direct-to-converter orders. MFDS regulates cosmetic packaging migration limits under harmonized East Asian standards. Digital storefronts in the Gangnam beauty district compress tube sourcing lead times from 12 weeks to 4 weeks.
Italy
Retort-processed food paste manufacturers adopt aluminum oxide-coated plastic tubes to replace metal cans for single-serve convenience formats. EFSA migration limits for food contact materials govern barrier layer composition. Bologna and Parma food processing hubs are validating aluminum oxide barrier tubes for tomato paste and pesto applications.
Barrier Tube Packaging Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across three distinct capability tiers. European-based laminate specialists hold EMA extractables and leachables certification that commodity converters cannot replicate. The market structure concentrates pharmaceutical-grade supply among five to seven qualified suppliers while cosmetics procurement fragments toward digital-direct sourcing. Strategic moves center on backward integration into EVOH resin tolling arrangements and geographic expansion into Indian CDMO corridors.
Among European laminate specialists, Albéa Group and Hoffmann Neopac AG exemplify the certified-supplier archetype serving pharmaceutical qualification pathways. Essel Propack Limited represents the South Asian scale anchor with dedicated capacity for export pharmaceutical markets. These three occupy positions across the premium certification tier, the regional scale tier, and the precision-format specialization tier respectively.
| Leading Market Players |
|---|
| Albéa Group |
| Essel Propack Limited |
| CCL Industries Inc. |
| Montebello Packaging |
| Hoffmann Neopac AG |
| Alltub Group |
| Linhardt GmbH & Co. KG |
| World Wide Packaging LLC |
| ALPLA |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical CDMO concentration in Germany's Rhine-Main corridor and Switzerland's Basel region anchors contract-based long-term offtake pricing for EMA-qualified laminate tubes, while cosmetics procurement fragmentation toward South Korean digital storefronts compresses lead-time premiums into transactional spot arrangements.
Pricing Analysis
Bundled extractables and leachables certification services versus unbundled commodity tube supply separates pharmaceutical-grade pricing from cosmetics procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by EMA certification status and volume scale, with monoclonal antibody formulations commanding the highest tier. Cost compression in mid-tier laminate specifications is intensifying because REACH Annex XVII compliance investments are spreading fixed qualification costs across smaller batch runs. Mass-market cosmetics OEMs exhibit the greatest price sensitivity, while Swiss precision formulators accept 40-60 percent premiums for metered-dose pump integration.
Supply Chain Analysis
Specialized polymer chemist availability in Germany, Switzerland, and India determines converter qualification capacity for pharmaceutical-grade production. EVOH resin supply draws from Kuraray and Nippon Gohsei tolling arrangements in Japan and Belgium, while aluminum oxide coating feedstocks rest on German chemical specialty suppliers. Single-source vulnerability in EVOH resin concentration exposes converters to allocation risk during pharmaceutical demand surges. Distribution runs through direct sales channels for pharmaceutical sponsors and converter digital storefronts for South Korean indie cosmetics brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory ratcheting, with EMA's 2023 stability testing guidelines forcing pharmaceutical brands to abandon commodity tubes and validate high-barrier laminate structures, compressing qualified supplier pools and elevating pricing power for certified converters.
For Market Incumbents: Extend EMA extractables and leachables certification coverage to capture CDMO pre-qualification programs before clinical trial design begins. Backward integration into EVOH resin tolling arrangements with Kuraray or Nippon Gohsei secures input cost stability against allocation risk. Capacity addition in India's Hyderabad pharma corridor addresses lead-time compression demands from export-oriented contract manufacturers.
For New Entrants and Emerging Players: Capture the precision-dosing format white space in topical corticosteroid and hormone therapy applications where metered-dose pump tubes command 40-60 percent price premiums. Target South Korean specialty skincare startups in Seoul's Gangnam cluster through digital storefront platforms that compress sourcing lead times from traditional distributor networks. Pursue mono-material barrier structure development compatible with EU Packaging and Packaging Waste Regulation recycling mandates as the primary go-to-market angle.
For Investors and Strategic Acquirers: Pharmaceutical packaging conglomerates seeking CDMO relationship density are the most active acquirer in this space, particularly those lacking EMA-certified laminate tube capabilities. The five-to-ten year viability window favors converters with validated container closure integrity data and established extractables and leachables study partnerships. Monitor EMA migration limit tightening announcements as the critical inflection signal for qualification backlog expansion and pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Certification Investment | Extractables and leachables validation unlocks pharmaceutical CDMO pre-qualification pathways in Germany and Switzerland. |
| Backward Integration into EVOH Resin | Tolling arrangements with Kuraray or Nippon Gohsei reduce input cost volatility exposure for laminate tube converters. |
| Digital Storefront Launch | Direct-to-brand platforms in Seoul's Gangnam cluster capture cosmetics procurement fragmentation toward small-batch flexibility. |
| Mono-Material Barrier R&D | Polyethylene-based high-barrier formulations align with EU Packaging and Packaging Waste Regulation recyclability mandates. |
| Hyderabad Capacity Expansion | Local supply to Indian CDMOs bypasses European lead times for export pharmaceutical markets. |
Study Parameters
Multiple input streams — converter qualification database analysis, CDMO procurement pattern surveys, and regulatory filing review — were reconciled to construct market estimates. Primary interviews with pharmaceutical packaging engineers, regulatory affairs specialists at EMA-notified bodies, CDMO sourcing directors, and laminate tube production managers were cross-validated against secondary sources including EMA stability testing guideline documents, REACH Annex XVII substance restriction registers, and EU Packaging and Packaging Waste Regulation implementation drafts. Bottom-up tube unit demand modeling and top-down pharmaceutical packaging spend allocation were triangulated to verify segment-level outputs.
Historical volume trajectories were cross-referenced against expert panel inputs from polymer chemists and pharmaceutical formulators to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include barrier layer technology, end-use industry, closure format type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating EVOH resin supply constraints and REACH compliance cost pass-through rates. Migration testing laboratory capacity queues and CDMO pre-qualification program timelines served as industry-specific forecast calibration inputs.
EVOH resin supply disruption, EMA migration limit unscheduled tightening, and EU recyclability mandate acceleration are the dominant revision risks to forecast assumptions. Material deviation in any of these triggers warrants strategic pause and model re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Moisture Barrier Bags Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Global Heat Sealable Packaging Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Hygiene Packaging Films Market