
 North America Barrier Films Market | 2026-2036
North America Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
North America Barrier Films Market Analytics
Mexico's expanding flexible packaging production base is reconfiguring North American supply patterns for high-performance barrier materials. Amcor PLC leverages integrated film extrusion and converting operations across multiple U.S. states to sustain cost-advantaged supply to CPG customers. Berry Global Group Inc anchors its position through deep thermoforming and extrusion capabilities in food and healthcare packaging. Sealed Air Corp differentiates via proprietary vacuum and modified-atmosphere packaging systems that command premium placement in protein and cheese applications.
Barrier films are engineered polymer structures, typically achieving oxygen transmission rates below 0.1 cc per square meter per day, designed to prevent gas, moisture, and aroma permeation in sensitive packaged goods. Multi-layer coextrusion dominates production economics, with five-to-seven-layer structures now standard for demanding food and pharmaceutical applications. Coated films command margin premiums in pharmaceutical blister packs where pinhole-free aluminum oxide deposition ensures extended shelf stability. Polyethylene-based laminates lead volume in food packaging, though nylon-reinforced structures are gaining ground in retort and hot-fill segments requiring dimensional integrity under thermal stress.
The U.S. FDA's food contact notification process and Health Canada's PMRA packaging safety standards govern material approval timelines, directly influencing reformulation cycles and new product qualification periods. OSHA process safety requirements and EPA air quality mandates for solvent-based coating operations add compliance layers that favor aqueous and electron-beam curing investments. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California, Oregon, and Colorado, as these frameworks will determine recyclability design rules and post-consumer content mandates that reshape material specifications and capital allocation priorities.
Market Dynamics
Multi-layer coextrusion capacity concentration across Wisconsin, Illinois, and Michigan is forcing converters to secure resin supply through long-term offtake agreements rather than spot markets.
Growth Catalysts
- Foodservice channel expansion:Grocery retailers are adopting vacuum-skin packaging for fresh proteins, driving specification upgrades to sub-0.1 cc oxygen transmission rate films.
- PMRA packaging safety standards:Health Canada's tightening residue guidelines are accelerating reformulation cycles for Canadian food contact materials.
- Retort segment nylon adoption:Hot-fill and retort applications are specifying nylon-reinforced structures for dimensional integrity under thermal stress.
Market Restraints
- Resin supply concentration:Ethylene and propylene feedstock availability concentrates among Gulf Coast petrochemical complexes, exposing converters to hurricane-related disruption.
- Aluminum oxide coating cost:Pharmaceutical blister pack specifications requiring pinhole-free vapor deposition carry 40-60% premium over standard barrier laminates.
- Solvent-based coating regulatory friction:EPA air quality mandates for volatile organic compound emissions are forcing capital-intensive aqueous or electron-beam curing conversions.
Strategic Opportunities
- Mexico flexible packaging buildout:Querétaro and Tamaulipas production corridors offer tariff-advantaged supply positioning for U.S. Southwest distribution.
- Extended producer responsibility frameworks:California, Oregon, and Colorado EPR legislation will create first-mover advantages for post-consumer content integration.
- Modified-atmosphere packaging convergence:Vacuum packaging systems combined with active scavenger technologies are opening premium placement in specialty cheese segments.
Industry Challenges
- Multi-layer recycling incompatibility:Five-to-seven-layer coextruded structures lack mechanical recycling pathways, forcing investment in chemical recycling partnerships or design-for-recyclability re-engineering.
- FDA food contact notification timelines:New material qualification periods extending 18-24 months are compressing product development cycles and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Barrier Films Market |
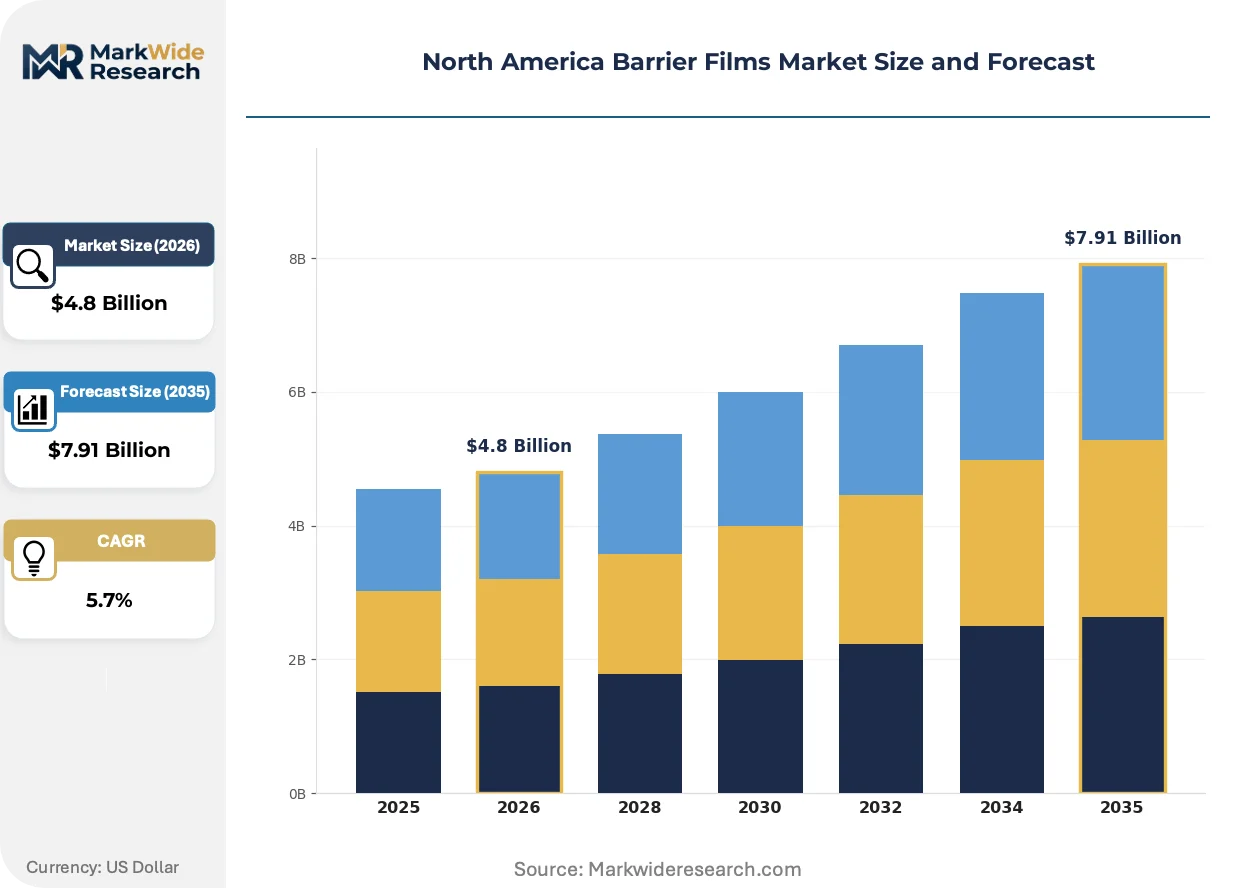
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-layer Films, Coated Films, Laminated Films, Shrink Films Material: Polyethylene, Polypropylene, Polyester, Nylon Application: Food Packaging, Pharmaceutical Packaging, Electronics Packaging, Industrial Applications End User: Food & Beverage, Healthcare, Consumer Goods, Electronics |
| Companies Covered | Amcor PLC, Berry Global Group Inc, Sealed Air Corp, DuPont Teijin Films, Winpak Ltd., Glenroy Inc., Mondi PLC, Toppan Holdings Inc, Flair Flexible Packaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Barrier Films Market Evolving Landscape
Digital process control and real-time quality monitoring are compressing specification drift in high-volume extrusion operations. These capabilities are redefining competitive differentiation beyond resin formulation alone.
Machine vision inspection systems integrated with spectroscopic analysis are digitizing defect detection in multi-layer film production. Protein packers and pharmaceutical contract manufacturers are specifying these capabilities in supplier scorecards. Real-time thickness profiling is enabling closed-loop gauge control that reduces resin giveaway by 3-5%.
OSHA process safety management requirements for high-pressure extrusion operations are mandating automated lockout-tagout systems and predictive maintenance protocols. Compliance investments favor larger integrated producers with dedicated safety engineering staff. The Great Lakes manufacturing corridor is seeing accelerated consolidation as mid-tier converters face capex burdens.
CPG procurement teams are consolidating supplier panels and demanding full lifecycle carbon footprint documentation. This specification shift favors converters with captive resin supply and renewable energy offtake agreements. The U.S. Great Lakes states and Ontario are emerging as preferred sourcing regions due to grid decarbonization progress and transportation proximity to major food processing clusters.
North America Barrier Films Market Segmentation
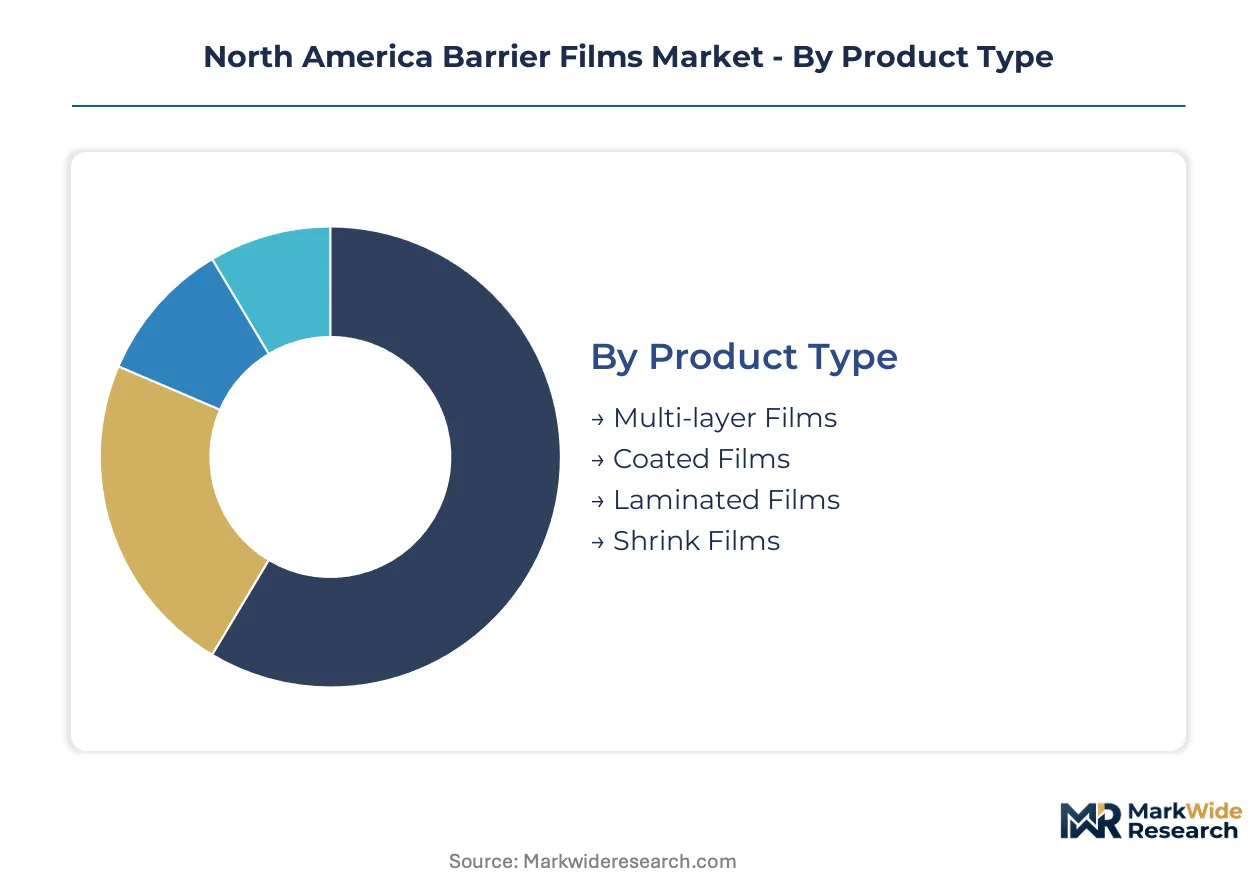
Barrier films serve radically different performance requirements across food preservation, pharmaceutical stability, and electronics protection. Each segment demands distinct technical specifications, resin formulations, and compliance protocols that reshape supplier selection criteria and manufacturing investment priorities.
Product Type:
After-sales service intensity varies sharply across product categories, with coated films requiring specialized application equipment support and multi-layer structures demanding ongoing technical consultation for line integration.
- Multi-layer Films:Five-to-seven-layer coextruded structures achieve sub-0.1 cc oxygen transmission rates through precise polymer sequencing. Demand concentrates in fresh protein packaging across Wisconsin and Illinois food processing corridors, where vacuum-skin specifications command premium placement. FDA food contact notification timelines extend 18-24 months for new multi-layer formulations, compressing product development cycles.
- Coated Films:Aluminum oxide vapor deposition creates pinhole-free barriers essential for pharmaceutical blister packs. Specifications from Health Canada PMRA residue guidelines and U.S. FDA standards drive qualification complexity. The 40-60% cost premium over standard laminates restricts adoption to high-value pharmaceutical and specialty food segments.
- Laminated Films:Polyethylene-based adhesive laminates dominate high-volume food packaging through cost-efficient production economics.
- Shrink Films:Biaxially oriented structures provide conformal protection for irregular product geometries in industrial bundling applications.
Multi-layer films hold the largest share; momentum sits with coated films.
Material:
Resin selection directly determines barrier performance, thermal stability, and recyclability compliance under emerging extended producer responsibility frameworks.
- Polyethylene:Linear low-density and metallocene grades anchor food packaging volume through sealability and cost efficiency. California and Oregon EPR legislation is forcing design-for-recyclability re-engineering of polyethylene-dominant structures.
- Nylon:Polyamide reinforcement delivers dimensional integrity under retort and hot-fill thermal stress. Specification growth concentrates in Michigan and Ontario ready-meal manufacturing clusters, where 121°C sterilization cycles demand creep resistance.
- Polypropylene:Oriented PP films provide moisture barriers with clarity for consumer goods display packaging.
- Polyester:PET substrates offer mechanical strength and printability for premium label and lidding applications.
Polyethylene maintains volume leadership; nylon is climbing the fastest.
Application:
Application-driven specifications create divergent margin profiles, with pharmaceutical packaging demanding certification-intensive qualification and food packaging prioritizing throughput economics.
- Food Packaging:Modified-atmosphere and vacuum-skin systems dominate protein, cheese, and produce preservation. Grocery retail and foodservice channel expansion across the U.S. Great Lakes corridor is driving specification upgrades to sub-0.1 cc oxygen transmission rate films.
- Pharmaceutical Packaging:Blister packs and cold-form foil laminates require pinhole-free barrier integrity for moisture-sensitive APIs. Health Canada PMRA packaging safety standards and U.S. FDA food contact substance notifications govern material approval timelines.
- Electronics Packaging:Static-dissipative and moisture-barrier films protect semiconductors during shipment and storage.
- Industrial Applications:Heavy-duty barrier films serve agricultural fumigation and chemical containment requirements.
Food packaging commands the dominant share; pharmaceutical packaging shows steepest expansion trajectory.
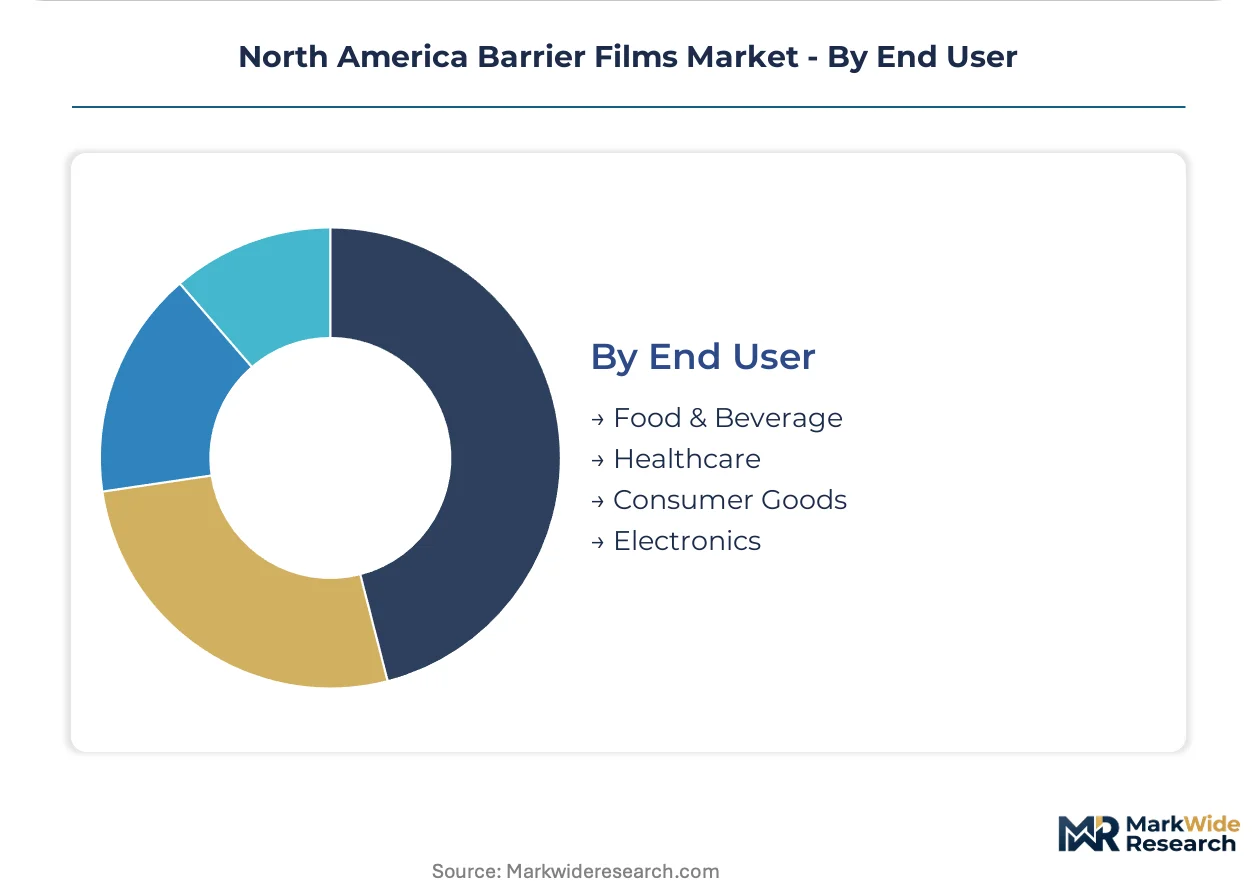
End User:
End-user procurement patterns differentiate between specification-driven healthcare buyers and cost-optimized consumer goods purchasers.
- Food & Beverage:Protein packers and dairy processors specify real-time thickness profiling and machine vision inspection in supplier scorecards. The U.S. Great Lakes manufacturing corridor concentration forces long-term resin offtake agreements rather than spot market exposure.
- Healthcare:Pharmaceutical contract manufacturers demand full lifecycle carbon footprint documentation and captive resin supply verification. OSHA process safety management requirements favor integrated producers with dedicated safety engineering staff.
- Consumer Goods:Personal care and household product brands prioritize shelf appeal through high-clarity barrier laminates.
- Electronics:OEMs and contract manufacturers specify ESD-controlled packaging for component protection.
Food & Beverage represents the largest end-use segment; Healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge system and Great Lakes-St. Lawrence Seaway interconnect the North American barrier films supply chain, anchoring resin distribution and converting capacity across the continent.
United States
Vacuum-skin packaging adoption by Kroger and Albertsons drives specification upgrades to sub-0.1 cc oxygen transmission rate films. EPA air quality mandates for solvent-based coating operations force capital-intensive aqueous or electron-beam curing conversions. The Great Lakes manufacturing corridor spanning Wisconsin, Illinois, and Michigan concentrates multi-layer coextrusion capacity, forcing converters into long-term resin offtake agreements.
Canada
Health Canada's PMRA packaging safety standards accelerate reformulation cycles for food contact materials. Tightening residue guidelines compress new product qualification timelines to 18-24 months. Ontario's ready-meal manufacturing clusters specify nylon-reinforced structures for dimensional integrity under 121°C retort sterilization cycles.
Mexico
Querétaro and Tamaulipas production corridors offer tariff-advantaged supply positioning for U.S. Southwest distribution. The country's national food safety regulator maintains alignment with U.S. FDA food contact notification processes. Expanding flexible packaging production bases reconfigure North American supply patterns for high-performance barrier materials.
North America Barrier Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin formulation and coating deposition. The North American barrier films market structures around three to five integrated multinational producers with captive extrusion and converting operations, supplemented by regional specialists in pharmaceutical coating and food-grade laminates. Strategic archetypes include integrated film-converting platforms, coating technology licensors, and niche healthcare packaging specialists. Dominant competitive moves center on Mexico capacity expansion for tariff-advantaged U.S. access and chemical recycling partnerships to address multi-layer incompatibility.
Among integrated packaging platforms, Amcor PLC and Berry Global Group Inc exemplify the scale-driven archetype with broad film extrusion and converting footprints. Sealed Air Corp occupies a differentiated position through proprietary vacuum and modified-atmosphere packaging systems. These three anchors represent contrasting strategic vectors: resin-integration scale, healthcare-specialized coating capabilities, and equipment-integrated system solutions.
| Leading Market Players |
|---|
| Amcor PLC |
| Berry Global Group Inc |
| Sealed Air Corp |
| DuPont Teijin Films |
| Winpak Ltd. |
| Glenroy Inc. |
| Mondi PLC |
| Toppan Holdings Inc |
| Flair Flexible Packaging Corporation |
| Others |
Value Network & Pricing Analysis
Hurricane exposure across Gulf Coast petrochemical complexes determines both the spread between contract and spot resin pricing and the geographic clustering of converting capacity around the Great Lakes manufacturing corridor. This concentration forces buyers into long-term offtake agreements that lock in tiered pricing structures while insulating against feedstock disruption.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical blister pack specifications from food-grade multi-layer laminates and industrial bundling films. Price differentiation rests on oxygen transmission rate certification and FDA food contact notification status, with sub-0.1 cc films commanding substantial premiums. Cost compression in standard food-grade laminates is intensifying because Mexico capacity expansion introduces tariff-advantaged supply alternatives. Protein packers and pharmaceutical contract manufacturers show lowest price sensitivity due to qualification-intensive supplier switching costs, while industrial bundling buyers prioritize unit economics above barrier performance.
Supply Chain Analysis
Ethylene and propylene feedstock production concentrates in the United States, Canada, and Mexico, with Gulf Coast crackers supplying the majority of North American resin demand. Raw material dependencies center on naphtha and natural gas liquids for polymer production, aluminum ingots for vapor deposition, and specialty adhesives for lamination. Single-source vulnerability runs through hurricane-prone Texas and Louisiana petrochemical infrastructure, where storm-related outages have historically disrupted regional supply. Distribution runs through Mississippi River barge networks and Great Lakes-St. Lawrence Seaway connections that link resin production to Wisconsin, Illinois, and Michigan converting clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated grocery retail and pharmaceutical procurement panels that demand full lifecycle carbon documentation and captive resin verification, squeezing margin from mid-tier converters lacking scale or specialty certification.
For Market Incumbents: Entrench position through backward integration into resin compounding and extrusion capacity expansion across the Great Lakes corridor to secure feedstock access. Chemical recycling partnerships address multi-layer incompatibility threats while satisfying California and Oregon extended producer responsibility mandates. FDA food contact notification expertise becomes a defendable moat as qualification timelines extend. For New Entrants and Emerging Players: Build out coating deposition capabilities for pharmaceutical blister pack specifications where Health Canada PMRA standards create qualification barriers favoring specialized entrants. Querétaro and Tamaulipas production corridors offer the most penetrable geography for tariff-advantaged U.S. Southwest distribution. A go-to-market angle targeting mid-size dairy processors with modified-atmosphere packaging systems bypasses entrenched protein packer relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated film-converting platforms with captive resin supply and renewable energy offtake agreements. Long-term viability across the next decade hinges on chemical recycling infrastructure access and EPR compliance positioning. The signal to watch is California implementation timelines for post-consumer content mandates that will determine which converters capture first-mover recycling advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Mexico Capacity Expansion | Querétaro and Tamaulipas corridors enable tariff-advantaged supply positioning for U.S. Southwest distribution. |
| Chemical Recycling Partnership | Multi-layer coextrusion incompatibility with mechanical recycling forces alternative recovery pathway investments. |
| Post-Consumer Content Integration | California EPR legislation creates competitive differentiation for converters with verified recycled resin supply. |
| Modified-Atmosphere System Development | Active scavenger technology convergence opens premium placement in specialty cheese packaging segments. |
| Real-Time Quality Infrastructure | Machine vision and spectroscopic inspection capabilities satisfy protein packer supplier scorecard requirements. |
Research Methodology
Initial hypotheses were tested against primary input from film extrusion plant managers, CPG procurement leads, pharmaceutical packaging engineers, and resin distribution channel partners and refined through secondary validation against U.S. FDA food contact substance notification databases, Health Canada PMRA residue guidelines, EPA air quality enforcement records, and American Chemistry Council trade flow data. Bottom-up capacity modeling across Wisconsin, Illinois, and Michigan converting clusters was cross-checked against top-down demand aggregation from protein packer and dairy processor consumption estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, material resin, application end-use, and geographic production hub. CAGRs were derived through regression analysis of historical capacity utilization and forward-looking qualification pipeline data. Forecast inputs incorporated FDA notification timeline distributions and EPR legislative implementation schedules.
Stress conditions across hurricane-related feedstock disruption, extended producer responsibility acceleration, and FDA qualification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding resin price volatility and regulatory implementation pacing. Cross-checking against American Chemistry Council resin production and trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Barrier Bags Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Global Medical Packaging Films Market