
 Automotive Seat Adjusters Market | 2026-2036
Automotive Seat Adjusters Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Adjusters Market Analysis
Fleet buyers of commercial vehicles are collapsing their historical preference for manual adjusters as electrified cabs and driver retention programs shift specifications toward power-adjustable seating. Lear Corporation leverages captive seat assembly capacity to bundle adjuster modules directly into OEM contracts. Brose Fahrzeugteile sustains engineering intensity in mechatronic track systems for European premium platforms. Adient anchors North American production through dedicated JIT lines serving Detroit Three full-size truck programs.
Automotive seat adjusters comprise mechanical, electromechanical, or pneumatic actuation subsystems that enable longitudinal sliding, recline, height, and lumbar positioning of vehicle seats, typically integrating precision-machined steel or aluminum rack-and-pinion mechanisms with torque-controlled motors rated for thousands of duty cycles. Their primary purpose is to optimize occupant ergonomics, safety belt geometry, and crashworthiness while supporting modular seat platform architectures across vehicle lines. Power adjusters now lead value contribution as OEMs delete manual hardware from mid-trim configurations, while intelligent adjusters with biometric feedback represent the fastest-growing margin pool despite current low volume. Memory adjusters retain strong positioning in luxury vehicle segments where multi-driver profiles justify the cost premium.
NHTSA Federal Motor Vehicle Safety Standards govern seat strength and displacement limits in the United States, while ECE R17 and R80 regulations administered under UN-ECE frameworks shape European homologation requirements for seat anchorage and adjustability. China's GB standards issued through MIIT add local certification layers that foreign suppliers must navigate for domestic OEM access. Stakeholders must monitor how software-defined vehicle architectures will redistribute adjuster control logic between seat modules and central compute platforms.
Market Dynamics
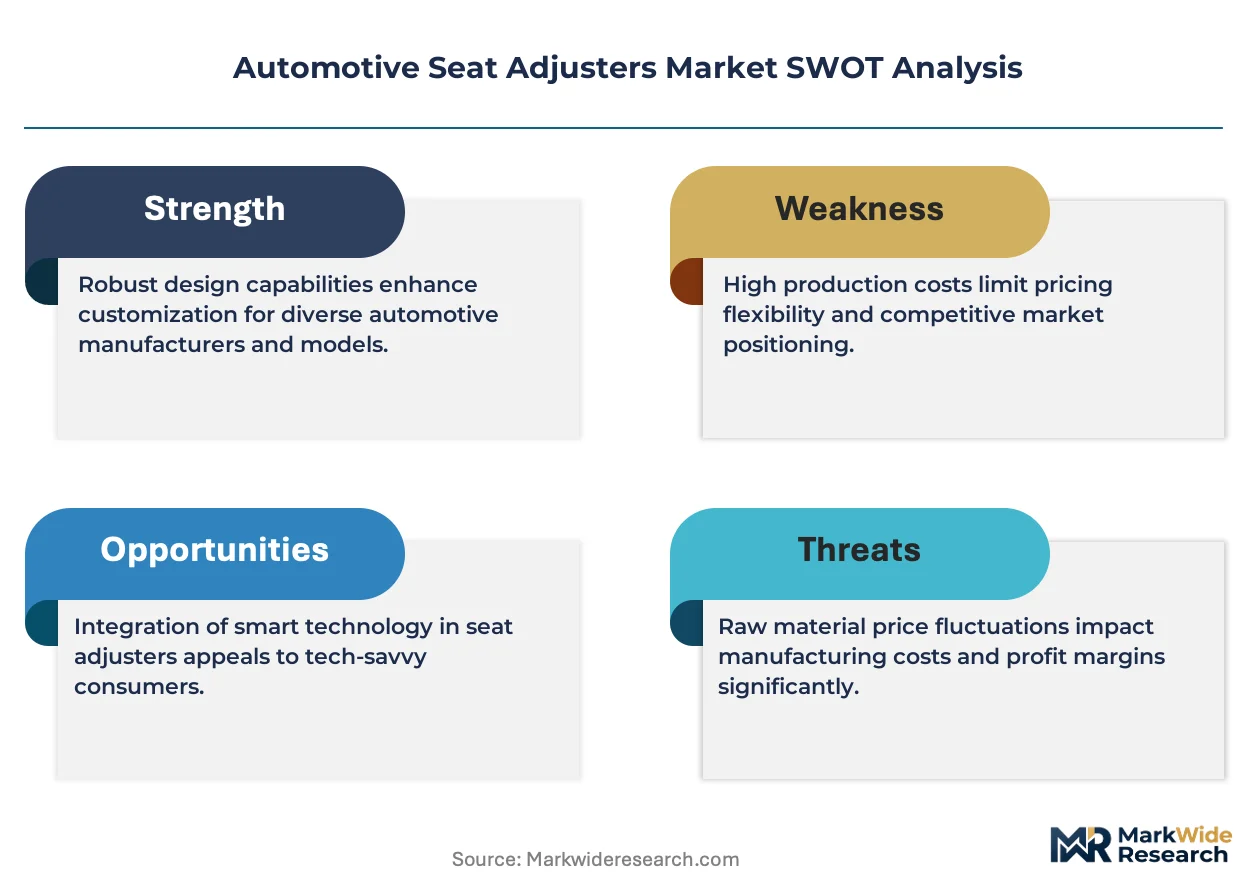
The electrification of vehicle platforms is collapsing legacy mechanical architectures as cabin space optimization and wire-harness reduction force adjuster systems toward integrated mechatronic modules.
Growth Catalysts
- EU safety directives:ECE R17 and R80 mandates for seat anchorage strength are compelling OEMs to upgrade from manual to power-adjustable hardware across mid-trim configurations.
- EV cabin ergonomics:Battery-electric vehicle platforms in China, Germany, and the United States prioritize flat-floor architectures that demand compact, multi-axis adjuster mechanisms.
- Biometric feedback convergence:Pressure-mapping sensors and occupant detection algorithms are creating new specification tiers for intelligent adjusters in luxury segments.
Market Restraints
- Rare-earth magnet volatility:Neodymium and dysprosium price swings embedded in torque motor supply chains compress margin predictability for electromechanical adjuster producers.
- Tooling concentration:Precision rack-and-pinion die casting capacity clusters in China's Yangtze River Delta, creating single-source vulnerability for global seat module assemblers.
- Homologation fragmentation:Divergent GB standards from MIIT, NHTSA FMVSS protocols, and UN-ECE frameworks force redundant testing cycles that extend program timelines.
Strategic Opportunities
- Software-defined vehicle redistribution:Central compute architectures are shifting adjuster control logic from distributed seat ECUs to domain controllers, opening firmware licensing revenue streams.
- Commercial fleet electrification:Driver retention programs at North American and European logistics operators are specifying power-adjustable seating for electrified cab configurations previously served by manual hardware.
- Memory adjuster penetration:Multi-driver profile storage remains underdeployed in premium SUV and MPV segments outside established luxury marques.
Industry Challenges
- Mechatronics talent scarcity:The intersection of precision mechanical engineering and embedded software development lacks sufficient cross-trained specialists for next-generation adjuster program execution.
- Legacy platform integration:CAN bus communication protocols in existing vehicle architectures constrain data bandwidth for advanced adjuster functions requiring real-time biometric feedback loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Adjusters Market |
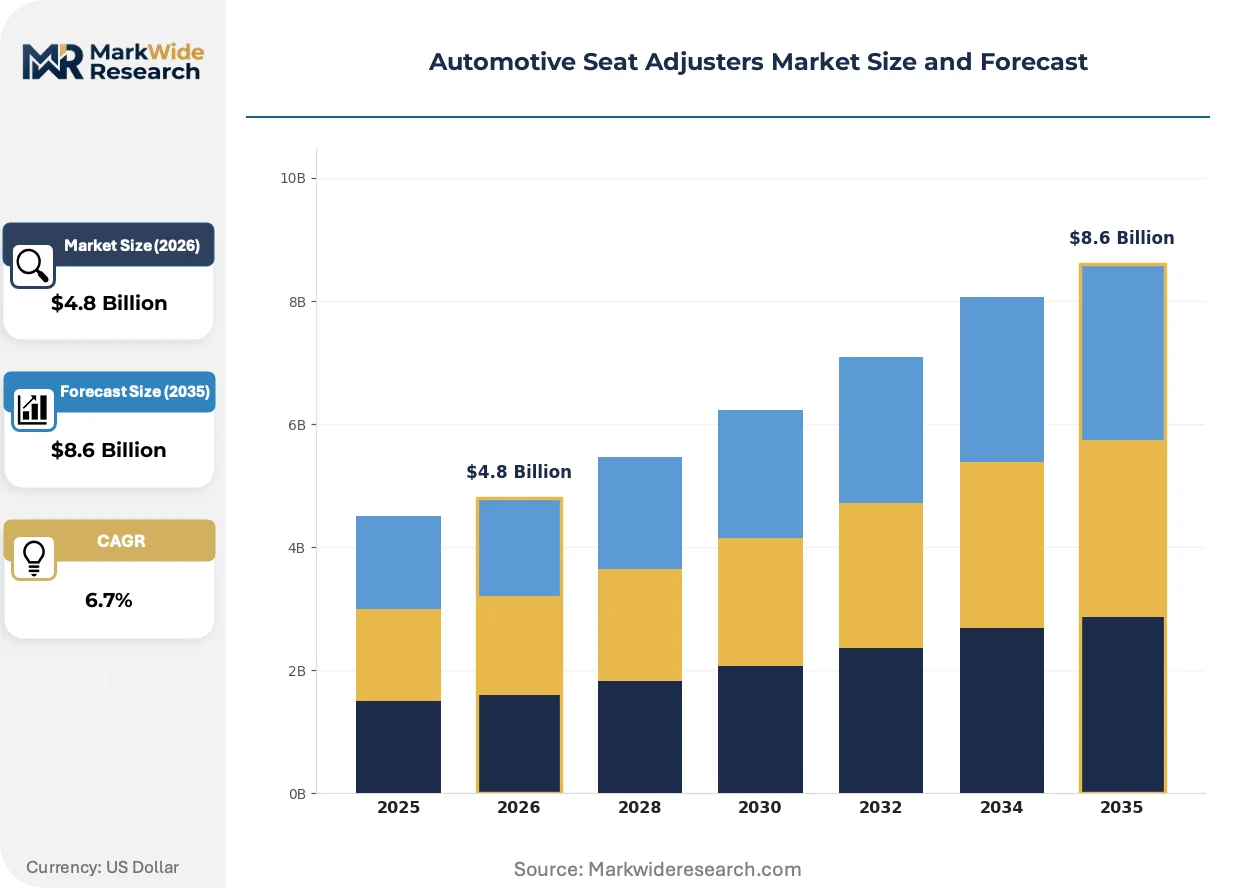
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Adjusters, Power Adjusters, Memory Adjusters, Intelligent Adjusters End User: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Sports Cars Adjuster Mechanism: Mechanical, Electrical, Pneumatic, Hybrid Material: Steel, Aluminum, Plastic, Composite |
| Companies Covered | SHIROKI Corporation, Imasen Electric Industrial, Johnson Electric, Aisin World Corp, Brose Fahrzeugteile, Lear Corporation, Adient, Magna International, Faurecia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Adjusters Market Emerging Trajectories
Actuator miniaturization and control logic migration are compressing hardware footprints while expanding functional scope across passenger and commercial vehicle segments.
Brushless DC torque motors with integrated position sensing are miniaturizing traditional adjuster drive units by consolidating gearbox, encoder, and thermal management into single housings. European premium OEMs are specifying these compact modules for second-row captain's chairs where packaging space constraints previously precluded power adjustment. The structural consequence is that seat track envelope dimensions are compressing by roughly one-third while maintaining load ratings, enabling flat-floor EV architectures without sacrificing longitudinal travel range.
NHTSA's updated interpretation of FMVSS 302 flammability standards for interior materials is forcing adjuster suppliers to requalify polymer gear housings and cable sheathing. The industrial consequence is a specification pivot toward halogen-free flame-retardant compounds that maintain torque transmission efficiency across temperature cycling. North American full-size truck programs are most affected, with Detroit Three procurement teams accelerating material validation timelines to avoid program delays.
Fleet operators are consolidating supplier relationships from discrete component sourcing toward integrated seat module contracts that bundle adjuster mechanisms with foam, trim, and structural frames. This purchasing consolidation is displacing standalone adjuster vendors who lack captive seat assembly capability. The pattern is most visible in North American commercial vehicle segments where total cost of ownership calculations now dominate specification decisions over upfront hardware pricing.
Automotive Seat Adjusters Market Segmentation
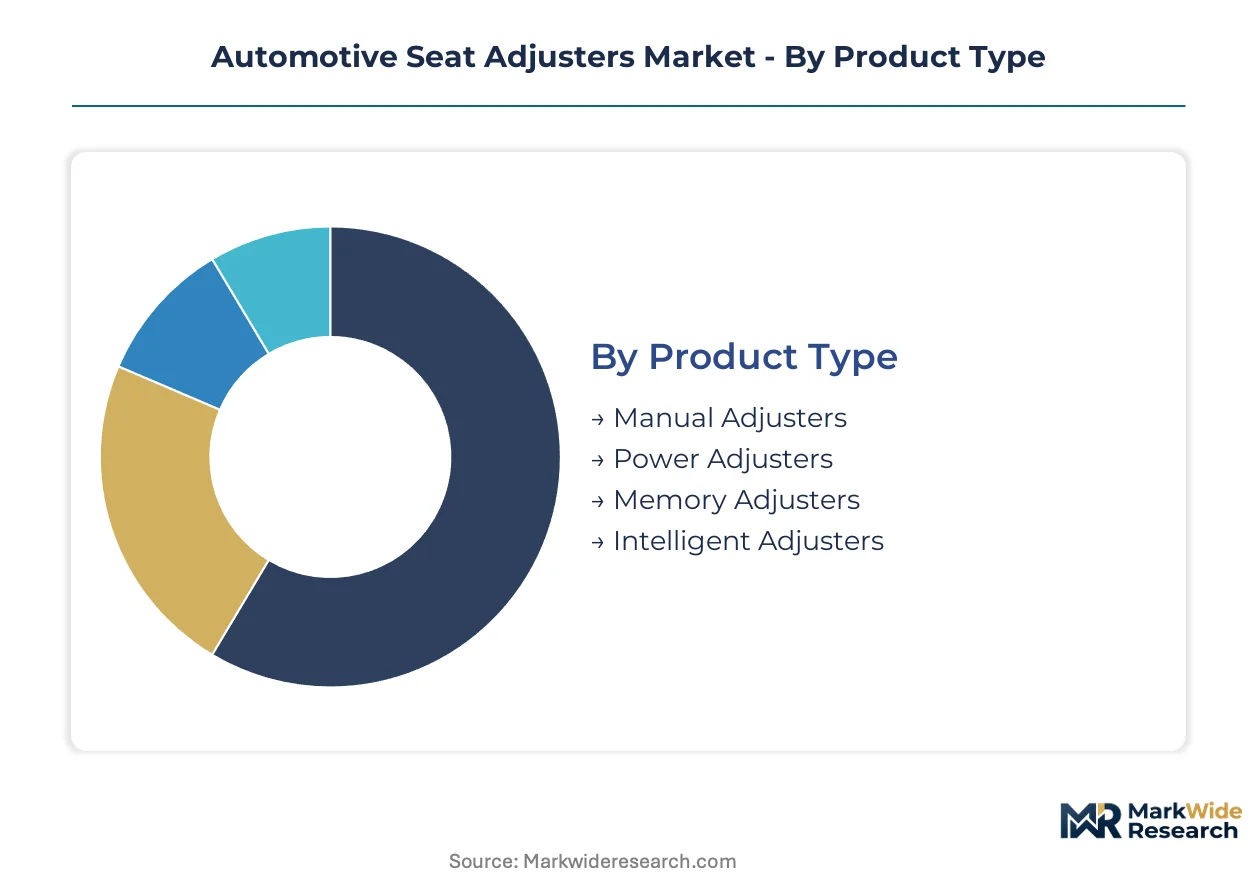
Segmentation in automotive seat adjusters reveals how hardware specifications, actuation technologies, and material choices map to distinct margin architectures. OEM procurement teams weight these dimensions differently across vehicle classes and regulatory environments.
Product Type:
Margin pools concentrate in electrified and sensor-integrated variants as manual hardware loses specification share across mid-trim configurations.
- Power Adjusters:Brushless DC torque motors with integrated position sensing consolidate gearbox, encoder, and thermal management into compact housings. Detroit Three full-size truck programs and European premium OEMs specify these modules for second-row captain's chairs where packaging constraints previously precluded electrification.
- Intelligent Adjusters:Biometric feedback systems incorporating pressure-mapping sensors and occupant detection algorithms command premium pricing in luxury segments. Chinese EV platforms and German premium marques are accelerating procurement as cabin ergonomics becomes a competitive differentiator.
- Manual Adjusters:Rack-and-pinion mechanisms without motor actuation retain residual specification in emerging market entry vehicles and certain fleet configurations.
- Memory Adjusters:Multi-driver profile storage systems remain concentrated in established luxury marques with multi-user households.
Power adjusters hold installed capacity. Intelligent adjusters are rotating up the share rankings.
End User:
Application mix determines duty cycle requirements and validation rigor, with commercial and luxury segments imposing divergent performance specifications.
- Commercial Vehicles:Fleet operators at North American and European logistics providers are specifying power-adjustable seating for electrified cab configurations previously served by manual hardware. Driver retention programs and total cost of ownership calculations now dominate procurement decisions over upfront hardware pricing.
- Luxury Vehicles:Multi-axis adjustment with memory functions and biometric integration represents standard specification. ECE R17 and R80 mandates for seat anchorage strength are compelling upgrades from manual to power-adjustable hardware across mid-trim configurations.
- Passenger Vehicles:Mass-market OEMs in China, Germany, and the United States are deleting manual adjusters from mid-trim configurations.
- Sports Cars:Lightweight, low-profile adjuster mechanisms prioritize packaging efficiency and center-of-gravity optimization over adjustment range.
Commercial vehicles are expanding specification fastest. Luxury vehicles retain the highest content per seat.
Adjuster Mechanism:
Actuation technology selection drives supply chain configuration and mechatronics talent requirements for program execution.
- Electrical:Brushless DC motors with rare-earth magnets dominate new program specifications despite neodymium and dysprosium price volatility compressing margin predictability.
- Hybrid:Combined electrical-mechanical architectures bridge legacy platform integration constraints and emerging functional requirements.
- Mechanical:Purely mechanical linkages without electrical actuation retain limited application in cost-sensitive vehicle classes.
- Pneumatic:Air-driven adjustment systems serve specialized commercial seating applications requiring rapid position changes.
Electrical mechanisms command program volume. Hybrid configurations are gaining specification in platform transition periods.
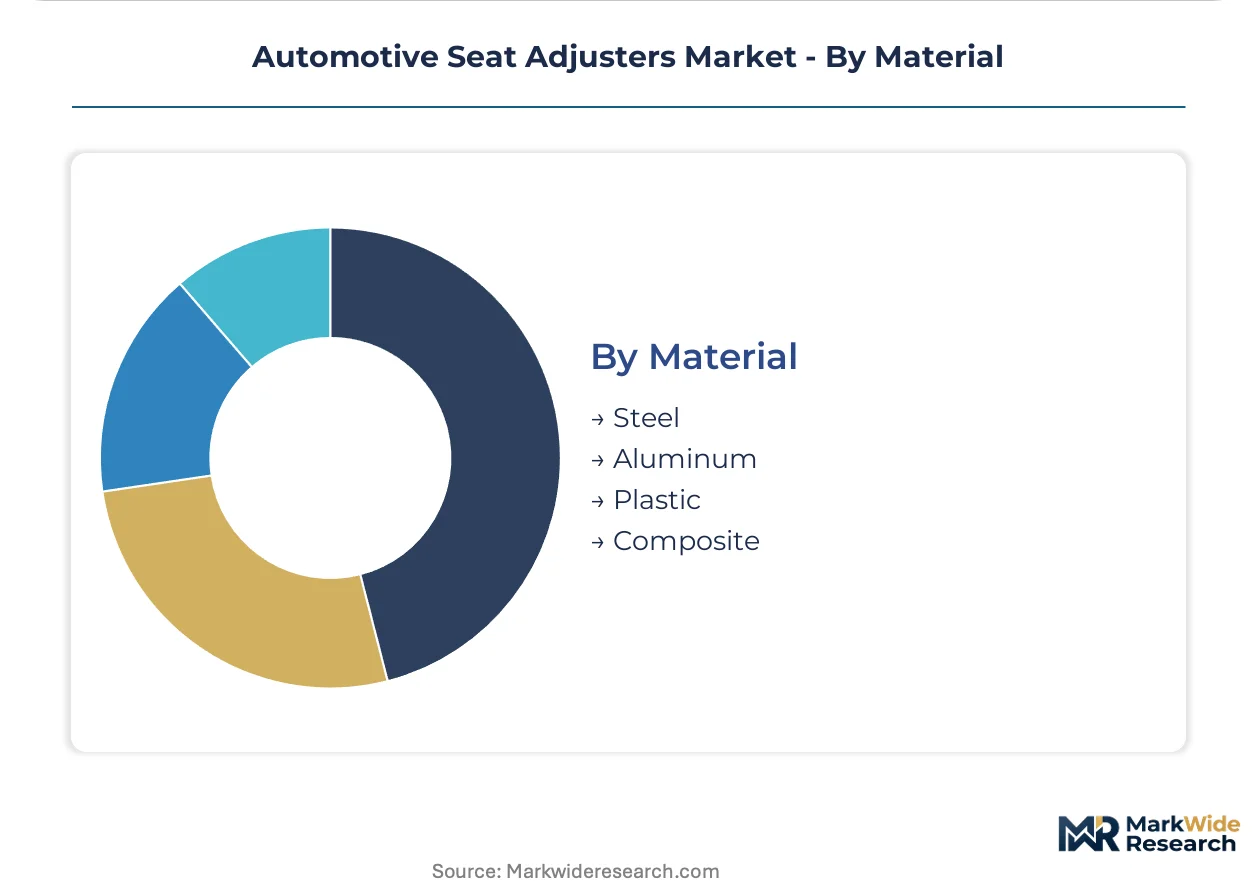
Material:
Material selection balances structural load requirements, flammability compliance, and mass reduction targets across temperature cycling demands.
- Steel:Precision-machined rack-and-pinion mechanisms maintain dominance in high-load track systems for full-size trucks and commercial applications.
- Aluminum:Die-cast and extruded aluminum components enable mass reduction in EV platforms where cabin space optimization and wire-harness reduction force adjuster systems toward integrated mechatronic modules.
- Plastic:Polymer gear housings and cable sheathing face requalification pressure under NHTSA's updated FMVSS 302 flammability interpretations, driving specification pivot toward halogen-free flame-retardant compounds.
- Composite:Fiber-reinforced materials serve niche applications requiring extreme stiffness-to-weight ratios in performance vehicle seating.
Steel maintains structural specification dominance. Aluminum is climbing fastest in EV platform content.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German seat adjuster exports flow predominantly to premium vehicle assembly plants across China and the United States, establishing a critical trade corridor that shapes global component pricing and specification standards.
United States
Detroit Three full-size truck programs are deleting manual adjusters from mid-trim configurations as NHTSA Federal Motor Vehicle Safety Standards tighten seat anchorage requirements. The NHTSA FMVSS 302 flammability reinterpretation is forcing polymer requalification across supplier networks. Michigan and Ohio assembly corridors concentrate JIT seat module delivery to major OEM final assembly lines.
Germany
European premium OEMs are specifying compact brushless DC modules for second-row captain's chairs where packaging constraints previously blocked electrification. ECE R17 and R80 mandates under UN-ECE frameworks compel hardware upgrades across vehicle lines. Baden-Württemberg engineering clusters sustain mechatronics development for track system miniaturization.
China
Domestic EV platforms prioritize flat-floor architectures demanding compact multi-axis adjuster mechanisms with reduced vertical envelope. MIIT GB standards add certification layers foreign suppliers must navigate for OEM access. Yangtze River Delta die-casting clusters host precision rack-and-pinion capacity serving both local and export seat module assemblers.
Japan
Lightweight adjuster development targets hybrid and battery-electric vehicle programs where cabin space optimization competes with structural load requirements. METI industrial standards shape domestic supplier qualification protocols. Kanto region manufacturing bases supply precision-machined components to regional OEM seat divisions.
South Korea
Domestic OEMs are integrating intelligent adjuster functions with centralized vehicle compute architectures as software-defined vehicle platforms mature. MFDS automotive component regulations align with broader industrial safety frameworks. Seoul Capital Area production facilities serve both domestic vehicle assembly and component export programs.
Automotive Seat Adjusters Market Vendor Landscape
Listed leaders compete with private specialists across capital access and engineering agility, creating a tiered structure where scale advantages in seat module integration clash with niche expertise in mechatronic actuation. Three archetypes dominate: integrated seat assemblers with captive adjuster capacity, standalone mechanism specialists, and diversified automotive suppliers leveraging cross-product platform synergies. M&A activity concentrates on acquiring software competencies for intelligent adjuster control, while capacity expansion targets aluminum die-casting and compact motor assembly in EV-centric geographies.
Within the integrated seat assembler tier, Lear Corporation and Adient exemplify archetypes that bundle adjuster mechanisms directly into OEM contracts through captive assembly capacity. Brose Fahrzeugteile occupies a position among European mechatronic specialists, sustaining engineering intensity in track systems for premium platforms. These three anchors illustrate how competitive positioning diverges between scale-driven module integration and focused component engineering depth.
| Leading Market Players |
|---|
| SHIROKI Corporation |
| Imasen Electric Industrial |
| Johnson Electric |
| Aisin World Corp |
| Brose Fahrzeugteile |
| Lear Corporation |
| Adient |
| Magna International |
| Faurecia |
| Others |
Supply Flow & Price Mechanics
Sixty-day die-casting tool lead times from Yangtze River Delta suppliers compress procurement flexibility for North American seat module assemblers, concentrating pricing power with integrated Tier 1s while fragmenting margin capture for standalone adjuster vendors. This inventory-to-supply coupling forces OEM procurement teams toward bundled seat module contracts that internalize cost volatility through captive assembly relationships.
Pricing Analysis
Current-generation brushless DC torque modules command substantial premiums over prior-generation brushed motor hardware, while next-generation intelligent adjuster systems with biometric integration stratify pricing further. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and volume scale, with NHTSA FMVSS 302 compliance tiers adding regulatory cost layers. Cost compression in economy-grade manual adjusters is intensifying because Chinese EV platforms are deleting mechanical hardware from base configurations. Fleet procurement teams at North American logistics operators demonstrate highest price sensitivity, while German premium marques absorb premium tiers for second-row electrification.
Supply Chain Analysis
Port congestion at Shanghai-Ningbo and container availability constraints on Asia-North America trade lanes inject inventory risk for just-in-time seat module programs serving Detroit Three assembly corridors. Precision rack-and-pinion capacity concentrates in China, Germany, and Mexico, with rare-earth magnet supply drawing from Chinese and Myanmar extraction clusters. Single-source vulnerability in Yangtze River Delta die-casting creates structural exposure for global assemblers. Distribution runs through captive Tier 1 seat integration facilities rather than standalone adjuster component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seat adjuster procurement fragmentation creates niche entry points as software-defined vehicle architectures redistribute control logic between distributed seat ECUs and domain controllers. This technical disaggregation enables specialist firmware vendors to capture value previously consolidated within integrated module suppliers.
For Market Incumbents: Shield program margins by deepening captive aluminum die-casting capacity in EV-centric geographies to offset rare-earth magnet volatility. Secure backward integration into brushless DC motor assembly before semiconductor talent scarcity constrains mechatronics execution. Prioritize ECE R17 and R80 certification maintenance as European safety mandates tighten anchorage requirements. For New Entrants and Emerging Players: Differentiate on intelligent adjuster firmware for Chinese EV platforms where cabin ergonomics commands specification priority. Target commercial fleet electrification segments previously served by manual hardware, leveraging driver retention program budgets. Pursue white-label licensing arrangements with established seat assemblers lacking embedded software competencies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive suppliers seeking to monetize non-core adjuster mechanism divisions amid seat module consolidation. Long-term viability hinges on software-defined vehicle integration depth rather than mechanical component scale. Monitor OEM central compute architecture announcements as inflection signals for firmware licensing revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Domain controller migration opens firmware licensing streams beyond hardware margins. |
| Geographic Manufacturing Footprint | Aluminum die-casting proximity to EV production clusters reduces logistics exposure. |
| Platform Standardization | Modular track systems across vehicle lines amortize validation costs for ECE R17 compliance. |
| Battery Supply Agreement | Electrified cab configurations at fleet operators drive power-adjuster specification share. |
| Charging Infrastructure Partnership | Commercial fleet electrification correlates with driver retention program seating budgets. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement patterns anchors the qualitative findings in observable contract structures. Primary interviews with seat module program managers, adjuster mechanism R&D directors, fleet procurement officers, and automotive regulatory consultants combined with secondary validation through UN-ECE ECE R17/R80 documentation, NHTSA FMVSS interpretation letters, MIIT GB standard filings, and vehicle production registration databases. Bottom-up content-per-vehicle estimates triangulate against top-down market value reconstruction.
Sensitivity analysis around rare-earth magnet price bands and EV platform penetration rates tests forecast robustness across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per seat, adjuster mechanism type, and regional production cluster. CAGRs derive from fitted growth curves calibrated to OEM procurement pipeline visibility and regulatory mandate implementation timelines. Forecast inputs incorporate die-casting capacity utilization rates and brushless DC motor supplier lead time trends.
Decision-makers should treat outputs as directional under assumptions of sustained EV platform prioritization of cabin ergonomics and continued ECE R17/R80 enforcement intensity; material deviation in either vector would warrant model refresh. Forecasts reflect these base conditions alongside assumed rare-earth supply chain stabilization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
South America Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Singapore Automotive Engine Oils Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Europe Automotive Parts Die Casting Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automotive Power Window Regulator Market