
 Automotive Brake Linings Market | 2026-2036
Automotive Brake Linings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Linings Market Analysis
The split between premium and commodity brake lining tiers is hardening on friction coefficient consistency and thermal fade resistance. Brembo S.p.A. dominates motorsport-derived ceramic formulations for performance applications. Federal-Mogul Corporation leverages captive resin blending and fiber processing to sustain margin pools in North American heavy-duty segments. Nisshinbo Holdings Inc. anchors Asian supply through integrated phenolic resin and copper-free material production.
Automotive brake linings are composite friction materials bonded to metal backing plates, typically comprising aramid fibers, ceramic particles, and phenolic resin matrices cured under 150-200°C press conditions, engineered to convert kinetic energy into thermal energy during deceleration. Non-asbestos formulations now lead product type demand as OEMs eliminate copper and heavy metals under state-level environmental mandates. Disc brake applications absorb the fastest-growing share of value given higher lining wear rates and replacement frequency versus drum configurations. Emergency vehicles represent a concentrated margin pool where specialized high-temperature formulations command premium positioning.
NHTSA's Federal Motor Vehicle Safety Standards govern friction performance and labeling requirements, while EPA oversight of copper runoff from brake pads shapes material composition roadmaps in multiple U.S. states. India's BIS certification mandates and the Automotive Research Association of India's test protocols determine market access for domestic and imported lining suppliers. Stakeholders must monitor regulatory divergence between copper-free mandates in North America and Europe's REACH restrictions on phenolic resin emissions as formulation strategies risk fragmenting across jurisdictions.
Market Dynamics
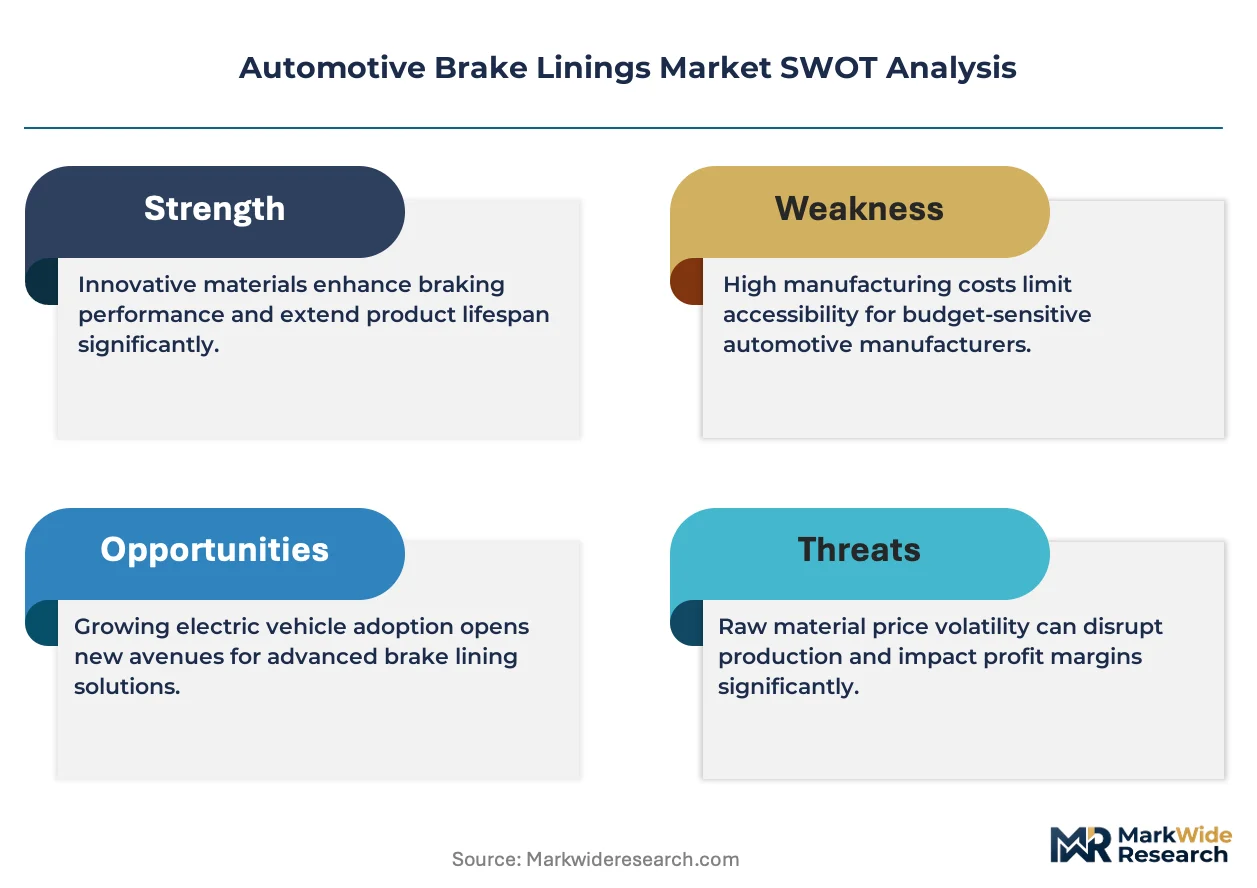
Copper-free formulation mandates across multiple U.S. states are forcing resin matrix redesigns and supplier qualification cycles, compressing development timelines while elevating technical barriers for non-integrated compounders.
Growth Catalysts
- EPA Copper Runoff Restrictions:Washington and California phase-in schedules accelerate non-asbestos formulation adoption across domestic OEM supply chains.
- Commercial Fleet Electrification:Regenerative braking systems on electric trucks extend disc brake service intervals while increasing per-vehicle lining counts.
- Aramid Fiber Processing:Advanced fiber dispersion techniques improve friction coefficient stability under thermal cycling conditions.
Market Restraints
- Phenolic Resin Price Volatility:Petrochemical feedstock fluctuations compress compounder margins on standardized formulations.
- Indian Supply Concentration:ASK Automotive and Rane Brake Lining control domestic OEM qualification pathways, limiting import penetration.
- Copper Substitution Ceiling:Alternative thermal conductors fail to match copper's heat dissipation at sustained high-load operation.
Strategic Opportunities
- Brazil Aftermarket Expansion:ANVISA alignment with UNECE brake standards opens import channels for certified Asian manufacturers.
- Emergency Vehicle Specialization:Fire apparatus and ambulance fleets require high-temperature ceramic-metallic hybrids with extended fade resistance.
- Direct-to-Fleet Distribution:Telematics-enabled inventory management allows compounders to bypass traditional jobber networks.
Industry Challenges
- Dyno Testing Bottlenecks:SAE J2522 and AK-Master protocol backlogs delay new compound approvals by 8-14 months.
- Legacy Drum Brake Integration:Heavy-duty truck fleets running mixed disc-drum configurations require compatible friction coefficients across axle positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Linings Market |
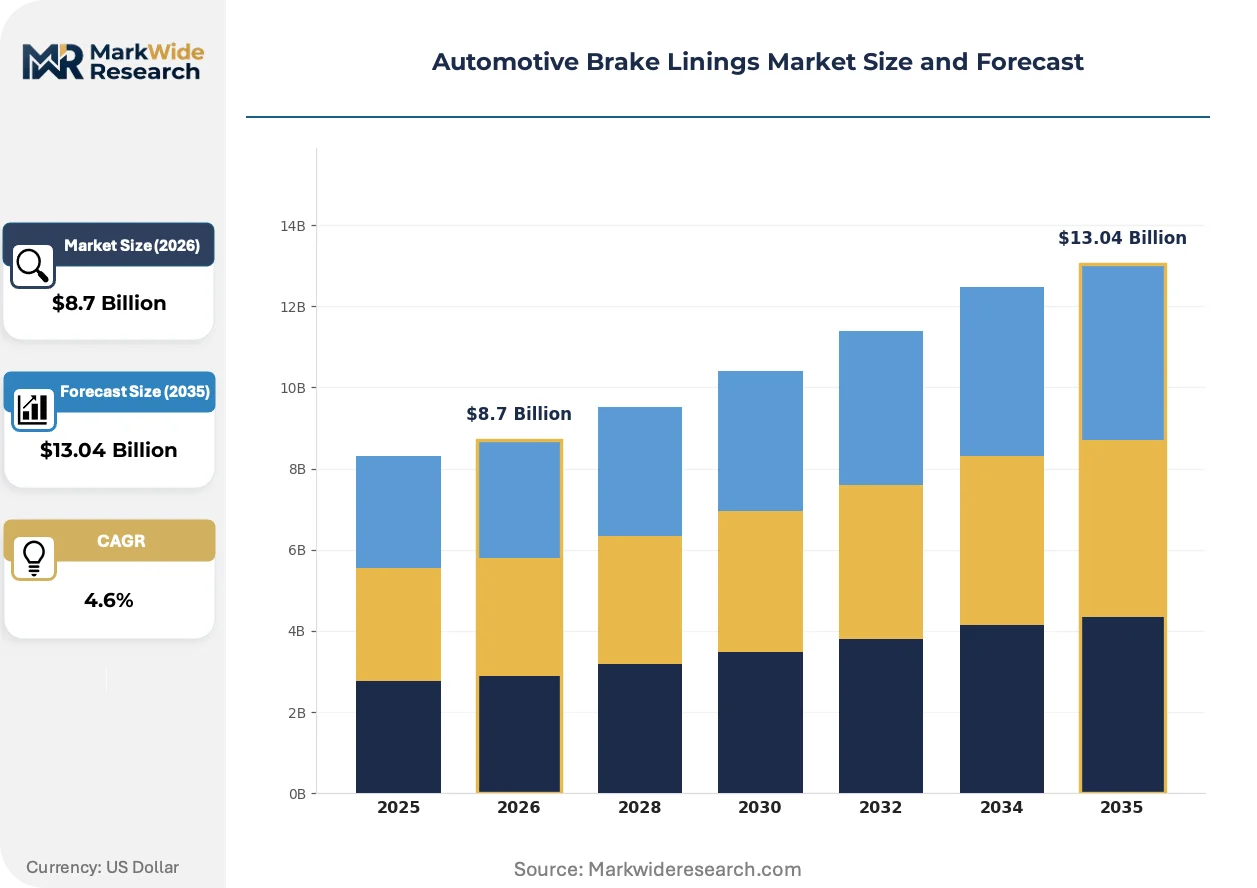
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Metallic, Semi-Metallic, Non-Asbestos End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Emergency Vehicles Application: Disc Brake, Drum Brake, Parking Brake, Anti-Lock Brake Distribution Channel: Direct Sales, Retail Outlets, Online Stores, Distributors |
| Companies Covered | Federal-Mogul Corporation, ASK Automotive Pvt. Ltd., Nisshinbo Holdings Inc., Akebono Brake Industry Co. Ltd., Brembo S.p.A., Miba AG, SGL Group, Sundaram Brake Linings Ltd., Rane Brake Lining Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Linings Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape friction compound portfolios, with thermal performance and environmental compliance now inseparable design parameters.
Ceramic particle reinforcement is overtaking traditional semi-metallic matrices in premium passenger applications. The technology delivers superior thermal stability above 350°C operating temperatures. European OEMs specify ceramic-enhanced compounds for 70% of new performance vehicle platforms. This shift is overtaking legacy aramid-resin blends in high-margin segments while compressing R&D amortization periods for compounders.
REACH Annex XVII restrictions on phenolic resin emissions are forcing European compounders toward water-based curing systems. The regulation mandates volatile organic compound reductions in manufacturing processes. Brake lining producers in Germany and Italy face 2026 compliance deadlines for facility retrofits. Heavy-duty segment suppliers absorb the steepest capital burden given batch size and press cycle requirements.
Fleet maintenance departments now specify certified lining programs with embedded wear sensors and predictive replacement scheduling. The practice displaces reactive jobber purchasing in North American commercial vehicle operations. Large for-hire carriers consolidate supplier relationships to three approved compounders per vehicle platform. This concentration is most visible in U.S. long-haul trucking where total cost-per-mile metrics dominate sourcing decisions.
Automotive Brake Linings Market Segmentation
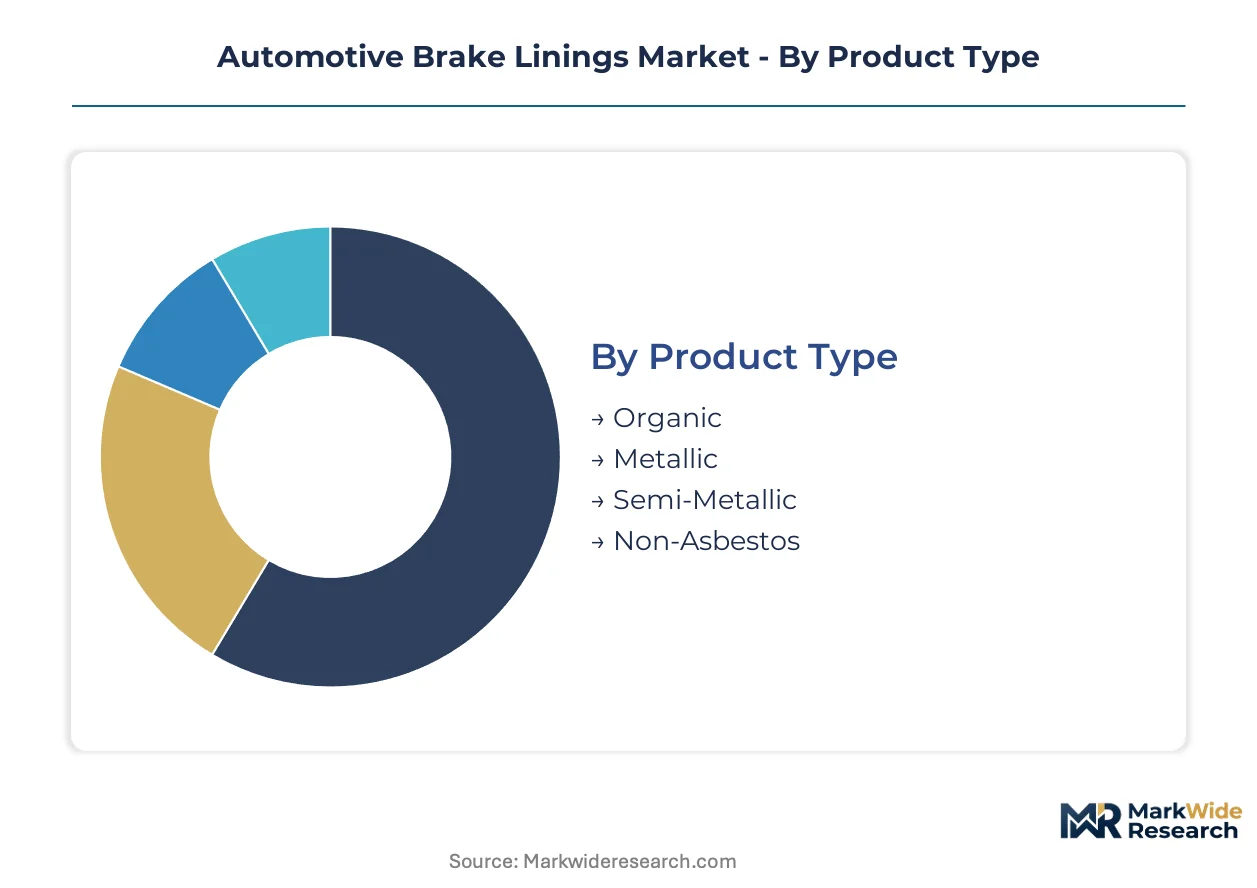
Friction compound selection, application architecture, and channel economics operate as independent decision layers in brake lining procurement. Each segmentation dimension carries distinct margin profiles and qualification barriers that shape supplier strategy.
Product Type:
Material composition determines thermal ceiling, wear rate, and regulatory compliance eligibility across OEM and aftermarket channels.
- Non-Asbestos:Aramid fiber and ceramic particle matrices bonded with phenolic resins dominate new vehicle fitment. Washington and California copper-free mandates accelerate displacement of legacy formulations across domestic OEM supply chains.
- Semi-Metallic:Steel fiber reinforcement delivers friction coefficient stability under sustained high-load braking. Heavy-duty commercial fleets specify these compounds for drum brake applications where thermal mass outweighs NVH considerations.
- Organic:Glass and rubber-modified binders serve economy aftermarket replacement with lower unit costs but reduced fade resistance.
- Metallic:Sintered copper and bronze alloys persist in motorsport and extreme-duty mining applications where operating temperatures exceed 500°C.
Volume sits with Non-Asbestos; growth tilts toward Semi-Metallic as commercial fleet electrification extends per-vehicle lining counts.
End User:
Vehicle category dictates duty cycle severity, replacement frequency, and specification authority centralization.
- Commercial Vehicles:Fleet procurement departments consolidate supplier relationships around total cost-per-mile metrics. Telematics-enabled wear monitoring displaces reactive jobber purchasing in North American long-haul operations.
- Emergency Vehicles:Fire apparatus and ambulance fleets require ceramic-metallic hybrids with extended fade resistance. Specialized high-temperature formulations command premium positioning in this concentrated margin pool.
- Passenger Vehicles:OEM specification locks in compound selection for initial fitment; aftermarket replacement follows price-tier segmentation.
- Motorcycles:Sintered pad architectures dominate performance segments; organic compounds serve commuter categories in India and Southeast Asia.
Procurement authority centralizes with Commercial Vehicles; specification complexity peaks with Emergency Vehicles.
Application:
Brake system architecture determines lining wear rate, replacement accessibility, and formulation compatibility requirements.
- Disc Brake:Higher lining wear rates and replacement frequency generate recurring aftermarket demand. Multiple piston caliper designs increase per-axle lining counts versus drum configurations.
- Drum Brake:Heavy-duty truck fleets running mixed disc-drum configurations require compatible friction coefficients across axle positions. Residual demand concentrates in rear axle and parking brake applications.
- Parking Brake:Mechanical actuation systems specify dedicated compounds with stable holding friction across temperature ranges.
- Anti-Lock Brake:ABS modulation duty cycles demand formulation consistency across repeated pressure pulsation events.
Aftermarket value concentrates in Disc Brake; Drum Brake retains installed base protection in heavy-duty segments.
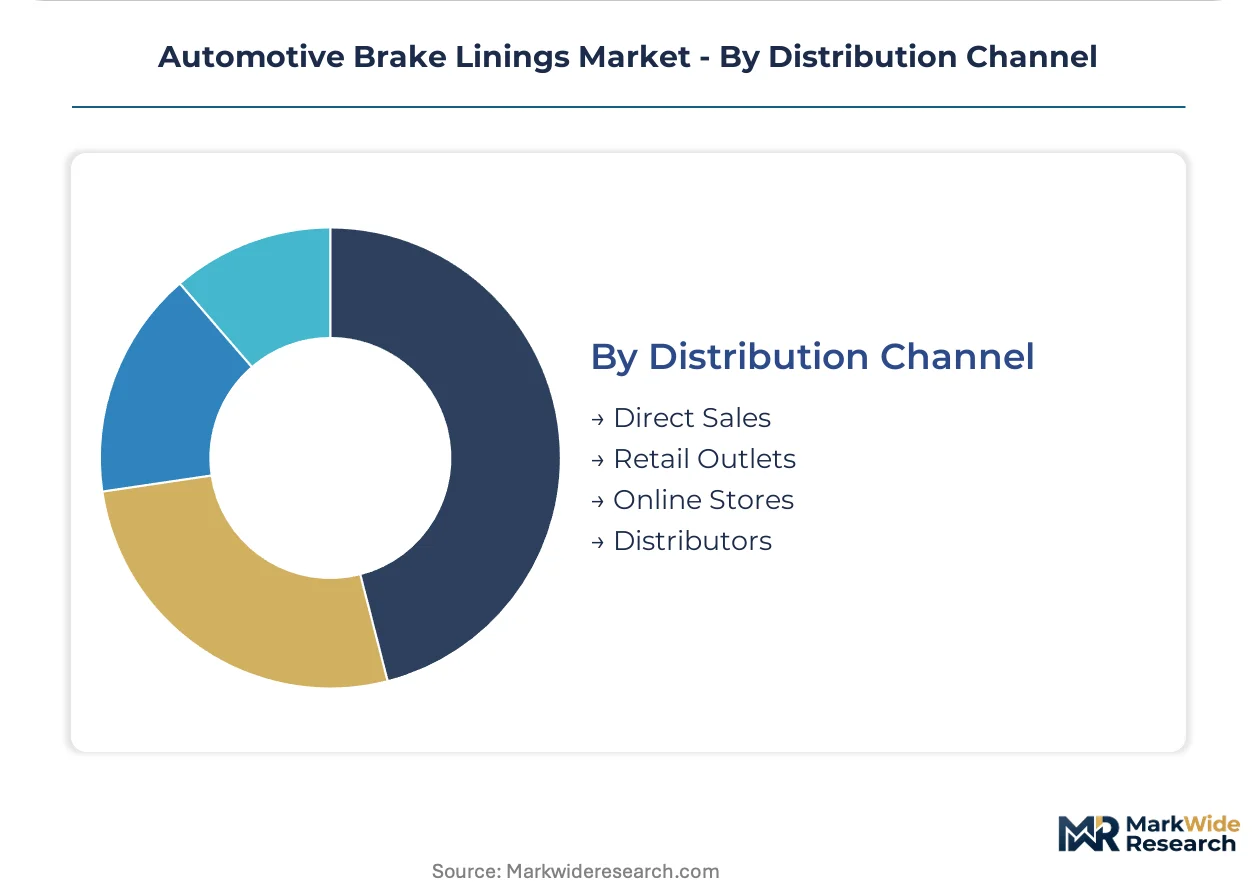
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and inventory velocity constraints.
- Distributors:Jobber networks maintain broad SKU availability for independent repair shops. Inventory carrying costs and technical training investments create regional consolidation patterns.
- Direct Sales:National fleet accounts negotiate multi-year supply agreements with embedded wear sensor integration and predictive replacement scheduling.
- Retail Outlets:Mass merchandisers and auto parts chains compete on price transparency and same-day availability for DIY replacement.
- Online Stores:E-commerce penetration accelerates in standardized passenger vehicle applications where fitment verification tools reduce return rates.
Margin capture favors Direct Sales; transaction volume flows through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive corridor drives North American friction material specification standards through direct OEM engineering relationships. Tier 1 suppliers cluster around Michigan and Ohio to access validation facilities and fleet testing infrastructure. Copper-free mandates in California and Washington propagate formulation requirements across domestic supply chains.
United States
Commercial fleet electrification extends per-vehicle lining counts as regenerative braking systems demand complementary friction materials. NHTSA's Federal Motor Vehicle Safety Standards govern friction performance and labeling requirements across all states. Michigan and Ohio host the densest concentration of brake system engineering centers and dyno testing facilities.
Germany
European OEM specification authority concentrates brake lining qualification decisions in Stuttgart and Munich engineering centers. REACH Annex XVII restrictions on phenolic resin emissions mandate water-based curing system retrofits by 2026. The Baden-Württemberg industrial corridor anchors ceramic particle reinforcement R&D for premium passenger applications.
India
Domestic OEM qualification pathways concentrate procurement authority with ASK Automotive and Rane Brake Lining. BIS certification mandates and ARAI test protocols determine market access for imported lining suppliers. Tamil Nadu and Maharashtra manufacturing clusters serve both domestic aftermarket channels and export markets.
China
Dual carbon goals accelerate copper-free formulation adoption across domestic OEM supply chains. MIIT standards on friction material emissions shape manufacturing process requirements. Yangtze River Delta production bases supply both domestic vehicle assembly and aftermarket replacement demand.
Brazil
ANVISA alignment with UNECE brake standards opens import channels for certified Asian manufacturers. Heavy-duty commercial fleet expansion drives aftermarket replacement volume in São Paulo and Minas Gerais logistics corridors. Local assembly requirements favor regional compounders with in-house resin blending capabilities.
Automotive Brake Linings Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and thermal performance certification tiers. The vendor base organizes around integrated resin compounders, specialized friction material fabricators, and diversified automotive component conglomerates. Three strategic archetypes dominate: captive resin producers controlling phenolic matrix supply, ceramic formulation specialists serving performance segments, and scale-driven compounders supplying fleet aftermarket channels. Competitive moves concentrate on backward integration into fiber processing and direct-to-fleet distribution partnerships bypassing traditional jobber networks.
Among European-based fabricators, Brembo S.p.A. and Miba AG exemplify premium-tier positioning through motorsport-derived and heavy-duty specialization respectively. Federal-Mogul Corporation anchors North American heavy-duty segment supply through captive manufacturing infrastructure. These three represent distinct competitive vectors: performance application authority, industrial scale coverage, and integrated material science capability.
| Leading Market Players |
|---|
| Federal-Mogul Corporation |
| ASK Automotive Pvt. Ltd. |
| Nisshinbo Holdings Inc. |
| Akebono Brake Industry Co. Ltd. |
| Brembo S.p.A. |
| Miba AG |
| SGL Group |
| Sundaram Brake Linings Ltd. |
| Rane Brake Lining Limited |
| Others |
Supply Flow & Price Mechanics
Premium-ceramic versus commodity-organic formulation divergence manifests in both pricing power and supply chain configuration across the automotive brake linings market. Washington and California copper-free mandates compress margins on legacy semi-metallic tiers while elevating certified non-asbestos compounds to premium positioning. Tier 1 OEM supply agreements tether pricing to friction coefficient consistency guarantees, whereas aftermarket jobber channels compete on per-unit cost transparency with minimal technical service bundling.
Pricing Analysis
Value-based pricing anchors on thermal fade resistance certification and fleet uptime guarantees rather than raw material weight. Three-tier pricing structure across premium, standard, and economy levels separates motorsport-derived ceramic formulations from commercial fleet semi-metallics and DIY organic replacements. Cost compression in commodity tiers intensifies because phenolic resin feedstock volatility erodes compounder margins. Fleet procurement departments demonstrate lowest price sensitivity given total cost-per-mile metrics, while independent repair shops exhibit acute sensitivity to per-axle replacement costs.
Supply Chain Analysis
Regional distribution centers in Michigan, Stuttgart, and Tamil Nadu anchor hub-and-spoke patterns for friction material logistics. Manufacturing concentrates in Germany, India, and China where integrated phenolic resin production and fiber processing capabilities cluster. Raw material dependencies draw from aramid fiber suppliers, copper-free thermal conductor sources, and petrochemical-based resin feedstocks. Single-source vulnerability in specialty ceramic particle supply creates qualification bottlenecks for new compound approvals. Distribution runs through authorized Tier 1 supplier networks for OEM fitment and fragmented jobber channels for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive brake linings market sits in a technology-transition phase as copper-free ceramic formulations displace legacy semi-metallic matrices under tightening environmental mandates. This substitution wave reshapes competitive positioning across formulation tiers and supply chain qualification pathways.
For Market Incumbents: To counter copper substitution ceiling effects on thermal performance, compounders should deepen backward integration into aramid fiber processing and captive phenolic resin blending. Securing direct-to-fleet distribution partnerships bypasses margin-stripping jobber networks while embedding telematics-enabled wear sensors locks in multi-year supply agreements with large for-hire carriers. For New Entrants and Emerging Players: The price-point gap between Brembo-tier ceramic premiums and unbranded organic economy pads creates entry space for mid-tier certified non-asbestos specialists. Brazil's ANVISA-UNECE alignment offers the most penetrable geography for Asian manufacturers with existing copper-free formulations. A fleet-certification-first go-to-market angle sidesteps entrenched OEM qualification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with integrated resin compounders given REACH Annex XVII water-based curing mandates and EPA copper runoff phase-ins as simultaneous margin-expansion catalysts. Long-term viability favors facilities with in-house fiber dispersion and press-curing capabilities over toll-compounding models. The signal to watch is SAE J2522 dyno testing protocol backlog resolution as inflection indicator for new compound approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Free Formulation Retrofit | California and Washington mandates force resin matrix redesigns across domestic OEM supply chains. |
| Direct-to-Fleet Distribution Partnership | Telematics-enabled inventory management displaces traditional jobber networks in North American long-haul operations. |
| Aramid Fiber Processing Integration | Captive fiber dispersion capabilities improve friction coefficient stability under thermal cycling conditions. |
| Emergency Vehicle Certification Program | Fire apparatus and ambulance fleets command premium positioning for high-temperature ceramic-metallic hybrids. |
| Water-Based Curing System Adoption | REACH Annex XVII compliance deadlines in Germany and Italy require facility retrofit capital deployment. |
Methodological Framework
Trade association publications, customs and tariff databases, and vehicle production registries formed the secondary backbone for market sizing and competitive landscape mapping. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and fleet maintenance directors validated formulation adoption trends and pricing dynamics. Bottom-up triangulation across friction material consumption by vehicle class and top-down reconciliation against brake system assembly outputs anchored volume estimates.
Historical trendline analysis of non-asbestos formulation penetration, disc brake fitment rates, and commercial fleet electrification patterns informed projection mechanics across the analysis window. Segmentation modeling incorporated product type, end user category, brake system architecture, and distribution channel dimensions with regional production cluster overlays. CAGRs derived from regression analysis of replacement frequency trends, per-vehicle lining count evolution, and regulatory compliance cost pass-through assumptions.
Inputs from EPA and NHTSA regulatory filings were available through the study window; gaps in state-level copper-free mandate enforcement timelines introduce uncertainty bands around adoption velocity assumptions. Forecasts reflect documented assumptions regarding phenolic resin price stability and dyno testing protocol clearance rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Industrial V Belt Market
Automotive Parts
Struts System Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
Exhaust Hanger Material Market
Automotive Parts
Brake Pad Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Automotive Dynamic Chassis Control System Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Needle Roller Bearings Market