
 Automotive Heaters Market | 2026-2036
Automotive Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Heaters Market Analytics
The capability gap between capital-intensive integrated thermal system suppliers and component-focused manufacturers is redrawing competitive boundaries in automotive heating. Denso Corporation leverages its in-house semiconductor and sensor portfolio to control full thermal management architectures. MAHLE anchors its position through sustained R&D investment in heat pump and electric compressor integration. Webasto differentiates by specializing in aftermarket and auxiliary heating solutions for commercial vehicle segments.
An automotive heater is a thermal management device engineered to regulate cabin and powertrain temperatures through heat exchange, resistive elements, or refrigerant-based heat pump cycles, typically operating within voltage ranges from 12V in conventional vehicles to 800V in battery-electric platforms. Its primary industrial purpose is to ensure occupant comfort, prevent battery thermal runaway, and maintain optimal operating efficiency for electric drivetrains. Electric heaters are capturing expanding share as OEMs phase out engine-dependent thermal sources, while ceramic heater variants command margin premiums due to faster response times and reduced energy draw. Forced-air technology dominates volume installations across mass-market platforms, though infrared configurations are gaining traction in premium cabin comfort applications.
The EPA and NHTSA in the United States enforce fuel economy and emissions standards that directly incentivize efficient thermal systems, while the EU Green Deal and F-Gas Regulation in Europe mandate refrigerant transitions and carbon footprint reductions across vehicle life cycles. These frameworks compel suppliers to redesign heater architectures around lower-GWP working fluids and electrified heat sources. Stakeholders must monitor how battery-electric platform thermal budgets reshape procurement specifications for heating subsystems.
Market Dynamics
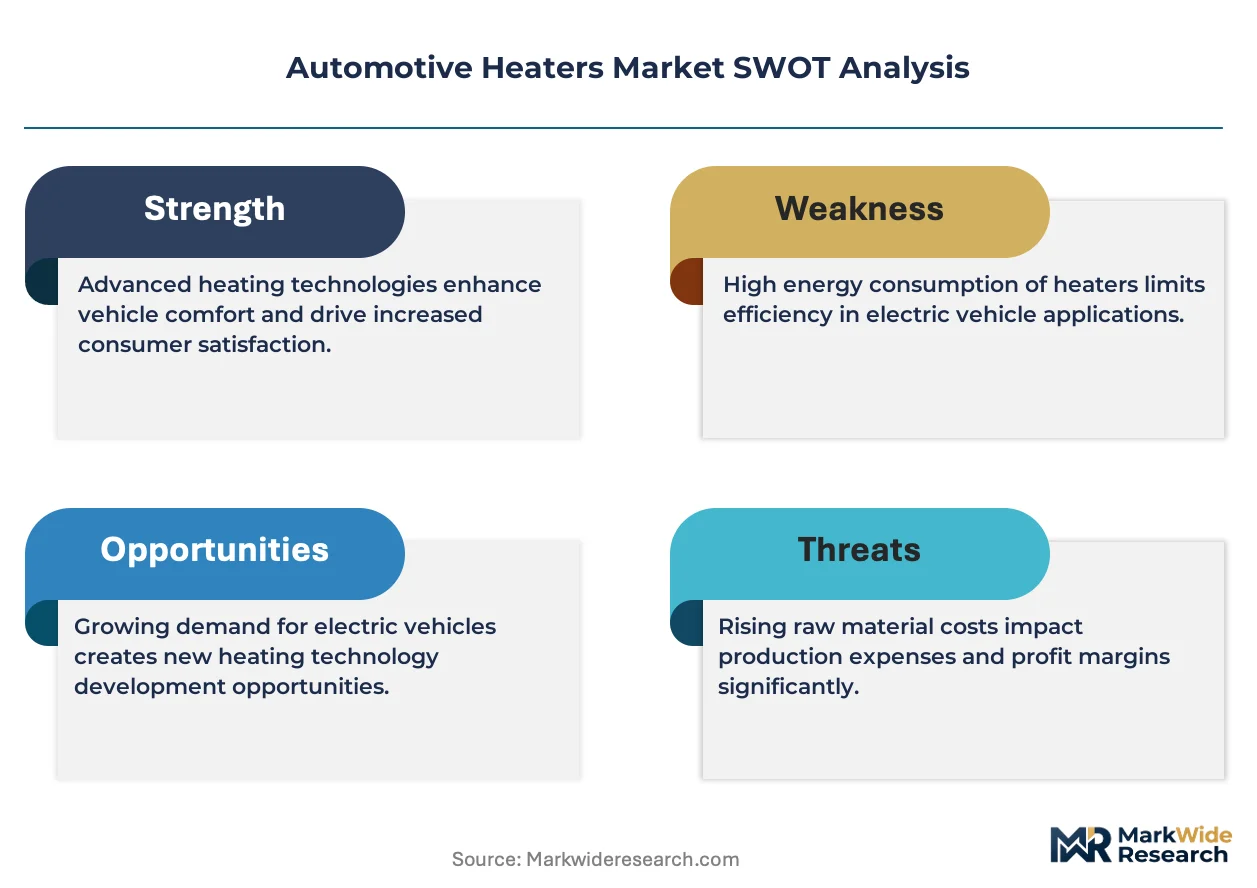
The transition from engine-waste-heat dependency to electrified thermal architectures is compressing supplier margins while opening premium positions for component specialists with high-voltage expertise.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants in heat pump systems is accelerating OEM procurement of next-generation thermal components across German and French automotive manufacturing clusters.
- Battery-electric platforms:Passenger and commercial EV fleets require independent cabin heating systems, expanding addressable component demand beyond traditional engine-coupled architectures.
- Ceramic PTC elements:Faster thermal response and reduced energy draw in 800V architectures command procurement preference from premium EV manufacturers targeting extended-range performance.
Market Restraints
- Semiconductor input volatility:Power electronics and sensor substrates face price instability, compressing margins for integrated thermal system suppliers dependent on captive semiconductor capacity.
- Refrigerant supply concentration:Lower-GWP working fluid production clusters in select chemical manufacturing regions, creating procurement bottlenecks for heat pump system assemblers.
- Heat pump cold-weather performance:Coefficient-of-degradation below minus fifteen degrees Celsius limits deployment latitude in Nordic and continental winter markets without auxiliary resistive backup.
Strategic Opportunities
- Commercial vehicle auxiliary heating:Sleeper cab and cargo compartment thermal management remains underpenetrated by electrified solutions, offering white space for specialized suppliers.
- Infrared cabin comfort:Premium passenger segments in Japan and South Korea are adopting radiant heating panels for zoned thermal control, creating technology-differentiation openings.
- US Inflation Reduction Act:Domestic content incentives for EV component manufacturing are reshaping supplier location decisions and local procurement requirements.
Industry Challenges
- High-voltage safety certification:800V system validation protocols require extended testing cycles, delaying product launch timelines and compressing development windows.
- Legacy thermal architecture integration:PHEV platforms must accommodate dual heating modes, multiplying system complexity and supplier coordination requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Heaters Market |
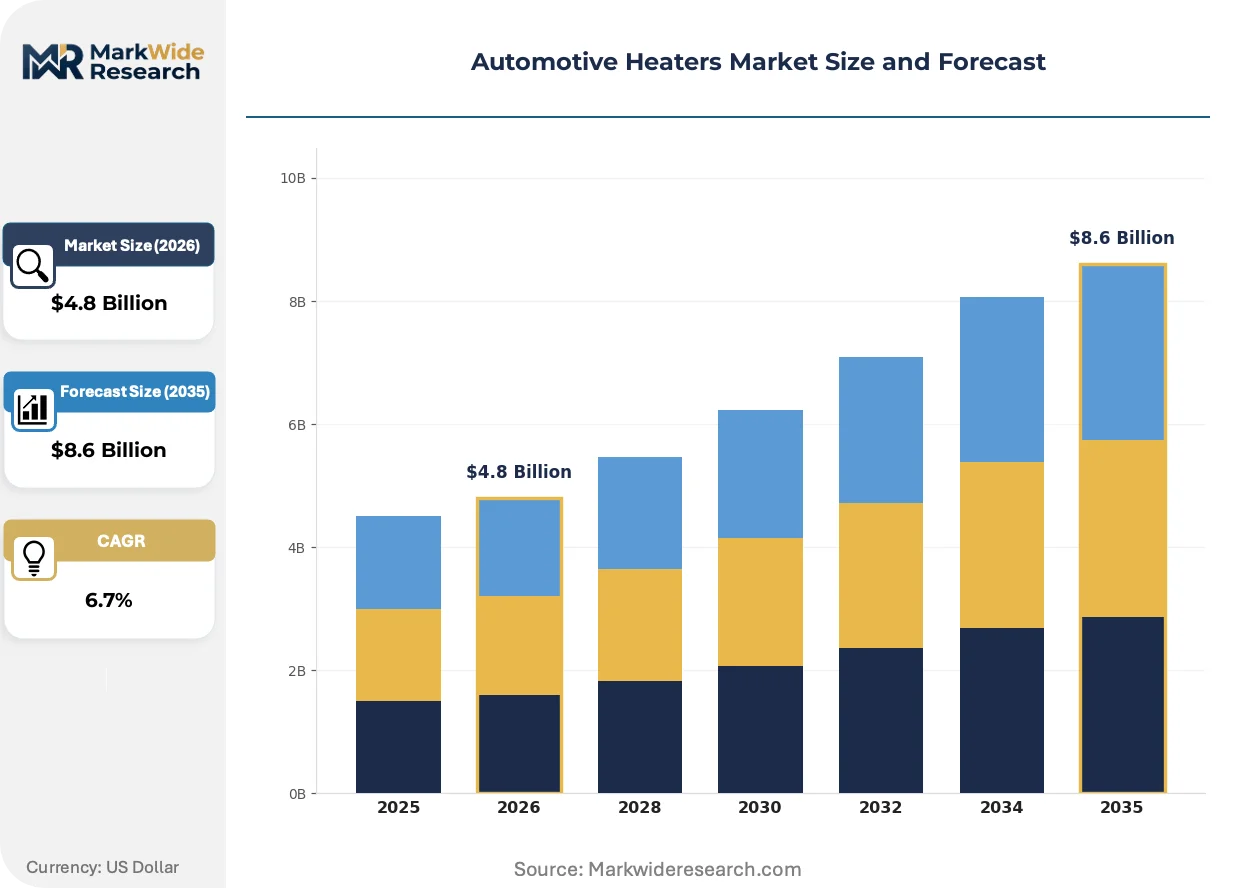
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Heaters, Ceramic Heaters, Electric Heaters, Exhaust Heaters End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Dealerships Fuel Type: Gasoline, Diesel, Electric, Hybrid Technology: Infrared, Induction, Radiant, Forced Air |
| Companies Covered | Denso Corporation, MAHLE, Webasto, Eberspächer, BorgWarner, Valeo Group, Hanon Systems, Sanden Holdings, GENTHERM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Heaters Market Evolving Landscape
Electrification is fragmenting thermal system architectures into discrete, swappable sub-assemblies while regulatory chemistry mandates and buyer procurement consolidation reshape competitive positioning.
Heat pump thermal management is decomposing the traditional engine-coupled heating monopoly in battery-electric platforms. German and Korean OEMs are specifying refrigerant-based cabin heating for new EV architectures launching through 2027. This technology shift is compressing demand for resistive-only systems while expanding addressable market for compressor and valve specialists with refrigerant circuit expertise.
Europe's F-Gas Regulation is forcing refrigerant transitions across vehicle life-cycle carbon accounting. The mandate requires heat pump suppliers to redesign architectures around lower-GWP working fluids by specified phase-down deadlines. German automotive OEMs and their tier-one thermal suppliers are absorbing the highest compliance costs, accelerating vertical integration into refrigerant handling and recovery services.
Fleet procurement consolidation is concentrating specification authority among select leasing and rental operators with multi-thousand-unit thermal system refresh cycles. These buyers are unbundling after-sales service contracts from initial hardware procurement, favoring suppliers with predictive maintenance platforms and regional parts distribution density. This pattern is most visible in German and Dutch commercial vehicle leasing markets where total-cost-of-ownership modeling dominates supplier selection.
Automotive Heaters Market Segmentation
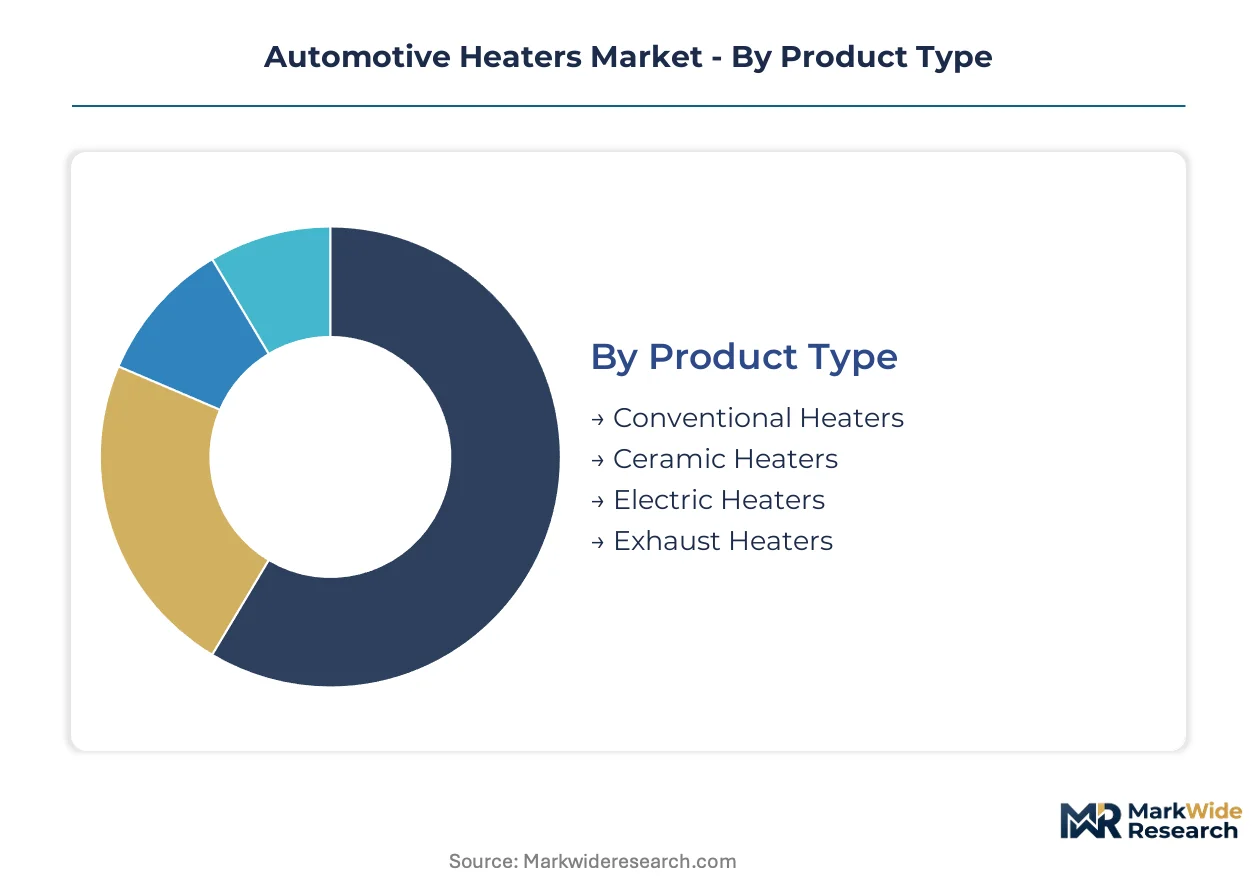
Segmentation in automotive heating reveals how procurement authority and technology maturity diverge across customer channels. OEMs and tier suppliers source integrated thermal architectures through long-term platform contracts, while aftermarket channels favor modular replacement components with shorter lead times.
Product Type:
Channel mix varies sharply by heater technology — ceramic and electric variants flow predominantly through OEM direct procurement for new EV platforms, while conventional and exhaust heaters concentrate in aftermarket channels serving legacy internal combustion fleets.
- Ceramic Heaters:Positive temperature coefficient (PTC) elements deliver rapid thermal response with self-regulating resistance properties. German and Korean OEMs specify these for 800V battery-electric architectures where cabin heating must operate independently of drivetrain waste heat. F-Gas Regulation compliance costs favor ceramic systems over refrigerant-dependent alternatives in European procurement.
- Electric Heaters:Resistive wire or film-based elements convert electrical energy directly to thermal output across 12V to 800V operating ranges. Battery-electric commercial fleets in North America and China specify these for auxiliary cabin heating where heat pump cold-weather performance proves inadequate. NHTSA safety certification requirements extend validation timelines for high-voltage variants.
- Conventional Heaters:Engine-coupled coolant-based systems leveraging waste heat from internal combustion powertrains.
- Exhaust Heaters:Heat exchanger units capturing thermal energy from exhaust gas streams for supplemental cabin warming.
Conventional heaters dominate installed base. Ceramic heaters are where expansion concentrates.
End User:
Cost tier stratification separates specification authority — OEMs and vehicle assemblers command premium pricing for integrated thermal architectures, while aftermarket providers and dealerships compete on replacement part velocity and regional inventory density.
- OEMs:Original equipment manufacturers specify thermal systems during vehicle platform development, locking in multi-year supply agreements with integrated component suppliers. European and Japanese OEMs consolidate procurement through captive tier-one thermal specialists with full-architecture design capability.
- Vehicle Assemblers:Contract manufacturing operations for emerging EV brands source modular heating sub-assemblies from specialist suppliers. Chinese and Indian EV assemblers favor this procurement model to accelerate platform launch timelines without vertical integration.
- Aftermarket Providers:Independent distributors and service chains supplying replacement heaters for out-of-warranty vehicles.
- Dealerships:Authorized service networks performing warranty repairs and manufacturer-specified thermal system replacements.
OEMs anchor premium thermal system revenue. Vehicle assemblers are climbing the fastest as EV platform outsourcing accelerates.
Fuel Type:
Application requirements dictate heater architecture — electric and hybrid platforms demand independent thermal sources, while gasoline and diesel systems retain engine-waste-heat dependency with auxiliary electrification.
- Electric:Battery-electric platforms require fully independent cabin heating systems with no engine waste heat available. EPA fuel economy standards and EU fleet CO2 mandates accelerate OEM transition to these architectures, expanding addressable market for high-voltage thermal component specialists.
- Hybrid:Dual-mode powertrains combine engine-coupled heating with electric auxiliary systems for engine-off cabin conditioning. Japanese and Korean OEMs lead hybrid thermal system integration, specifying compact heat pump modules for plug-in variants.
- Gasoline:Internal combustion engines with conventional coolant-based cabin heating systems.
- Diesel:Compression-ignition powertrains with higher thermal efficiency requiring supplemental heating for rapid cabin warmup.
Gasoline systems retain largest installed base. Electric fuel type platforms are gaining share fastest as thermal architecture procurement shifts.
Technology:
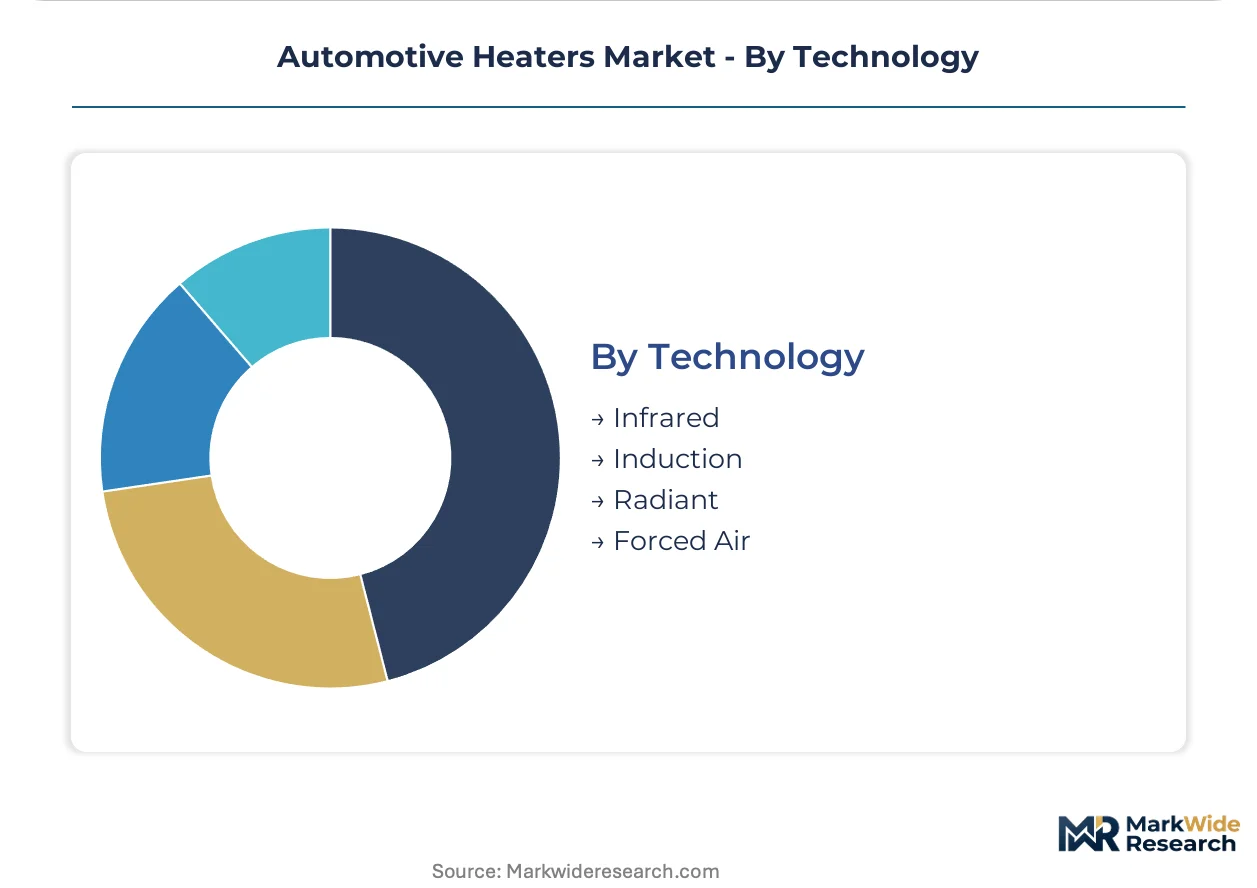
Margin concentration follows performance differentiation — infrared and radiant technologies command premium positioning in luxury cabin comfort, while forced air and induction systems compete on manufacturing scale and unit cost.
- Forced Air:Blower-driven convective heating distributes warmed air through ducted cabin ventilation networks. Mass-market passenger platforms across German, Japanese, and US manufacturing clusters specify these for cost-optimized thermal management with proven reliability metrics.
- Infrared:Electromagnetic radiation panels provide zoned radiant heating without air circulation, reducing energy draw and improving perceived comfort. Premium Japanese and South Korean OEMs deploy these in flagship EV sedans for rear-seat passenger thermal control.
- Radiant:Surface-based heat distribution through warmed panels or seating elements for localized comfort.
- Induction:Electromagnetic field heating of conductive elements for rapid thermal response in specialized applications.
Forced air dominates volume installations. Infrared technology represents the steepest expansion trajectory in premium cabin comfort applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs command pricing premiums for integrated thermal architectures, while Chinese EV assemblers compress component costs through modular procurement strategies. This asymmetry redistributes supplier margins across manufacturing clusters. Regulatory chemistry mandates and battery-electric platform rollouts are reshaping regional competitive positioning.
Germany
BMW and Volkswagen Group procurement of 800V ceramic PTC systems drives premium thermal component demand. The F-Gas Regulation accelerates refrigerant transition timelines for heat pump suppliers. Stuttgart and Munich manufacturing clusters concentrate tier-one thermal system integration for next-generation EV platforms.
China
BYD and NIO battery-electric fleets require independent cabin heating without engine waste heat. MIIT domestic content incentives favor local component sourcing for thermal management sub-assemblies. Shenzhen and Shanghai EV manufacturing hubs are scaling high-voltage heater production for export and domestic platforms.
United States
General Motors and Ford EV truck platforms specify resistive auxiliary heating for cold-weather performance gaps. NHTSA safety certification protocols extend validation cycles for high-voltage thermal systems. Michigan and Tennessee automotive corridors concentrate thermal supplier engineering centers near OEM platform development.
Japan
Toyota and Honda hybrid thermal integration demands compact dual-mode heating architectures. METI carbon neutrality roadmaps mandate efficiency improvements in passenger vehicle thermal management. Nagoya and Tokyo manufacturing clusters specialize in heat pump compressor and valve component production.
South Korea
Hyundai and Kia EV platforms specify infrared radiant panels for premium cabin zoned heating. MFDS automotive component safety standards align with international thermal system certification. Seoul and Busan industrial zones concentrate ceramic heater element manufacturing for 800V architectures.
Automotive Heaters Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered supplier structure. Integrated thermal system specialists with captive semiconductor capacity occupy premium platform positions, while component-focused manufacturers compete on unit economics for modular procurement channels. Three archetypes dominate: full-architecture designers, high-voltage component specialists, and aftermarket service providers. M&A activity concentrates among tier-one thermal suppliers seeking refrigerant circuit expertise, while strategic partnerships proliferate between heater element producers and battery-electric platform developers.
Among Japanese and German integrated suppliers, Denso Corporation and MAHLE occupy positions as full-architecture providers with in-house control over thermal management design. Webasto represents the specialist archetype focused on auxiliary and aftermarket heating applications. These three companies exemplify how geographic origin and organizational structure correlate with competitive positioning in electrified thermal systems.
| Leading Market Players |
|---|
| Denso Corporation |
| MAHLE |
| Webasto |
| Eberspächer |
| BorgWarner |
| Valeo Group |
| Hanon Systems |
| Sanden Holdings |
| GENTHERM |
| Others |
Value Network & Pricing Analysis
800V ceramic PTC manufacturing scale in South Korean and German production clusters compresses unit costs for high-voltage architectures while establishing price floors that smaller component specialists cannot match. This concentration of thermal element capacity across Stuttgart and Seoul industrial zones simultaneously strengthens procurement leverage for OEM platform contracts and squeezes margin recovery for modular aftermarket suppliers.
Pricing Analysis
Configured-to-order pricing for 800V ceramic PTC systems commands substantial premiums over standard resistive heater configurations. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation driven by certification grade (ISO 26262 functional safety tier) and volume scale commitments. Cost compression in mass-market forced-air systems is intensifying because Chinese EV assemblers are consolidating procurement around standardized thermal sub-assemblies. Fleet leasing operators exhibit highest price sensitivity, while premium German OEMs prioritize thermal response performance over unit economics.
Supply Chain Analysis
Inventory lead times for semiconductor power modules and ceramic substrate materials have extended from standard procurement cycles, constraining heater controller availability. Manufacturing concentrates in Germany, China, and South Korea, with raw material dependencies spanning rare-earth elements for PTC ceramics, copper for high-voltage wiring harnesses, and silicon carbide substrates for power electronics. Single-source vulnerability in refrigerant-grade aluminum heat exchanger supply creates exposure for heat pump system assemblers. Distribution runs through captive tier-one thermal specialists for OEM channels and independent aftermarket distributors for replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive heaters market functions as a service-attach opportunity where predictive maintenance platforms and thermal system refresh contracts are expanding faster than discrete hardware shipments. Fleet operators are unbundling after-sales service from initial procurement, creating recurring-revenue layers that outpace unit sales growth.
For Market Incumbents: Fortify platform lock-in through backward integration into refrigerant handling services and captive semiconductor capacity for 800V controller production. The threat of modular procurement strategies from Chinese EV assemblers demands defensive investment in full-architecture design capability alongside certification depth for EU F-Gas Regulation compliance. For New Entrants and Emerging Players: Differentiate on cold-weather performance specialization for Nordic commercial vehicle fleets where heat pump coefficient-of-degradation creates auxiliary heating white space. Target sleeper cab thermal management as the most penetrable segment, leveraging direct fleet operator relationships as the primary go-to-market angle against established tier-one incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated thermal system specialists with predictive maintenance platforms and regional parts distribution density. Over the medium-term horizon, acquisition targets should display refrigerant circuit expertise alongside high-voltage safety certification infrastructure. Monitor heat pump cold-weather performance degradation thresholds as the critical inflection signal for auxiliary resistive heating demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | BMW and Volkswagen Group consolidation around 800V architectures reduces supplier qualification overhead for ceramic PTC specialists. |
| Battery Supply Agreement | Thermal management subsystem procurement is increasingly bundled with cell supplier contracts for integrated pack conditioning. |
| Software-Defined Vehicle Investment | OEMs are specifying over-the-air thermal calibration updates, shifting value toward heater controller firmware developers. |
| Geographic Manufacturing Footprint | US Inflation Reduction Act domestic content incentives are relocating heater assembly capacity to Michigan and Tennessee corridors. |
| Charging Infrastructure Partnership | Pre-conditioning thermal systems at fast-charging stations extends battery range, creating alliance opportunities between heater suppliers and charging network operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, OEM supplier disclosure filings, and EU regulatory chemistry mandates. Interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and thermal system R&D directors were synthesized with bottom-up component demand modeling and top-down vehicle production forecasts.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the projection horizon. CAGRs were derived from triangulating unit shipment trajectories against average selling price evolution, incorporating battery-electric platform rollout schedules, refrigerant transition timelines under EU F-Gas Regulation, and commercial fleet electrification intensity as automotive-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EV adoption rates, stable semiconductor supply availability, or unchanged regulatory chemistry phase-down schedules would require recalibration. Forecasts reflect documented assumptions regarding platform standardization timelines and thermal architecture procurement consolidation patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Automotive Center Stack Display Market