
 Constant Velocity Joint Market | 2026-2036
Constant Velocity Joint Market Size, Share, and Industry Trends Forecast 2026-2036
Constant Velocity Joint Market Insights
A widening capital-intensity divergence between forged-component specialists and assembly-focused suppliers is rotating competitive advantage toward players with in-house heat-treatment and precision-machining capabilities. GKN Automotive leverages captive forging operations across European and Chinese plants to sustain margin control on ball-type units. NTN Corporation anchors its position through integrated bearing-to-joint production in Japan and Thailand. JTEKT Corporation differentiates via torque-vectoring compatible joint architectures for hybrid drivetrains.
A constant velocity joint transmits rotational power between two shafts at variable angles while maintaining uniform angular velocity, typically incorporating six precision-ground steel balls housed in a spherical inner race and grooved outer race lubricated by molybdenum-disulfide grease. Ball-type configurations dominate passenger vehicle front-wheel-drive architectures due to their angular flexibility up to 47 degrees and tolerance for plunge movement during suspension travel. Tripod-type joints occupy the inboard position on transverse drivetrains where plunge capacity exceeds angular demand. Steel alloy materials retain the largest volume share, though aluminum variants are penetrating premium EV platforms seeking unsprung mass reduction.
NHTSA crashworthiness standards and EPA corporate average fuel economy mandates in the United States compel lighter, more efficient drivetrain components. China's MIIT enforces GB standards for new energy vehicle component durability that directly specify joint lifecycle testing protocols. The EU's REACH regulation restricts certain lubricant additives, forcing reformulation of joint greases. Stakeholders must monitor how platform-sharing agreements between legacy OEMs and EV-native manufacturers reshape specification standardization and procurement consolidation timelines.
Market Dynamics
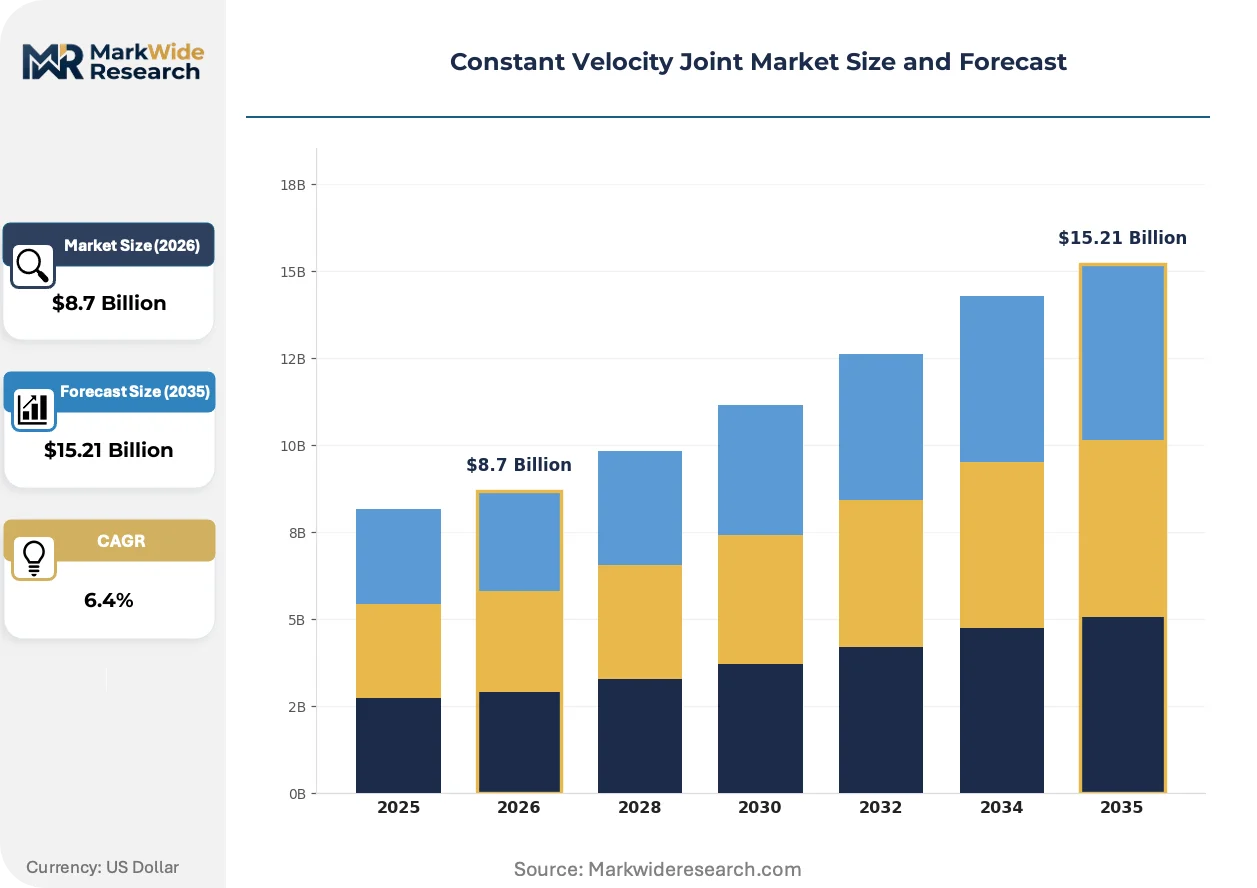
Electric vehicle platform architectures are compressing joint specification cycles from legacy 7-year vehicle programs to 3-year EV refresh timelines, forcing suppliers to front-load R&D amortization across shorter production runs.
Growth Catalysts
- EPA Corporate Average Fuel Economy mandates:NHTSA-aligned efficiency targets compel OEMs to specify lighter, lower-friction joint designs that reduce parasitic driveline losses.
- China MIIT GB standards for NEV durability:Mandatory lifecycle testing protocols for new energy vehicle joints create certified demand pools for qualified suppliers.
- Aluminum alloy penetration:Premium EV platforms specify aluminum CVJ variants to trim unsprung mass, opening material substitution revenue streams.
Market Restraints
- Alloy steel price volatility:Nickel and chromium input cost swings compress forging margins on ball-type units during contract lock-in periods.
- Heat-treatment capacity concentration:Precision induction hardening equipment clusters in Germany and Japan, creating geographic supply bottlenecks for tier-two assemblers.
- REACH lubricant additive restrictions:ECHA-mandated grease reformulation raises R&D compliance costs without immediate performance equivalence.
Strategic Opportunities
- India PLI scheme for auto components:Domestic production-linked incentives attract joint assembly investment to serve emerging EV manufacturing clusters.
- Torque-vectoring joint architectures:Hybrid drivetrain electrification creates specification white space for joints managing bidirectional torque flow.
- Direct-to-fleet channel development:Commercial vehicle electrification opens procurement relationships bypassing traditional tiered supply hierarchies.
Industry Challenges
- Precision grinding skill scarcity:Ball groove finishing tolerances below 5 microns require specialized machinist training pipelines that regional labor markets underproduce.
- Platform-sharing integration complexity:Legacy OEM-EV native partnerships force joint suppliers to reconcile incompatible specification databases and validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Constant Velocity Joint Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball-Type, Tripod-Type, Double-Cardan, Plunging-Type Material: Steel Alloy, Aluminum, Composite, Hardened Metal Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Motorcycles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Repair Workshops |
| Companies Covered | GKN Automotive, American Axle & Manufacturing, NTN Corporation, JTEKT Corporation, Dana Incorporated, Schaeffler AG, SKF, Nexteer Automotive, NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Constant Velocity Joint Market Trends and Innovations
Additive manufacturing of joint cage prototypes is compressing design iteration cycles from months to weeks, enabling faster geometry optimization for EV-specific torque profiles.
Cross-roller bearing integration into CVJ outer races is decomposing the traditional separation between joint and wheel bearing functions. Premium EV platforms adopt these consolidated modules to reduce part count and assembly labor. Suppliers with captive bearing production lines capture margin that would otherwise flow to tier-two bearing specialists.
EU REACH regulation on persistent organic pollutants forces molybdenum-disulfide grease reformulation across all European-assembled vehicles. Joint lubricant suppliers invest in calcium-sulfonate complex alternatives that maintain friction coefficients under high-angle articulation. The compliance timeline compresses most severely for suppliers serving multi-brand platform programs with divergent certification schedules.
Fleet operators now specify joint lifecycle cost rather than unit price in procurement tenders. Commercial EV buyers prioritize predictive maintenance data access over traditional warranty terms. This preference shift concentrates most visibly in North American last-mile delivery vehicle segments where uptime metrics dominate total cost of ownership calculations.
Constant Velocity Joint Market Segmentation
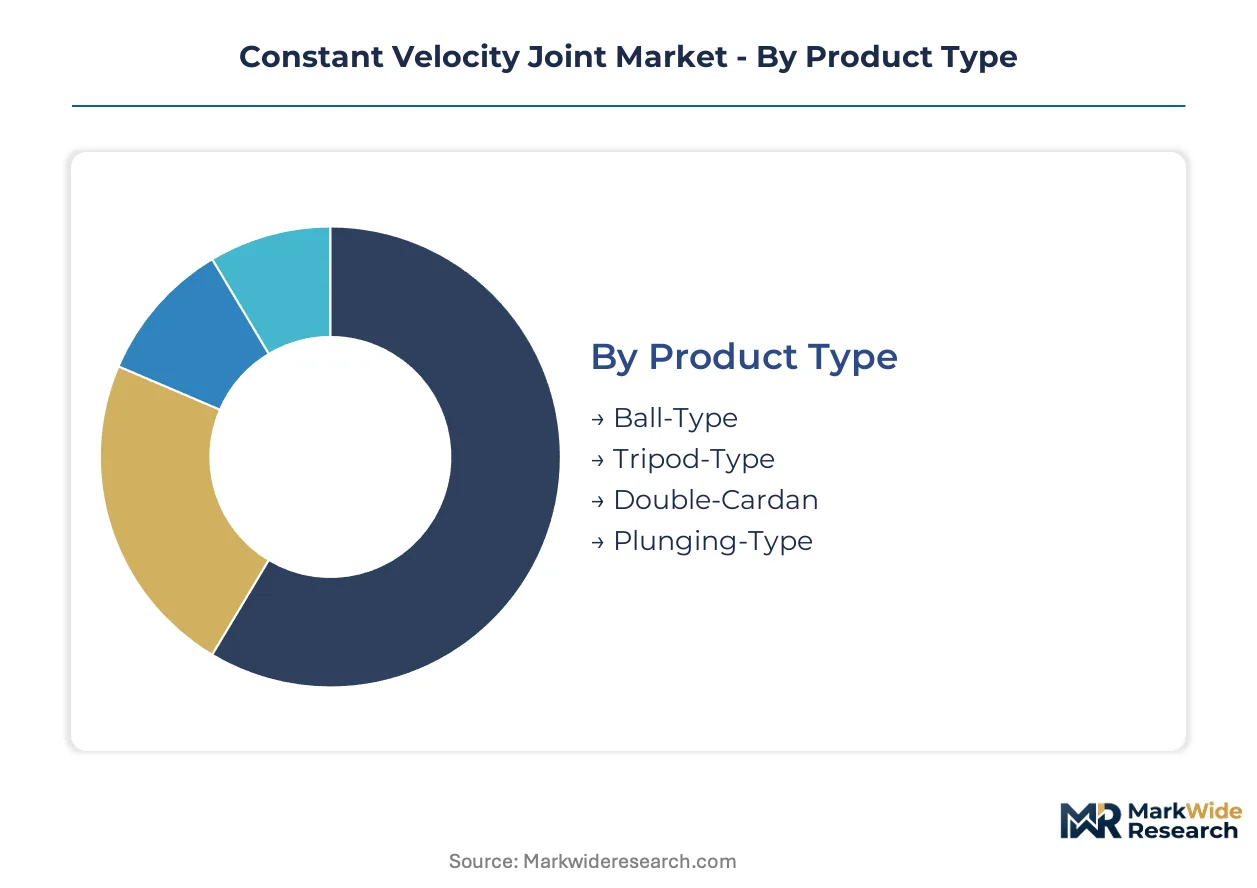
CVJ procurement channels diverge sharply between platform-engineered OEM supply and fragmented aftermarket distribution. Segment-specific margin structures and technical validation requirements determine which suppliers capture value at each tier.
Product Type:
Ball-type units flow predominantly through captive OEM channels with multi-year program commitments, while tripod-type and specialty configurations serve mixed OEM-aftermarket demand with shorter contract cycles.
- Ball-Type:Six precision-ground steel balls housed in spherical inner and grooved outer races deliver angular flexibility up to 47 degrees. Front-wheel-drive passenger vehicle architectures in China and Europe concentrate demand, with EPA fuel economy mandates accelerating specification for low-friction variants.
- Tripod-Type:Three-roller tripod architecture prioritizes plunge movement capacity over angular range for inboard transverse drivetrain positions. Hybrid powertrain proliferation in Japan and Thailand drives specification growth as electrified platforms demand enhanced axial compliance.
- Double-Cardan:Dual universal joint configuration eliminates velocity fluctuation in heavy-duty applications through phased joint angles. Commercial vehicle drivetrains in North American long-haul segments sustain primary demand.
- Plunging-Type:Axial displacement capability accommodates suspension travel without secondary joint complexity. Off-road vehicle manufacturers specify these for terrain-adaptive drivelines.
By volume, ball-type leads. By growth pace, tripod-type is ahead.
Material:
Cost tier stratification separates premium aluminum and composite formulations from standard steel alloy production, with material selection directly determining heat-treatment investment requirements and forging margin profiles.
- Steel Alloy:Chromium-nickel bearing steels dominate forged component production through established induction hardening protocols. Nickel price volatility compresses margins during contract lock-in periods.
- Aluminum:Unsprung mass reduction priorities on premium EV platforms in Germany and California accelerate specification. Cast and forged aluminum variants require specialized friction-welding expertise that limits qualified supplier pools.
- Composite:Carbon-fiber reinforced polymer cages reduce rotating mass in motorsport-derived road applications. Niche penetration concentrates in low-volume performance vehicle programs.
- Hardened Metal:Surface-hardened ductile iron alternatives serve cost-optimized emerging market vehicle segments. India's domestic component manufacturing targets attract capacity investment for this tier.
Steel alloy retains volume leadership. Aluminum climbs the fastest.
Application:
Customer type fragmentation distinguishes fleet procurement standardization from individual owner replacement patterns, with commercial vehicle electrification creating new specification authority structures.
- Passenger Vehicles:Transverse front-wheel-drive and all-wheel-drive architectures generate highest unit volumes across compact through luxury segments. China's MIIT GB standards for NEV durability reshape lifecycle testing requirements.
- Commercial Vehicles:Drive axle and steering axle applications demand enhanced torque capacity with maintenance interval extension. Last-mile delivery electrification in North America prioritizes predictive maintenance data access over traditional warranty terms.
- Off-Road Vehicles:Articulated steering and independent suspension systems require extreme angular capability beyond standard automotive ranges. Agricultural and construction equipment manufacturers specify these for terrain adaptability.
- Motorcycles:Shaft-drive touring and adventure bike platforms adopt compact CVJ solutions in place of chain final drives. Premium European and Japanese manufacturers lead specification.
Passenger vehicles dominate unit volume. Commercial vehicles show steepest expansion trajectory.
End User:
Supply concentration varies dramatically between vertically integrated vehicle assemblers and fragmented repair workshop networks, determining pricing power and technical support requirements.
- OEMs:Platform-engineered specifications with seven-year program horizons demand upfront R&D amortization and dedicated validation capacity. Direct relationships with GKN Automotive and NTN Corporation concentrate procurement authority.
- Aftermarket Suppliers:Independent distribution channels serve replacement demand with reverse-engineered or licensed designs. REACH lubricant reformulation compliance creates differentiation pressure in European markets.
- Vehicle Assemblers:Contract manufacturing arrangements for EV-native brands require rapid specification cycle adaptation from traditional tier-one suppliers.
- Repair Workshops:Fragmented installation base drives demand for pre-greased, pre-assembled joint modules with simplified press-fit installation protocols.
OEMs command volume leadership. Vehicle assemblers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply by geography. Fleet buyers in the United States prioritize lifecycle cost over unit price, while emerging market operators remain acutely price-sensitive on replacement cycles. European procurement sits between these poles, with regulatory compliance costs compressing margin tolerance.
China
MIIT production targets for new energy vehicles sustain concentrated demand for ball-type and tripod-type joints across transverse drivetrain architectures. GB standards for NEV component durability mandate specific lifecycle testing protocols that filter supplier qualification pools. Shanghai and Guangzhou anchor assembly capacity where domestic EV-native brands compress specification cycles to three-year refresh timelines.
United States
NHTSA fuel economy standards and EPA emissions mandates tighten drivetrain efficiency requirements, accelerating specification of low-friction joint designs. Commercial vehicle electrification in last-mile delivery segments prioritizes predictive maintenance data access over traditional warranty structures. Michigan and Ohio retain forging and heat-treatment clusters serving Detroit-based OEM platform programs.
Germany
REACH regulation on persistent organic pollutants forces molybdenum-disulfide grease reformulation across European-assembled vehicles. Premium EV platforms specify aluminum CVJ variants for unsprung mass reduction, requiring specialized friction-welding expertise. Baden-Württemberg and Bavaria host precision grinding capacity where induction hardening equipment concentrates for ball groove finishing below 5-micron tolerances.
Japan
METI industrial policy supports hybrid powertrain proliferation driving specification of torque-vectoring compatible joint architectures. JIS standards govern material certification for chromium-nickel bearing steels used in forged component production. Aichi Prefecture and Kanagawa Prefecture integrate bearing-to-joint production lines that capture margin otherwise flowing to tier-two specialists.
India
PLI scheme production-linked incentives attract joint assembly investment to serve emerging EV manufacturing clusters. Domestic vehicle manufacturers specify cost-optimized hardened metal alternatives to chromium-nickel steels for mass-market segments. Tamil Nadu and Maharashtra concentrate contract manufacturing arrangements where tier-one suppliers adapt to rapid specification cycles from EV-native brands.
Constant Velocity Joint Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. The upper tier commands captive forging operations and in-house heat-treatment capacity that insulates margin control from alloy steel price volatility. Mid-scale assemblers without upstream metalworking capabilities face geographic bottlenecks around precision induction hardening equipment clusters. Strategic archetypes separate integrated forging-to-assembly operators, bearing-specialist diversifiers, and torque-vectoring architecture innovators. Dominant competitive moves include backward integration into heat-treatment capacity and technology licensing for EV-specific joint geometries.
Within the integrated forging tier, GKN Automotive and NTN Corporation exemplify players with captive European and Asian production footprints. JTEKT Corporation occupies a position among specialists developing hybrid-drivetrain-compatible architectures. These three anchors represent distinct strategic postures: transcontinental forging control, integrated bearing-to-joint production, and electrified powertrain innovation.
| Leading Market Players |
|---|
| GKN Automotive |
| American Axle & Manufacturing |
| NTN Corporation |
| JTEKT Corporation |
| Dana Incorporated |
| Schaeffler AG |
| SKF |
| Nexteer Automotive |
| NSK Ltd. |
| Others |
Pricing and Supply Chain Analysis
MIIT GB standards for NEV component durability gate supplier qualification pools while simultaneously stratifying price tiers between certified and uncertified producers. This regulatory filter concentrates procurement authority among qualified suppliers who command premium positioning in OEM channels.
Pricing Analysis
After-sales service revenue from fleet maintenance contracts drives lifetime value more than initial unit sales. Three-tier pricing structure across premium, standard, and economy levels separates aluminum CVJ variants for German EV platforms from steel alloy mass-market units and hardened metal alternatives for India. Cost compression in standard-grade ball-type units is intensifying because nickel price volatility squeezes forging margins during contract lock-in periods. Fleet operators in North America show least price sensitivity as they prioritize predictive maintenance data access, while independent repair workshops in emerging markets remain most acutely cost-conscious on replacement cycles.
Supply Chain Analysis
Inventory lead times for precision induction hardening equipment extend 18-24 months, creating geographic bottlenecks around German and Japanese supplier clusters. Forged component production draws from chromium-nickel bearing steel mills in Germany, Japan, and China, with finished assembly concentrated in Thailand, Mexico, and Eastern European automotive corridors. Single-source vulnerability concentrates in molybdenum-disulfide grease formulations facing REACH-mandated reformulation timelines. Distribution runs through captive OEM supply chains for ball-type units and fragmented independent channels for tripod-type aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. MIIT GB certification requirements and REACH lubricant compliance create switching costs that lock qualified suppliers into multi-year OEM program horizons.
For Market Incumbents: Shield margin position by deepening backward integration into heat-treatment capacity in Baden-Württemberg and Aichi Prefecture clusters. Accelerate R&D amortization across shorter EV specification cycles by locking platform-sharing agreements with legacy-EV native partnerships before validation protocol fragmentation intensifies.
For New Entrants and Emerging Players: Lead with torque-vectoring joint architectures for hybrid drivetrains where JTEKT Corporation currently dominates specification white space. Target India's PLI scheme corridors in Tamil Nadu for cost-optimized hardened metal production serving domestic EV manufacturing clusters. Develop direct-to-fleet channel relationships bypassing traditional tiered supply hierarchies in North American last-mile delivery segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aluminum friction-welding capacity required for premium EV platforms. Long-term viability over the next decade favors suppliers with captive forging-to-assembly footprints rather than pure-play assemblers exposed to alloy steel price volatility. Watch for MIIT GB standard revision announcements as the critical signal indicating certification barrier adjustments that would reshape supplier qualification pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Capacity | Captive induction hardening insulates margin control from nickel price swings in forging operations. |
| Torque-Vectoring Joint Architecture Development | Hybrid drivetrain electrification opens specification white space beyond traditional ball-type and tripod-type units. |
| Aluminum Friction-Welding Capacity Expansion | Premium EV platforms in Germany and California specify unsprung mass reduction variants requiring specialized expertise. |
| Direct-to-Fleet Channel Establishment | Commercial vehicle electrification in North America prioritizes uptime metrics over traditional tiered supply hierarchies. |
| REACH-Compliant Grease Formulation Investment | ECHA-mandated molybdenum-disulfide alternatives create differentiation pressure in European aftermarket channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and MIIT NEV production bulletins. Interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and heat-treatment equipment manufacturers informed demand-side validation. Bottom-up unit volume estimates triangulated against top-down value projections derived from content-per-vehicle analysis across propulsion architectures.
Segmentation dimensions modeled include joint type, material grade, vehicle application, and end-user channel across the analysis window. CAGRs were derived from regression analysis of historical production volumes against MIIT NEV targets and EPA CAFE trajectory assumptions. Industry-specific inputs incorporated platform-sharing agreement timelines, REACH lubricant reformulation compliance deadlines, and PLI scheme investment flow patterns.
Forecasts assume regulatory continuity in MIIT GB standards, EPA CAFE mandates, and REACH additive restrictions; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
High Level Brake Lamp Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Suspension Spring Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Car Refrigerator Market
Automotive Parts
Brake Pad Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Colombia Automotive Lubricants Market