
 Automotive Lubricants Market | 2026-2036
Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lubricants Market Analysis
Commercial vehicle fleets is repositioning the automotive lubricants landscape toward extended-drain synthetic formulations. Shell plc leverages its integrated base oil production network to secure feedstock advantages across major refining hubs. ExxonMobil Corporation anchors its position through proprietary additive chemistry developed for heavy-duty diesel engines. Valvoline Inc. specializes in quick-lube channel control, sustaining brand visibility among fleet maintenance operators.
Automotive lubricants are formulated blends of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in powertrain components, with viscosity grades such as SAE 5W-20 and SAE 15W-40 defining cold-start flow and high-temperature film strength. Engine oil commands the largest volume share while synthetic base oil captures the fastest growth trajectory due to OEM fill specifications and drain-interval extension. Transmission fluid concentrates margin pools where specialized friction modifiers command premium pricing, and biodegradable oil remains nascent outside regulated European corridors.
EPA tailpipe standards and the California Air Resources Board's low-emission vehicle rules compel lubricant reformulation for improved fuel economy and reduced ash content. China's MIIT enforces GB standards that align domestic products with international viscosity and performance benchmarks. Stakeholders must monitor regulatory divergence between North American and Asian test protocols when allocating R&D budgets across regional formulation centers.
Market Dynamics
The automotive lubricants sector is pivoting around tightening emissions mandates that force reformulation toward lower-viscosity, ash-reduced chemistries. OEM fill specifications now dictate synthetic penetration rates more than aftermarket price competition ever did.
Growth Catalysts
- EPA Tier 3 tailpipe standards:The US Environmental Protection Agency's sulfur and particulate limits compel fleets to adopt extended-drain synthetic formulations that maintain catalyst efficiency across longer service intervals.
- Group III base oil capacity expansion:Refinery investments in hydrocracker units across the US Gulf Coast and Singapore are compressing synthetic-versus-conventional price differentials for volume buyers.
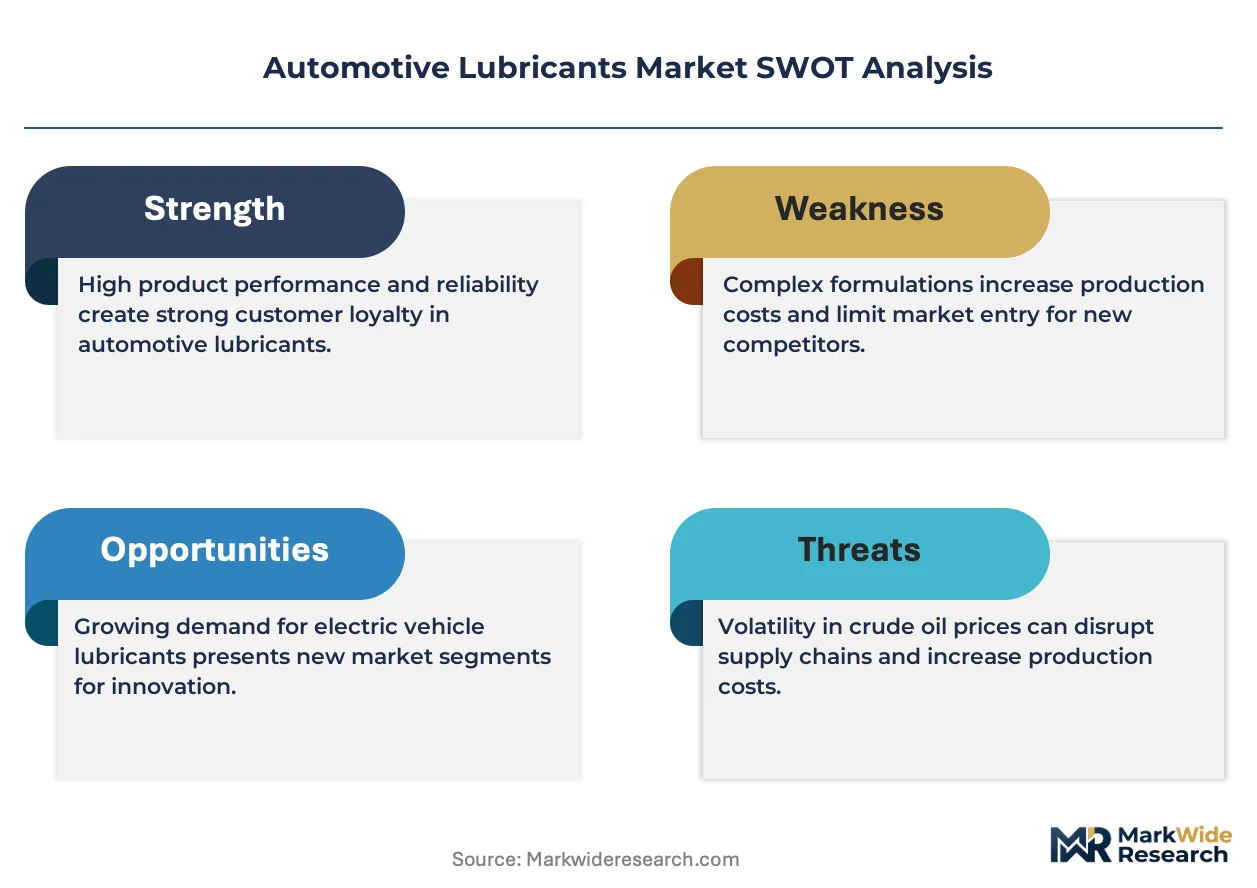
- Electric axle thermal management:Hybrid and battery-electric commercial platforms require dielectric coolants and specialized greases that command formulation premiums unavailable to legacy mineral suppliers.
Market Restraints
- API Group II+ supply concentration:Base oil production clusters disproportionately along the US Gulf Coast and Rotterdam corridor, exposing blenders to hurricane and labor-action disruptions without geographic diversification.
- Calcium sulfonate complex grease feedstock volatility:Tall oil fatty acid and lime derivative costs swing with pulp mill output and construction demand, compressing margin predictability for high-performance chassis lubricant lines.
- REACH SVHC disclosure thresholds:The European Chemicals Agency's Substances of Very High Concern list forces reformulation of zinc dialkyldithiophosphate packages, eliminating proven anti-wear chemistries before fully validated replacements reach scale.
Strategic Opportunities
- India's Bharat Stage VI Phase II enforcement:The country's stricter particulate and NOx limits for commercial vehicles create first-mover advantage for suppliers with pre-certified low-SAPS (sulfated ash, phosphorus, sulfur) portfolios.
- Wind turbine gearbox service contracts:Renewable energy operators seek decade-long lubrication management agreements that bundle fluid analysis, filtration, and scheduled replacement, shifting revenue from product to performance-based service.
- Polyalkylene glycol-water emulsion convergence:Fire-resistant hydraulic fluids for underground mining and steel mills combine PAG synthetic base stocks with advanced emulsion stabilizers, opening specification slots previously locked by mineral oil incumbents.
Industry Challenges
- Tribology PhD pipeline constriction:Universities in Germany, Japan, and the US have reduced specialized lubrication engineering programs, forcing additive houses to train chemists in-house for two to three years before productive formulation work.
- API SP/ILSAC GF-6B certification timeline compression:The American Petroleum Institute's sequence test requirements for newer viscosity grades demand engine stand time that outpaces available test cell capacity, delaying product launches by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lubricants Market |
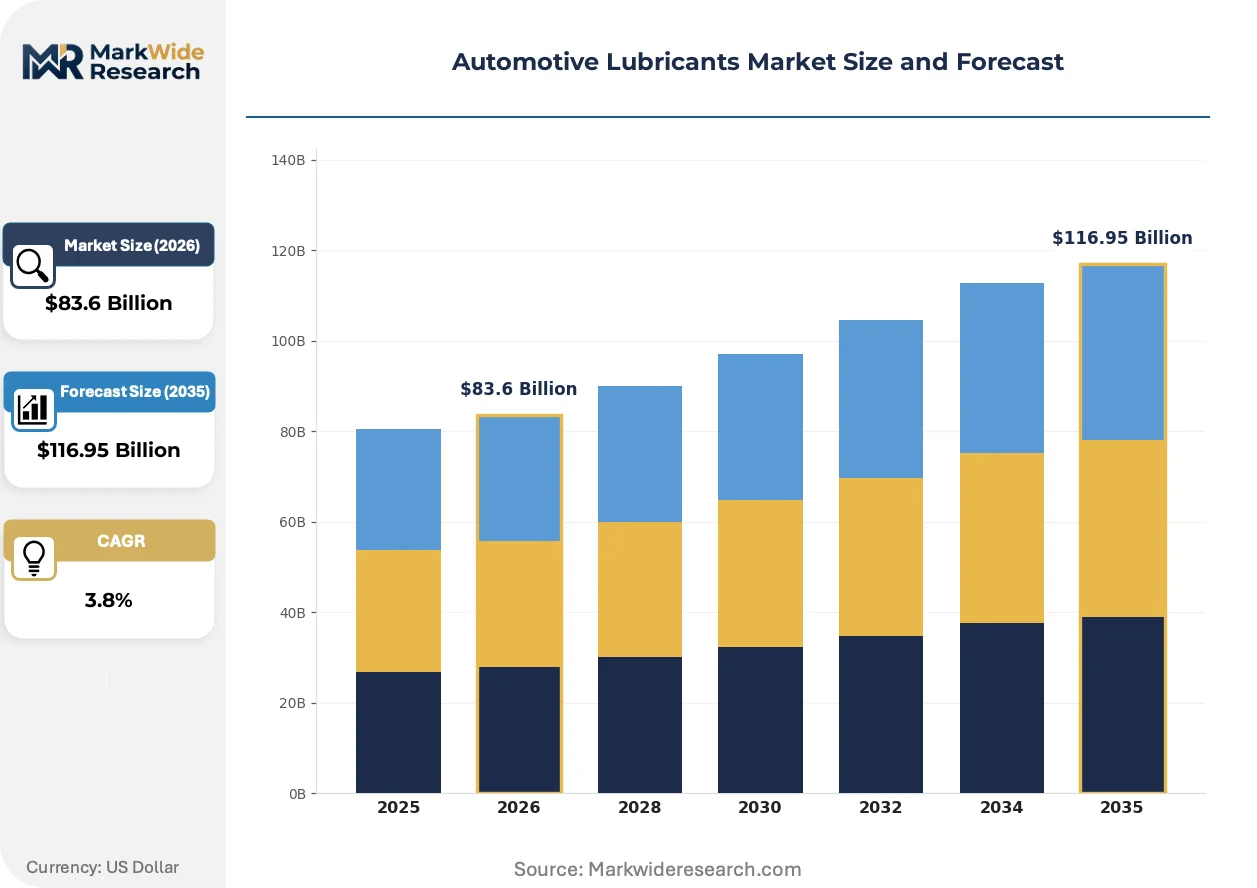
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $116.95 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Brake Fluid Application: Passenger Vehicles, Commercial Vehicles, Agricultural Equipment, Motorcycles Base Oil: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Biodegradable Oil Viscosity Grade: SAE 10W-30, SAE 5W-20, SAE 15W-40, SAE 20W-50 |
| Companies Covered | Shell plc, ExxonMobil Corporation, BP p.l.c., Chevron Corporation, TotalEnergies SE, PetroChina Company Limited, China Petroleum & Chemical Corporation, ENEOS Holdings, Inc., Valvoline Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lubricants Market Emerging Trajectories
Reformulation priorities are diverging sharply between markets chasing electrification compatibility and those extending internal combustion asset life. The technological frontier now sits at the intersection of thermal conductivity engineering and biodegradability certification.
Polymer-thickened greases with ionic liquid boundary lubricants are decentralizing the traditional calcium-lithium soap thickener hierarchy in high-temperature bearing applications. Steel mills and cement kilns in South Korea and Germany are specifying these chemistries for continuous casting lines where conventional greases fail within weeks. The shift is compressing incumbent thickener suppliers' volume positions while opening specification slots for additive houses with ionic liquid synthesis capabilities.
The European Union's F-Gas Regulation phase-down is forcing refrigerant lubricant suppliers to reformulate polyolester base stocks for lower-global-warming-potential hydrofluoroolefins. Compressor OEMs in Italy and Poland now require lubricants compatible with R-1234yf and R-513A blends that exhibit different miscibility curves than legacy R-134a systems. Mobile air conditioning service channels are responding by consolidating refrigerant-and-lubricant procurement to single-source distributors with technical service capabilities.
Fleet maintenance departments are unbundling fluid analysis from lubricant supply contracts, contracting directly with third-party laboratories for used oil diagnostics. This disintermediation is stripping quick-lube channels of their traditional lock-in mechanism and forcing lubricant marketers to compete on technical service rather than volume rebates. The pattern is most advanced among US Class 8 truck fleets operating dedicated maintenance facilities in the Midwest and Southeast corridors.
Automotive Lubricants Market Segmentation
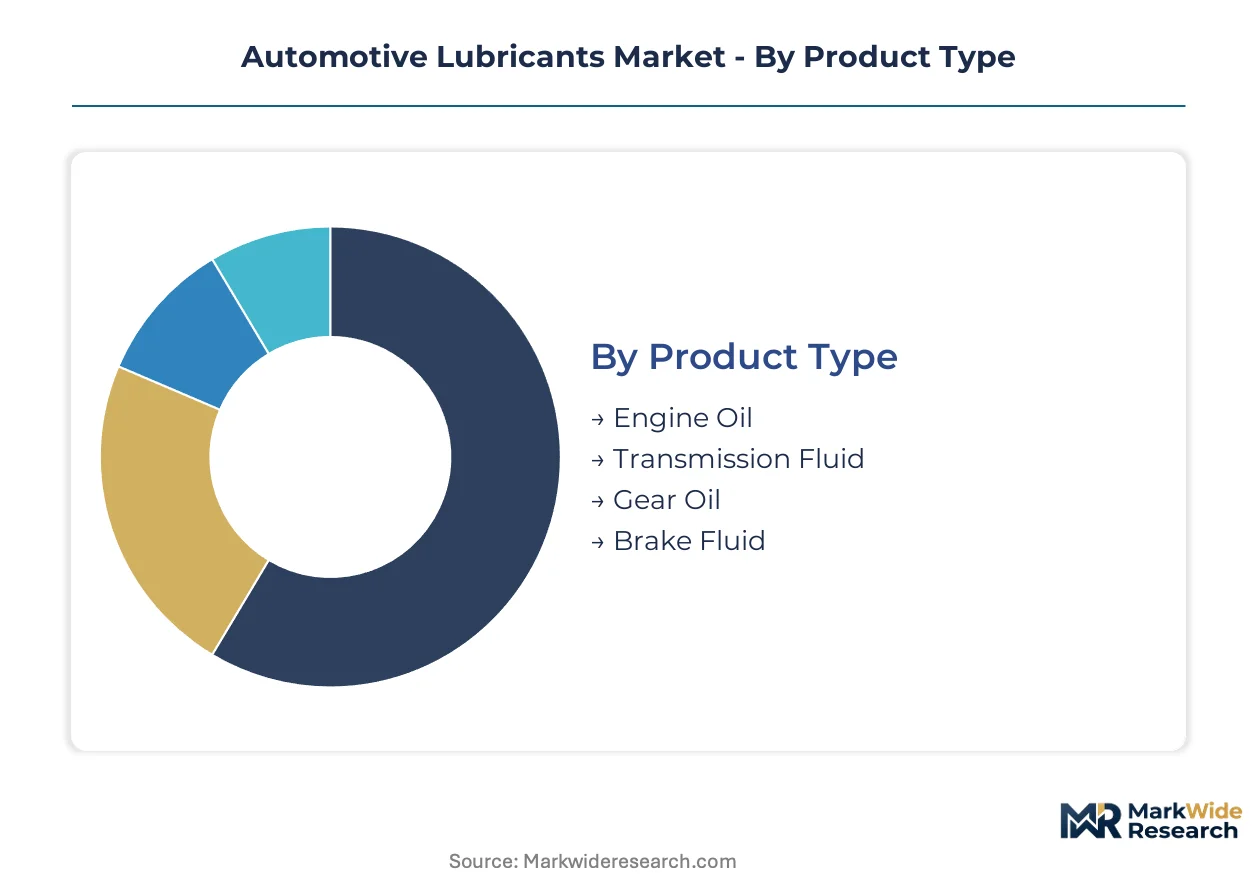
Segmentation in automotive lubricants reveals how formulation chemistry, equipment stress profiles, and regulatory thresholds fragment demand across incompatible specification tiers. Buyers select products based on OEM warranty compliance, drain-interval economics, and regional emissions mandates rather than price alone.
Product Type:
Fleet maintenance departments prioritize drain-interval extension and catalyst compatibility when selecting lubricant categories.
- Engine Oil:Formulated blends of base oils and performance additives reduce friction, dissipate heat, and prevent wear in powertrain components. Passenger vehicle service centers in the United States concentrate purchases around SAE 0W-16 and SAE 5W-30 grades as EPA fuel economy standards tighten; commercial fleets extend intervals with synthetic formulations to minimize downtime.
- Transmission Fluid:Specialized friction modifiers and viscosity index improvers manage clutch engagement and torque transfer precision. Demand concentrates in automatic transmission rebuild shops across Germany and Japan where ZF and Aisin specification compliance commands premium pricing; electrified axle thermal management is forcing reformulation of dielectric properties.
- Gear Oil:Extreme-pressure additives protect hypoid gears under high-load, low-speed conditions.
- Brake Fluid:Hygroscopic glycol-ether or silicone formulations maintain compressibility across temperature ranges.
Volume sits with Engine Oil; growth tilts toward Transmission Fluid.
Application:
Equipment utilization intensity and OEM service network density reshape procurement patterns across vehicle categories.
- Commercial Vehicles:Heavy-duty diesel engines operating in US Midwest freight corridors require extended-drain synthetics compliant with API CK-4 and FA-4 specifications. Fleet operators negotiate direct supply agreements with blenders to secure volume pricing and used oil analysis services.
- Passenger Vehicles:Light-duty gasoline and diesel powertrains dominate unit volume through quick-lube channels and dealership service departments. China's MIIT enforcement of GB standards is accelerating synthetic penetration in domestic OEM fill specifications.
- Agricultural Equipment:Seasonal operating patterns and field contamination exposure drive demand for high-detergent formulations.
- Motorcycles:Wet clutch compatibility and shear-stable viscosity grades address compact engine packaging and high-RPM operation.
Commercial Vehicles capture margin concentration; Passenger Vehicles retain volume dominance.
Base Oil:
Refinery configuration and hydrocracking investment cycles determine synthetic-versus-conventional price differentials for blenders.
- Synthetic Oil:Group III, IV, and V base stocks engineered through severe hydrocracking, gas-to-liquids synthesis, or polyalphaolefin polymerization deliver thermal stability and low-temperature fluidity. OEM fill specifications in South Korea and Germany now mandate synthetic content for warranty coverage; Group III capacity expansion along the US Gulf Coast is compressing historical premiums.
- Mineral Oil:Solvent-refined or hydrofinished Group I and II base stocks serve price-sensitive aftermarket segments and legacy equipment.
- Semi-Synthetic Oil:Blended formulations balance cost and performance for mid-tier service intervals.
- Biodegradable Oil:Vegetable-derived or synthetic ester bases target environmentally sensitive applications in regulated European corridors.
Synthetic Oil is climbing the fastest; Mineral Oil retains installed-base volume.
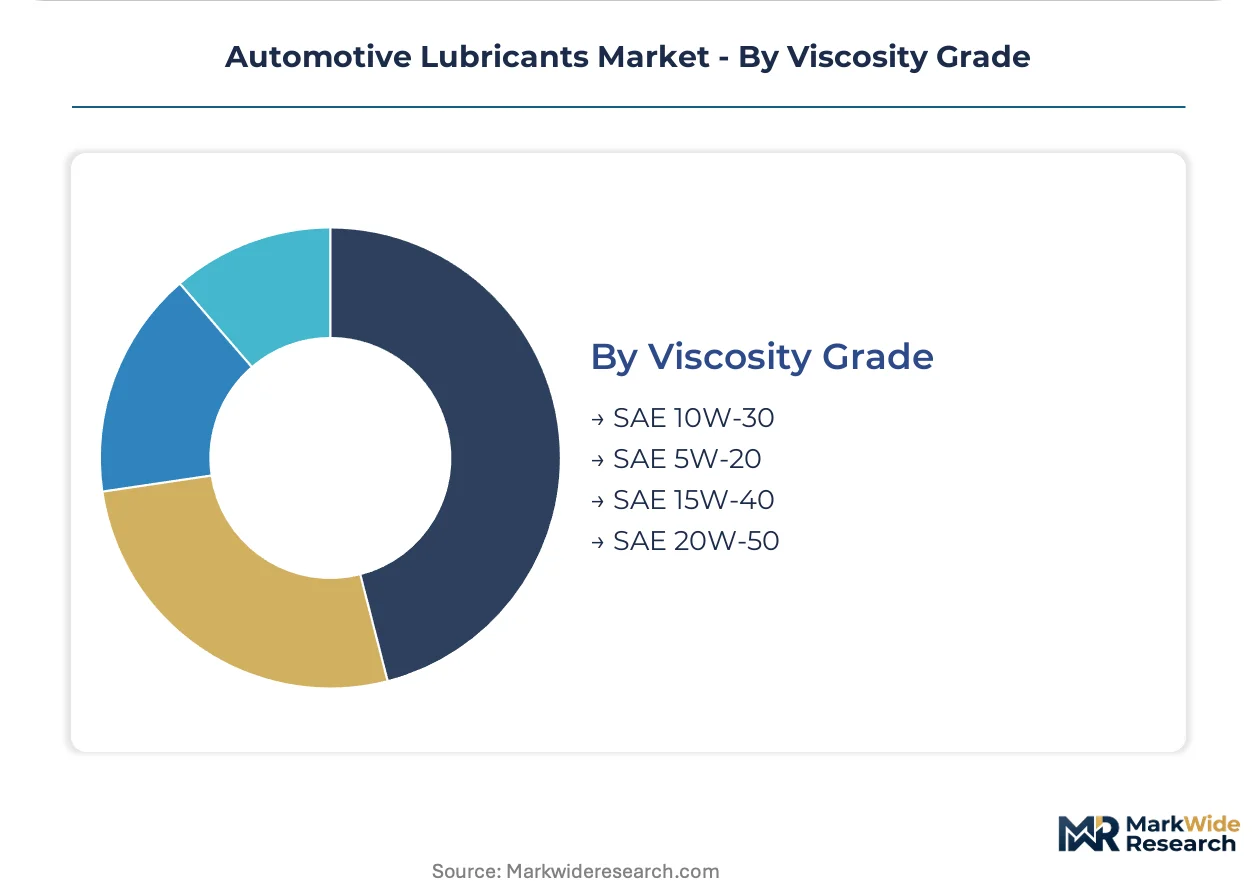
Viscosity Grade:
Cold-start flow requirements and high-temperature film strength define specification selection across climate zones.
- SAE 5W-20:Low-viscosity formulation optimized for fuel economy in modern gasoline direct-injection engines. US passenger vehicle OEMs specify this grade for CAFE compliance; Japanese manufacturers have extended its use to hybrid thermal management circuits.
- SAE 15W-40:Heavy-duty multigrade maintaining protective film thickness under turbocharged diesel thermal loads. Commercial fleets across India and Brazil specify this grade for Bharat Stage VI and Proconve P8 engine compatibility; high soot-loading capacity extends drain intervals in severe service.
- SAE 10W-30:Versatile multigrade balancing cold-cranking performance and high-temperature protection.
- SAE 20W-50:High-viscosity legacy grade serving air-cooled engines and high-mileage applications in warm climates.
SAE 15W-40 anchors commercial volume; SAE 5W-20 expands most quickly in OEM fill.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery capacity concentrates along the US Gulf Coast and Singapore corridor, while consumption gravity shifts toward China's industrial cities and India's freight corridors. This production-consumption divide forces blenders to optimize logistics networks and regional formulation centers rather than centralized manufacturing.
United States
Commercial fleet operators in the Midwest and Southeast freight corridors drive synthetic lubricant procurement as EPA Tier 3 standards tighten sulfur and particulate limits. The Environmental Protection Agency compels reformulation toward lower-viscosity, ash-reduced chemistries that maintain catalyst efficiency. Houston anchors base oil production with hydrocracker investments compressing synthetic-versus-conventional price differentials for volume buyers.
China
Domestic OEM service networks in the Yangtze River Delta and Pearl River Delta require GB-standard compliant formulations for warranty coverage. The Ministry of Industry and Information Technology enforces viscosity and performance benchmarks that align domestic products with international specifications. Shenzhen and Shanghai clusters concentrate demand for synthetic content in OEM fill specifications as domestic vehicle production scales.
Germany
Automotive OEM specification compliance commands premium pricing in transmission fluid and specialized friction modifier segments. The European Chemicals Agency's REACH SVHC disclosure thresholds force reformulation of zinc dialkyldithiophosphate anti-wear packages. Stuttgart and Munich industrial corridors specify polymer-thickened greases with ionic liquid boundary lubricants for high-temperature bearing applications in steel and cement operations.
India
Heavy-duty diesel commercial fleets across the Delhi-Mumbai freight corridor specify SAE 15W-40 grades for Bharat Stage VI Phase II engine compatibility. The Central Pollution Control Board enforces stricter particulate and NOx limits that create first-mover advantage for suppliers with pre-certified low-SAPS portfolios. Maharashtra and Gujarat manufacturing clusters concentrate aftermarket demand as domestic commercial vehicle production expands.
South Korea
Steel mills and cement kilns in the Busan-Ulsan industrial belt specify advanced grease chemistries for continuous casting lines where conventional formulations fail. The Ministry of Trade, Industry and Energy drives synthetic base oil mandates through OEM fill specifications for warranty coverage. Daegu-Gyeongbuk manufacturing corridors concentrate procurement for high-performance chassis lubricant lines serving export-oriented heavy industry.
Automotive Lubricants Market Vendor Landscape
Top-tier vendors anchor integrated base oil production and proprietary additive chemistry, while mid-tier blenders compete on quick-lube channel control and regional formulation flexibility. The structure consolidates around refinery-linked majors with captive feedstock access and specialized additive houses with tribology expertise. Strategic archetypes include hydrocracker-integrated refiners, quick-lube channel specialists, and industrial grease formulators. Capacity expansion in Group III base oil and acquisition of regional blending assets represent the dominant competitive moves.
Within the integrated refiner tier, Shell plc and ExxonMobil Corporation occupy positions defined by upstream base oil network control and downstream formulation capabilities. Valvoline Inc. exemplifies the quick-lube channel specialist archetype, anchoring brand visibility among fleet maintenance operators through service network penetration. PetroChina Company Limited represents the national oil company blender model with captive feedstock advantages in Asia-Pacific markets. These three entities collectively illustrate how competitive positioning in automotive lubricants depends on either backward integration into base oil production or forward integration into service channel control.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| BP p.l.c. |
| Chevron Corporation |
| TotalEnergies SE |
| PetroChina Company Limited |
| China Petroleum & Chemical Corporation |
| ENEOS Holdings, Inc. |
| Valvoline Inc. |
| Others |
Supply Flow & Price Mechanics
EPA Tier 3 tailpipe standards and their equivalents across Asia-Pacific markets gate qualified supply to blenders capable of low-SAPS formulation, compressing premium-tier pricing access to additive houses with pre-certified chemistry portfolios and hydrocracker-integrated refiners with captive Group III base oil production.
Pricing Analysis
Margin tightening in synthetic formulations reflects Group III capacity expansion along the US Gulf Coast and Singapore corridor. Three-tier pricing structure across premium synthetic, standard mineral, and economy aftermarket levels stratifies by API certification grade and OEM fill specification compliance. Cost-down pressure on mineral-based segments accelerates because fleet operators negotiate direct volume contracts that strip distributor markups. Commercial vehicle fleets demonstrate lowest price sensitivity due to drain-interval economics, while independent quick-lube channels face highest margin compression.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for factory-fill specifications, while aftermarket distribution runs through regional blending terminals and quick-lube service networks. Supply concentrates in the United States, Singapore, and South Korea where hydrocracker investments anchor Group III base oil production. Raw material dependencies include tall oil fatty acids for calcium sulfonate greases, polyalphaolefin feedstocks for synthetic engine oils, and specialized friction modifier packages for transmission fluids. Single-source vulnerability around API Group II+ production clusters exposes blenders to hurricane disruptions along the Gulf Coast. Distribution feeds from refinery-linked terminals through dedicated tanker fleets to OEM fill plants and aftermarket blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over hydrocracker base oil production or quick-lube service networks determines margin capture, with additive chemistry capabilities serving as the critical downstream lever players are pursuing.
For Market Incumbents: Acquire regional blending assets in India's Maharashtra and Gujarat corridors to preempt Bharat Stage VI Phase II certification requirements. Secure long-term offtake agreements with Group III base oil producers to defend margin position against price compression from capacity expansion. Invest in low-SAPS formulation R&D to maintain specification compliance as zinc dialkyldithiophosphate faces REACH-driven phase-out.
For New Entrants and Emerging Players: E-commerce fleet procurement platforms offer the most penetrable route to bypass entrenched quick-lube channel control. Target wind turbine gearbox service contracts where performance-based lubrication management agreements shift revenue from product to bundled fluid analysis and scheduled replacement. Pursue polyalkylene glycol-water emulsion specifications for underground mining and steel mill hydraulic systems previously locked by mineral oil incumbents.
For Investors and Strategic Acquirers: India's Central Pollution Control Board enforcement of Bharat Stage VI Phase II is the leading indicator that low-SAPS portfolio certification will separate viable acquisition targets from stranded asset risks. Over the projection horizon, blenders with captive base oil supply and pre-certified synthetic formulations represent the most defensible acquisition archetype. Monitor API SP/ILSAC GF-6B certification timeline compression as the signal for test cell capacity constraints delaying product launches and creating distressed opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Hydrocracker investments in the US Gulf Coast secure captive Group III feedstock supply against price volatility. |
| Low-SAPS Formulation Certification | Pre-certified portfolios capture first-mover advantage in India and Europe as emissions standards tighten. |
| Quick-Lube Channel Acquisition | Service network control sustains brand visibility among fleet maintenance operators facing fluid analysis disintermediation. |
| Wind Turbine Service Contract Bundling | Decade-long lubrication management agreements shift revenue from transactional product sales to performance-based service. |
| Ionic Liquid Grease Chemistry Development | Polymer-thickened formulations with ionic liquid boundary lubricants open specification slots in South Korean and German steel mills. |
Methodological Framework
Document review covered customs and trade data, SEC filings from integrated oil majors, API certification registries, and national emissions enforcement notices, complemented by interviews with lubricant blending plant managers, OEM procurement leads at commercial vehicle manufacturers, aftermarket distribution channel partners, and technical R&D directors at additive houses. Bottom-up volume estimates from regional production and consumption data were cross-checked against top-down market sizing derived from base oil capacity and fill-rate assumptions.
Segment-level projections across product type, application, base oil category, and viscosity grade were generated through elasticity modeling of OEM specification adoption rates and fleet drain-interval extension patterns. CAGRs were derived from regression analysis of historical synthetic penetration trajectories and regulatory enforcement timelines. Industry-specific forecast inputs included Group III capacity expansion schedules, REACH SVHC disclosure threshold implementations, and electric axle thermal management fluid specification developments.
The model holds under stable regulatory enforcement trajectories and continued OEM synthetic fill mandates; deviation in base oil feedstock cost volatility or test cell capacity constraints would shift volume and value outputs. Forecasts reflect assumptions around EPA Tier 3 alignment, MIIT GB standard enforcement, and REACH reformulation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
South Africa Electric Power Steering Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
Africa Passenger Vehicles Lubricants Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
EV Reduction Gears Market