
 Global Automotive Motor Oil Market | 2026-2036
Global Automotive Motor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Motor Oil Market Analysis
Asset-light leasing and toll-manufacturing arrangements is rewriting competitive entry barriers for mid-tier blenders seeking regional scale. ExxonMobil Corporation leverages its integrated base-oil refining network across the US Gulf Coast to sustain margin capture from feedstock through finished lubricant. Valvoline Inc. anchors its position through captive quick-lube service channels that control the final mile of consumer distribution.
Automotive motor oil comprises refined petroleum or synthetic base stocks blended with performance additives to achieve specified viscosity grades, thermal stability, and wear-protection characteristics for internal-combustion engine lubrication. Full synthetic formulations command premium positioning as OEM drain-interval extensions and turbocharged engine proliferation intensify thermal-load requirements. Conventional motor oil retains volume dominance in emerging aftermarket segments where price-sensitive motorcycle and aging passenger-vehicle fleets dominate purchasing decisions.
API licensing requirements in the US, ACEA sequences in Europe, and China's GB standards collectively dictate additive-package chemistry and labeling claims that determine market access across major economies. India's BIS certification and the EU's REACH chemical-registration framework further constrain formulation flexibility for suppliers operating across multiple jurisdictions. Stakeholders must track evolving OEM factory-fill specifications and regional emissions-compliance deadlines to align product-portfolio investments with enforceable performance tiers.
Market Dynamics
Commercial fleet operators are compressing oil-drain intervals while OEMs extend factory-fill specifications, creating a bifurcated demand structure that rewards suppliers with dual-certification capabilities across service and first-fill channels.
Growth Catalysts
- ACEA C6 and API SP Sequences:Europe's tightened emissions standards and the US lubricant performance tiers are mandating lower-viscosity formulations that accelerate synthetic-conversion rates in passenger-vehicle service bays.
- Turbocharged Engine Proliferation:Heat-stressed powertrain architectures in China's industrial corridor cities are driving specification upgrades toward high-thermal-stability base stocks.
- Captive Quick-Lube Networks:Controlled distribution channels in North America are securing volume commitments that stabilize blender throughput against aftermarket price volatility.
Market Restraints
- API Group II/III Base-Oil Supply Concentration:Refinery capacity for premium base stocks clusters on the US Gulf Coast and Northeast Asia, exposing blenders to regional disruption risk.
- REACH Chemical-Registration Burden:Europe's additive-package compliance costs are diverting R&D investment from performance innovation toward regulatory documentation.
- Extended OEM Drain Intervals:Factory-fill synthetic formulations rated for 15,000+ mile service cycles are compressing aftermarket volume-per-vehicle in developed markets.
Strategic Opportunities
- India's BIS Certification Gap:Domestic blenders with unapproved import formulations face exclusion as organized workshop chains consolidate in Mumbai and Delhi industrial zones.
- E-Fleet Preventive Maintenance Contracts:Battery-electric commercial vehicles retain gear-reduction and thermal-management systems requiring specialized lubricant service protocols.
- China's GB Standards Evolution:Stricter domestic testing protocols for domestic OEM factory-fill approvals are creating captive supply relationships with state-owned base-oil refiners.
Industry Challenges
- Formulation Chemist Scarcity:Additive-package blending expertise for multi-jurisdiction certification is concentrating among retiring specialists in European and North American technical centers.
- Dual-Carbon Compliance Timelines:China's MEE carbon-intensity reporting for lubricant manufacturing is forcing capital allocation toward refinery emissions abatement rather than product development.
- Cross-Licensing IP Complexity:Proprietary friction-modifier patents held by additive majors are fragmenting supply options for mid-tier blenders seeking ACEA C6-equivalent performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Motor Oil Market |
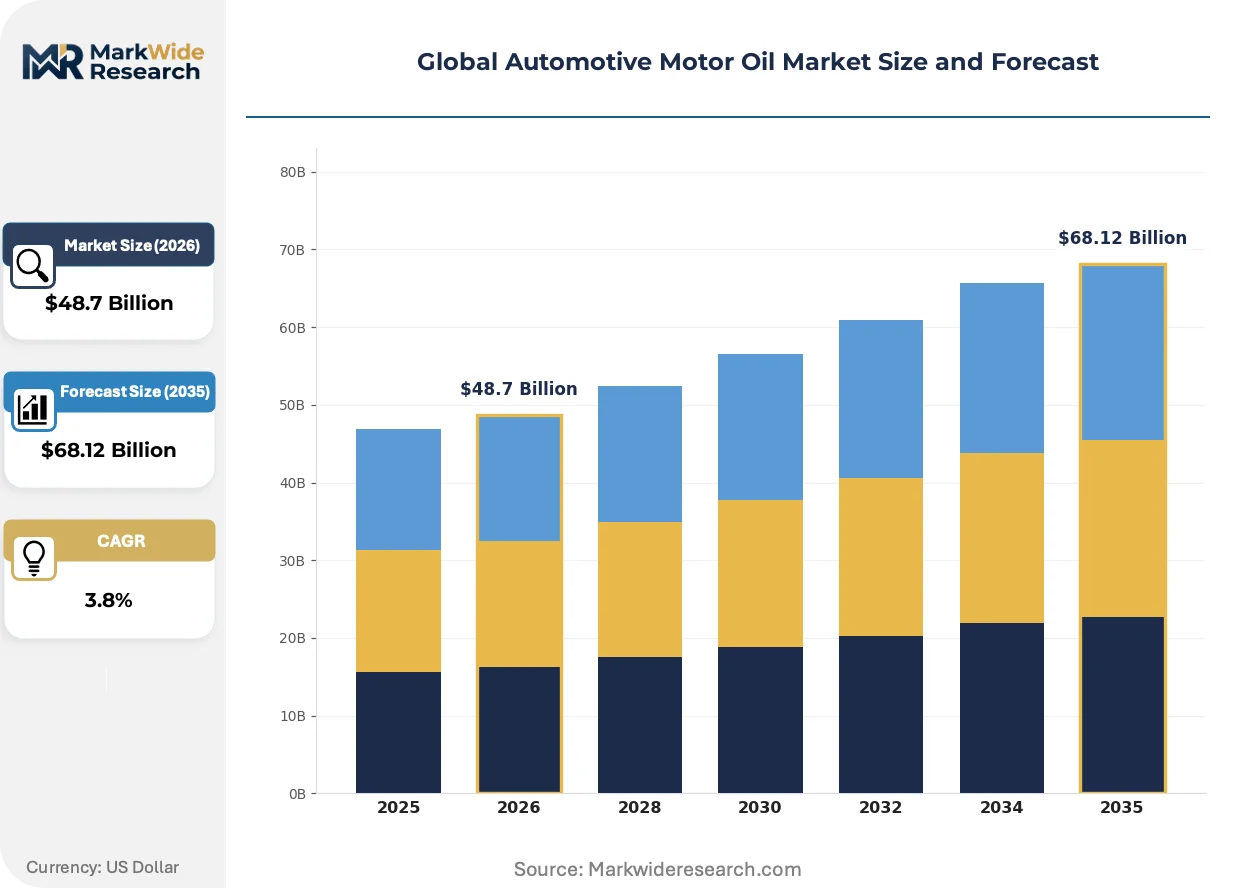
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $68.12 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Synthetic, Full Synthetic, Conventional, High Mileage Packing Type: Bottles, Drums, Bulk, Sachets End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Dealerships |
| Companies Covered | Chevron Corporation, Valvoline Inc., ExxonMobil Corporation, Fuchs Petrolub SE, Sinopec Lubricant Company, Shell plc, TotalEnergies SE, Lukoil, BP plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Motor Oil Market Emerging Trajectories
Re-refined base stocks and bio-synthetic hybrids are disrupting conventional petroleum supply chains as circular-economy mandates and carbon-accounting requirements penetrate procurement specifications.
Re-refined base-oil technology is hybridizing post-consumer lubricant recovery with virgin Group II/III blending to meet OEM factory-fill viscosity specifications. Major fleet operators in Germany and California are piloting closed-loop collection programs that secure feedstock supply for captive re-refining capacity. This hybridizing process is compressing demand for virgin base-oil imports in markets with established used-oil collection infrastructure.
REACH authorization requirements for zinc dialkyldithiophosphate and other anti-wear chemistries are forcing additive-package reformulations ahead of 2025 sunset reviews. European blenders are accelerating ashless friction-modifier testing to maintain ACEA C6 claims without restricted substances. Passenger-vehicle service channels in France and Germany are absorbing the cost pass-through while commercial fleet operators delay specification upgrades.
Workshop procurement is consolidating through integrated service platforms that bundle lubricant supply with diagnostic equipment and technician training. Independent garages in Brazil and Mexico are migrating from spot purchasing to contractual volume commitments with regional distributors. This channel transformation is most visible in Latin American markets where OEM-authorized service networks are underpenetrated relative to vehicle parc growth.
Global Automotive Motor Oil Market Segmentation
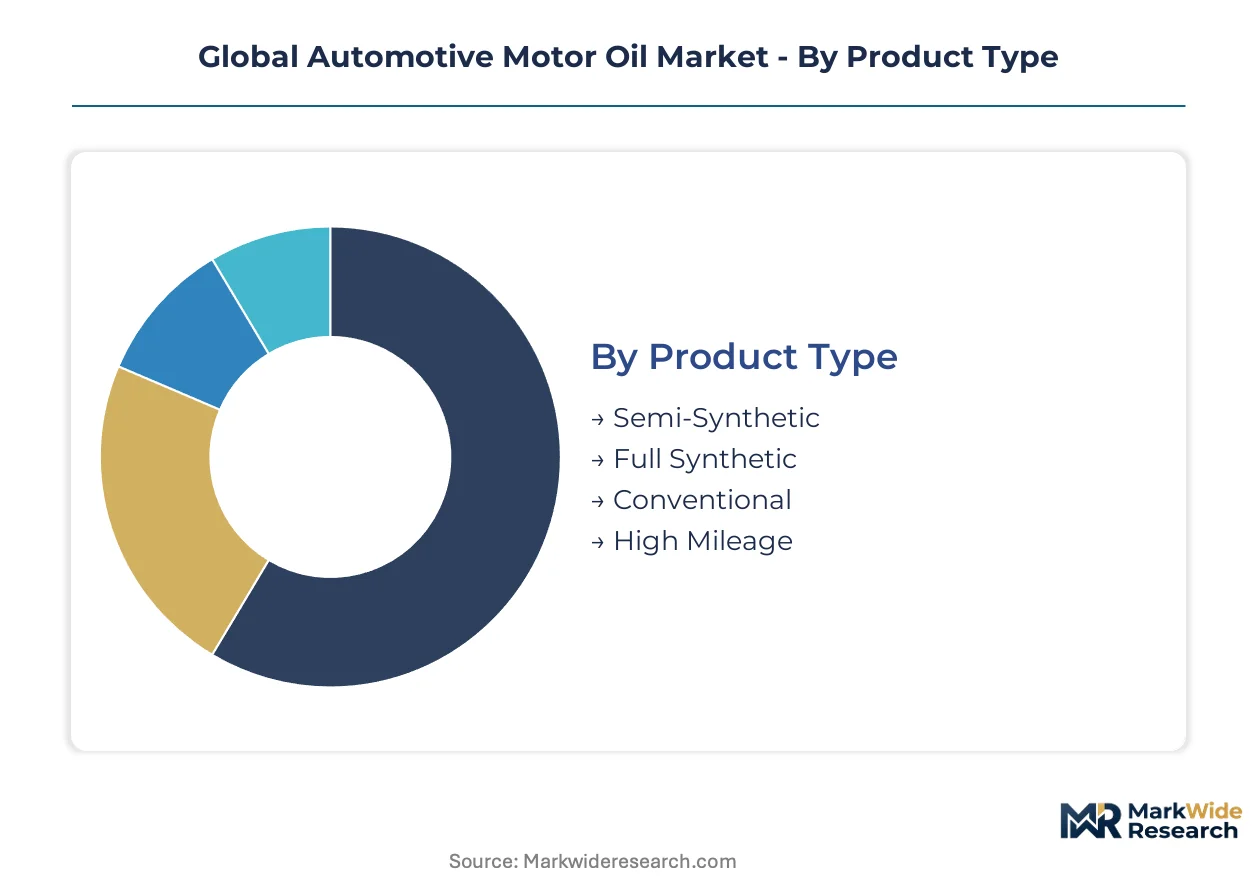
Segmentation in automotive motor oil reveals how formulation chemistry, packaging economics, and channel control interact to determine margin capture. Suppliers must align product-portfolio investments with the diverging requirements of OEM factory-fill programs and fragmented aftermarket service channels.
Product Type:
Mature petroleum-based formulations coexist with emerging synthetic technologies across divergent price-performance tiers.
- Full Synthetic:Group III and PAO base stocks deliver thermal stability for turbocharged engines and extended drain intervals. OEM factory-fill specifications in Germany and China mandate these formulations for new vehicle warranties, concentrating demand in state-owned refinery corridors and integrated blender networks.
- Semi-Synthetic:Blended Group II/III base stocks balance cost and performance for service bay upsell conversions. Workshop chains in India's Mumbai industrial zone favor this tier for aging passenger vehicle fleets requiring API SP compliance without full synthetic premiums.
- Conventional:Mineral base stocks dominate price-sensitive motorcycle and commercial fleet segments in Brazil and Mexico where BIS-equivalent certification gaps persist.
- High Mileage:Seal-conditioning additive packages target vehicles exceeding 75,000 miles, capturing do-it-yourself demand in US auto parts retail channels.
Conventional formulations handle the majority of throughput; full synthetic is expanding most quickly on share.
Packing Type:
Packaging economics track volume scale and collection infrastructure maturity across service channel types.
- Bulk:Tanker-delivered supply secures captive quick-lube throughput commitments in North America and captive fleet contracts in Germany's closed-loop re-refining programs. The 205-liter drum equivalent pricing compresses per-liter logistics costs for high-volume operators.
- Drums:Standard 205-liter containers serve independent workshops and commercial fleet depots lacking bulk storage infrastructure. Regional distributors in China's industrial corridor cities maintain drum inventory for OEM-authorized service networks.
- Bottles:Retail-ready 1-liter to 5-liter formats dominate do-it-yourself consumption in US auto parts stores and Brazilian supermarket chains.
- Sachets:Single-use pouches address informal motorcycle service points in India's Delhi industrial zone and Southeast Asian roadside repair stalls.
Bulk shipments command the steepest volume discounts; sachets are climbing fastest as informal channel penetration deepens.
End User:
Vehicle parc composition and utilization intensity create diverging lubricant stress profiles and specification requirements.
- Passenger Vehicles:Turbocharged gasoline direct injection engines in China's tier-1 cities drive low-viscosity synthetic demand for thermal-load management. OEM drain interval extensions compress aftermarket volume-per-vehicle in developed markets.
- Commercial Vehicles:Compressed oil-drain intervals in European fleet preventive maintenance programs sustain high-volume synthetic offtake. California's closed-loop collection pilots secure feedstock for captive re-refining capacity serving this segment.
- Motorcycles:Wet-clutch compatibility requirements and price-sensitive owner behavior sustain conventional and semi-synthetic dominance in Brazil, Mexico, and Southeast Asian markets.
- Heavy-Duty Trucks:Extended highway operation cycles and emissions aftertreatment sensitivity drive API CK-4 and FA-4 specification upgrades in US long-haul corridors and Chinese logistics hubs.
Passenger vehicles absorb the largest volume share; commercial vehicles show the steepest specification upgrade trajectory.
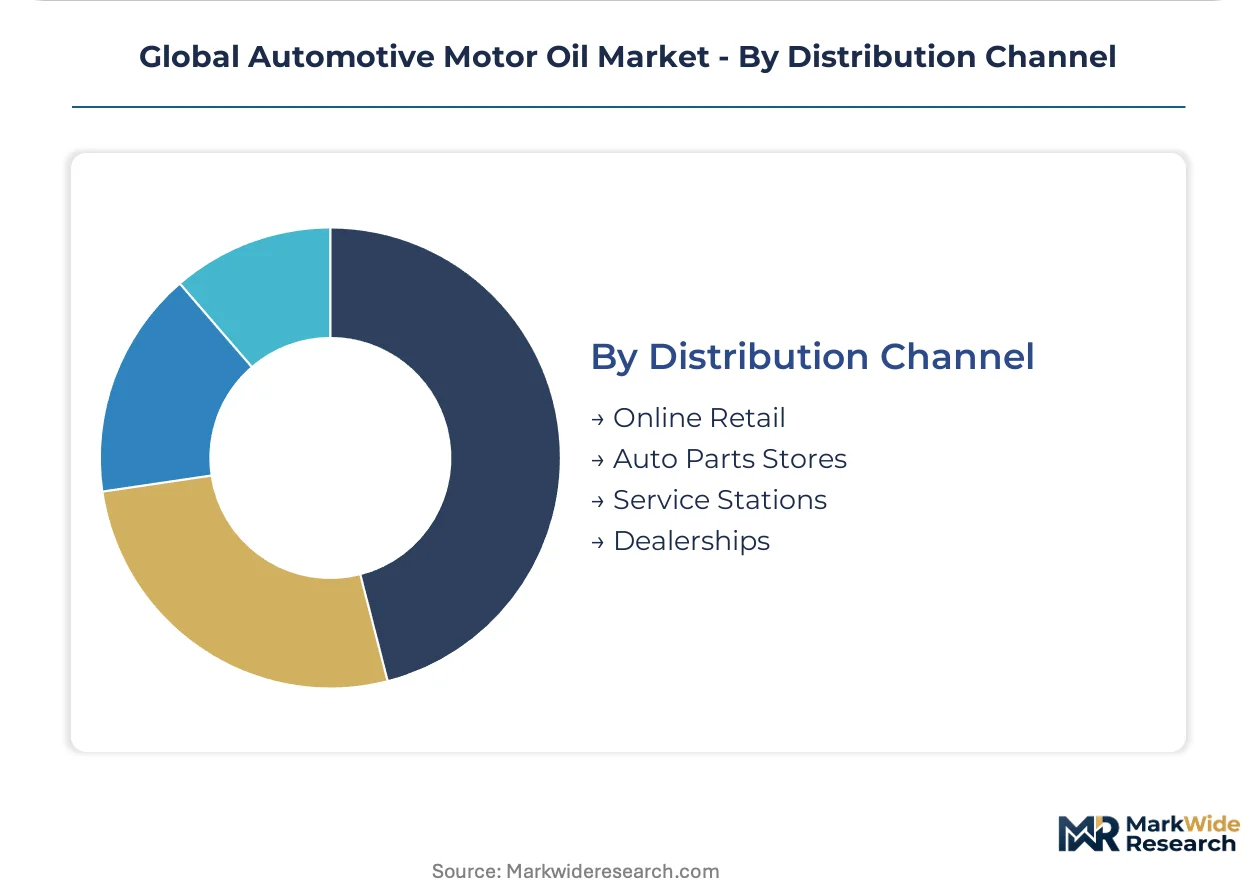
Distribution Channel:
Channel control determines margin retention and brand positioning access across fragmented service landscapes.
- Service Stations:Captive quick-lube networks in North America secure volume commitments that stabilize blender throughput against aftermarket price volatility. Controlled final-mile distribution anchors premium positioning.
- Dealerships:OEM-authorized service channels in Germany and China enforce factory-fill specification compliance, creating captive supply relationships with approved blenders.
- Auto Parts Stores:Retail do-it-yourself demand concentrates in US chains and Brazilian independent distributors where spot purchasing persists.
- Online Retail:E-commerce platforms in India's organized workshop consolidation and Latin American independent garage migration enable contractual volume commitments bundled with diagnostic equipment.
Service stations retain the highest throughput concentration; online retail is gaining share fastest as procurement platforms consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base-oil trade flows reveal persistent imbalances: the United States and Northeast Asia export premium Group II/III stocks while India and Brazil remain net importers dependent on Gulf Coast and Singapore refinery output. This geographic asymmetry shapes blender location decisions and captive supply strategies.
United States
Gulf Coast petrochemical complexes supply Group II/III base oils to domestic blenders and export markets. EPA fuel-economy standards and NHTSA corporate average fuel economy mandates push low-viscosity synthetic formulations. Houston and Port Arthur anchor integrated refining-blending corridors where ExxonMobil and Shell operate captive networks.
Germany
REACH chemical-registration requirements and F-Gas Regulation compliance costs filter out smaller additive-package suppliers. KBA vehicle-type approval processes synchronize with ACEA C6 lubricant specifications. The Rhine-Ruhr industrial zone hosts Fuchs Petrolub and TotalEnergies blending facilities serving captive fleet re-refining programs.
China
GB standards evolution and MEE dual-carbon reporting requirements force state-owned refiners toward emissions-abatement investments. MIIT new-energy vehicle mandates indirectly pressure lubricant formulation for hybrid thermal-management systems. Yangtze River Delta cities—Shanghai, Nanjing, Suzhou—concentrate Sinopec and domestic OEM factory-fill demand.
India
BIS certification gaps exclude unapproved import formulations as organized workshop chains consolidate in Mumbai and Delhi industrial zones. DGFT import duties on finished lubricants protect domestic blenders. Gujarat's Jamnagar refinery corridor and Maharashtra's Pune-Nashik automotive belt anchor local base-oil supply.
Brazil
ANVISA chemical-control frameworks and IBAMA environmental licensing slow additive-package registration timelines. Price-sensitive motorcycle and aging passenger-vehicle fleets sustain conventional motor oil dominance. São Paulo state's ABC automotive cluster and Rio de Janeiro's industrial port zone concentrate blending capacity.
Global Automotive Motor Oil Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on base-stock and additive-package supply. The market structures around three tiers: integrated majors with captive refining, mid-tier blenders dependent on toll-manufacturing, and regional distributors controlling final-mile service channels. Strategic moves concentrate on backward integration into base-oil supply and forward integration into quick-lube networks.
Among integrated petroleum majors, ExxonMobil Corporation and Shell plc exemplify the captive-refinery archetype with Gulf Coast and Singapore base-oil positions. Valvoline Inc. represents the service-channel anchor model, controlling quick-lube throughput commitments that stabilize blender volume against aftermarket volatility. These three occupy positions that illustrate how feedstock access and distribution control determine margin capture.
| Leading Market Players |
|---|
| Chevron Corporation |
| Valvoline Inc. |
| ExxonMobil Corporation |
| Fuchs Petrolub SE |
| Sinopec Lubricant Company |
| Shell plc |
| TotalEnergies SE |
| Lukoil |
| BP plc |
| Others |
Supply Flow & Price Mechanics
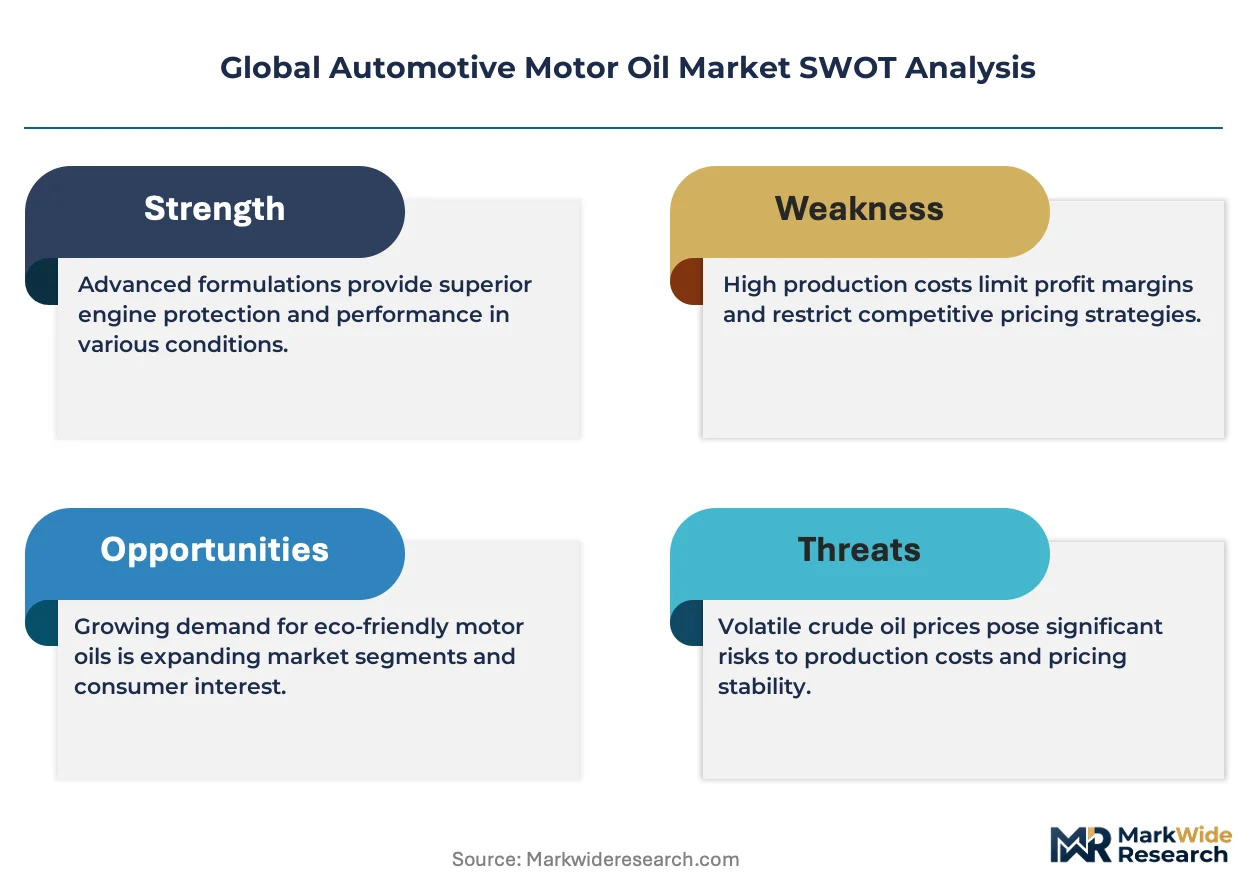
Houston-Port Arthur freight corridors transmit Gulf Coast base-oil cost advantages to blenders across North America, compressing delivered pricing for high-volume synthetic formulations while amplifying margin pressure on importers in India and Brazil lacking integrated refinery access. This logistics asymmetry stratifies pricing power between captive supply networks and toll-dependent regional blenders.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that secure volume commitments against spot market volatility. Pricing stratifies across full synthetic, semi-synthetic, and conventional tiers driven by ACEA/API certification grade and captive refinery integration. Cost compression in semi-synthetic formulations is intensifying because European REACH compliance burdens divert additive-package investment toward regulatory documentation rather than performance differentiation. Commercial fleet operators in Germany exhibit lowest price sensitivity due to closed-loop re-refining programs, while independent motorcycle service points in India's Delhi industrial zone demand sachet pricing below drum-equivalent thresholds.
Supply Chain Analysis
Extended payment terms from additive majors to mid-tier blenders are restructuring working-capital requirements across the value chain. Base-oil supply concentrates in the United States, China, and South Korea, with Group II/III capacity clustering on the US Gulf Coast and Northeast Asia. Formulation chemistry draws from petroleum-derived base stocks, ashless friction modifiers, and zinc dialkyldithiophosphate alternatives facing REACH sunset reviews. Single-source vulnerability persists for European blenders dependent on Singapore refinery exports. Distribution runs through captive quick-lube networks in North America, OEM-authorized dealerships in Germany and China, and consolidating online procurement platforms in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across specification tiers and certification jurisdictions is opening niche positions for specialized blenders as OEM factory-fill requirements diverge from aftermarket service protocols. Turbocharged engine proliferation and extended drain intervals are simultaneously compressing volume-per-vehicle and elevating thermal-stability premiums.
For Market Incumbents: Entrench captive supply relationships with state-owned base-oil refiners in China's Yangtze River Delta corridor to defend against Sinopec's integrated factory-fill expansion. Deepen backward integration into re-refining capacity serving European fleet operators, securing feedstock supply against virgin base-oil price volatility. Prioritize ACEA C6 additive-package certification investment to maintain access to German OEM channels as REACH authorization timelines tighten.
For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified semi-synthetic segment as organized workshop chains in Mumbai and Delhi industrial zones consolidate procurement through integrated service platforms. Target Brazil's price-sensitive motorcycle aftermarket through sachet-format distribution partnerships with independent roadside repair networks. Leverage toll-manufacturing arrangements with Gulf Coast refiners to bypass capital-intensive base-oil capacity requirements.
For Investors and Strategic Acquirers: REACH chemical-registration sunset reviews reshape the acquisition landscape by concentrating additive-package expertise among incumbent majors with compliance infrastructure. Long-term viability hinges on dual-certification capabilities spanning OEM factory-fill and aftermarket service channels. Mid-tier blenders with approved BIS formulations and captive quick-lube throughput commitments in North America represent priority acquisition targets. Monitor GB standards evolution in China as the inflection signal for state-owned refinery consolidation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base-Oil Refining | Captive Group II/III supply from Gulf Coast complexes secures margin capture against import-dependent competitors. |
| ACEA C6 Additive-Package Certification | European emissions compliance unlocks OEM factory-fill approvals in Germany's KBA-synchronized vehicle-type processes. |
| Captive Quick-Lube Network Expansion | Controlled final-mile distribution in North America stabilizes blender throughput against aftermarket price volatility. |
| Closed-Loop Re-Refining Program Development | German and California fleet pilots secure post-consumer feedstock supply for circular-economy mandates. |
| BIS Certification Investment for India Entry | Domestic approval barrier exclusion captures organized workshop chain consolidation in Mumbai industrial zones. |
Methodological Framework
Desk research of customs trade data, SEC 10-K filings, and national lubricant association statistics preceded structured interviews with OEM platform engineers, aftermarket distribution heads, refinery operations managers, and additive-package R&D directors. Primary fieldwork across the United States, Germany, China, India, and Brazil validated secondary estimates of base-oil trade flows and blender capacity utilization. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Assumptions held OEM factory-fill specification trajectories and regional emissions-compliance deadlines fixed while varying synthetic-conversion rates and re-refining adoption curves across the projection horizon. Segmentation dimensions spanned formulation chemistry, packaging economics, vehicle class, and channel control structure. CAGRs derived from elasticity-adjusted demand projections incorporating turbocharged engine penetration and drain-interval extension parameters. Industry-specific inputs included IHS Markit vehicle registration data and national base-oil refinery capacity disclosures.
Sensitivities concentrate around REACH authorization timelines, China's MEE dual-carbon enforcement intensity, and commercial fleet preventive-maintenance contract renewals. Forecasts reflect documented assumptions regarding specification-grade substitution elasticity and channel consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
VVT Actuators Market
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
Europe Industrial Roller Chain Drive Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Accelerator Pedal Module Market