
 Russia Automotive Parts Magnesium Die Casting Market | 2026-2036
Russia Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Parts Magnesium Die Casting Market Analytics
Aftermarket service revenue for magnesium casting refurbishment is fragmenting as OEMs extend warranty coverage and tighten parts authentication. Solikamsk Magnesium Plant JSC anchors Russia's upstream supply with captive magnesium smelting and alloy feedstock production. Continental Casting LLC competes through specialized high-pressure die casting lines serving domestic OEM transmission programs. Georg Fischer AG leverages its global tooling know-how to sustain premium positioning among Tier-1 suppliers operating in Russia.
Russia automotive parts magnesium die casting involves injecting molten magnesium alloys—typically AZ91D or AM60B with aluminum content between 8.3% and 9.7%—into hardened steel molds at pressures exceeding 70 MPa to produce lightweight, high-strength components. The process achieves density of 1.81 g/cm³, yielding parts 33% lighter than comparable aluminum castings for powertrain and structural applications where mass reduction directly improves fuel efficiency. Structural parts command the deepest margin pools as crashworthiness certification and alloy purity requirements create qualification barriers for new entrants. Electric vehicles represent the fastest-growing application segment as battery enclosure castings and motor housing demand rises with domestic EV platform development, while passenger vehicles retain the largest volume base due to Lada and Kia-Hyundai assembly output.
Russia's Federal Agency on Technical Regulating and Metrology administers GOST R certification and TR CU 018/2011 compliance, which mandates fatigue testing and corrosion resistance thresholds for safety-critical magnesium castings. The country's national automotive regulator enforces homologation protocols that restrict non-certified imports and favor domestic foundries with established test documentation. Stakeholders must monitor how alloy price volatility and sanctions-affected tooling imports reshape casting economics and localize supply chain decisions.
Market Dynamics
Domestic OEMs are consolidating supplier relationships around localized magnesium alloy sourcing as TR CU 018/2011 fatigue-testing mandates reshape qualification timelines and procurement risk profiles for structural casting programs.
Growth Catalysts
- TR CU 018/2011 homologation protocols:Russia's vehicle safety framework mandates domestic fatigue-testing documentation, channeling OEM sourcing toward established foundries with certified test facilities.
- AZ91D alloy density advantages:Powertrain engineers specify magnesium transmission housings achieving 1.81 g/cm³ to meet corporate average fuel economy targets without redesigning assembly architectures.
- Volga Federal District supplier clustering:Proximity to AvtoVAZ assembly plants reduces logistics costs and enables just-in-time delivery schedules for steering column bracket programs.
Market Restraints
- Magnesium ingot price volatility:Solikamsk Magnesium Plant JSC's smelter output fluctuations transmit directly to die-casting feedstock costs, compressing margin predictability for contract manufacturers.
- Sanctions-affected tooling imports:Hardened steel mold fabrication equipment faces restricted supply channels, extending lead times for high-pressure die casting line expansions.
- Aluminum substitution in non-structural applications:Lower-grade brackets and covers face displacement by aluminum sand castings where crashworthiness certification is not required.
Strategic Opportunities
- Battery enclosure castings for EV platforms:Domestic electric vehicle development programs are specifying magnesium motor housings and thermal management housings as platform architectures mature.
- Central Federal District aftermarket refurbishment:Moscow-region service networks lack certified magnesium welding and crack-repair capabilities, creating white space for specialized remanufacturing operations.
- GOST R alloy purity premiums:Certification tiers rewarding 99.9% magnesium content enable pricing stratification beyond commodity AZ91D specifications.
Industry Challenges
- High-pressure die casting technician scarcity:Russian technical institutes graduate fewer metallurgists with molten magnesium handling credentials than foundries require for 70 MPa injection line operations.
- TR CU 018/2011 corrosion-resistance documentation:Salt-spray testing protocols add six to nine months to new component qualification, delaying program launches and freezing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Parts Magnesium Die Casting Market |
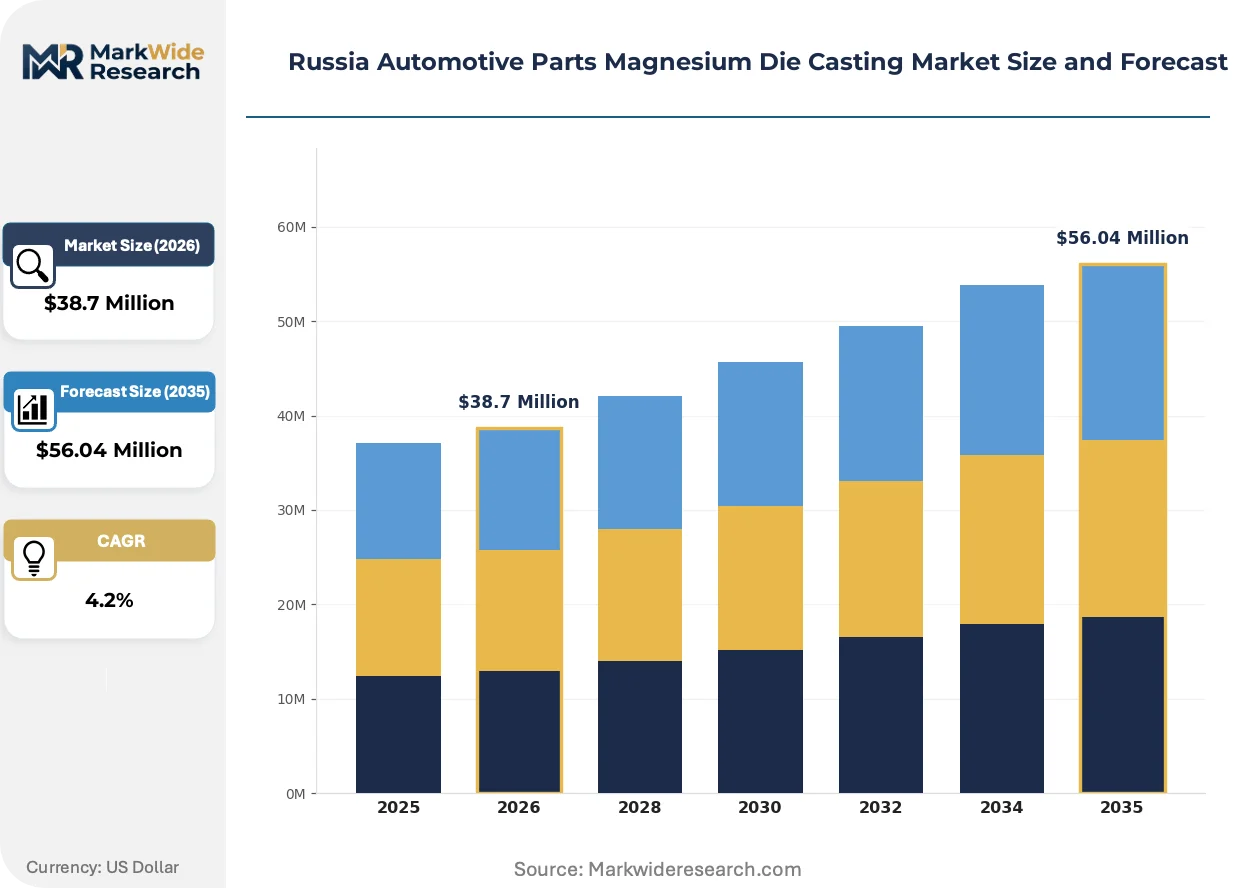
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $56.04 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Chassis Components, Structural Parts Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Vacuum Die Casting, Semi-Solid Die Casting |
| Companies Covered | Georg Fischer AG, China Precision Diecasting, Meridian Lightweight Technologies, Solikamsk Magnesium Plant JSC, Continental Casting LLC, Pace Industries, Gibbs Die Casting Group, Dynacast, Shiloh Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Parts Magnesium Die Casting Market Evolving Landscape
Process automation and alloy formulation advances are compressing cycle times while regulatory documentation requirements are extending supplier qualification periods, creating divergent pressures on capital deployment.
Thixomolding technology for semi-solid magnesium processing is migrating from aerospace prototyping into automotive structural applications. Tier-1 suppliers serving AvtoVAZ programs are piloting thixomolded A-pillar reinforcements to reduce porosity defects. This migration from conventional high-pressure die casting is enabling thinner-wall designs that maintain crashworthiness certification under TR CU 018/2011 load-case testing.
Russia's Federal Agency on Technical Regulating and Metrology is expanding GOST R certification scope to cover recycled magnesium alloy content declarations. Foundries must now document scrap-source traceability and secondary refining protocols. Battery enclosure manufacturers are most affected, as EV platform suppliers face dual pressure for lightweighting and circular-economy compliance in homologation submissions.
Buyer concentration among domestic OEMs is compressing supplier negotiation leverage and standardizing contract terms. AvtoVAZ and its joint-venture partners now mandate multi-year price-lock provisions with raw-material pass-through caps. Tier-2 foundries in the Volga Federal District are responding by forming purchasing cooperatives for magnesium ingot to restore volume-based pricing power against Solikamsk Magnesium Plant JSC.
Russia Automotive Parts Magnesium Die Casting Market Segmentation
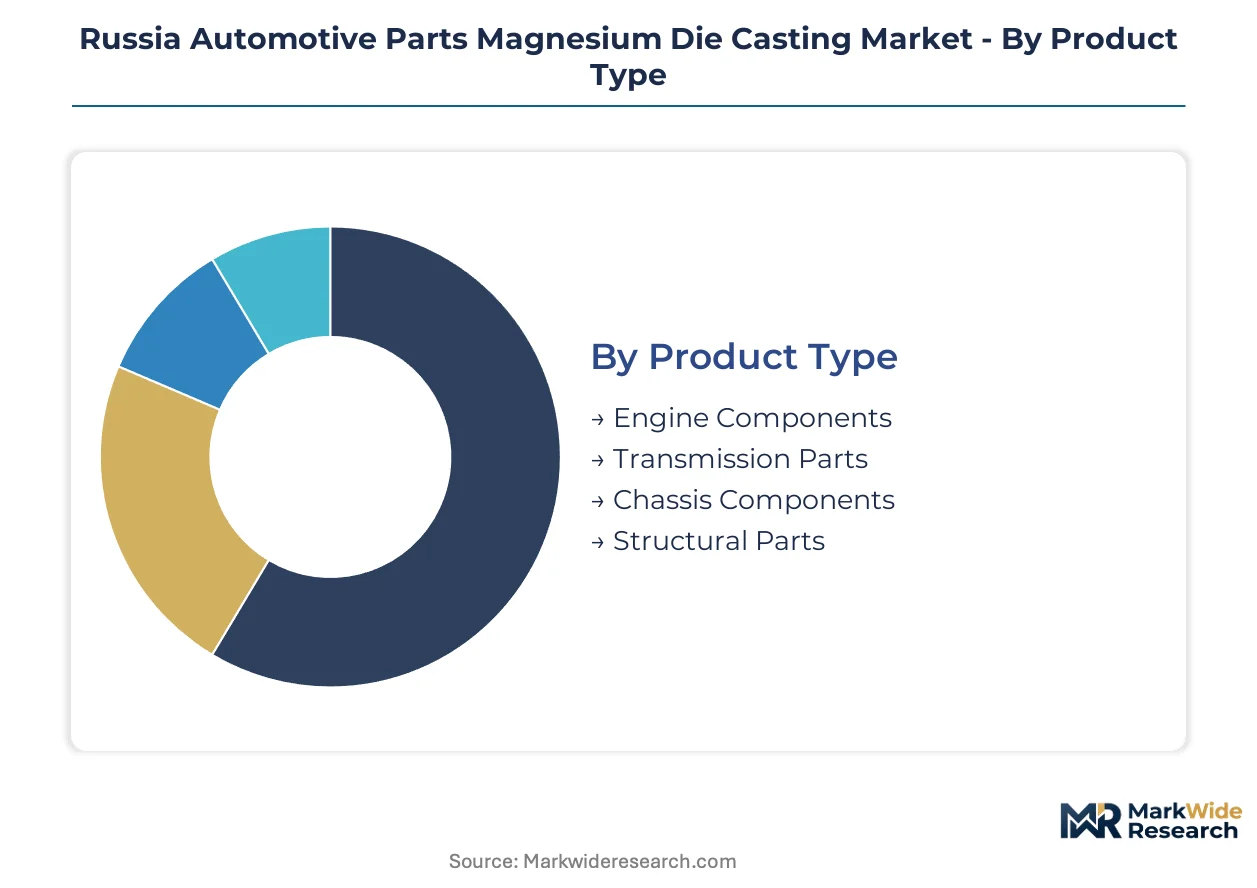
Magnesium die casting programs in Russia exhibit divergent production rhythms across product categories, with transmission housings turning on 90-second cycles versus structural castings requiring 180-second dwell times for porosity control. Understanding these velocity differentials helps suppliers align capacity investments with OEM scheduling requirements and TR CU 018/2011 qualification timelines.
Product Type:
Cycle-time compression varies dramatically across product categories, with thin-wall transmission components achieving sub-60-second injection-to-ejection intervals while structural castings absorb extended thermal management phases.
- Transmission Parts:Gearbox housings and clutch bell housings utilize AZ91D alloy at 1.81 g/cm³ density to achieve the fastest production cycles in Russian foundries. AvtoVAZ procurement concentrates in Tolyatti for Lada automated manual transmission programs where mass reduction targets override material cost premiums.
- Structural Parts:A-pillar reinforcements and steering column brackets demand extended solidification control to meet TR CU 018/2011 crashworthiness certification. The Volga Federal District supplier cluster absorbs these slower cycles through dedicated high-tonnage press lines serving domestic OEM safety-critical programs.
- Engine Components:Valve covers and oil pans spec AM60B for elevated temperature resistance.
- Chassis Components:Crossmembers and suspension brackets face aluminum substitution pressure in non-certified applications.
Transmission parts anchor the volume base while structural parts gain share at the steepest rate.
Application:
Customer engineering specifications fragment across vehicle classes, with passenger platforms prioritizing fuel economy coefficients and commercial fleets emphasizing payload recovery through chassis lightweighting.
- Passenger Vehicles:Lada Granta and Vesta platforms specify magnesium steering column brackets and seat frames to meet corporate average fuel economy mandates without platform redesign. Kia-Hyundai St. Petersburg output sustains steady demand for transmission housing castings.
- Electric Vehicles:Battery enclosure castings and motor housings represent the application segment expanding most quickly as domestic EV platforms from Moskvich and AvtoVAZ advance through homologation. Thermal management housing requirements exceed conventional powertrain specifications for alloy purity.
- Commercial Vehicles:GAZ Group light commercial vehicle programs specify differential housings for payload optimization.
- Heavy-Duty Trucks:Kamaz cab structures absorb limited magnesium adoption due to cost sensitivity and load-bearing requirements.
Passenger vehicles retain the deepest production volume while electric vehicles command the steepest expansion trajectory.
End User:
Procurement authority concentrates differently across the value chain, with OEMs controlling safety-critical specifications and Tier-1 suppliers managing commodity bracket programs.
- OEMs:AvtoVAZ and foreign joint-venture partners directly source transmission housings and structural castings to control TR CU 018/2011 certification documentation. Moscow-based engineering centers mandate alloy traceability from Solikamsk Magnesium Plant JSC smelter to finished component.
- Tier-1 Suppliers:Continental Casting LLC and similar specialists operate as program integrators for steering column brackets and pedal box assemblies, consolidating multi-component supply to vehicle assemblers.
- Vehicle Assemblers:Contract manufacturers in the Volga Federal District perform final magnesium component integration.
- Aftermarket Providers:Fragmented refurbishment networks lack GOST R-certified welding capabilities for crack repair.
OEMs dominate safety-critical procurement while Tier-1 suppliers capture the broadest component scope.
Technology:
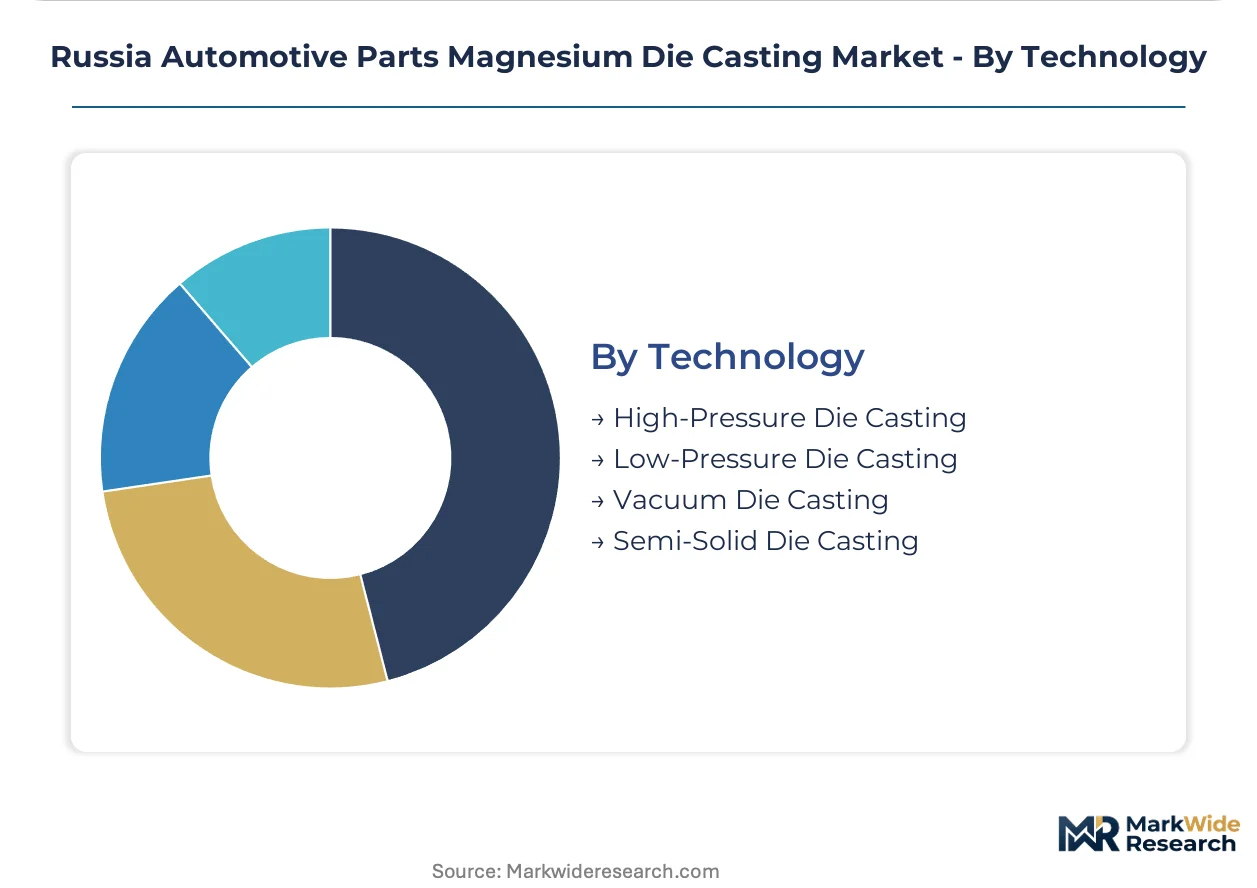
Capital intensity stratifies across process technologies, with conventional high-pressure lines requiring 70 MPa injection systems versus thixomolding's semi-solid feedstock preparation infrastructure.
- High-Pressure Die Casting:Conventional 70 MPa injection lines dominate Russian installed base for AZ91D transmission housings. Solikamsk-area foundries operate legacy equipment with cycle times optimized for commodity bracket production.
- Semi-Solid Die Casting:Thixomolding technology migrates from aerospace prototyping into automotive structural applications with reduced porosity. Tier-1 suppliers pilot A-pillar reinforcements for AvtoVAZ crashworthiness programs under extended TR CU 018/2011 load-case testing.
- Vacuum Die Casting:Reduced gas entrapment enables thinner-wall battery enclosure designs for EV thermal management.
- Low-Pressure Die Casting:Limited adoption for wheel and non-structural applications with lower integrity requirements.
High-pressure die casting retains the dominant equipment base while semi-solid processing gains adoption for premium structural qualifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Volga Federal District show the least price elasticity as AvtoVAZ programs prioritize TR CU 018/2011 certification over feedstock costs, while aftermarket channels in the Central Federal District absorb the steepest margin compression from alloy volatility.
Volga Federal District
AvtoVAZ assembly plants in Tolyatti and Izhevsk anchor procurement for Lada transmission housings and steering column brackets. The region's supplier cluster operates under TR CU 018/2011 fatigue-testing mandates that favor established foundries with certified documentation. Solikamsk Magnesium Plant JSC's proximity reduces inbound logistics costs for AZ91D alloy feedstock.
Central Federal District
Moscow-region engineering centers specify premium-grade castings for imported OEM joint-venture programs where alloy traceability requirements exceed commodity specifications. The national automotive regulator enforces homologation protocols that restrict non-certified imports. Tier-1 suppliers concentrate in the Moscow Oblast to service just-in-time delivery contracts.
Northwestern Federal District
Kia-Hyundai St. Petersburg output sustains steady demand for gearbox housings with density targets at 1.81 g/cm³. The region's port infrastructure enables tooling import channels that bypass sanctions-affected overland routes. Local foundries specialize in high-pressure die casting cycles optimized for 90-second transmission component production.
Ural Federal District
Chelyabinsk and Yekaterinburg machine-building complexes absorb magnesium castings for commercial vehicle differential housings. Regional technical institutes face shortages of metallurgists certified for 70 MPa injection line operations. The district's heavy industrial base supports captive remelting facilities for scrap alloy recovery.
Southern Federal District
Rostov-on-Don assembly plants for GAZ Group light commercial vehicles specify chassis brackets where aluminum substitution pressure is weakest. The region's agricultural machinery sector creates secondary demand for non-structural magnesium covers. Logistics connectivity to Black Sea ports offers alternative alloy import corridors.
Russia Automotive Parts Magnesium Die Casting Market Competitive Landscape
Capability concentration sits with upstream alloy producers and certified foundries; scale advantage sits with program integrators serving multi-OEM transmission contracts. The market structures around three tiers: captive magnesium smelters controlling feedstock purity, specialized high-pressure die casting operations with TR CU 018/2011 documentation, and global tooling specialists licensing process technology. Dominant competitive moves include backward integration into alloy supply and geographic clustering near AvtoVAZ assembly plants.
Within the captive supply tier, Solikamsk Magnesium Plant JSC anchors Russia's upstream position through in-house smelting and alloy feedstock production. Continental Casting LLC occupies a position among specialized high-pressure die casting operators serving domestic OEM transmission programs. Georg Fischer AG represents the global tooling archetype, leveraging international process know-how to sustain premium positioning among Tier-1 suppliers operating in Russia.
| Leading Market Players |
|---|
| Georg Fischer AG |
| China Precision Diecasting |
| Meridian Lightweight Technologies |
| Solikamsk Magnesium Plant JSC |
| Continental Casting LLC |
| Pace Industries |
| Gibbs Die Casting Group |
| Dynacast |
| Shiloh Industries |
| Others |
Value Network & Pricing Analysis
Rail freight corridors from Solikamsk to Tolyatti transmit magnesium ingot cost volatility directly to die-casting contract rates, amplifying price differentiation between TR CU 018/2011-certified structural programs and commodity bracket production.
Pricing Analysis
Aftermarket service contracts and extended warranty bundles now drive lifetime value capture more than initial component sales. Three-tier pricing structure across premium, standard, and economy levels separates GOST R-certified crashworthiness castings from commodity AZ91D transmission housings. Cost compression in non-structural brackets is intensifying because aluminum sand castings displace magnesium where certification is not required. Tier-1 suppliers serving AvtoVAZ programs show the least price sensitivity, while fragmented aftermarket refurbishment channels absorb the steepest margin pressure.
Supply Chain Analysis
Upstream AZ91D and AM60B alloy feedstock draws from Russia's captive Solikamsk smelter, Chinese export flows, and limited Kazakh secondary refining capacity. Hardened steel mold fabrication equipment, high-pressure injection systems, and vacuum-assisted casting tooling constitute critical component dependencies. Single-source vulnerability concentrates in sanctions-affected European tooling imports, extending lead times for 70 MPa line expansions. Distribution runs through Volga Federal District supplier clusters feeding just-in-time AvtoVAZ assembly schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's automotive magnesium die casting market represents an early-cycle expansion story as domestic EV platform development accelerates battery enclosure casting specifications beyond conventional powertrain applications.
For Market Incumbents: Build certification moats around TR CU 018/2011 fatigue-testing documentation to lock out non-compliant imports. Anchor capacity additions in the Volga Federal District to capture AvtoVAZ transmission program consolidation. Counter aluminum substitution threats by embedding magnesium designs into platform architectures during early engineering phases. For New Entrants and Emerging Players: Build out specialized thixomolding capabilities for A-pillar reinforcements where porosity control creates qualification barriers. Target the Central Federal District aftermarket refurbishment gap, where Moscow-region service networks lack GOST R-certified magnesium welding. Pursue joint-venture structures with Solikamsk Magnesium Plant JSC to secure alloy supply preferencing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semi-solid processing specialists with EV thermal management housing qualifications. Five-to-ten-year viability hinges on battery enclosure casting penetration as domestic electric vehicle platforms scale. Watch thixomolding adoption rates among Tier-1 suppliers as the inflection signal for process technology shift.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Smelting | Captive AZ91D feedstock production insulates margin from Solikamsk price volatility. |
| Thixomolding Process Qualification | Semi-solid A-pillar reinforcements meet TR CU 018/2011 crashworthiness with thinner walls. |
| Battery Enclosure Casting Certification | EV thermal management housings command purity premiums beyond commodity specifications. |
| Volga Federal District Capacity Expansion | Proximity to AvtoVAZ Tolyatti assembly enables just-in-time delivery contracts. |
| Aftermarket Refurbishment Network Buildout | Moscow-region certified welding capabilities capture service revenue from aging vehicle fleets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, GOST R certification registries, and vehicle production databases. Interviews with die-casting plant managers, OEM platform engineers, Tier-1 procurement leads, and aftermarket service operators informed demand-side validation. Bottom-up capacity assessments across Volga Federal District foundries were triangulated against top-down consumption estimates derived from AvtoVAZ and Kia-Hyundai St. Petersburg output figures.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation. CAGRs were derived from regression analysis of historical die-casting tonnage against vehicle assembly volumes, with adjustments for EV platform magnesium intensity and thixomolding adoption curves. Alloy price elasticity and sanctions-affected tooling import constraints were modeled as scenario variables.
Practitioners should monitor TR CU 018/2011 regulatory amendments and Solikamsk smelter output fluctuations for early signals of forecast revision. Quarterly review of EV platform homologation timelines and thixomolding pilot program outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Automotive Seat Track Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Automotive Paint Robots Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Global Automotive Nitrous Oxide System Market
Automotive Parts
Global Motorcycle Carbon Ceramic Brake Rotors Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Oil Catch Cans Market