
 Global Embolotherapy Market | 2026-2036
Global Embolotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Embolotherapy Market Foresight
Oncology interventional suites within hospitals is consolidating as the primary revenue anchor for embolotherapy vendors. Medtronic leverages its integrated catheter and coil portfolio to dominate neurovascular embolization workflows. Boston Scientific Corporation sustains competitive intensity through specialized drug-eluting bead platforms for hepatocellular carcinoma. Penumbra differentiates via aspiration and mechanical thrombectomy adjacencies that extend its addressable case mix.
Embolotherapy encompasses catheter-directed occlusion of blood vessels using mechanical devices, particulate agents, or liquid embolics to achieve hemorrhage control, tumor devascularization, or malformation elimination. Platinum-tungsten alloy coils with synthetic fiber jackets constitute a core mechanical platform, while n-butyl cyanoacrylate and ethylene vinyl alcohol copolymers serve as liquid embolic systems for high-flow fistulas. Embolic agents command the largest revenue pool given recurring consumption per procedure, whereas image-guided therapy modalities represent the fastest-expanding delivery mode as cone-beam CT and 3D roadmap fusion reduce fluoroscopy burden. Catheter-based procedures remain the mature workhorse segment, though minimally invasive techniques gain share as outpatient migration accelerates.
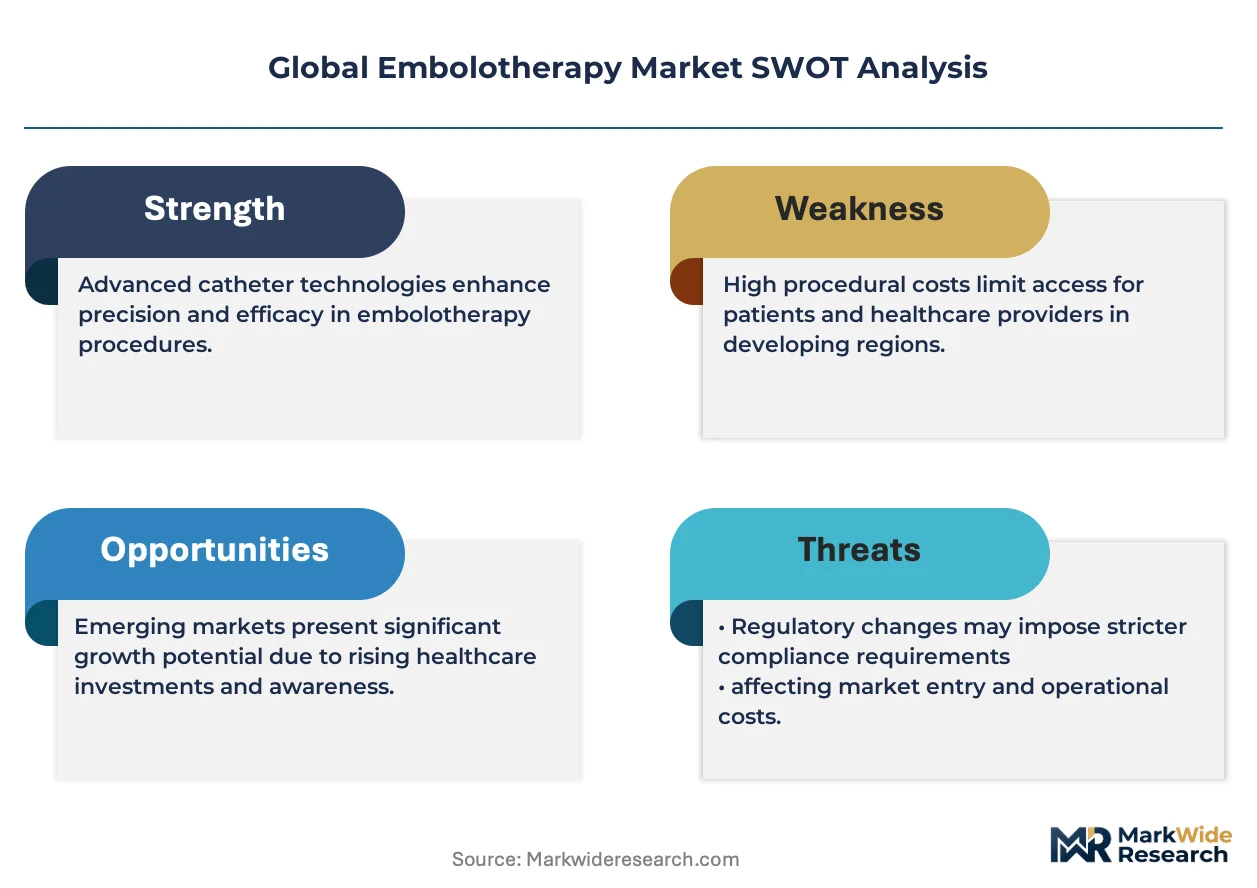
The FDA's breakthrough device program and the EU MDR recertification timeline shape product development priorities and market access cadence for embolotherapy manufacturers. EMA's heightened scrutiny of permanent implantable devices extends clinical evidence requirements for coils and liquid embolics in Europe. Stakeholders must monitor reimbursement parity between inpatient and ambulatory surgical center settings as site-of-care economics determine adoption velocity for newer delivery platforms.
Market Dynamics
Embolotherapy workflows are consolidating around image-guided delivery platforms as cone-beam CT and 3D roadmap fusion reduce fluoroscopy burden and expand procedure eligibility to outpatient settings.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's accelerated commercialization track compresses time-to-market for novel liquid embolics and bioabsorbable coils in the United States.
- Germany's Angiography Infrastructure:Specialized angiography suites with reimbursement clarity under the German DRG system sustain procedure volume expansion for hepatocellular carcinoma interventions.
- Drug-Eluting Bead Technology:Doxorubicin-loaded microspheres enable locoregional chemotherapy delivery with reduced systemic toxicity, expanding treatable patient populations.
Market Restraints
- Platinum-Tungsten Alloy Supply Concentration:Coil manufacturing depends on concentrated rare metal sourcing from limited geopolitical regions, exposing margins to raw material volatility.
- EU MDR Recertification Burden:EMA's heightened scrutiny of permanent implantable devices extends clinical evidence requirements and delays market access for next-generation embolic agents in Europe.
- Catheter Reprocessing Economics:Single-use microcatheter consumption per procedure creates recurring cost pressure that limits adoption in budget-constrained healthcare systems.
Strategic Opportunities
- India's Interventional Radiology Expansion:PLI scheme incentives for medical device manufacturing and CDSCO streamlined approvals create first-mover advantage for localized production.
- Mechanical Thrombectomy Convergence:Aspiration platforms combined with embolic delivery systems enable stroke and trauma crossover applications in hybrid angiography suites.
- Ambulatory Surgical Center Migration:Site-of-care economics favor outpatient embolization for uterine fibroids and benign prostatic hyperplasia in United States reimbursement frameworks.
Industry Challenges
- Interventional Radiologist Training Pipeline:Fellowship program capacity constraints limit qualified operator supply for complex neurovascular and oncologic embolization procedures.
- ISO 13485 Quality System Complexity:Multinational manufacturers face divergent audit requirements across notified bodies, elongating certification timelines for liquid embolic formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Embolotherapy Market |
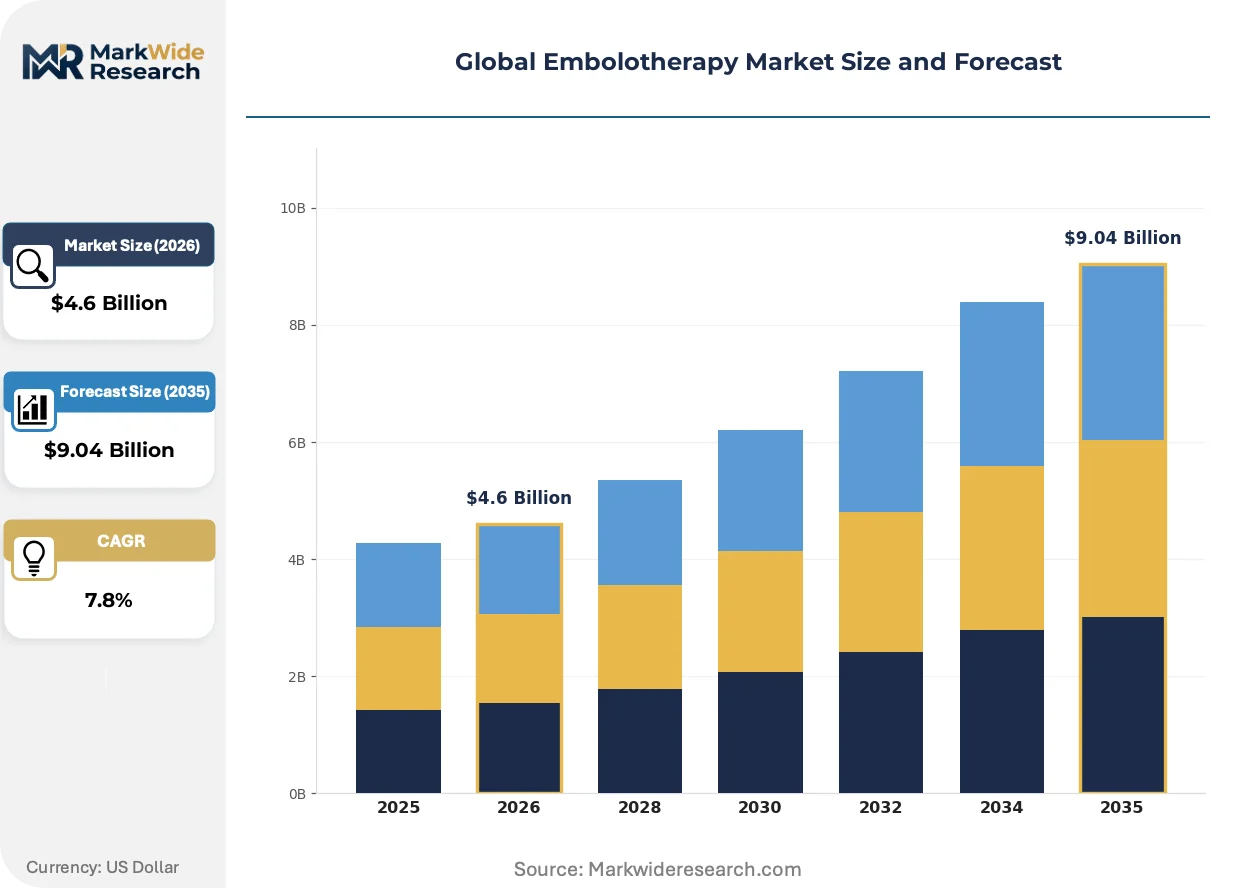
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $9.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embolic Agents, Catheters, Microcatheters, Delivery Systems, Embolization Coils, Balloon Catheters Therapy Area: Neurovascular Disorders, Cardiovascular Diseases, Liver Tumors, Uterine Fibroids, Gastrointestinal Bleeding, Peripheral Vascular Diseases End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Centers Delivery Mode: Catheter-Based Procedures, Image-Guided Therapy, Minimally Invasive Techniques, Fluoroscopy-Guided Embolization |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific Corporation, Terumo Corporation, Stryker Corporation, Penumbra, Abbott Laboratories, Cook Medical, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Embolotherapy Market Shifts & Advancements
Digital integration across imaging, navigation, and delivery systems is compressing procedure times and enabling same-day discharge protocols that reshape site-of-care economics.
Shape-memory polymer coils with controlled expansion profiles are rewriting mechanical embolization standards by enabling precise deployment in tortuous vasculature. Interventional radiology departments at academic medical centers are adopting these platforms for cerebral aneurysm and arteriovenous malformation cases. The technology is rewriting competitive positioning by reducing retreatment rates and extending device premium capture.
EMA's Medical Device Regulation recertification timeline is compressing product lifecycle planning for European market participants. Manufacturers must generate additional clinical evidence for permanent implants previously grandfathered under the Medical Device Directive. Liquid embolic systems with longer regulatory histories face disproportionate scrutiny, favoring newer entrants with purpose-built MDR dossiers.
Hospital procurement committees are unbundling capital equipment from consumable contracts to optimize total cost of ownership across hybrid angiography suite investments. Integrated vendors face pressure to separate imaging system leases from coil and bead supply agreements. This pattern is most visible in United States IDN consolidation, where centralized sourcing functions extract volume-based pricing concessions across catheter and embolic agent categories.
Global Embolotherapy Market Segmentation
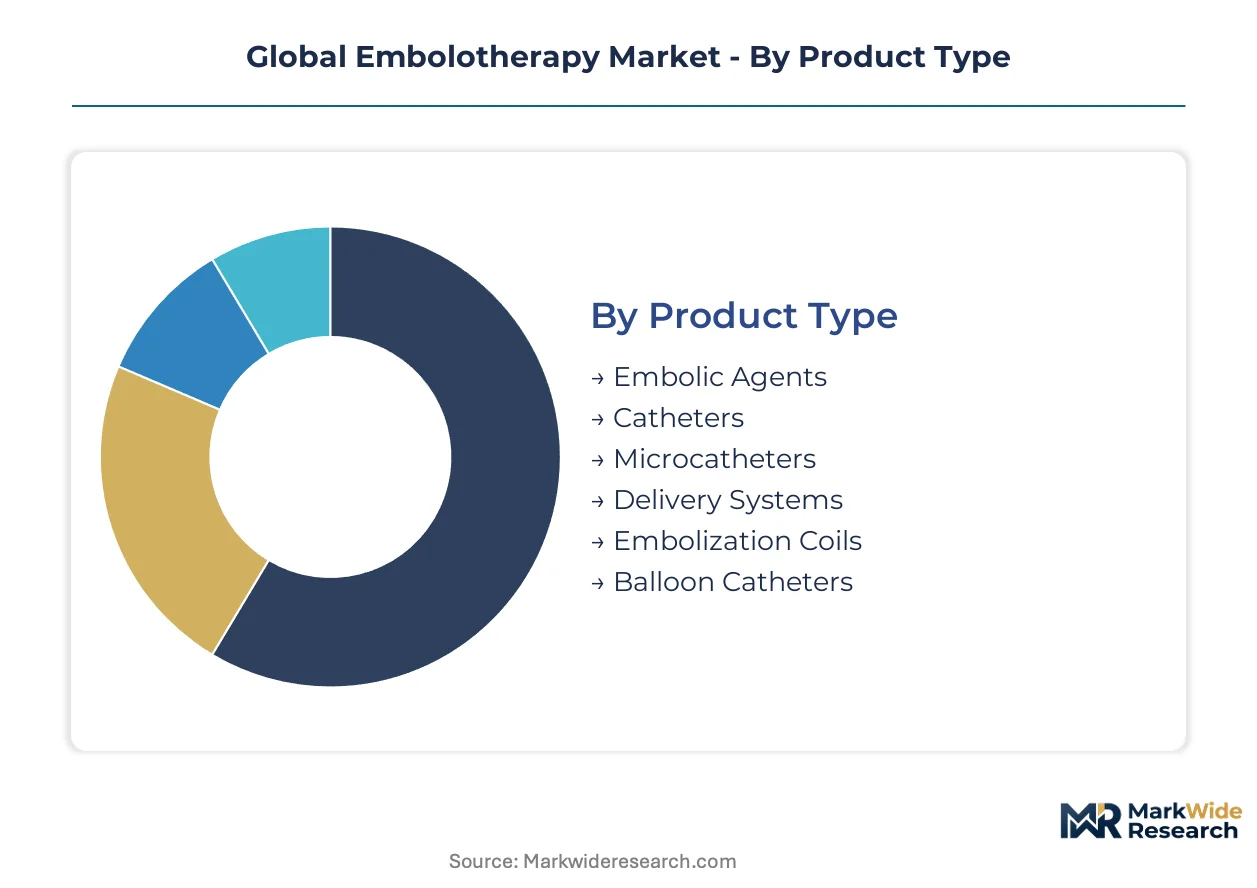
Segmentation in embolotherapy reveals how capital deployment, regulatory pathways, and site-of-care economics fragment purchasing authority across hospitals, outpatient centers, and specialized clinics. Understanding these divides enables vendors to align R&D investment with the specific evidence requirements and procurement workflows of each channel.
Product Type:
Capital intensity concentrates in delivery systems and imaging-integrated platforms, whereas consumable embolic agents generate recurring revenue with lower fixed asset requirements.
- Embolic Agents:Particulate microspheres, liquid polymers, and mechanical coils constitute the recurring revenue backbone of embolotherapy. Demand concentrates in oncology interventional suites at academic medical centers in the United States, where drug-eluting bead protocols for hepatocellular carcinoma require consistent resupply.
- Embolization Coils:Platinum-tungsten alloys with synthetic fiber jackets enable mechanical vessel occlusion for cerebral aneurysms and arteriovenous malformations. German hospital procurement committees prioritize coil inventory depth given high neurovascular procedure volumes under DRG reimbursement clarity.
- Catheters:Diagnostic and guiding catheters provide vascular access for embolic delivery.
- Microcatheters:Single-use microcatheters enable superselective vessel cannulation.
- Delivery Systems:Integrated injection platforms for liquid embolics.
- Balloon Catheters:Temporary flow occlusion devices for controlled embolization.
Most installed capacity flows through embolic agents. Expansion is steepest in embolization coils.
Therapy Area:
Procedure volume and reimbursement rates vary sharply across therapeutic applications, with oncology and neurovascular commanding premium pricing compared to peripheral interventions.
- Liver Tumors:Transarterial chemoembolization and radioembolization for hepatocellular carcinoma represent the highest-value application segment. Demand clusters in Germany and the United States, where specialized interventional radiology departments and favorable reimbursement sustain complex procedure economics.
- Neurovascular Disorders:Cerebral aneurysm coiling and arteriovenous malformation embolization require the most advanced imaging integration and operator training. Academic medical centers in the United States anchor demand, with FDA breakthrough device designations accelerating adoption of novel liquid embolics.
- Cardiovascular Diseases:Coronary and structural heart embolization procedures.
- Uterine Fibroids:Uterine artery embolization for symptomatic fibroid management.
- Gastrointestinal Bleeding:Emergency embolization for hemorrhage control.
- Peripheral Vascular Diseases:Limb salvage and trauma embolization interventions.
Revenue concentration tilts toward liver tumors. Patient volume expansion runs fastest in uterine fibroids.
End User:
Purchasing sophistication and capital availability diverge between integrated hospital networks and independent outpatient facilities, reshaping vendor sales force deployment.
- Hospitals:Comprehensive interventional radiology departments with hybrid angiography suites and 24/7 emergency coverage. Demand in the United States concentrates in IDN-affiliated centers where centralized procurement extracts volume-based pricing on coils and microcatheters.
- Ambulatory Surgical Centers:Outpatient embolization for uterine fibroids and benign prostatic hyperplasia. United States reimbursement parity between hospital outpatient departments and ASCs is accelerating site migration for stable patients.
- Specialty Clinics:Focused interventional radiology practices without full hospital infrastructure.
- Diagnostic Centers:Imaging facilities with limited therapeutic capability.
Capital deployment favors hospitals. Patient migration is shifting fastest toward ambulatory surgical centers.
Delivery Mode:
Technology integration levels and procedure time requirements separate mature catheter-based workflows from emerging image-guided platforms.
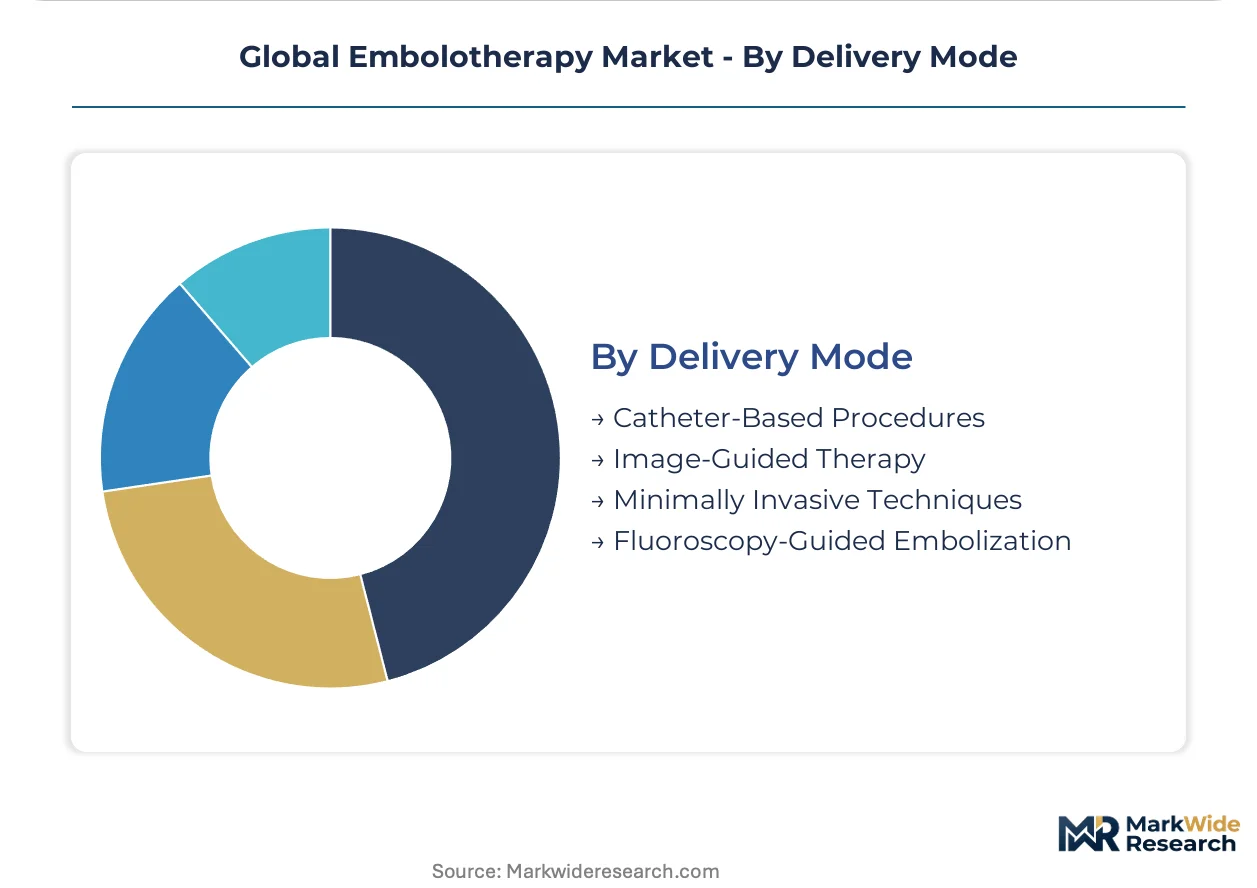
- Image-Guided Therapy:Cone-beam CT and 3D roadmap fusion systems reduce fluoroscopy burden and enable same-day discharge protocols. German angiography suites lead adoption, with specialized reimbursement for complex oncologic interventions supporting platform investment.
- Catheter-Based Procedures:Conventional fluoroscopy-guided embolization remains the workhorse delivery mode globally. Hospitals in the United States maintain the largest installed base, though procedure growth is decelerating relative to image-guided alternatives.
- Minimally Invasive Techniques:Percutaneous and ultrasound-guided access methods.
- Fluoroscopy-Guided Embolization:Traditional X-ray based navigation without advanced reconstruction.
Procedure volume runs through catheter-based workflows. Capability investment is concentrating fastest in image-guided therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between the FDA's breakthrough pathway and EMA's MDR recertification burden are redirecting product development investment toward jurisdictions with clearer commercialization timelines. Manufacturers now site clinical trials and early manufacturing capacity based on speed-to-reimbursement rather than market size alone.
United States
Academic medical centers in Boston and Houston anchor neurovascular procedure volume, with the FDA's breakthrough device designation compressing time-to-market for novel liquid embolics. The Centers for Medicare & Medicaid Services maintains reimbursement parity between hospital outpatient departments and ambulatory surgical centers for uterine fibroid embolization, accelerating site-of-care migration in Texas and Florida markets.
Germany
Specialized angiography suites in Munich and Heidelberg sustain the highest per-capita embolization procedure rates in Europe, driven by DRG reimbursement clarity for hepatocellular carcinoma interventions. The Federal Institute for Drugs and Medical Devices enforces stringent post-market surveillance for permanent implants, favoring established coil manufacturers with robust clinical dossiers over newer entrants.
China
Domestic catheter production in Suzhou and Shenzhen is displacing imported microcatheters in provincial hospitals, supported by NMPA streamlined approvals for Class II devices. The National Healthcare Security Administration's volume-based procurement pilots for embolic agents are compressing margins for multinational suppliers in Jiangsu and Zhejiang provinces.
India
Interventional radiology departments at Apollo and Fortis hospital networks in Mumbai and Bangalore are expanding embolization service lines for trauma and oncology applications. CDSCO's risk-based classification system accelerates registration timelines for drug-eluting beads, while PLI scheme incentives attract coil manufacturing investment to Gujarat's medical device parks.
Japan
PMDA's Sakigake designation pathway provides priority review for innovative embolic agents, with Tokyo and Osaka academic centers leading adoption of shape-memory polymer coils. METI's reimbursement price revision cycle for medical devices creates predictable pricing environments that support capital investment in hybrid angiography suites at Keio University and Osaka University hospitals.
Global Embolotherapy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated catheter-coil portfolios commanding premium positioning in neurovascular workflows while regional fabricators capture commoditized microcatheter categories. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with full imaging-to-implant stacks, interventional radiology pure-plays with therapy-specific depth, and Asian component suppliers feeding OEM private-label programs. Competitive moves center on unbundling capital equipment from consumable contracts to secure hybrid angiography suite placements, and backward integration into platinum-tungsten alloy sourcing to insulate coil margins from rare metal volatility.
Among diversified conglomerates, Medtronic and Boston Scientific Corporation anchor the premium tier with integrated delivery platforms, while Stryker Corporation occupies a position within the neurovascular specialization vector. Penumbra exemplifies the pure-play archetype, representing interventional radiology-focused vendors that extend addressable case mix through aspiration and mechanical thrombectomy adjacencies. These named entities serve as reference points for competitive positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Terumo Corporation |
| Stryker Corporation |
| Penumbra |
| Abbott Laboratories |
| Cook Medical |
| Merit Medical Systems |
| Others |
Supply & Pricing Matrix
Captive supply of platinum-tungsten alloys anchors coil manufacturers' cost positions while insulating them from rare metal spot volatility that would otherwise compress neurovascular device margins. This backward integration into raw material sourcing simultaneously secures production continuity for high-value embolization coils and supports premium pricing power against commodity-dependent competitors.
Pricing Analysis
Direct-to-hospital contracting eliminates distributor markups for integrated catheter-coil portfolios at academic medical centers in the United States. Three-tier pricing structure across premium, standard, and economy levels stratifies by coil complexity and imaging integration depth. Cost compression in standard-grade microcatheters intensifies as Chinese provincial hospitals adopt domestic alternatives. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings under CMS frameworks.
Supply Chain Analysis
Single-source vulnerability sits with South African platinum concentrate and Chinese tungsten processing for alloy feedstock. Manufacturing draws from Germany for precision coil winding, United States for liquid embolic formulation, and Japan for shape-memory polymer production. Tariff exposure on rare earth imports from concentrated geopolitical regions threatens margin stability. Distribution runs through GPO-aggregated hospital procurement committees and specialized interventional radiology distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embolotherapy market compounds steadily as interventional radiology departments expand embolization service lines across oncology and neurovascular applications. Recurring consumable demand for drug-eluting beads and embolization coils generates predictable revenue streams.
For Market Incumbents: Deploy MDR-compliant clinical dossier investment to defend European market access against recertification delays that favor newer entrants with purpose-built regulatory submissions. Consolidate catheter-coil portfolio bundling to resist hospital procurement committee unbundling pressure. Secure captive platinum-tungsten supply agreements to insulate neurovascular coil margins from raw material volatility.
For New Entrants and Emerging Players: Interventional radiology pure-plays in India represent the most penetrable channel partner type for localized manufacturing under PLI scheme incentives. Target CDSCO-fast-tracked drug-eluting bead registration to establish oncology interventional suite presence before multinational contract renegotiations. Pursue academic medical center co-development partnerships for shape-memory polymer coil validation.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 quality system complexity elongates certification timelines for liquid embolic formulations. Long-term viability favors vendors with integrated imaging-to-implant stacks and recurring consumable revenue density. Monitor FDA breakthrough device designation velocity as inflection indicator for novel embolic agent commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates commercialization timelines for novel liquid embolics in United States academic centers. |
| CE Marking Pathway Under MDR | Secures European market access for permanent implants facing heightened clinical evidence requirements. |
| Hospital System Partnership | Locks in hybrid angiography suite placements through integrated capital-consumable contracts. |
| Software Companion Development | Enables cone-beam CT fusion and 3D roadmap integration for reduced fluoroscopy workflows. |
| Reimbursement Strategy | Optimizes site-of-care economics for uterine fibroid embolization across ASC and HOPD settings. |
Research Methodology
Coverage spans United States, Germany, China, India, and Japan, with primary inputs from each regional cluster. Interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA filings, EMA MDR submissions, CMS Medicare data, and hospital procurement databases. Bottom-up procedure volume modeling triangulates against top-down market value estimates.
Segmentation granularity extends to embolic agent type, therapy area, end-user channel, and delivery mode across the projection horizon. CAGRs derive from procedure volume trajectories, ASP erosion curves, and site-of-care migration patterns. Forecast inputs incorporate DRG reimbursement evolution in Germany, NMPA volume-based procurement pilots in China, and ASC reimbursement parity dynamics in United States markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interventional radiologist training pipeline constraints and platinum-tungsten supply disruptions. Forecasts reflect assumptions about regulatory pathway efficiency and reimbursement stability without guaranteeing specific outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Global Stents Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Argentina Cardiovascular Devices Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Global Peripheral Stent Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Medical Devices Cuffs Market