
 Acute Surgical Mechanical Circulatory Support System Market | 2026-2036
Acute Surgical Mechanical Circulatory Support System Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Surgical Mechanical Circulatory Support System Market Analytics
The EU Medical Device Regulation is expanding compliance requirements for active implantable cardiovascular devices sold across European member states. Medtronic leverages its integrated manufacturing footprint to sustain supply continuity for intra-aortic balloon pump consoles. Abbott Laboratories anchors its position through continuous-flow ventricular assist device platforms designed for postcardiotomy recovery.
Acute surgical mechanical circulatory support systems are temporary or short-term blood pumping devices that supplement or replace native cardiac function during critical perioperative periods, typically employing centrifugal or pulsatile flow mechanisms with biocompatible surfaces to prevent thromboembolism. Their primary purpose is to maintain end-organ perfusion when the heart cannot generate adequate output following cardiac surgery, trauma, or acute decompensation. Ventricular assist devices dominate procedural volumes in cardiac surgery applications, while extracorporeal membrane oxygenation systems capture expanding utilization in emergency care settings where biventricular failure complicates resuscitation. Continuous flow technology leads installed base metrics, though hybrid systems integrating pulsatile elements are gaining traction among centers prioritizing physiologic perfusion patterns.
The FDA governs premarket approval pathways for these Class III devices in the United States, while the EMA coordinates notified body oversight under the EU MDR framework in Europe. Both agencies mandate clinical evidence standards that shape trial design, prolong development timelines, and filter market access to firms with sufficient capital reserves. Stakeholders must monitor evolving reimbursement thresholds for temporary mechanical circulatory support in major hospital payment systems.
Market Dynamics
Centrifugal flow technology is displacing pulsatile mechanisms in cardiac surgery units, compressing development cycles for device manufacturers while elevating biocompatibility requirements for blood-contacting surfaces.
Growth Catalysts
- Postcardiotomy Recovery Protocols:Cardiac surgery programs in tertiary hospitals are expanding ventricular assist device deployment for temporary circulatory support following complex procedures.
- FDA PMA Streamlining:The FDA's premarket notification pathway for Class III cardiovascular devices is accelerating commercial entry timelines for acute surgical mechanical circulatory support systems.
- ECMO Emergency Expansion:Extracorporeal membrane oxygenation systems are capturing utilization in resuscitation settings where biventricular failure complicates patient stabilization.
Market Restraints
- Silicone Membrane Supply Concentration:Biocompatible membrane production concentrates among specialty chemical suppliers in Germany and Japan, creating input vulnerability for oxygenator manufacturers.
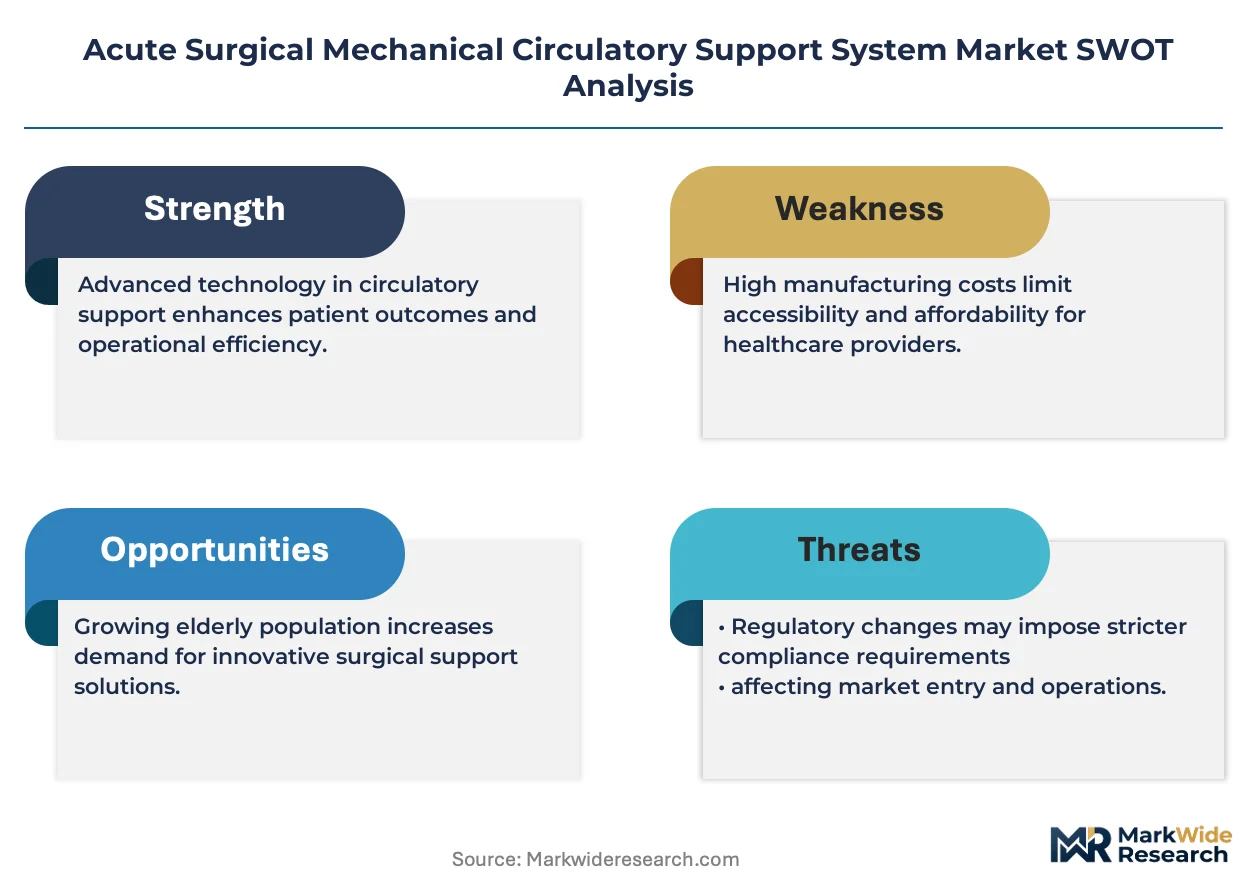
- EU MDR Compliance Burden:The EU Medical Device Regulation is extending clinical evidence requirements and notified body review timelines for active implantable cardiovascular devices.
- Thromboembolism Risk Limitations:Current anticoagulant surface coatings impose bleeding complications that restrict prolonged device deployment beyond seventy-two hours.
Strategic Opportunities
- Hybrid Flow Convergence:Continuous flow technology is converging with pulsatile elements to create systems that replicate physiologic perfusion patterns for end-organ protection.
- Academic Medical Center Clusters:High-volume mechanical circulatory support programs in Boston, Houston, and Cleveland represent concentrated demand nodes for device manufacturers.
- Reimbursement Threshold Expansion:Hospital payment systems are developing dedicated billing codes for temporary mechanical circulatory support procedures.
Industry Challenges
- Perfusionist Workforce Scarcity:Specialized training programs for extracorporeal circuit management are failing to match expansion rates of cardiac surgery volumes.
- Legacy System Integration Friction:Newer centrifugal pump platforms require interface adaptation with existing operating room monitoring architectures.
- Anticoagulation Protocol Standardization:Institution-specific heparin management guidelines complicate multi-center clinical trial design for device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Surgical Mechanical Circulatory Support System Market |
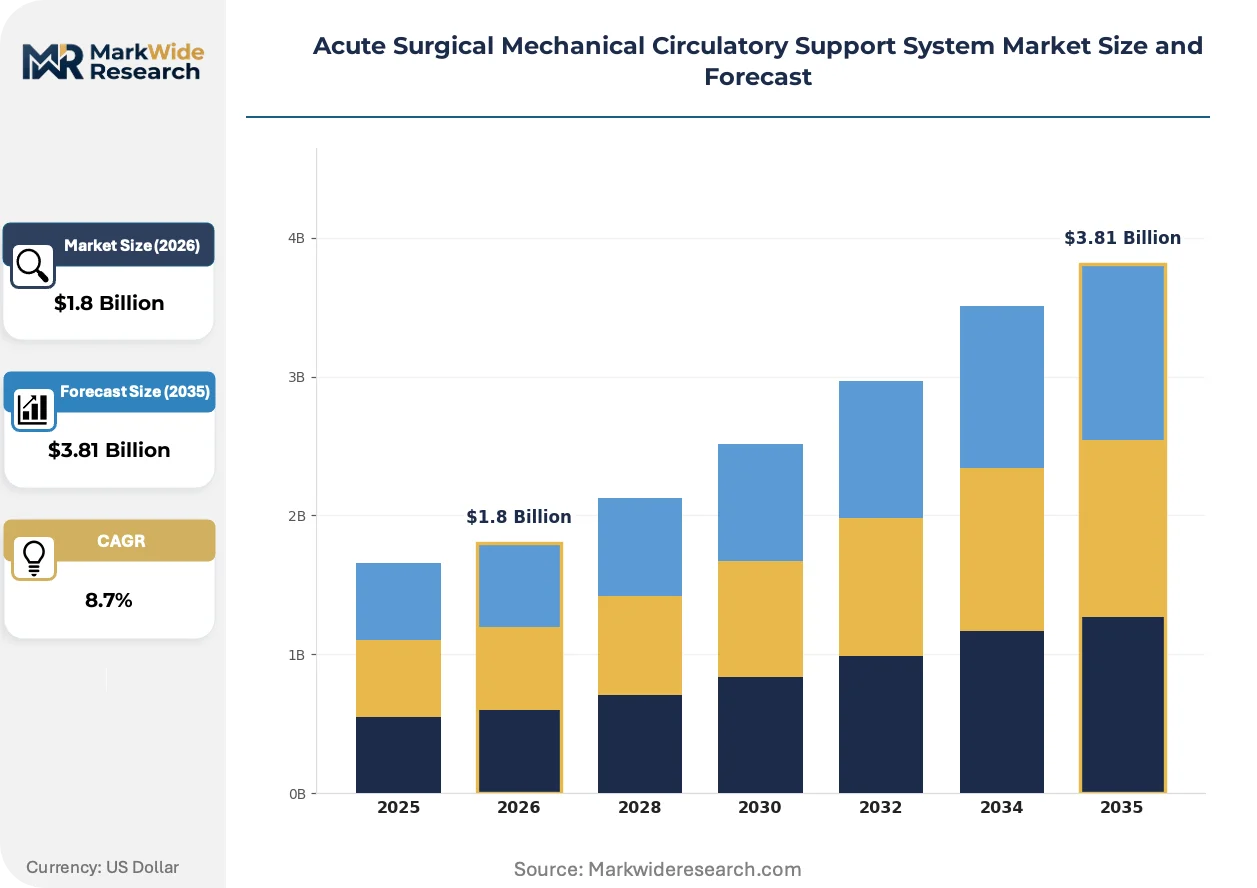
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intra-aortic Balloon Pump, Ventricular Assist Device, Total Artificial Heart, Extracorporeal Membrane Oxygenation End User: Hospitals, Clinics, Surgical Centers, Specialty Care Facilities Application: Cardiac Surgery, Trauma Surgery, Heart Transplant, Emergency Care Technology: Pulsatile Flow, Continuous Flow, Hybrid Systems, Novel Biomaterials |
| Companies Covered | Medtronic, Abbott Laboratories, Getinge Group, LivaNova, Eurosets, Nipro Corporation, Terumo Corporation, Abiomed, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Surgical Mechanical Circulatory Support System Market Evolving Landscape
Device architecture is pivoting toward modularity and miniaturization, enabling rapid deployment in emergency settings while reducing priming volumes and hemodilution risk.
Magnetic levitation bearing systems are eliminating mechanical wear points in centrifugal blood pumps, extending device durability for prolonged postcardiotomy support. Academic medical centers in Cleveland and Houston are piloting these platforms for biventricular failure cases. This bearing technology is converging with integrated flow sensors to enable real-time hemodynamic optimization without invasive monitoring.
The EU MDR's expanded post-market surveillance requirements are mandating systematic device registries and annual safety reporting for active implantable cardiovascular devices. Manufacturers must now maintain clinical evidence portfolios spanning the full product lifecycle. European notified bodies are prioritizing review resources toward mechanical circulatory support submissions with established real-world performance data.
Hospital procurement committees are consolidating vendor relationships to secure service bundling and training commitments across multiple device platforms. Academic medical centers are displacing transactional equipment purchases with multi-year partnership agreements that embed technical support and staff education. This consolidation pattern is most visible in United States cardiac surgery programs where volume thresholds justify dedicated clinical specialist assignments.
Acute Surgical Mechanical Circulatory Support System Market Segmentation
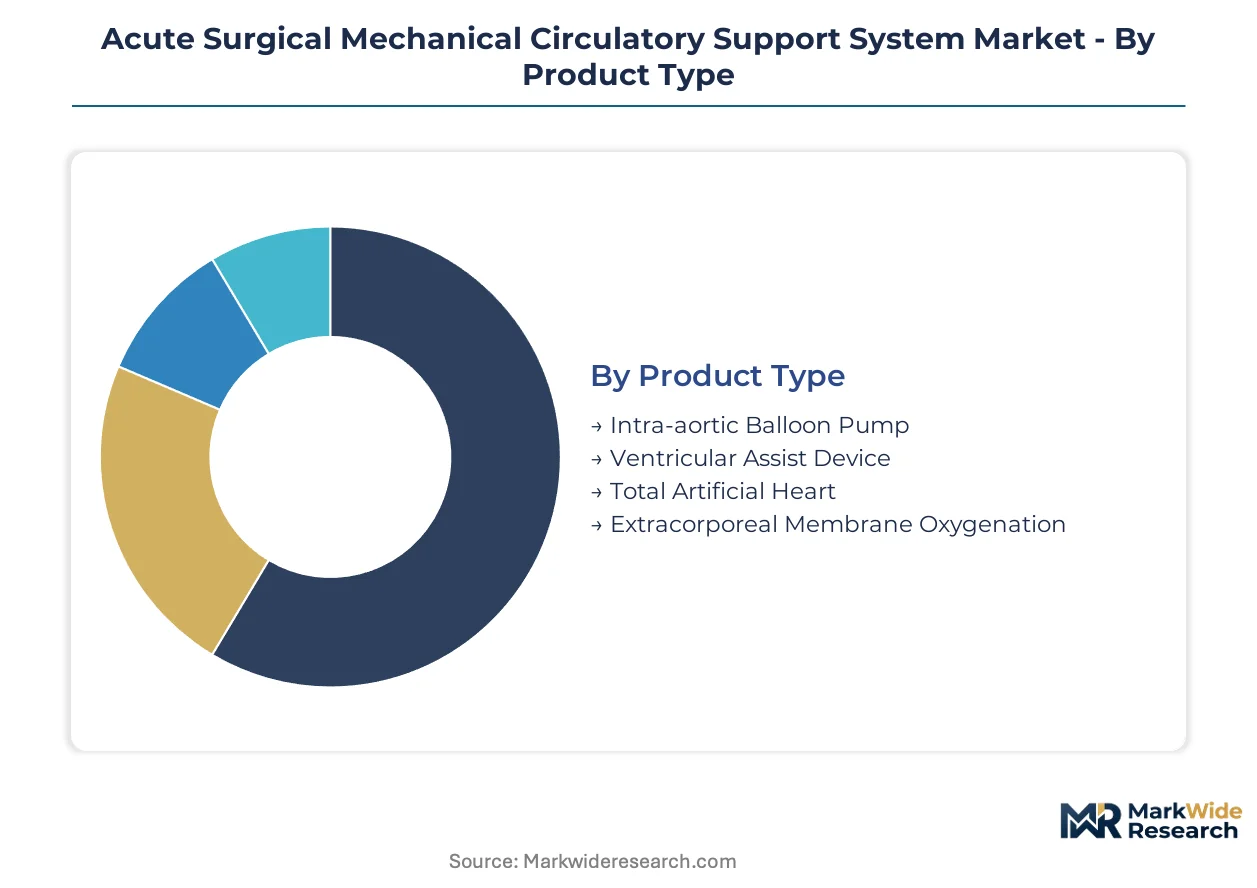
Segmentation in acute surgical mechanical circulatory support reveals how procurement priorities diverge across clinical settings. Technology choices, patient acuity thresholds, and reimbursement frameworks reshape demand patterns for each product category.
Product Type:
Hospital purchasing committees weight capital intensity against versatility and outcome data when selecting among blood pumping platforms.
- Intra-aortic Balloon Pump:Counterpulsation technology augments diastolic coronary perfusion through balloon inflation synchronized with cardiac cycle. Demand concentrates in United States community hospitals where postcardiotomy support protocols remain standardized and perfusionist staffing is limited.
- Ventricular Assist Device:Continuous-flow rotary pumps provide univentricular or biventricular support through percutaneous or surgical cannulation. Academic medical centers in Boston and Cleveland deploy these systems for complex cardiac surgery cases requiring prolonged circulatory assistance.
- Total Artificial Heart:Biventricular replacement systems bridge patients to transplantation when native cardiac recovery is impossible. Specialty cardiac surgery programs in Houston maintain these devices for select transplant-eligible candidates.
- Extracorporeal Membrane Oxygenation:Integrated pump-oxygenator circuits deliver cardiopulmonary support for refractory cardiogenic shock. Emergency departments and surgical ICUs are expanding ECMO deployment for resuscitation scenarios.
Ventricular assist devices lead volumes today; extracorporeal membrane oxygenation is gaining share fastest.
End User:
Facility scale and case volume determine which institutions can sustain dedicated mechanical circulatory support programs.
- Hospitals:Tertiary cardiac surgery centers with ECMO capabilities and 24-hour perfusionist coverage. United States academic medical centers anchor device procurement through high-complexity case volumes.
- Clinics:Outpatient settings with limited acute intervention capacity; minimal penetration for surgical mechanical circulatory support.
- Surgical Centers:Ambulatory facilities performing low-acuity cardiac procedures; intra-aortic balloon pumps appear in select high-volume coronary intervention sites.
- Specialty Care Facilities:Dedicated cardiovascular institutes with hybrid operating rooms and advanced imaging integration. Cleveland Clinic and Texas Heart Institute exemplify this concentration model.
Hospitals dominate installed base; specialty care facilities show steepest expansion trajectory.
Application:
Clinical indication shapes device selection through required support duration and anticipated weaning success.
- Cardiac Surgery:Postcardiotomy cardiogenic shock drives ventricular assist device and intra-aortic balloon pump utilization. Complex valve reconstruction and coronary revascularization cases generate concentrated demand in high-volume United States programs.
- Trauma Surgery:Blunt cardiac injury and hemorrhagic shock with secondary cardiac failure require rapid ECMO deployment. Level I trauma centers in Houston and Baltimore maintain emergency circuit priming protocols.
- Heart Transplant:Bridge-to-transplantation support demands durable biventricular assistance or total artificial heart implantation. United Network for Organ Sharing allocation policies influence device selection timing.
- Emergency Care:Refractory ventricular fibrillation and pulseless electrical activity resuscitation incorporate extracorporeal cardiopulmonary resuscitation protocols. Mobile ECMO teams in Boston and Minneapolis extend hospital capabilities to pre-hospital settings.
Cardiac surgery anchors procedural volumes; emergency care applications are climbing the fastest.
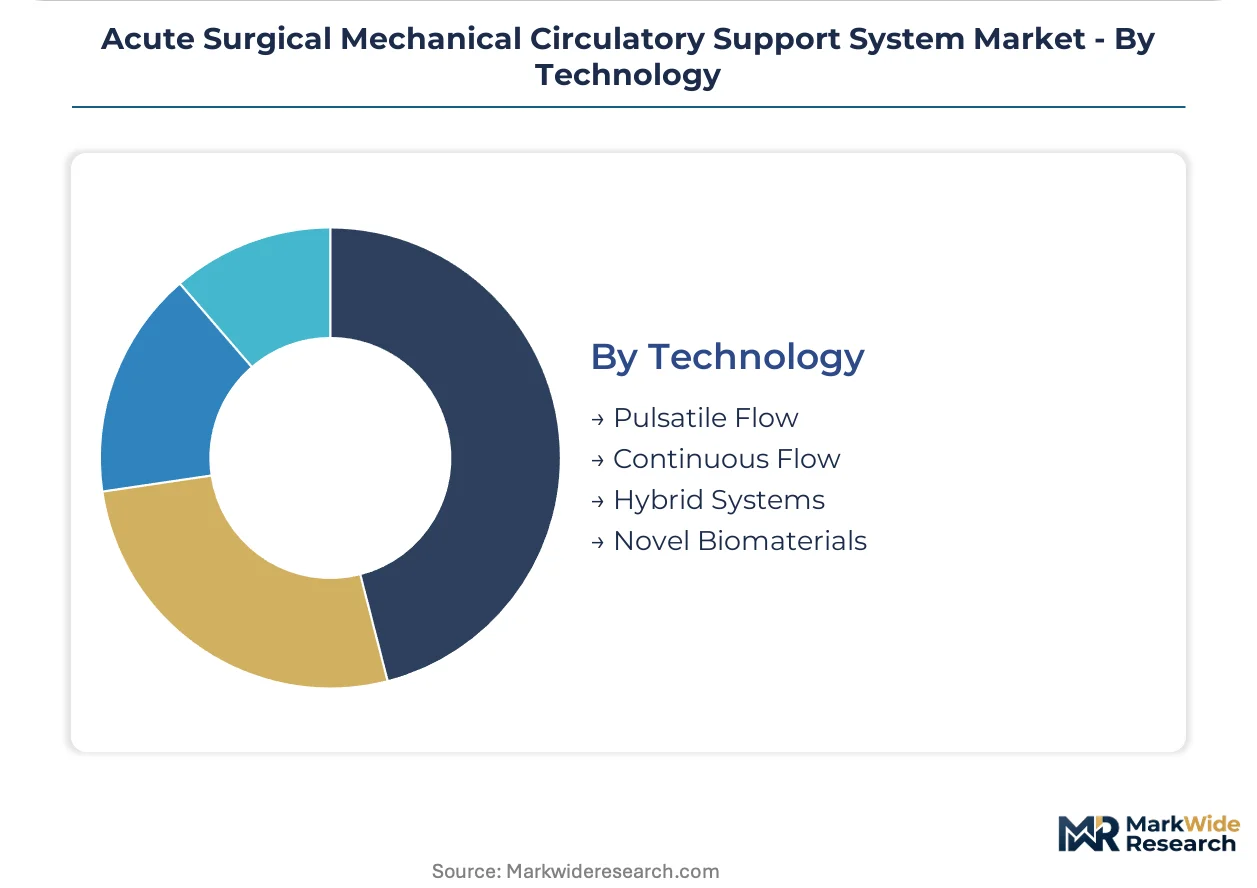
Technology:
Flow mechanism selection balances hemocompatibility against physiologic fidelity and system complexity.
- Pulsatile Flow:Volume-displacement pumps replicate native cardiac output patterns through positive displacement chambers. Niche utilization persists in centers prioritizing end-organ pulsatile perfusion for prolonged support.
- Continuous Flow:Centrifugal and axial rotary pumps dominate contemporary device architectures through simplicity and durability. Magnetic levitation bearings in newer platforms eliminate mechanical wear points.
- Hybrid Systems:Integrated pulsatile elements within continuous-flow circuits attempt physiologic perfusion without complexity penalties. Early adoption concentrates in Cleveland and Houston academic programs.
- Novel Biomaterials:Advanced surface coatings and textured blood-contacting materials reduce thromboembolism without systemic anticoagulation. FDA breakthrough device designation pathways accelerate evaluation of endothelialized surfaces.
Continuous flow technology commands installed base; hybrid systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechanical circulatory support systems first achieved clinical scale in United States academic medical centers during the 1960s, with subsequent diffusion to European and Asian cardiac surgery programs through technology transfer agreements and training fellowships.
United States
FDA premarket approval pathways for Class III cardiovascular devices establish the regulatory benchmark that shapes trial design timelines worldwide. Centers in Boston, Houston, and Cleveland operate high-volume mechanical circulatory support programs that generate concentrated procurement demand. Postcardiotomy recovery protocols at these institutions drive ventricular assist device utilization for complex cardiac surgery cases.
Germany
Specialty chemical suppliers in Germany concentrate biocompatible silicone membrane production for oxygenator manufacturers serving European cardiac surgery units. The EU Medical Device Regulation extends clinical evidence requirements through notified body oversight that filters market access to well-capitalized firms. Industrial clusters in Baden-Württemberg and Bavaria host precision manufacturing operations for centrifugal pump components.
Japan
PMDA regulatory frameworks for active implantable devices mandate extensive clinical evaluation periods that extend commercialization timelines for cardiovascular technology. Domestic cardiac surgery programs in Tokyo and Osaka deploy extracorporeal membrane oxygenation systems for emergency resuscitation scenarios. Japanese perfusionist training programs maintain rigorous certification standards that influence regional device selection criteria.
China
NMPA medical device registration pathways are streamlining review processes for Class III cardiovascular implants through priority review channels. Tertiary hospitals in Beijing and Shanghai are scaling extracorporeal membrane oxygenation capabilities for cardiogenic shock management. Domestic manufacturers are developing centrifugal pump platforms to reduce import dependence for acute surgical mechanical circulatory support systems.
United Kingdom
NHS reimbursement frameworks for temporary mechanical circulatory support procedures determine hospital procurement thresholds across English cardiac surgery networks. The Medicines and Healthcare products Regulatory Agency coordinates post-market surveillance requirements that align with EU MDR standards. Academic medical centers in London and Manchester maintain bridge-to-transplantation programs utilizing total artificial heart systems for select candidates.
Acute Surgical Mechanical Circulatory Support System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and clinical evidence portfolios in the acute surgical mechanical circulatory support system market. The vendor base stratifies between diversified cardiovascular conglomerates with integrated manufacturing footprints and specialized device manufacturers focused on single-modality platforms. Three archetypes dominate: diversified medtech conglomerates with full cardiac surgery portfolios, specialized mechanical circulatory support pure-plays, and regional Asian manufacturers with cost-optimized offerings. Competitive dynamics center on M&A activity to acquire magnetic levitation bearing technologies and strategic partnerships with academic medical centers to secure high-volume reference sites.
Among diversified medtech conglomerates, Medtronic and Abbott Laboratories occupy positions representing integrated cardiovascular device portfolios. Medtronic exemplifies the manufacturing-scale archetype through its supply continuity infrastructure for intra-aortic balloon pump consoles. Abbott Laboratories sits within the continuous-flow technology tier, anchoring positioning through ventricular assist device platforms designed for postcardiotomy recovery applications. These two entities represent distinct strategic postures within the premium-margin segment.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Getinge Group |
| LivaNova |
| Eurosets |
| Nipro Corporation |
| Terumo Corporation |
| Abiomed |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists in perfusion equipment manufacturing have consolidated procurement leverage across German and Japanese silicone membrane suppliers, tightening pricing discipline for oxygenator producers while compressing margin buffers for independent pump console assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the acute surgical mechanical circulatory support market. FDA breakthrough device designation and magnetic levitation bearing technology command premium positioning, while volume scale and after-sales service bundling differentiate mid-tier offerings. Pricing pressure stems from hospital procurement committee consolidation favoring multi-year partnership agreements over transactional equipment purchases. Community hospitals exhibit highest price sensitivity due to limited perfusionist staffing and standardized postcardiotomy protocols, whereas academic medical centers in Boston and Cleveland prioritize clinical evidence portfolios over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty chemical suppliers controlling biocompatible silicone membrane production for ECMO oxygenators. Centrifugal pump magnetic levitation bearings draw from precision manufacturing clusters in Baden-Württemberg and Bavaria, while cannula assemblies rest on Taiwanese medical-grade polymer extrusion capabilities. Tariff exposure on Chinese-sourced electronic pump controllers creates input cost volatility for console manufacturers. Distribution runs through GPO contracts and direct hospital system partnerships, with academic medical center clusters anchoring volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in acute surgical mechanical circulatory support hinges on magnetic levitation bearing cost-down curves and hybrid flow technology premium-tier adoption displacing commodity pulsatile systems.
For Market Incumbents: Acquire magnetic levitation bearing patent portfolios to lock up centrifugal pump durability advantages before specialty manufacturers commercialize competing platforms. Deepen backward integration into biocompatible surface coating chemistry to offset silicone membrane supply concentration vulnerability. Hospital procurement committee consolidation demands embedded clinical specialist teams defending installed base positions against emerging Asian cost-optimized entrants. For New Entrants and Emerging Players: The price-point gap between FDA PMA-approved premium ventricular assist devices and unapproved economy-tier intra-aortic balloon pumps creates white-space opportunity for mid-tier continuous-flow platforms with CE marking pathway. Target United States community hospitals with limited perfusionist coverage through simplified console interfaces and remote technical support bundling. Emergency department ECMO deployment represents the most penetrable application segment given resuscitation protocol standardization gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among regional Asian manufacturers developing domestic centrifugal pump platforms to reduce import dependence. Long-term viability across the projection horizon rests on regulatory approval runway length and real-world evidence generation capacity. Watch FDA breakthrough device designation velocity as the inflection signal distinguishing premium-multiple platforms from commodity-margin competitors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for novel biomaterial surface coatings reducing thromboembolism risk. |
| CE Marking Pathway Investment | Opens EU MDR-compliant market access for hybrid flow convergence platforms targeting physiologic perfusion. |
| Academic Medical Center Partnership | Secures high-volume reference sites in Boston, Houston, and Cleveland generating clinical evidence portfolios. |
| Magnetic Levitation Bearing Acquisition | Eliminates mechanical wear points extending device durability for prolonged postcardiotomy support applications. |
| Reimbursement Strategy Development | Captures dedicated billing codes for temporary mechanical circulatory support procedures in hospital payment systems. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down centrifugal pump manufacturing tracking forms the analytical core of this study. Primary interviews with perfusionist program directors, cardiovascular surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies combined with secondary validation from FDA 510(k) and PMA filings, EMA medical device registration databases, hospital procurement records, and EU MDR technical documentation standards. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of ventricular assist device and ECMO procedural volumes across cardiac surgery programs established baseline growth patterns. The forecast framework segments by product type, end user facility scale, application indication, and flow mechanism technology, with CAGRs derived from installed base replacement cycles and emergency care protocol expansion rates. Magnetic levitation bearing adoption curves and EU MDR compliance cost burdens fed scenario-weighted projections.
Caveats apply where FDA PMA review timeline extensions, EU MDR notified body capacity constraints, or silicone membrane supply disruptions could materially shift the outlook. Forecasts reflect assumptions about perfusionist workforce expansion and hospital reimbursement threshold evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market
Cardiovascular Devices
Global Heart Pump Devices Market
Cardiovascular Devices
Peripherally Inserted Central Catheters Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
North America Vascular Stents Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Middle East and Africa Heart Valve Repair and Replacement Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market