
 Japan Mobile Battery Market | 2026-2036
Japan Mobile Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Mobile Battery Market Insights
Aftermarket refurbishment revenue is rewriting profit expectations for Japanese suppliers. Panasonic Holdings Corporation leverages its vertical cell production network to capture service margins. Murata Manufacturing Co., Ltd. specializes in compact lithium-polymer designs for wearables. Sony Corporation anchors premium smartphone contracts through proprietary electrode formulations.
Japan mobile batteries electrochemically store and discharge energy through ion transfer between anode and cathode materials, typically achieving 3.6–4.4V nominal output with energy densities exceeding 250 Wh/kg in advanced lithium-ion formats. These cells power portable electronics, electric mobility devices, and industrial IoT hardware requiring reliable off-grid operation. Lithium-ion chemistry dominates installed base owing to mature supply chains and proven cycle life. Solid-state prototypes attract R&D capital as manufacturers seek higher thermal stability. Consumer electronics applications retain volume leadership, though automotive-grade cells command superior unit economics.
METI enforces battery safety certification under DENAN Law, while JIS standards govern cell testing protocols and recycling quotas. PMDA oversight extends to medical-grade portable power packs, creating segmented compliance pathways. Stakeholders must track solid-state manufacturing yield breakthroughs and recycling infrastructure buildout to align capacity decisions with evolving regulatory thresholds.
Market Dynamics
Solid-state cell prototyping is compressing conventional lithium-ion investment timelines across Japan's electronics corridor. METI pilot programs and OEM consolidation around Kanto are forcing suppliers to choose between legacy capacity refurbishment or clean-sheet manufacturing architectures.
Growth Catalysts
- DENAN Law safety certification:Mandatory battery testing protocols under METI enforcement are standardizing quality thresholds. Tier-1 smartphone OEMs now require certified cells for domestic flagship launches.
- Wearables miniaturization:Compact lithium-polymer demand from health-monitoring devices in Osaka's medical device cluster is pulling ultra-thin cell capacity expansion.
- Kanto supplier clustering:Proximity between cathode material refiners and pack assemblers in Saitama and Chiba prefectures is compressing logistics costs and lot-to-lot variation.
Market Restraints
- Cobalt sulfate price volatility:DRC concentrate dependence exposes Japanese cathode producers to LME price swings and maritime freight premiums.
- Single-source solid-state electrolyte:Sulfide-based ceramic precursor supply concentrates with three domestic chemical houses, creating qualification bottlenecks.
- JIS C 8712 cycle-life thresholds:Testing protocol stringency for consumer cells extends certification timelines by 4-6 months versus IEC baseline.
Strategic Opportunities
- Kyushu semiconductor corridor:Underpenetrated pack assembly presence near Kumamoto's TSMC-adjacent fabs creates captive demand for high-reliability cells.
- Medical-grade portable power:PMDA Class II certification pathways for implantable device batteries command 3-4x unit economics versus consumer segments.
- Solid-state and silicon-anode convergence:Hybrid architectures combining ceramic electrolytes with nanowire anodes are opening energy density tiers above 400 Wh/kg.
Industry Challenges
- Thin-film deposition technicians:Vacuum coating expertise for solid-state layer stacking remains concentrated with legacy optical disc and semiconductor equipment veterans.
- Legacy cylindrical cell retooling:Prismatic and pouch format migration requires $40-60 million per line for electrode slitting and stacking automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Mobile Battery Market |
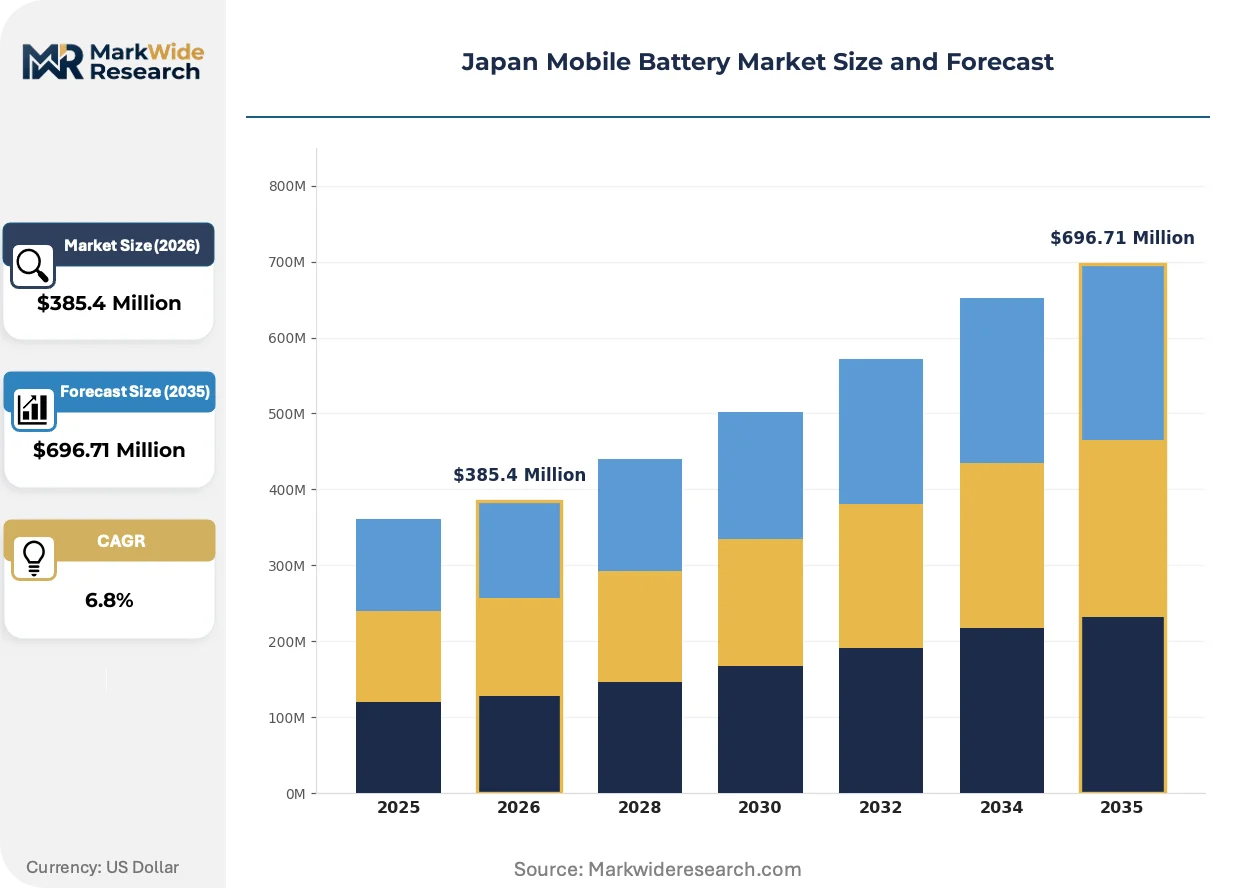
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Cadmium, Lead-acid, Solid-state End User: Smartphones, Tablets, Laptops, Wearable Devices Service Type: Charging Stations, Replacement Services, Recycling Services, Maintenance Services Application: Consumer Electronics, Automotive, Industrial, IoT Devices |
| Companies Covered | Panasonic Holdings Corporation, Sony Corporation, Murata Manufacturing Co., Ltd., GS Yuasa Corporation, Toshiba Corporation, Maxell Holdings, Ltd., TDK Corporation, Hitachi Ltd., FDK Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Mobile Battery Market Trends and Innovations
Electrode architecture and pack integration are converging around thermal management and form-factor flexibility. Japanese suppliers are racing to bridge the gap between proven lithium-ion reliability and next-generation solid-state performance.
Sulfide solid-state electrolyte technology is hybridizing conventional liquid electrolyte manufacturing with ceramic sintering processes. Tier-1 automotive suppliers in Nagoya are piloting hybrid lines at 10-20% scale. The technology is hybridizing equipment vendor ecosystems, forcing toolmakers to combine wet-coating and dry-pressing competencies.
METI's battery recycling mandates under the Act on Promotion of Resource Circulation for Batteries are mandating 50% material recovery rates by 2030. Cathode black mass refining capacity in Kitakyushu is expanding to handle end-of-life EV and consumer electronics streams. Medical-grade portable power packs face segmented PMDA oversight extending compliance timelines versus consumer segments.
Aftermarket refurbishment is unbundling from OEM warranty programs. Independent service providers in Tokyo's Akihabara district are capturing cell replacement demand outside authorized channels. Smartphone users in Kansai are extending device lifecycles through third-party battery swaps, compressing new cell attach rates for mid-tier handset launches.
Japan Mobile Battery Market Segmentation
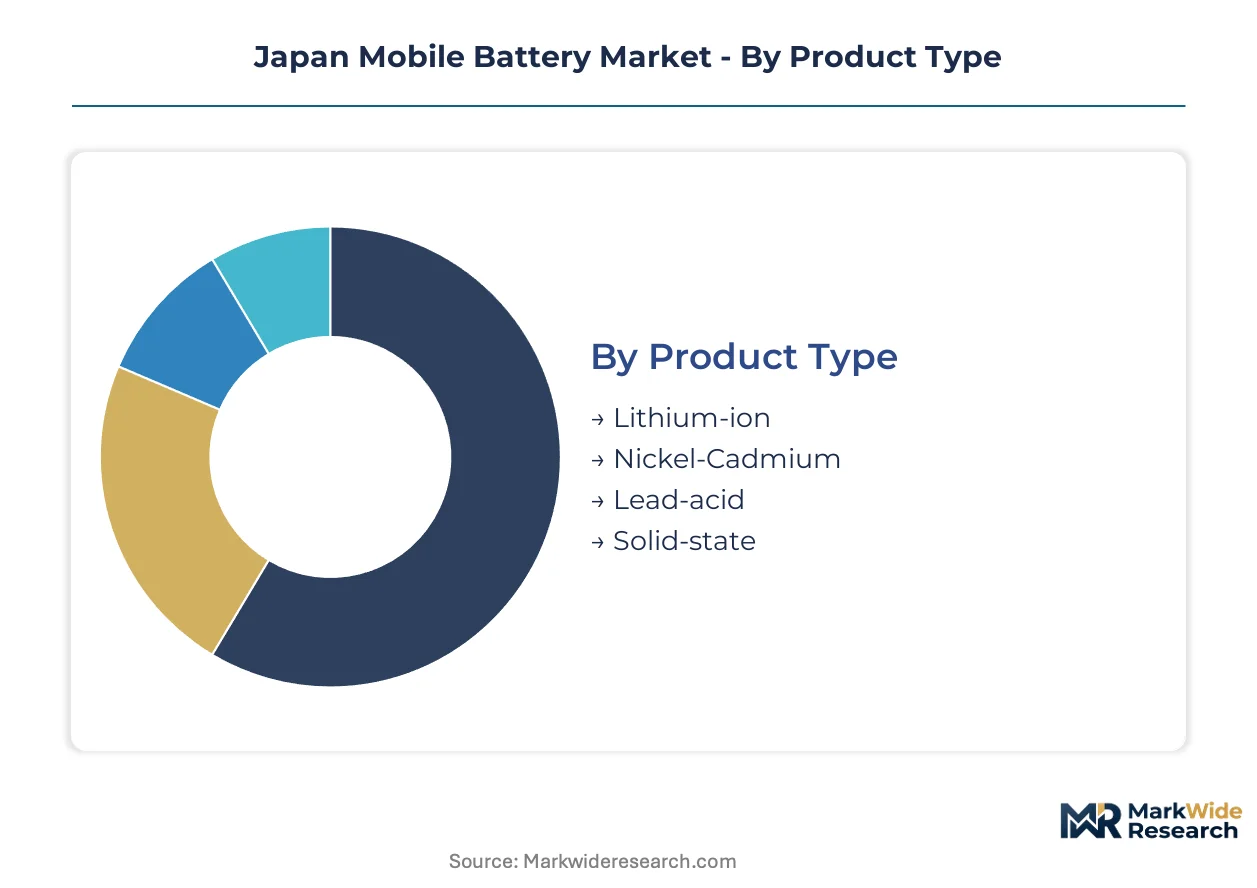
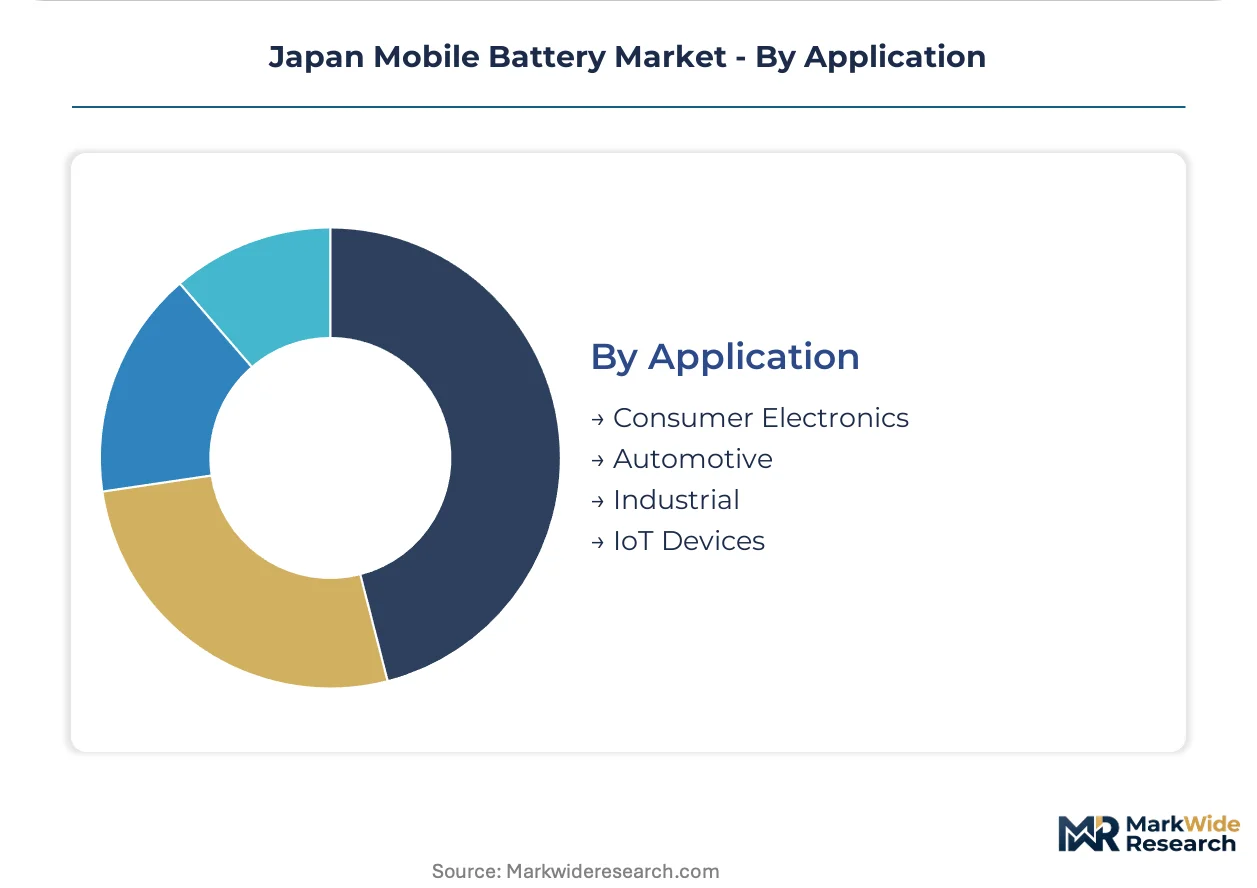
Segmentation in Japan's mobile battery market reveals how replacement cycles, certification requirements, and form-factor demands create divergent profit pools. Suppliers must align capacity investments with the velocity profile of each segment rather than treating mobile power as a uniform commodity.
Product Type:
Lithium-ion cells turn over fastest in consumer channels, while solid-state prototypes operate on extended qualification timelines that compress near-term revenue recognition.
- Lithium-ion:Dominant chemistry employs layered oxide cathodes and graphite anodes achieving 250-300 Wh/kg energy density. Smartphone OEMs in Tokyo and Osaka specify these cells for flagship launches under DENAN Law certification, with cathode refiners in Saitama compressing lot-to-lot variation through proximity to pack assemblers.
- Solid-state:Sulfide ceramic electrolytes paired with silicon-anode architectures target 400+ Wh/kg thresholds. METI pilot programs are accelerating automotive qualification timelines, though sulfide precursor supply concentrates with three domestic chemical houses creating bottlenecks.
- Nickel-Cadmium:Legacy cylindrical format retains niche industrial demand from legacy telecom backup systems in Hokkaido's remote infrastructure.
- Lead-acid:Absorbed glass mat variants serve price-sensitive mobility scooter segments outside major metropolitan clusters.
Lithium-ion dominates installed base. Solid-state is where expansion concentrates.
End User:
Cost tier stratification separates premium device contracts from refurbishment-driven aftermarket channels.
- Smartphones:Prismatic and pouch formats command highest volume with OEMs specifying 500+ cycle life under JIS C 8712 protocols. Independent service providers in Akihabara capture replacement demand outside authorized channels, compressing new cell attach rates for mid-tier launches.
- Wearable Devices:Ultra-thin lithium-polymer cells below 2mm thickness serve health-monitoring devices from Osaka's medical device cluster, with compact designs pulling dedicated capacity expansion from Murata Manufacturing.
- Tablets:Larger form-factor cells face demand pressure from extended replacement cycles in Kansai educational procurement.
- Laptops:High-capacity 18650 and 21700 cylindrical configurations retain steady enterprise refresh demand.
Smartphone volume anchors supplier revenue. Wearable Devices is climbing the fastest.
Service Type:
Margin structure inverts between capital-intensive charging infrastructure and labor-light recycling streams.
- Replacement Services:Aftermarket refurbishment revenue is rewriting profit expectations as third-party battery swaps extend device lifecycles. Panasonic Holdings leverages vertical cell production networks to capture service margins denied to pure distributors.
- Recycling Services:METI mandates under the Act on Promotion of Resource Circulation for Batteries require 50% material recovery by 2030, with cathode black mass refining capacity expanding in Kitakyushu to handle end-of-life streams.
- Charging Stations:Public infrastructure deployment concentrates around Tokyo and Osaka transit hubs with utility partnerships.
- Maintenance Services:Enterprise fleet management contracts for industrial IoT hardware create recurring revenue pools.
Replacement Services commands premium margin. Recycling Services is gaining share fastest through regulatory compulsion.
Application:
Supply concentration in Kanto's electronics corridor shapes procurement patterns across end-use verticals.
- Consumer Electronics:Volume leadership retains proven lithium-ion reliability with OEM consolidation around cathode material refiners and pack assemblers in Chiba prefecture compressing logistics costs.
- Automotive:Solid-state pilot programs in Nagoya are forcing suppliers to choose between legacy capacity refurbishment or clean-sheet manufacturing architectures for next-generation cells.
- Industrial:Ruggedized pack designs for construction and logistics hardware face qualification delays from JIS testing protocol stringency.
- IoT Devices:Low-power wide-area network sensors in Kyushu's semiconductor corridor create captive demand for high-reliability cells near Kumamoto's TSMC-adjacent fabs.
Consumer Electronics dominates installed base. Automotive is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Japan's regional battery markets. Kanto buyers absorb premium cells for flagship devices, while Kansai procurement favors refurbishment channels. Kyushu demand concentrates on high-reliability specifications for semiconductor-adjacent applications.
Kanto/Tokyo
Smartphone OEMs in Tokyo and Saitama specify DENAN Law-certified cells for domestic flagship launches. METI enforces battery safety protocols that standardize quality thresholds across the electronics corridor. Cathode material refiners cluster in Chiba prefecture, compressing logistics costs and lot-to-lot variation for pack assemblers.
Kansai/Osaka
Health-monitoring wearables from Osaka's medical device cluster pull ultra-thin lithium-polymer capacity expansion. Third-party battery swaps in Akihabara extend device lifecycles, compressing new cell attach rates for mid-tier handset launches. Independent service providers capture replacement demand outside authorized channels.
Chubu/Nagoya
Tier-1 automotive suppliers pilot hybrid solid-state lines at 10-20% scale, forcing suppliers to choose between legacy capacity refurbishment or clean-sheet manufacturing architectures. METI pilot programs accelerate automotive qualification timelines. Sulfide ceramic electrolyte development concentrates with domestic chemical houses.
Kyushu
Underpenetrated pack assembly presence near Kumamoto's TSMC-adjacent fabs creates captive demand for high-reliability cells. Low-power wide-area network sensors require industrial-grade specifications. Semiconductor corridor proximity pulls specialized cell procurement away from standard consumer channels.
Hokkaido
Legacy cylindrical nickel-cadmium formats retain niche industrial demand from remote telecom backup systems. Price-sensitive procurement favors established chemistries over solid-state prototypes. Infrastructure maintenance cycles extend replacement timelines versus metropolitan markets.
Japan Mobile Battery Market Competitive Landscape
Capability concentration sits with integrated cell producers; scale advantage sits with diversified electronics conglomerates. The market structures around three tiers: vertical manufacturers controlling electrode-to-pack production, component specialists focusing on compact form factors, and diversified industrials leveraging cross-divisional R&D. Consolidation pressures favor backward integration into cathode materials and strategic partnerships with sulfide electrolyte suppliers.
Among Japan-based producers, Panasonic Holdings Corporation, Sony Corporation, and Murata Manufacturing Co., Ltd. occupy distinct competitive positions. Panasonic exemplifies the vertically integrated archetype with captive cell production networks. Sony represents premium-tier positioning through proprietary electrode formulations. Murata sits within the compact-specialist tier, serving wearables miniaturization demand from Osaka's medical device cluster.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Sony Corporation |
| Murata Manufacturing Co., Ltd. |
| GS Yuasa Corporation |
| Toshiba Corporation |
| Maxell Holdings, Ltd. |
| TDK Corporation |
| Hitachi Ltd. |
| FDK Corporation |
| Others |
Pricing and Supply Chain Analysis
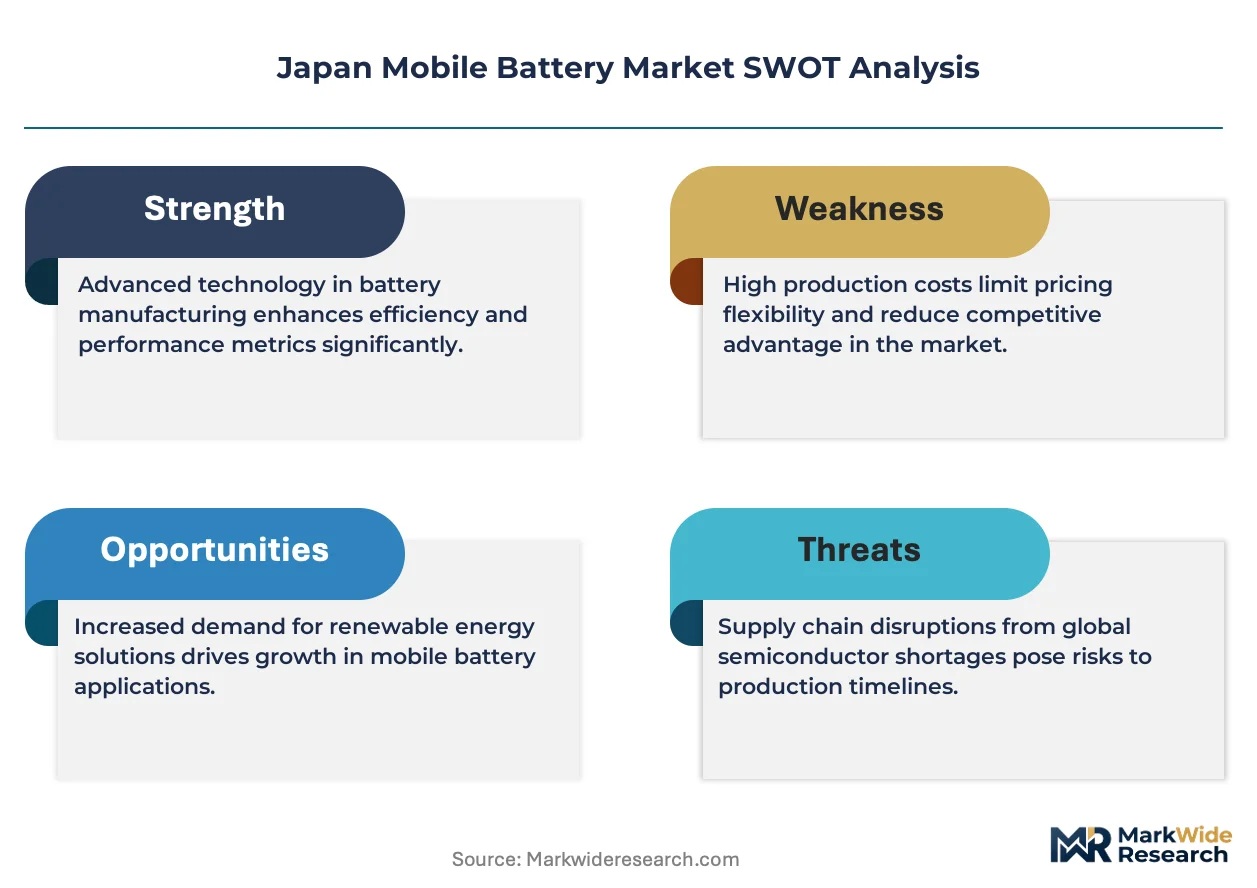
Cobalt sulfate price volatility from DRC concentrate dependence determines both tier spreads and supply chain shape. Japanese cathode producers face LME price swings and maritime freight premiums that compress margins on standard lithium-ion cells while solid-state prototypes command premium positioning through sulfide electrolyte scarcity.
Pricing Analysis
Aftermarket refurbishment revenue drives lifetime value for Japanese suppliers. Three-tier pricing structure across premium, standard, and economy levels separates DENAN Law-certified flagship cells from uncertified replacement units and industrial-grade bulk contracts. Cost compression in mid-tier smartphone cells is intensifying because third-party battery swaps in Akihabara extend device lifecycles. Price-sensitive procurement concentrates in Kansai educational and mobility scooter segments, while premium device OEMs in Tokyo absorb certified cell premiums.
Supply Chain Analysis
Export-control regimes on sulfide-based ceramic precursor technology limit flows from three domestic chemical houses to qualified cell manufacturers. Raw material sourcing draws from Indonesian nickel laterite, Chilean lithium carbonate, and Australian spodumene concentrate. Cathode active material production rests on cobalt sulfate from DRC hydroxide shipments. Single-source vulnerability concentrates with sulfide electrolyte suppliers in Chubu prefecture. Distribution runs through Kanto's electronics corridor with cathode refiners in Chiba feeding pack assemblers in Saitama.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film deposition technician scarcity constrains solid-state manufacturing scale-up. Vacuum coating expertise for ceramic layer stacking remains locked within legacy optical disc and semiconductor equipment veterans, creating a bottleneck that determines competitive positioning.
For Market Incumbents: Build captive sulfide electrolyte supply moats through strategic partnerships with domestic chemical houses. Secure qualification slots for METI pilot programs before capacity allocation freezes. Backward integration into cathode black mass refining in Kitakyushu captures recycling mandate economics. For New Entrants and Emerging Players: Establish a beachhead in Kyushu's semiconductor corridor near Kumamoto's TSMC-adjacent fabs. Medical-grade portable power packs offer penetrable PMDA Class II certification pathways with superior unit economics. Target industrial IoT sensor deployments through high-reliability cell specifications. For Investors and Strategic Acquirers: METI's 2030 recycling mandate reshapes the acquisition landscape toward integrated refining and recovery capabilities. Five-to-ten year viability favors suppliers with dual lithium-ion and solid-state production architectures. Monitor sulfide ceramic electrolyte yield breakthroughs as the inflection signal for manufacturing readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Line Deployment | Hybrid wet-coating and dry-pressing capabilities bridge lithium-ion reliability to next-generation performance. |
| Cathode Material Backward Integration | In-house production of layered oxide cathodes compresses lot-to-lot variation for DENAN Law certification. |
| Medical-Grade Certification Investment | PMDA Class II pathways command premium positioning in Osaka's health-monitoring device cluster. |
| Recycling Infrastructure Buildout | Kitakyushu black mass refining capacity captures METI-mandated material recovery economics. |
| Kyushu Pack Assembly Expansion | Proximity to Kumamoto's semiconductor fabs creates captive demand for high-reliability industrial cells. |
Research Methodology
Initial hypotheses were tested against primary input from cell manufacturing executives, cathode material procurement leads, solid-state R&D directors, and aftermarket service providers and refined through secondary validation. METI regulatory filings, JIS standard documentation, customs trade data for lithium and cobalt imports, and OEM supply chain disclosures anchored the quantitative foundation. Bottom-up capacity modeling and top-down demand aggregation triangulated market sizing.
Demand-supply balance dynamics shaped the analytical framework across the analysis window. Segmentation dimensions included chemistry type, end-use application, form factor, certification tier, and regional production cluster. CAGRs were derived from installed base turnover rates and replacement cycle compression. Forecast inputs incorporated solid-state manufacturing yield curves and recycling infrastructure buildout timelines.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rates and maritime freight indices would shift the trajectory. Forecasts reflect documented assumptions on sulfide electrolyte qualification timelines and cobalt price band stability. Material shifts in METI pilot program scale or DENAN Law enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Cell Market
Batteries
Middle-East Battery Market
Batteries
North Europe Battery Market
Batteries
Forklift Battery Charger Market
Batteries
Automotive Starting Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Silicon Battery Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
Potassium-Ion Battery Market
Batteries
United States SLI Battery Market
Batteries
Iron Salt Battery Market
Batteries
Drone Power Sources Market
Batteries
Lithium Pouch Cell Market
Batteries
Flow Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market