
 North Africa Battery Market | 2026-2036
North Africa Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North Africa Battery Market Analytics
Moroccan gigafactory development is pivoting toward phosphate-derived cathode materials for regional battery production. Panasonic Corporation leverages its lithium-ion expertise to anchor supply relationships with North African renewable developers. Saft Groupe S.A. specializes in industrial nickel-cadmium systems for oil and gas backup applications across Algeria. Chloride Egypt S A E dominates domestic lead-acid assembly and controls distribution networks throughout the Nile Delta.
North Africa batteries encompass electrochemical energy storage devices utilizing lead-acid, lithium-ion, nickel-cadmium, or nickel-metal hydride chemistries with nominal voltages typically spanning 2V to 48V per cell, engineered for repeated charge-discharge cycles exceeding 500 cycles depending on depth of discharge and thermal management. These systems primarily stabilize intermittent renewable generation, power electric mobility fleets, and ensure continuity for industrial operations across grid-constrained environments. Lead-acid technology occupies the mature replacement segment for automotive starter batteries and telecom backup across price-sensitive rural markets. Lithium-ion chemistry leads growth in grid energy storage and electric vehicle applications where energy density above 250 Wh/kg offsets premium procurement costs. Solid-state technology represents the emerging margin pool, with regional R&D partnerships targeting safer thermal profiles for desert climate deployment.
Egypt's FRA and EETC enforce grid interconnection standards that mandate frequency response capabilities for utility-scale battery installations, while Morocco's ONEE integrates storage procurement into national renewable auction mechanisms. Algeria's national energy regulator imposes local content thresholds that restrict fully imported systems and incentivize domestic assembly partnerships. Stakeholders must monitor how evolving CE marking alignment and EU Green Deal carbon border adjustments reshape competitive access for European versus Asian battery suppliers.
Market Dynamics
Egypt's FRA and EETC grid interconnection standards are forcing battery suppliers to redesign frequency response capabilities into utility-scale systems, while Morocco's renewable auction mechanisms embed storage procurement into every new solar and wind tender.
Growth Catalysts
- ONEE auction mandates:Morocco's national electricity office requires co-located storage for all utility-scale renewable projects, guaranteeing lithium-ion procurement volumes through 2030.
- Phosphate-derived cathodes:Moroccan mining-to-materials integration is creating regional LFP supply chains that bypass Asian precursor dependence.
- Industrial corridor electrification:Egypt's Cairo-Alexandria manufacturing belt is replacing diesel backup generators with battery systems to meet factory uptime requirements.
Market Restraints
- Lithium carbonate volatility:Raw material price swings from South American brine operations compress margins for regional assemblers lacking long-term offtake contracts.
- Algerian local content floors:Domestic assembly thresholds below 40 percent trigger import restrictions that block fully integrated foreign systems from national tenders.
- Thermal degradation in desert climates:Ambient temperatures exceeding 45°C accelerate lithium-ion calendar aging, forcing oversizing and cooling costs that erode project economics.
Strategic Opportunities
- Tunisian grid modernization:STEG's transmission reinforcement plans create first-mover openings for frequency regulation battery installations along the coastal load centers.
- EU Green Deal carbon border adjustments:European carbon intensity requirements on imported batteries favor North African producers with renewable-powered gigafactories over coal-dependent Asian competitors.
- Telecom tower hybridization:Shared infrastructure operators are replacing diesel gensets with solar-battery hybrids across Libya's underserved eastern provinces.
Industry Challenges
- Electrochemical engineering talent scarcity:Regional universities produce mechanical and electrical graduates, but cell chemistry specialists and battery management system firmware developers remain concentrated in East Asian and European labor markets.
- Multi-regulator certification timelines:Products must sequentially clear Egypt's FRA type approval, Morocco's ONEE technical specifications, and Algerian energy ministry testing, extending commercialization cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Africa Battery Market |
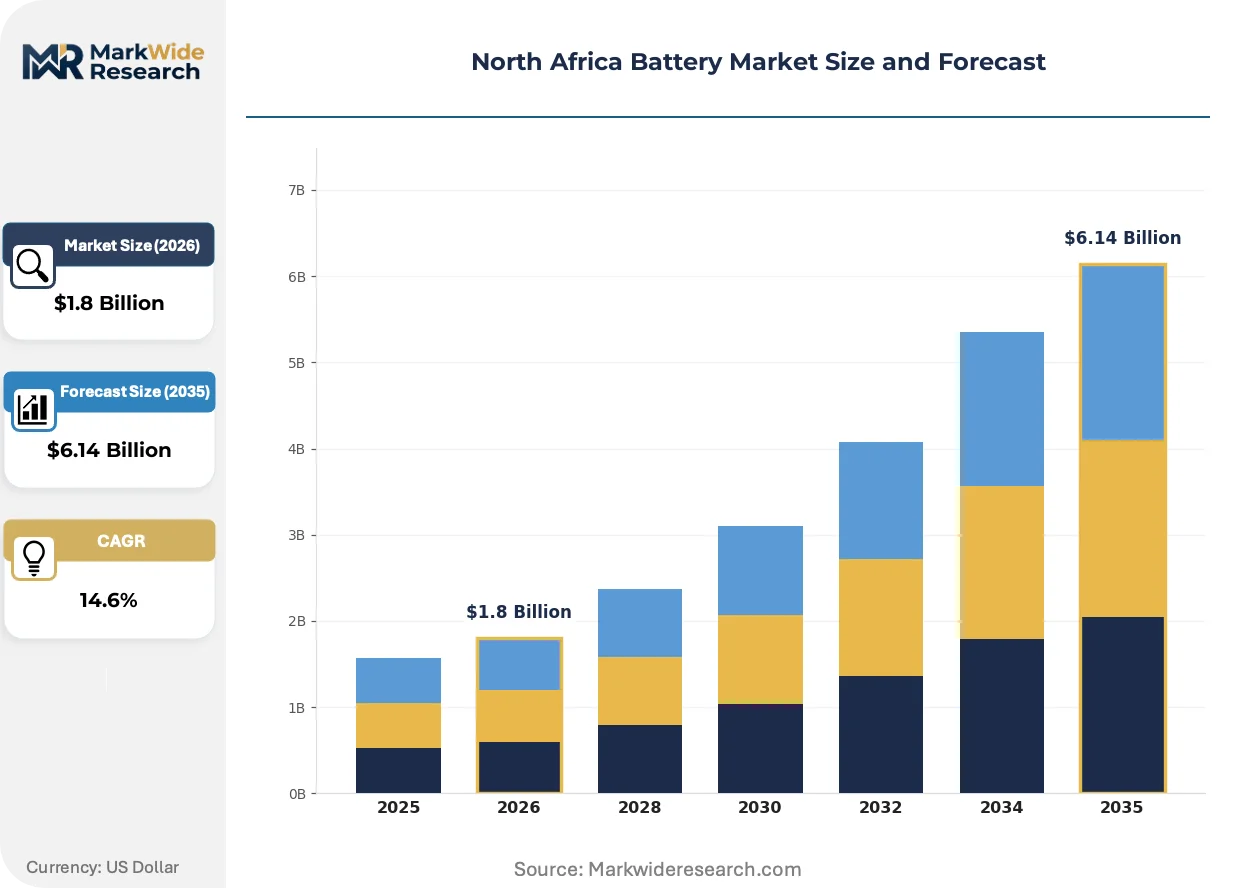
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Nickel-Metal Hydride End User: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Industrial Equipment Application: Automotive, Grid Energy Storage, Portable Devices, Backup Power Systems Technology: Solid-State, Flow Battery, Traditional Battery, Hybrid Technology |
| Companies Covered | Toshiba Corp, Murata Manufacturing Co., Ltd., Exide Industries Ltd, Panasonic Corporation, Duracell Inc, ACDelco, Johnson Controls, Saft Groupe S.A., Chloride Egypt S A E, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Africa Battery Market Evolving Landscape
Desert climate engineering is driving thermal management innovation, while regulatory alignment with European standards is reshaping supplier qualification criteria across North African procurement channels.
Solid-state electrolyte research partnerships between Moroccan phosphate processors and European institutes are integrating ceramic separator technologies into pilot production lines. ONEE and private renewable developers are monitoring these trials for potential deployment in high-temperature installations where conventional liquid electrolytes degrade prematurely. Successful integration would enable thinner thermal management systems and higher energy density packaging for utility-scale containers.
CE marking alignment is accelerating as Moroccan and Tunisian regulators adopt EU battery directive testing protocols ahead of formal trade agreements. This regulatory convergence allows manufacturers to clear single certification pathways for both North African tenders and European export markets. Algerian authorities have resisted full harmonization, maintaining national testing laboratories that extend approval timelines for non-EU certified products.
Industrial buyers from cement, steel, and petrochemical operations are consolidating procurement through engineering-procurement-construction contractors rather than direct battery vendor relationships. This channel shift transfers technical specification responsibility to EPC firms with stronger balance sheets and existing banking relationships. Egypt's heavy industry clusters around Suez and Alexandria exhibit the most pronounced migration toward turnkey storage contracting models.
North Africa Battery Market Segmentation
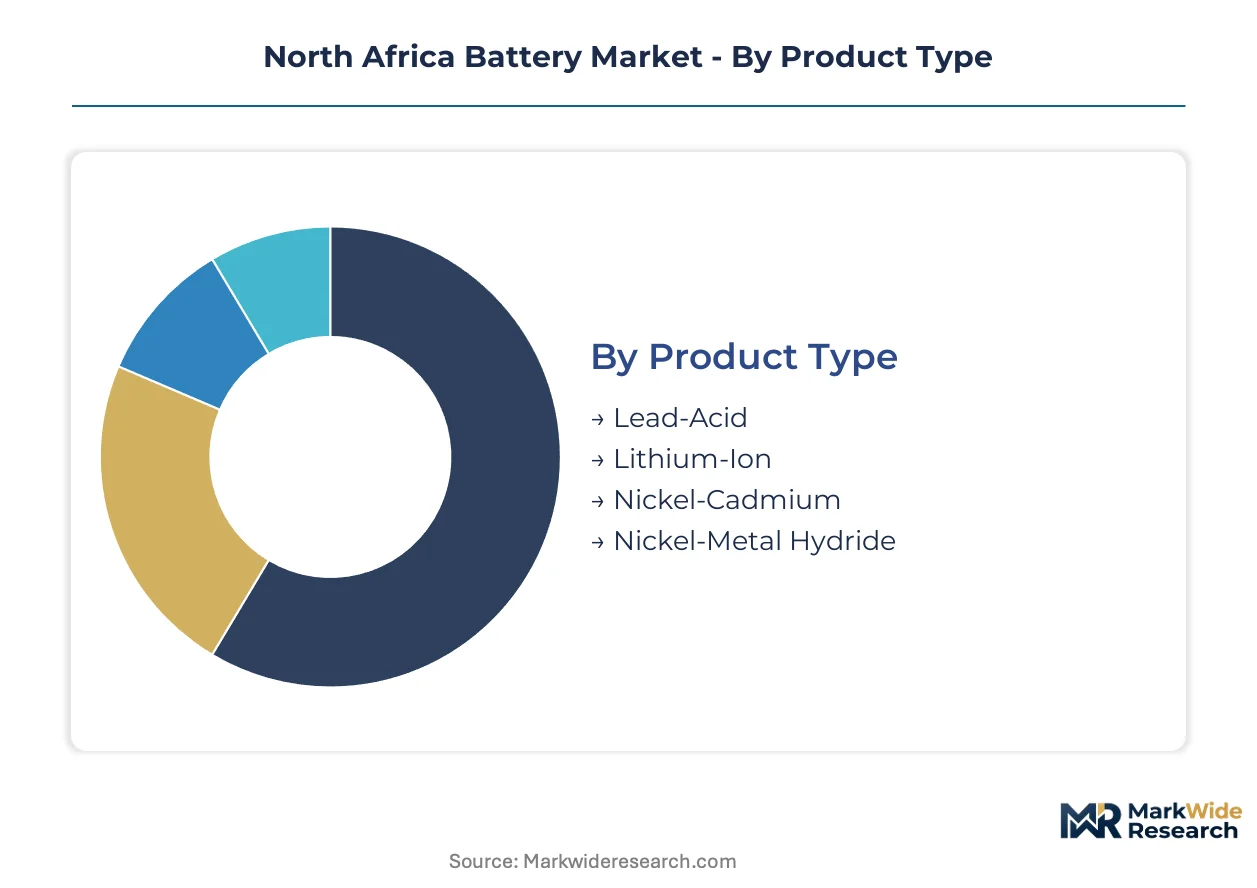
North Africa's battery procurement patterns diverge sharply by chemistry and use case, with lithium-ion commanding premium project finance while lead-acid sustains volume through replacement cycles. Understanding these segment boundaries clarifies where Moroccan phosphate integration, Egyptian industrial electrification, and Algerian local content rules reshape competitive access.
Product Type:
Capital intensity varies dramatically across electrochemical systems, with lithium-ion gigafactory investments dwarfing lead-acid assembly operations by orders of magnitude.
- Lead-Acid:Mature flooded and valve-regulated designs utilizing lead dioxide cathodes and sponge lead anodes in sulfuric acid electrolyte. Demand concentrates in Egypt's Nile Delta automotive aftermarket and telecom backup installations where price sensitivity dominates procurement decisions and established distribution networks favor incumbent suppliers.
- Lithium-Ion:NMC and LFP cell architectures with energy densities exceeding 200 Wh/kg and cycle lives above 3,000 deep discharges. Moroccan ONEE renewable auctions and Egypt's Cairo-Alexandria industrial corridor are absorbing utility-scale containerized systems and forklift fleets, though thermal management costs erode desert deployment economics.
- Nickel-Cadmium:Sintered plate designs prized for extreme temperature tolerance and maintenance-free operation in remote installations. Algerian oil and gas infrastructure operators specify these systems for wellhead automation backup despite cadmium content restrictions tightening in European export markets.
- Nickel-Metal Hydride:Rare earth hydride anode chemistry bridging performance between nickel-cadmium and lithium-ion for hybrid vehicle auxiliary power and medical equipment.
Lead-acid absorbs the bulk of installed capacity; lithium-ion is expanding most quickly.
End User:
Customer scale and technical sophistication determine procurement channel structure, from multinational EPC consortiums to fragmented retail distributors.
- Electric Vehicles:Passenger cars, buses, and material handling equipment utilizing high-voltage battery packs with integrated thermal management and battery management systems. Morocco's nascent EV assembly sector and Egypt's forklift electrification mandates in Suez Canal Economic Zone freeports are concentrating early procurement volumes.
- Renewable Energy Storage:Utility-scale and commercial behind-the-meter installations co-located with solar and wind generation. ONEE's storage procurement mandates and Egypt's FRA frequency response requirements are standardizing lithium-ion container specifications across North African tender documents.
- Consumer Electronics:Smartphones, laptops, and power tools requiring cylindrical and prismatic cells with standardized form factors and safety certifications.
- Industrial Equipment:Uninterruptible power supplies, mining equipment, and manufacturing automation systems demanding customized form factors and extended operational lifespans in harsh environments.
Industrial equipment commands the highest margins per megawatt-hour; renewable energy storage is climbing the fastest.
Application:
Deployment environment dictates engineering specifications, with grid-connected systems facing stricter certification burdens than portable devices.
- Automotive:Starter, lighting, and ignition batteries alongside traction packs for electrified drivetrains. Egypt's domestic vehicle assembly sector and Moroccan Renault-Nissan supplier parks are localizing procurement for conventional lead-acid while importing lithium-ion modules for emerging EV platforms.
- Grid Energy Storage:Frequency regulation, peak shaving, and renewable firming installations requiring megawatt-hour scale and utility interconnection compliance. Moroccan solar-wind hybrid projects and Tunisian STEG transmission reinforcement plans are creating tender pipelines for containerized lithium-ion systems.
- Portable Devices:Consumer electronics and professional tools emphasizing energy density and recharge speed over cycle longevity.
- Backup Power Systems:Stationary reserve power for telecom towers, data centers, and critical infrastructure where discharge duration and reliability supersede energy density metrics.
Backup power systems retain the largest installed base; grid energy storage is gaining share fastest.
Technology:
R&D investment intensity separates emerging architectures from commoditized production, with solid-state partnerships commanding premium valuation multiples.
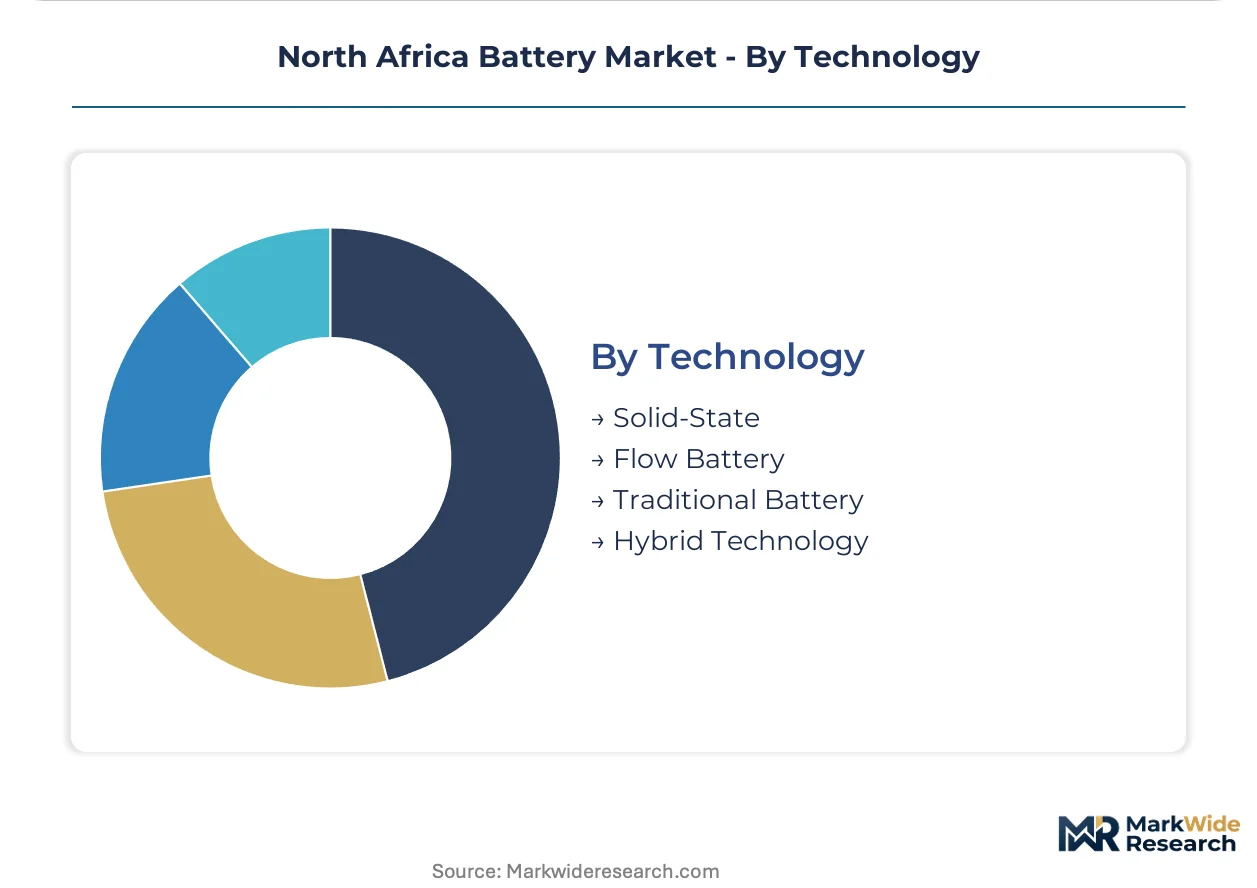
- Solid-State:Ceramic or polymer electrolyte replacements for liquid organic solvents, targeting enhanced safety and energy density above 400 Wh/kg. Moroccan phosphate processors and European research institutes are piloting sulfide and oxide electrolyte integration for desert climate deployment where thermal stability offers decisive advantages.
- Flow Battery:Vanadium and zinc-bromine redox systems with decoupled power and energy scaling for long-duration storage applications. Remote mining operations in Algeria and Mauritania are evaluating these technologies for off-grid renewable integration despite higher upfront capital requirements.
- Traditional Battery:Conventional liquid electrolyte lithium-ion and lead-acid chemistries with established supply chains and recycling infrastructure.
- Hybrid Technology:Combined electrochemical and mechanical storage or dual-chemistry systems optimizing for multiple discharge durations.
Traditional battery technology dominates current deployments; solid-state is advancing most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco's phosphate reserves anchor the region's cathode material integration. Egypt's Cairo-Alexandria corridor concentrates industrial battery demand. Algeria's hydrocarbon infrastructure sustains nickel-cadmium procurement.
Morocco
ONEE's renewable auction mandates are driving lithium-ion procurement for solar-wind hybrid projects. The national electricity office embeds storage requirements into every utility-scale tender. OCP Group's mining operations near Khouribga are supplying phosphate-derived LFP precursors to emerging gigafactory developments.
Egypt
FRA and EETC grid interconnection standards are forcing frequency response redesigns into utility-scale battery systems. The financial regulatory authority and electricity transmission company jointly enforce technical compliance for renewable installations. Industrial facilities across the Suez Canal Economic Zone are replacing diesel backup generators with lithium-ion systems to meet uptime requirements.
Algeria
Sonatrach's oil and gas infrastructure operators specify nickel-cadmium systems for remote wellhead automation backup. The national energy regulator imposes local content thresholds above 40 percent that restrict fully imported battery systems from national tenders. Hydrocarbon processing clusters around Hassi Messaoud are absorbing maintenance-free industrial batteries for critical control systems.
Tunisia
STEG's transmission reinforcement plans are creating procurement openings for frequency regulation battery installations. The national electricity and gas utility targets coastal load centers for grid modernization investments. Manufacturing facilities around Tunis and Sfax are evaluating behind-the-meter storage to manage peak demand charges.
Libya
Shared telecom infrastructure operators are deploying solar-battery hybrids to replace diesel gensets across underserved eastern provinces. The fractured regulatory environment complicates equipment certification but creates first-mover opportunities for off-grid energy solutions. Coastal cities from Benghazi to Tobruk are concentrating early hybrid system deployments.
North Africa Battery Market Competitive Landscape
Global majors compete with regional champions across certification pathways and distribution networks. The vendor base spans Japanese electronics conglomerates, European industrial specialists, and entrenched local assemblers. Three archetypes dominate: integrated materials-to-cells players leveraging phosphate integration, industrial battery specialists serving oil and gas backup applications, and domestic assemblers controlling last-mile distribution. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms navigate multi-regulator approval timelines.
Within the industrial specialist tier, Saft Groupe S.A. and Chloride Egypt S A E exemplify contrasting geographic anchoring strategies. Panasonic Corporation occupies a position bridging global lithium-ion expertise with regional renewable developer relationships. Toshiba Corp represents the diversified electronics conglomerate archetype with cross-sector battery applications.
| Leading Market Players |
|---|
| Toshiba Corp |
| Murata Manufacturing Co., Ltd. |
| Exide Industries Ltd |
| Panasonic Corporation |
| Duracell Inc |
| ACDelco |
| Johnson Controls |
| Saft Groupe S.A. |
| Chloride Egypt S A E |
| Others |
Value Network & Pricing Analysis
Cell chemistry specialists concentrated in East Asian labor markets widen pricing-tier spreads between premium lithium-ion systems and commoditized lead-acid alternatives. Egyptian assembly operations leverage lower electrochemical engineering wages to compress mid-tier pricing against Moroccan phosphate-integrated producers.
Pricing Analysis
Warranty and thermal management service bundling separates premium lithium-ion offerings from unbundled lead-acid transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in standard-tier containerized systems is intensifying because Moroccan gigafactory capacity additions reduce precursor import dependence. Industrial buyers in Egypt's Suez Canal Economic Zone exhibit highest price sensitivity, while Algerian oil and gas operators prioritize reliability over procurement cost.
Supply Chain Analysis
Containerized freight costs from Chinese and South Korean cell manufacturers dominate landed cost structures for utility-scale projects. Raw material dependencies on Chilean lithium carbonate, Indonesian nickel, and Moroccan phosphate feedstock create multi-continental sourcing complexity. Single-source vulnerability in solid-state electrolyte precursor supply threatens pilot production timelines. Distribution runs through engineering-procurement-construction contractors rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-regulator certification timelines exceeding fourteen months force capital-constrained assemblers toward exit, consolidating procurement relationships around balance-sheet-strong EPC partners.
For Market Incumbents: Extend phosphate-derived cathode backward integration into precursor production to defend against Asian cell import competition. Anchor capacity additions in Morocco's Khouribga mining corridor to capture ONEE auction procurement. Certification investment in CE marking alignment opens parallel European export channels. For New Entrants and Emerging Players: Engineering-procurement-construction contractors represent the most accessible channel partners for bypassing established distribution networks. Target Tunisia's STEG transmission reinforcement tenders where incumbent relationships remain underdeveloped. White-space exists in Libyan telecom tower hybridization and Algerian nickel-cadmium replacement cycles. For Investors and Strategic Acquirers: Re-rating potential sits with phosphate-integrated materials processors given EU Green Deal carbon border adjustment catalysts. Long-term viability favors archetypes with captive mining supply and renewable-powered gigafactory operations. Watch solid-state electrolyte pilot yields as inflection indicator for thermal management cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | OCP Group phosphate supply secures LFP cost advantage against Asian competitors. |
| CE Marking Alignment Investment | Moroccan and Tunisian regulatory convergence enables single-certification European market access. |
| Desert Climate Thermal Management R&D | Solid-state electrolyte partnerships address 45°C ambient degradation eroding project economics. |
| EPC Channel Partnership Development | Turnkey contracting models transfer technical specification responsibility from battery vendors. |
| Local Content Threshold Compliance | Algerian assembly partnerships circumvent 40 percent domestic content import restrictions. |
Research Methodology
Document review covered regulatory filings from Egypt's FRA and EETC, Moroccan ONEE tender documentation, and Algerian energy ministry circulars, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and cell chemistry procurement leads. Secondary validation drew from IEA renewable investment databases, UN Comtrade battery flow statistics, and North African customs records. Bottom-up project pipeline aggregation and top-down macroeconomic scaling were triangulated against primary field intelligence.
Installed capacity and revenue estimates were generated across chemistry type, end-use segment, and national regulatory framework dimensions. CAGRs were derived from regression analysis of historical procurement volumes and auction pipeline disclosure. Forecast inputs incorporated lithium carbonate price volatility indices and desert climate degradation curves specific to thermal management engineering requirements.
Caveats apply where lithium raw material supply disruptions or EU carbon border adjustment implementation delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Anode Materials Market
Batteries
Nickel-Based Battery Charger Market
Batteries
Global Coke Oven Batteries Market
Batteries
Italy SLI Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
GCC Rechargeable Battery Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Marine Powerboat Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Europe Battery Market
Batteries
South Africa Battery Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Marine Low-Voltage Battery Market