
 Absorbed Glass Mat (AGM) Separator Batteries Market | 2026-2036
Absorbed Glass Mat (AGM) Separator Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbed Glass Mat (AGM) Separator Batteries Market Outlook
Data center uninterruptible power supply deployment is hardening as the dominant demand pillar for AGM separator batteries. East Penn Manufacturing Co., Inc. anchors North American production capacity through its vertically integrated lead-acid operations. Hollingsworth & Vose specializes in advanced glass microfiber formulations that determine separator porosity and acid retention. FIAMM Energy Technology S.p.A. competes across European industrial and telecommunications channels with region-specific certification depth.
Absorbed Glass Mat separator batteries employ compressed glass microfiber mats between lead plates to immobilize electrolyte, enabling valve-regulated operation with minimal gas emission and orientation-independent installation. The 12V product category dominates commercial and residential replacement cycles, while 48V configurations are gaining traction in telecom base stations and light electric vehicle architectures. Lead acid technology sustains cost-sensitive volume applications, though lithium-ion alternatives are displacing premium segments in renewable energy storage where cycle life requirements exceed AGM capabilities.
The EPA enforces stringent recycling mandates for lead-acid batteries under the Battery Act, shaping collection infrastructure and secondary material economics across the United States. REACH and the EU Green Deal impose substance restrictions and carbon footprint disclosures on European battery supply chains, elevating compliance costs for imported separators. China's MIIT enforces GB standards for VRLA battery performance and safety, creating a dual-track certification burden for multinational suppliers. Stakeholders must monitor chemistry-neutral procurement policies in military and critical infrastructure segments where technology lock-ins are loosening.
Market Dynamics
Data center UPS deployment is compressing replacement cycles for AGM separator batteries as hyperscale operators demand 15-year design life and 99.999% uptime guarantees, forcing separator manufacturers to reformulate glass microfiber porosity standards.
Growth Catalysts
- EU Green Deal carbon footprint disclosures:Stationary energy storage procurement in Germany's industrial corridor now mandates lifecycle emissions documentation, advantaging established AGM suppliers with certified recycling streams.
- Telecom base station densification:48V AGM configurations are capturing rack space in edge computing nodes where lithium thermal runaway risks complicate indoor installation codes.
- China's dual carbon goals:MIIT enforcement of GB standards for VRLA battery safety is accelerating domestic separator quality upgrades and import substitution.
Market Restraints
- Lead price volatility:Secondary smelter capacity constraints in North America are amplifying raw material cost swings for battery manufacturers without captive recycling.
- Glass microfiber supply concentration:Advanced separator formulations depend on Hollingsworth & Vose and a narrow European supplier base, creating single-source vulnerability.
- Lithium-ion cycle life superiority:Renewable energy storage applications exceeding 3,000 cycles are defaulting to lithium iron phosphate, capping AGM's addressable market in utility-scale buffers.
Strategic Opportunities
- India's telecom tower electrification:Diesel displacement mandates in rural base stations are opening volume deployment for 48V AGM systems in hot-climate configurations.
- Hybrid energy storage architectures:Coupling AGM buffers with lithium-ion cycling cores is emerging as a cost-optimized design for commercial solar-plus-storage installations.
- US military chemistry-neutral procurement:Defense logistics commands are relaxing technology lock-ins for tactical power systems, enabling AGM requalification against lithium alternatives.
Industry Challenges
- Separator porosity engineering talent scarcity:Glass microfiber formulation expertise concentrates among retiring specialists at Hollingsworth & Vose and East Penn Manufacturing, constraining new entrant R&D velocity.
- Dual-track certification burden:Multinational suppliers must simultaneously satisfy China's GB standards, EU REACH substance restrictions, and US EPA recycling mandates, extending product qualification timelines.
- Legacy charging infrastructure incompatibility:Existing float-charger networks in industrial facilities require voltage recalibration to accommodate next-generation AGM electrochemistry, slowing retrofit adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbed Glass Mat (AGM) Separator Batteries Market |
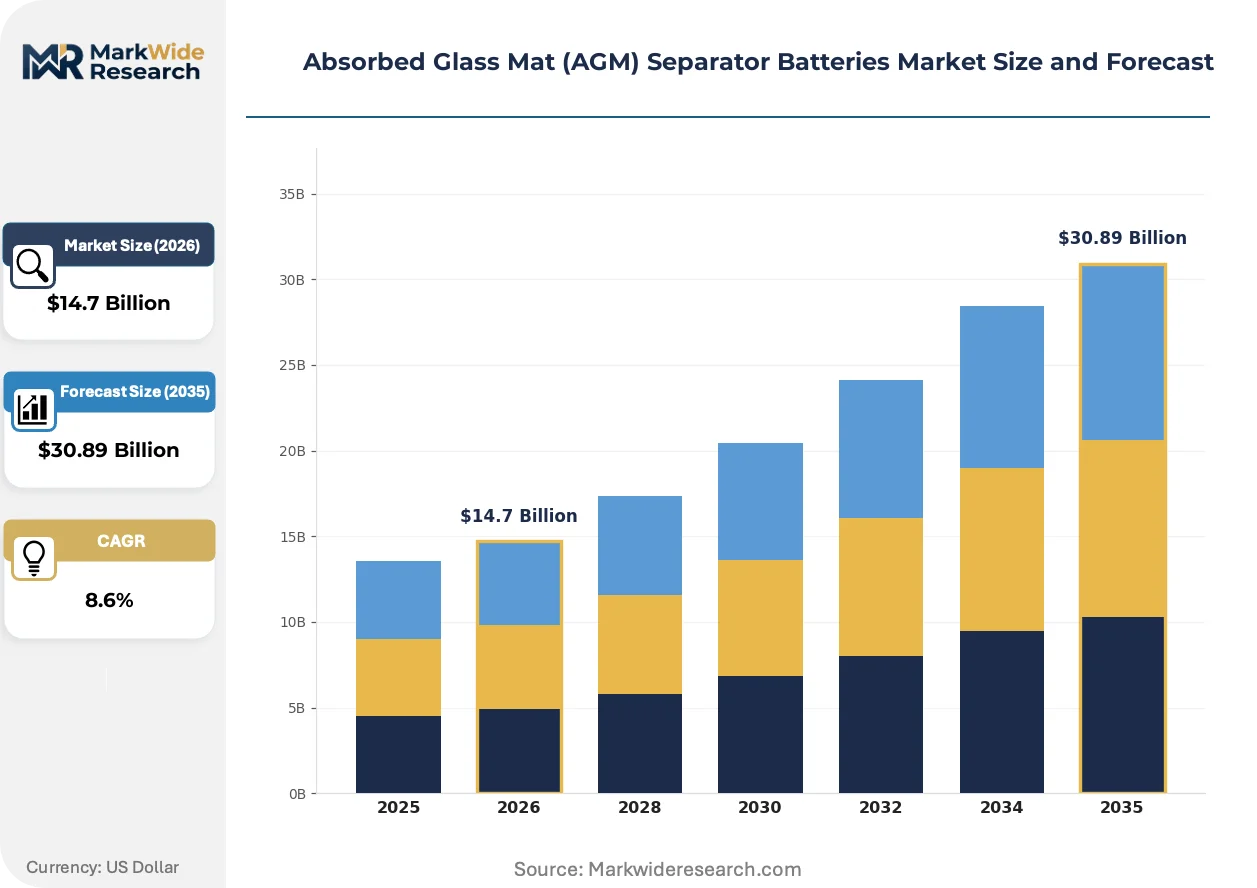
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 12V, 6V, 24V, 48V Application: Uninterruptible Power Supply, Electric Vehicles, Renewable Energy Storage, Telecommunications End User: Residential, Commercial, Industrial, Military Technology: Lead Acid, Lithium-ion, Nickel Cadmium, Others |
| Companies Covered | NINGBO BAIHENG SCIENCE&TECHNOLOGY CO., LTD., Fengxin Industrial Co. Ltd., Hollingsworth & Vose, Hokuetsu Corporation, ShanDong Renfeng Special Materials Co. Ltd., Nippon Sheet Glass Co., Ltd., FIAMM Energy Technology S.p.A., Daramic, East Penn Manufacturing Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbed Glass Mat (AGM) Separator Batteries Market Strategic Shifts
Separator technology and procurement patterns are diverging as data center operators, telecom carriers, and industrial buyers impose incompatible performance specifications on AGM manufacturers.
Compressed glass microfiber mat technology is decentralizing stationary power architecture by enabling orientation-independent battery deployment in constrained mechanical rooms. Hyperscale data center operators in Northern Virginia and Frankfurt are specifying 12V monobloc configurations with front-terminal access for aisle-width reduction. This topology is compressing traditional centralized battery room footprints by 40% while complicating thermal management requirements.
REACH substance restrictions and the EU Green Deal's carbon border adjustment mechanism are tightening separator supply chain documentation requirements for European battery assemblers. German industrial buyers now demand batch-level recycled content certificates for glass microfiber mats. The 12V replacement segment is responding by consolidating procurement around suppliers with vertically integrated European recycling infrastructure.
Buyer concentration among hyperscale data center operators is compressing vendor negotiation leverage and unbundling traditional after-sales service contracts. Amazon Web Services and Microsoft Azure are mandating 20-year total cost of ownership guarantees that transfer separator degradation risk to manufacturers. This shift is most visible in Northern Virginia's Data Center Alley, where procurement teams are disqualifying suppliers without predictive analytics capabilities for state-of-health monitoring.
Absorbed Glass Mat (AGM) Separator Batteries Market Segmentation
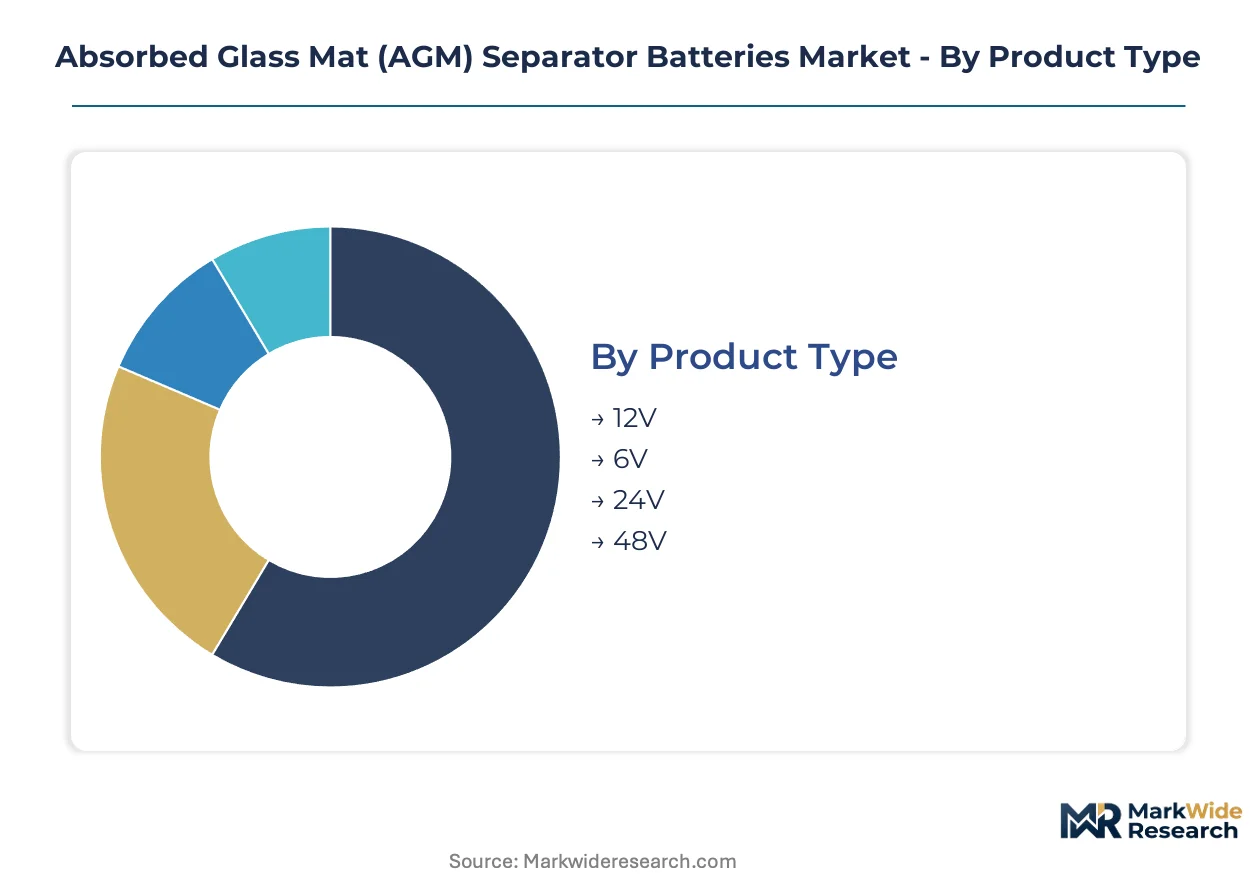
AGM separator batteries fragment across voltage configurations, end-use applications, and competing electrochemical systems. Procurement patterns diverge sharply between replacement-driven markets and emerging installation categories. Each segment imposes distinct separator porosity specifications and certification burdens.
Product Type:
Voltage tiers split between high-volume replacement cycles and emerging system architectures demanding specialized electrochemical performance.
- 12V:Compressed glass microfiber mats in monobloc configurations dominate commercial and residential replacement cycles with front-terminal access for aisle-width reduction. Data center operators in Northern Virginia and Frankfurt specify these for 15-year design life guarantees, forcing separator manufacturers to tighten acid retention standards.
- 48V:Rack-mounted configurations capture space in telecom base stations and light electric vehicle architectures where orientation-independent deployment matters. India's diesel displacement mandates for rural tower electrification are accelerating hot-climate specification demand.
- 6V:Deep-cycle variants serve marine and recreational vehicle applications with thick-plate construction for sustained discharge tolerance.
- 24V:Industrial forklift and material handling equipment specify these for opportunity charging protocols in European warehouse automation.
Mature deployment sits with 12V monobloc systems. Newer deployment is concentrated in 48V rack configurations.
Application:
End-use concentration tracks infrastructure investment cycles and regulatory mandates for backup power reliability.
- Uninterruptible Power Supply:Hyperscale data center operators demand 99.999% uptime guarantees, compressing replacement cycles and transferring separator degradation risk to manufacturers through 20-year total cost of ownership contracts. Amazon Web Services and Microsoft Azure procurement teams disqualify suppliers lacking predictive state-of-health analytics.
- Telecommunications:Edge computing node densification favors 48V AGM where lithium thermal runaway risks complicate indoor installation codes under NFPA and IEC standards. German industrial corridor retrofit programs specify these for base station hardening.
- Electric Vehicles:Light electric vehicle architectures and golf cart fleets specify AGM for cost-sensitive volume production against lithium-ion alternatives.
- Renewable Energy Storage:Commercial solar-plus-storage installations default to lithium iron phosphate for cycle life exceeding 3,000 cycles, capping AGM penetration to hybrid buffer configurations.
UPS procurement commands premium pricing tiers. Telecom expansion is gaining share fastest.
End User:
Buyer sophistication and contract structures diverge across facility scale and regulatory oversight intensity.
- Industrial:German manufacturing corridor retrofits mandate lifecycle emissions documentation under EU Green Deal procurement rules, advantaging suppliers with certified European recycling streams. Existing float-charger infrastructure requires voltage recalibration for next-generation AGM electrochemistry.
- Commercial:Data center, healthcare, and financial services procurement teams unbundle after-sales service contracts and impose predictive analytics requirements.
- Military:US defense logistics commands relax technology lock-ins under chemistry-neutral procurement policies, enabling AGM requalification against lithium alternatives for tactical power systems.
- Residential:Replacement cycles dominate with price-sensitive procurement through distributor and retail channels.
Industrial buyers drive specification tightening. Military requalification opens replacement opportunities.
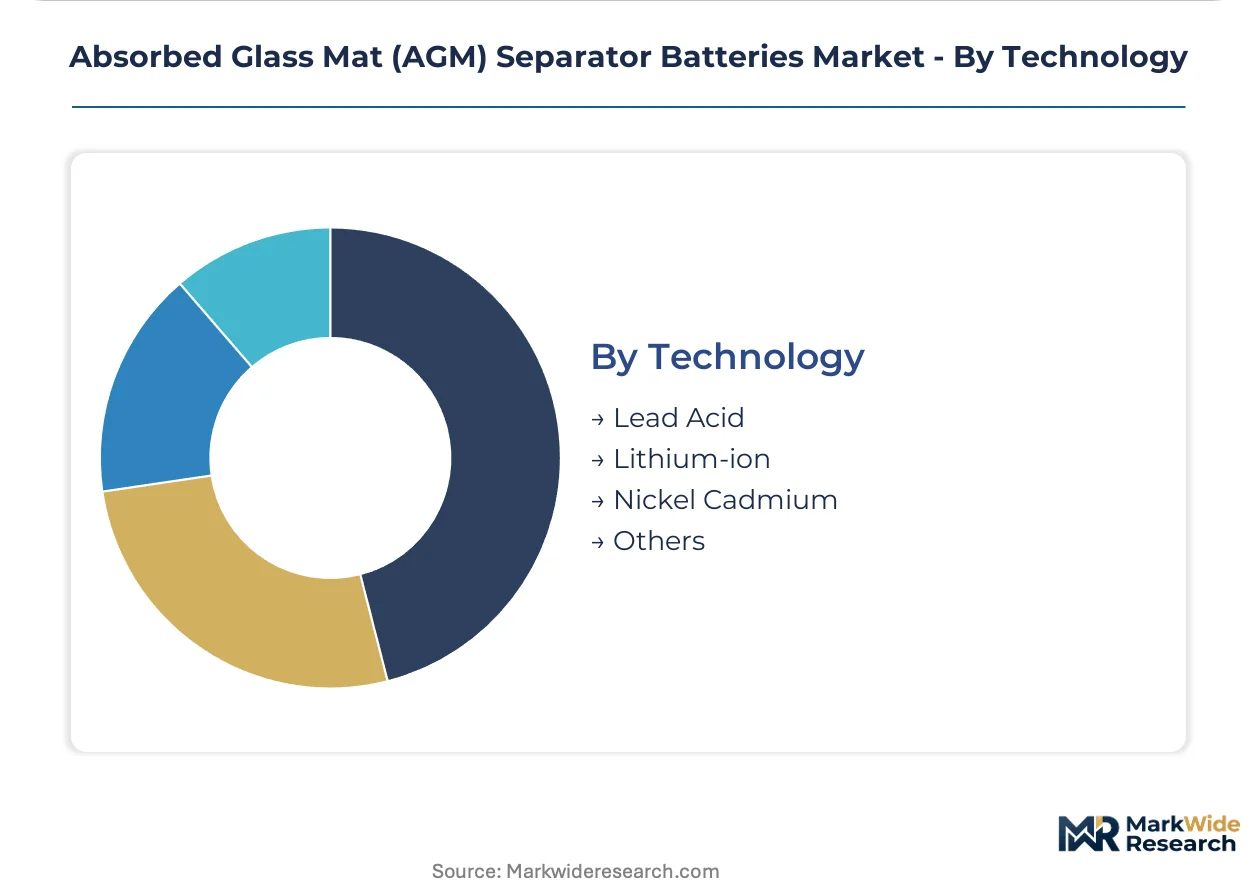
Technology:
Electrochemical competition segments by cycle life requirements and capital cost sensitivity.
- Lead Acid:AGM and gel variants sustain cost-sensitive volume applications in telecom backup and automotive starting-lighting-ignition. EPA Battery Act recycling mandates and REACH substance restrictions shape collection infrastructure economics.
- Lithium-ion:Lithium iron phosphate chemistry displaces AGM in renewable energy storage where cycle life requirements exceed 3,000 cycles. China's MIIT GB standards and EU carbon border adjustment mechanisms tighten supply chain documentation.
- Nickel Cadmium:Aviation and rail signaling applications persist where extreme temperature tolerance outweighs cadmium toxicity concerns under RoHS exemptions.
- Others:Sodium-ion and flow battery technologies occupy experimental utility-scale installations.
Lead acid retains installed base dominance. Lithium-ion is climbing the fastest in new renewable energy capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's Data Center Alley concentrates hyperscale UPS deployment through state tax incentives and proximity to fiber backbones. Frankfurt's industrial corridor drives German retrofit demand under EU Green Deal procurement rules. China's Yangtze River Delta anchors domestic separator manufacturing scale.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth compress replacement cycles through 20-year total cost of ownership contracts. EPA Battery Act recycling mandates shape collection infrastructure economics across secondary smelter networks. The Pacific Northwest's renewable energy clusters default to lithium iron phosphate for utility-scale buffers, capping AGM penetration.
Germany
Industrial corridor retrofits mandate lifecycle emissions documentation under EU Green Deal carbon border adjustment mechanisms. REACH substance restrictions tighten separator supply chain documentation requirements for battery assemblers. Bavaria's manufacturing base specifies certified recycling streams for glass microfiber procurement.
China
MIIT enforcement of GB standards for VRLA battery safety accelerates domestic separator quality upgrades. Dual carbon goals tighten emissions benchmarks for stationary energy storage procurement. The Yangtze River Delta concentrates advanced glass microfiber production capacity serving telecom and industrial channels.
India
Diesel displacement mandates for rural telecom tower electrification open volume deployment for 48V AGM systems in hot-climate configurations. CEA grid reliability standards harden backup power requirements across commercial and industrial facilities. Maharashtra's industrial belt drives specification demand for opportunity charging protocols in warehouse automation.
Japan
METI energy storage guidelines favor hybrid architectures coupling lead-acid buffers with lithium-ion cycling cores. JIS standards maintain certification depth for industrial and telecommunications applications. Kanto region data center operators specify orientation-independent battery deployment in constrained mechanical rooms.
Absorbed Glass Mat (AGM) Separator Batteries Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertical integration determining separator supply security. The vendor base concentrates among glass microfiber formulators and battery assemblers with captive recycling infrastructure. Three archetypes dominate: integrated battery manufacturers controlling separator sourcing, specialized glass microfiber suppliers licensing formulation IP, and regional assemblers dependent on merchant separator supply. Capacity expansion and backward integration into glass microfiber production represent the dominant competitive vectors.
Among North American integrated manufacturers, East Penn Manufacturing Co., Inc. anchors industrial and automotive channel presence through vertically structured lead-acid operations. Hollingsworth & Vose occupies a specialist position in advanced glass microfiber formulations that determine separator porosity standards across the industry. FIAMM Energy Technology S.p.A. exemplifies European certification depth for industrial and telecommunications segments.
| Leading Market Players |
|---|
| NINGBO BAIHENG SCIENCE&TECHNOLOGY CO., LTD. |
| Fengxin Industrial Co. Ltd. |
| Hollingsworth & Vose |
| Hokuetsu Corporation |
| ShanDong Renfeng Special Materials Co. Ltd. |
| Nippon Sheet Glass Co., Ltd. |
| FIAMM Energy Technology S.p.A. |
| Daramic |
| East Penn Manufacturing Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Hyperscale data center operators compress vendor negotiation leverage through 20-year total cost of ownership contracts that transfer separator degradation risk to manufacturers. This buyer concentration forces pricing stratification across premium, standard, and economy tiers based on predictive analytics capabilities and certified recycling infrastructure.
Pricing Analysis
Short lead-time premiums dominate separator procurement as data center operators in Northern Virginia and Frankfurt demand 15-year design life guarantees with immediate availability. Price differentiation rests on glass microfiber porosity certification and batch-level recycled content documentation under EU Green Deal rules. Cost compression in standard-tier 12V monobloc systems is intensifying because secondary smelter capacity constraints amplify lead price volatility. Residential replacement buyers exhibit highest price sensitivity; hyperscale operators with uptime guarantees show lowest.
Supply Chain Analysis
Reverse logistics flows for spent lead-acid batteries anchor secondary material economics under EPA Battery Act mandates. Glass microfiber supply concentrates in the United States, Germany, and China, with advanced separator formulations drawing from Hollingsworth & Vose and narrow European supplier bases. Raw material dependencies include lead ingot, borosilicate glass fiber, and sulfuric acid electrolyte. Single-source vulnerability in microfiber formulation creates structural risk. Distribution runs through vertically integrated battery manufacturers and specialized industrial distributors serving telecom and data center channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
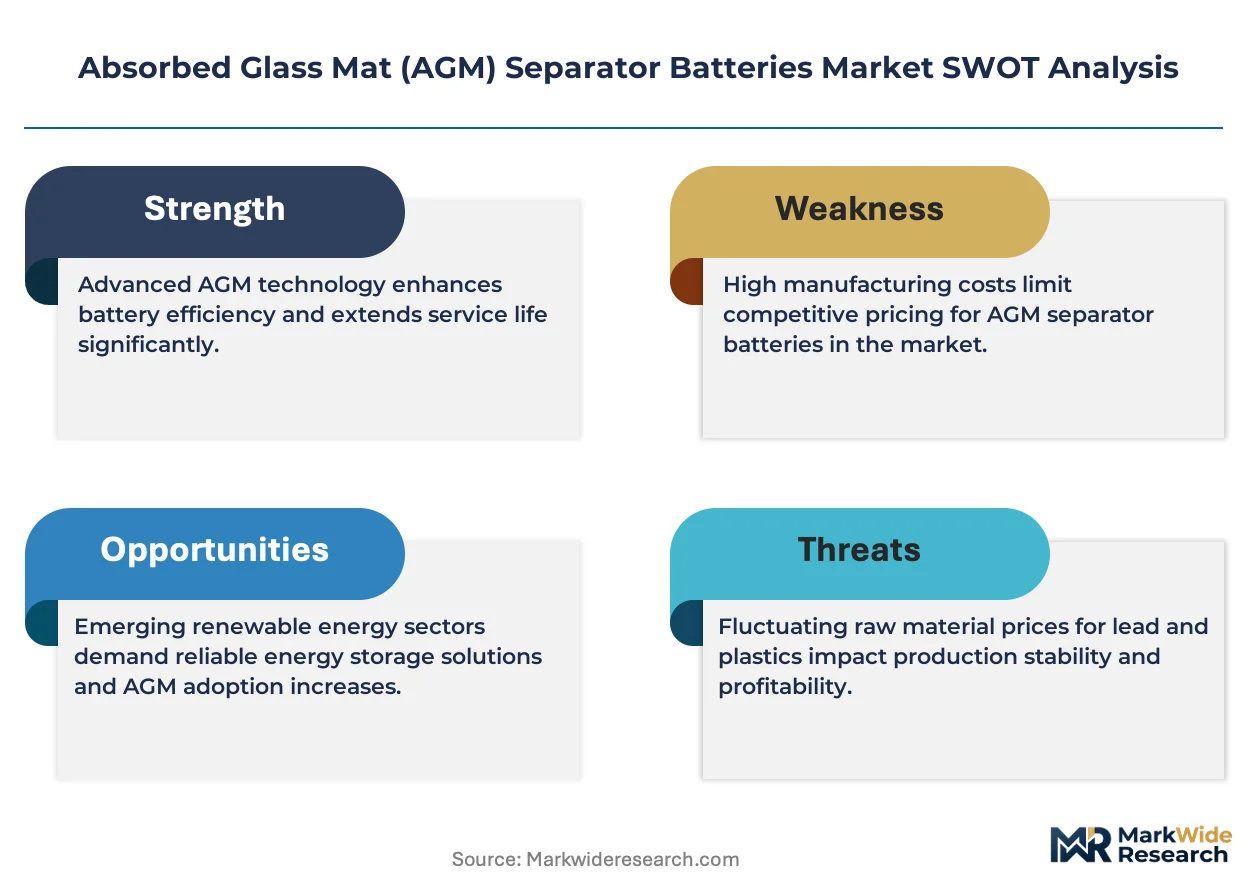
AGM separator batteries constitute a cost-of-compliance story where REACH substance restrictions and EU carbon border adjustment mechanisms erect barrier-to-entry moats for certified incumbents. New entrants face prohibitive qualification timelines against established recycling infrastructure.
For Market Incumbents: Deepen backward integration into glass microfiber production to secure separator supply against Hollingsworth & Vose concentration risk. Expand predictive state-of-health analytics capabilities to meet Amazon Web Services and Microsoft Azure procurement requirements. Capture margin protection through captive secondary smelter capacity that buffers lead price volatility.
For New Entrants and Emerging Players: India's rural telecom tower electrification presents the most penetrable volume deployment for hot-climate 48V configurations. Target diesel displacement mandates with cost-optimized rack systems against lithium thermal runaway installation barriers. Enter through joint manufacturing arrangements with domestic glass fiber suppliers to bypass dual-track certification burdens.
For Investors and Strategic Acquirers: The window for entry favors vertically structured lead-acid manufacturers with certified European recycling streams. Long-term viability hinges on separator porosity engineering talent retention as Hollingsworth & Vose specialists approach retirement. Monitor MIIT enforcement of GB standards for VRLA battery safety as inflection indicator for import substitution acceleration in China.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Microfiber Production | Captive separator supply secures margin protection against Hollingsworth & Vose single-source vulnerability. |
| Predictive Analytics Platform Development | State-of-health monitoring capabilities satisfy hyperscale data center procurement disqualification thresholds. |
| Certified European Recycling Infrastructure Expansion | Batch-level recycled content documentation meets EU Green Deal carbon border adjustment mechanism requirements. |
| Hot-Climate 48V System Qualification | Diesel displacement mandates in India's rural telecom towers open volume deployment against lithium thermal runaway risks. |
| Dual-Track Certification Investment | Simultaneous GB standards, REACH, and EPA compliance accelerates product qualification timelines for multinational supply. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with separator manufacturing executives, data center procurement directors, telecom infrastructure planners, and secondary smelter operators combined with EPA Battery Act enforcement records, MIIT GB standard documentation, and EU ETS carbon border filings. Bottom-up unit economics triangulated against top-down energy storage investment tracking.
Granularity-level modeling addressed voltage configuration, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derived from installation base forecasting and replacement cycle compression analysis. Forecast inputs incorporated hyperscale data center capex disclosures, telecom tower electrification mandates, and lead price volatility indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion cost curves and chemistry-neutral procurement policy shifts. Forecasts reflect documented assumptions about separator degradation rates and recycling stream economics. Practitioners should monitor MIIT GB standard enforcement intensity and EU carbon border adjustment mechanism implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Carbon Foam Battery Market
Batteries
Portable Battery Pack Market
Batteries
Southeast Asia Battery Market
Batteries
Netherlands Rechargeable Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Proton Battery Market
Batteries
Europe Battery Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
East Africa Battery Market
Batteries
Solid Electrolyte Market
Batteries
Hybrid Flow Battery Market
Batteries
Forklift Battery Charger Market
Batteries
Secondary Battery Market
Batteries
South and Central America Battery Market
Batteries
Primary Battery Market
Batteries
Global Zinc Air Batteries Market