
 Cobalt-Free Battery Market | 2026-2036
Cobalt-Free Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt-Free Battery Market Outlook
High-nickel, low-cobalt cathode formulations is reorganizing competitive tiers in cell manufacturing. CATL leverages its integrated precursor-to-pack architecture to sustain cost leadership across prismatic formats. SVOLT differentiates through aggressive capacity builds in Europe and Asia, while BYD anchors vertical control over lithium iron phosphate supply through captive mining and refining positions.
Cobalt-free batteries replace cobalt-containing cathodes with iron, manganese, or nickel-dominant chemistries, typically operating at 3.2-3.7 V nominal voltage and cycling over 3,000 charge events in commercial configurations. Their primary purpose is to eliminate supply chain concentration risk in the Democratic Republic of Congo while maintaining energy density thresholds for mobility and grid applications. Lithium iron phosphate products occupy the dominant revenue position due to mature manufacturing yields and thermal stability profiles that reduce pack-level cooling overhead. Nickel manganese variants represent the fastest-expanding chemistry class as automakers demand higher volumetric energy density without cobalt content. Sodium-ion technology, though earlier in commercial scale, is attracting dedicated capacity investments for stationary storage and entry-level electric vehicles where gravimetric density requirements relax.
The EU Battery Regulation mandates recycled content minimums and supply chain due diligence disclosures that reshape procurement criteria for European automotive OEMs. China's SAMR enforces GB standards on cell safety and labeling that filter market access for imported and domestic producers alike. The US IRA ties production tax credits to North American assembly and critical mineral sourcing thresholds, redirecting investment flows across the value chain. Stakeholders must monitor how regulatory stringency on material provenance intersects with actual cathode chemistry performance in cold-climate duty cycles.
Market Dynamics
Automakers are decoupling from cobalt supply chains as the Democratic Republic of Congo concentrates 70% of global mined output, triggering parallel investments in iron-phosphate and high-nickel manganese alternatives.
Growth Catalysts
- EU Battery Regulation:Mandatory due diligence disclosures and recycled content minimums are compelling European OEMs to certify cobalt-free cathode supply chains ahead of 2030 compliance deadlines.
- Electric vehicle procurement:Tier-1 automakers are inserting cobalt-free chemistry clauses into multi-year cell supply agreements, redirecting foundry capacity toward lithium iron phosphate and nickel-manganese formulations.
- Integrated precursor manufacturing:China-based cell producers are consolidating cathode active material production with pack assembly, compressing unit economics for cobalt-free architectures.
Market Restraints
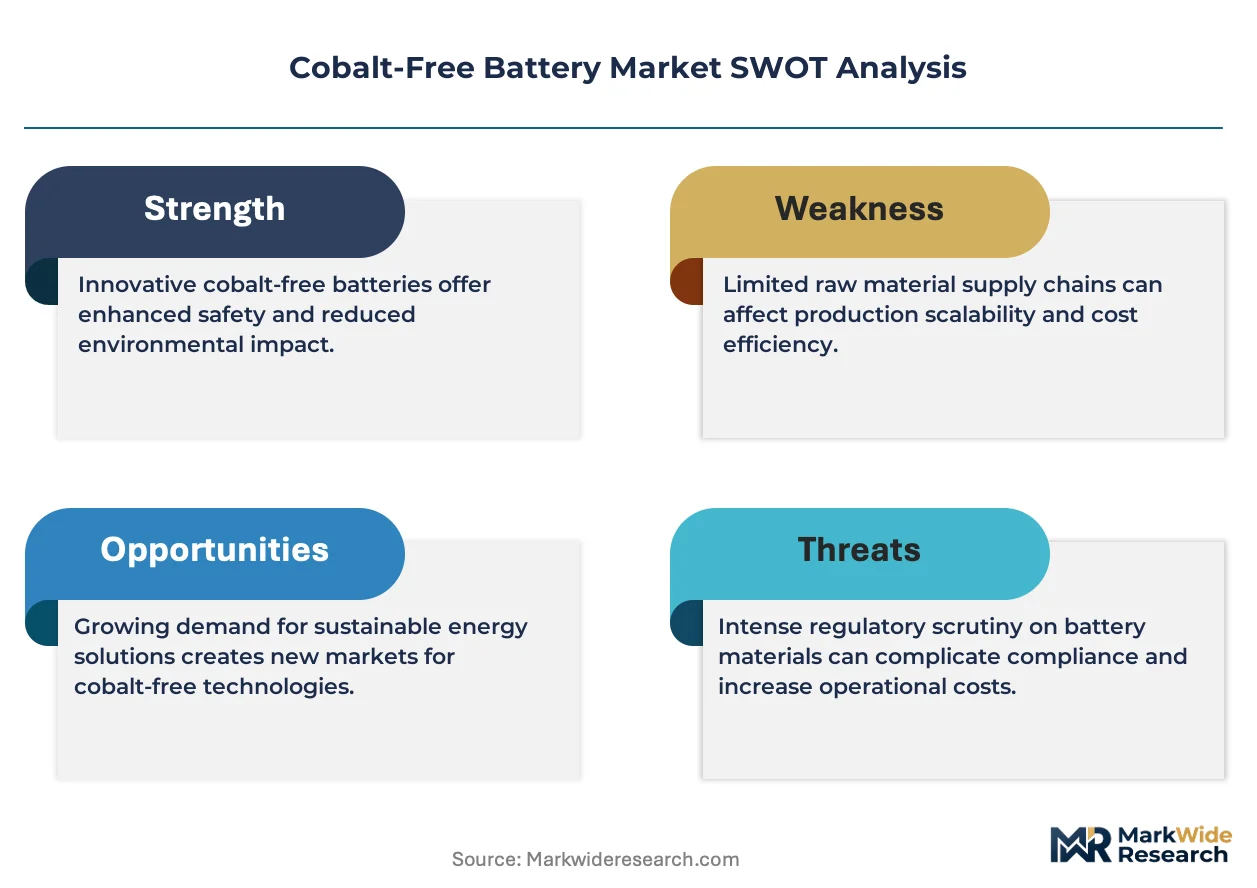
- Nickel price volatility:High-nickel cobalt-free cathodes remain exposed to London Metal Exchange price swings that compress margin buffers for non-integrated producers.
- DRC supply concentration:Cobalt's geological concentration in Central African copperbelt operations sustains ethical sourcing risks that stain brand equity regardless of technical substitution.
- Gravimetric density ceiling:Lithium iron phosphate cells hit 160-180 Wh/kg practical limits, constraining range extension in premium electric vehicle segments where nickel-cobalt-aluminum still dominates.
Strategic Opportunities
- Stationary storage deployment:Grid-scale battery installations are absorbing sodium-ion and lithium iron phosphate output where energy density requirements relax and cycle life premiums command pricing power.
- US IRA production credits:North American assembly and critical mineral sourcing thresholds are redirecting capital toward domestic cathode precursor and cell manufacturing investments.
- Entry-level electric vehicle segments:Cost-optimized urban mobility platforms in Southeast Asia and Latin America are specifying cobalt-free chemistries to hit sub-$25,000 price points.
Industry Challenges
- Electrolyte formulation expertise:High-voltage nickel-manganese cathodes require proprietary electrolyte additives that remain concentrated among Japanese and South Korean chemical suppliers.
- Cell-to-pack thermal management:Cobalt-free architectures demand redesigned cooling architectures that extend engineering validation timelines by 12-18 months versus conventional module-based systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt-Free Battery Market |
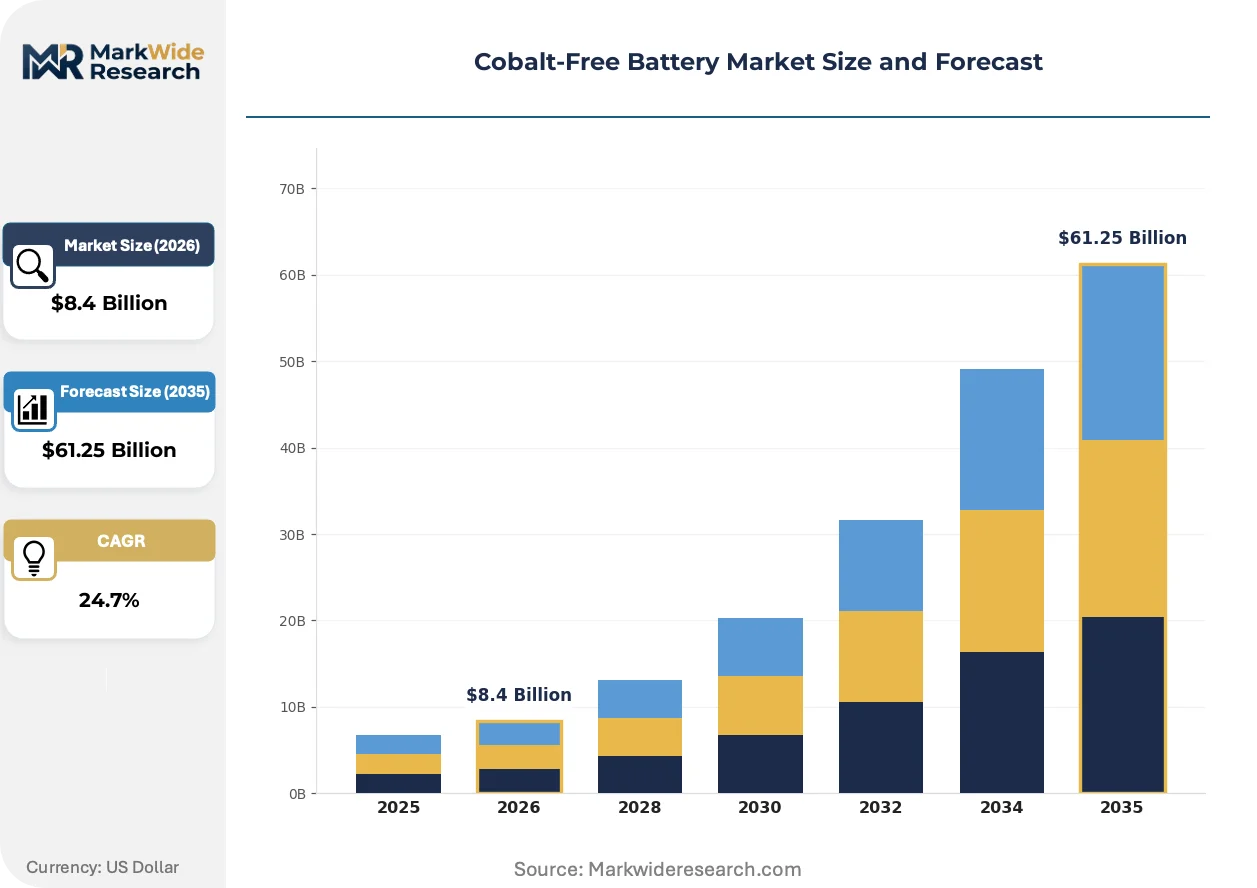
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $61.25 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Iron Phosphate, Nickel Manganese, Sodium-Ion, Solid-State Technology: Rechargeable, Thin-Film, Flow, Ultracapacitor End User: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Industrial Applications Form Factor: Prismatic, Cylindrical, Pouch, Modular |
| Companies Covered | Conamix, Lithium Werks, SVOLT, SPARKZ, CATL, Cobra, BYD, AESC, CALB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt-Free Battery Market Strategic Shifts
Cathode chemistry roadmaps are diverging across automotive OEMs as energy density targets, thermal stability requirements, and supply chain audit standards harden into procurement specifications.
High-nickel manganese cobalt-free formulations are decomposing the historical trade-off between volumetric energy density and ethical material sourcing. European premium automakers are qualifying these chemistries for 800-volt architectures with sub-20-minute fast-charge capability. The technology is decomposing incumbent nickel-cobalt-aluminum market share in the 300-mile-range vehicle segment.
China's SAMR enforcement of revised GB standards on cell safety testing and labeling is filtering market access for imported and domestic producers. The regulations mandate nail penetration, overcharge, and thermal runaway propagation tests that favor prismatic cell formats with ceramic-coated separators. European cell producers are responding by redesigning pilot lines to GB-compliant specifications before commercial scale-up.
Fleet operators are consolidating cell procurement around certified cobalt-free supply chains with blockchain-tracked material provenance. Leasing companies and municipal transit authorities are displacing spot-market purchasing with decade-long service agreements that bundle cell supply, second-life repurposing, and recycling commitments. This pattern is most visible in Nordic markets where public procurement rules embed supply chain transparency scoring.
Cobalt-Free Battery Market Segmentation
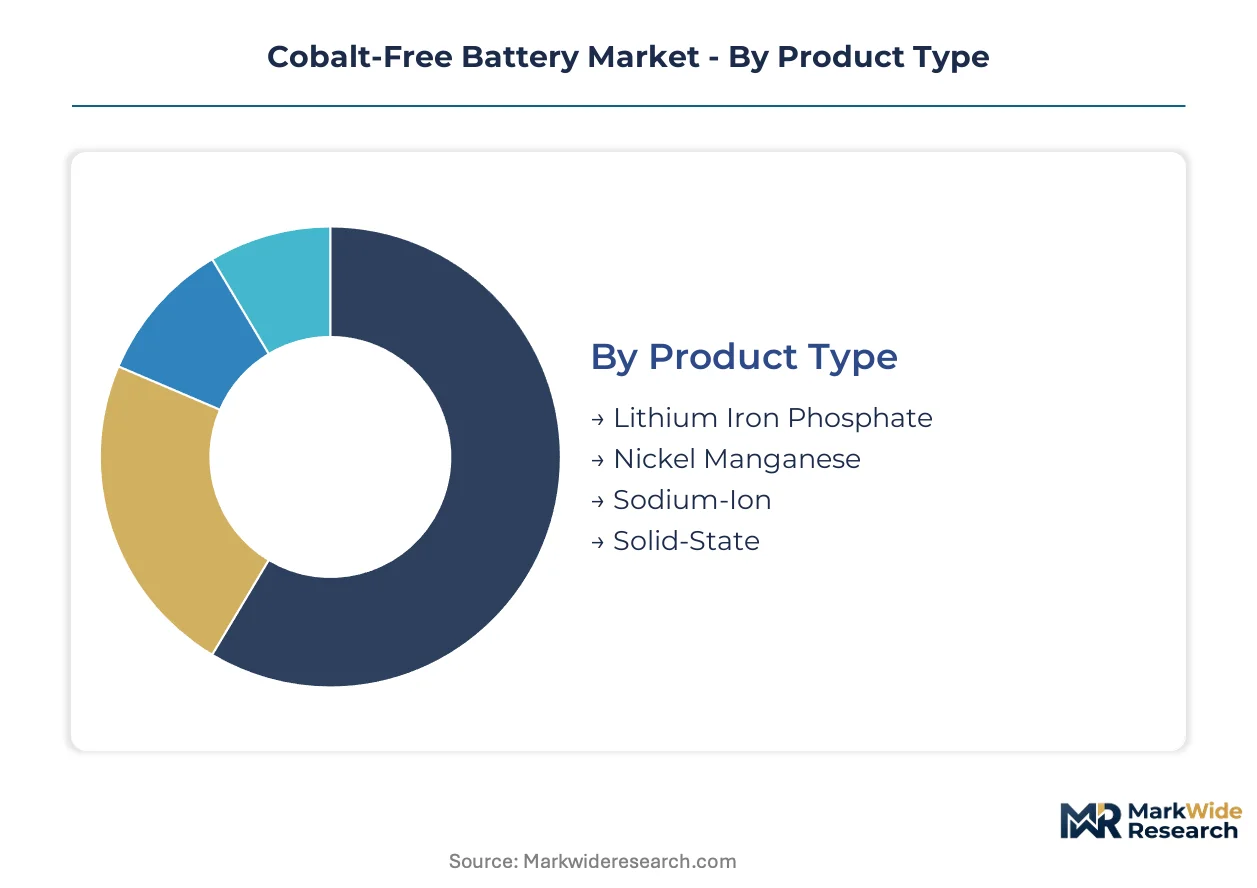
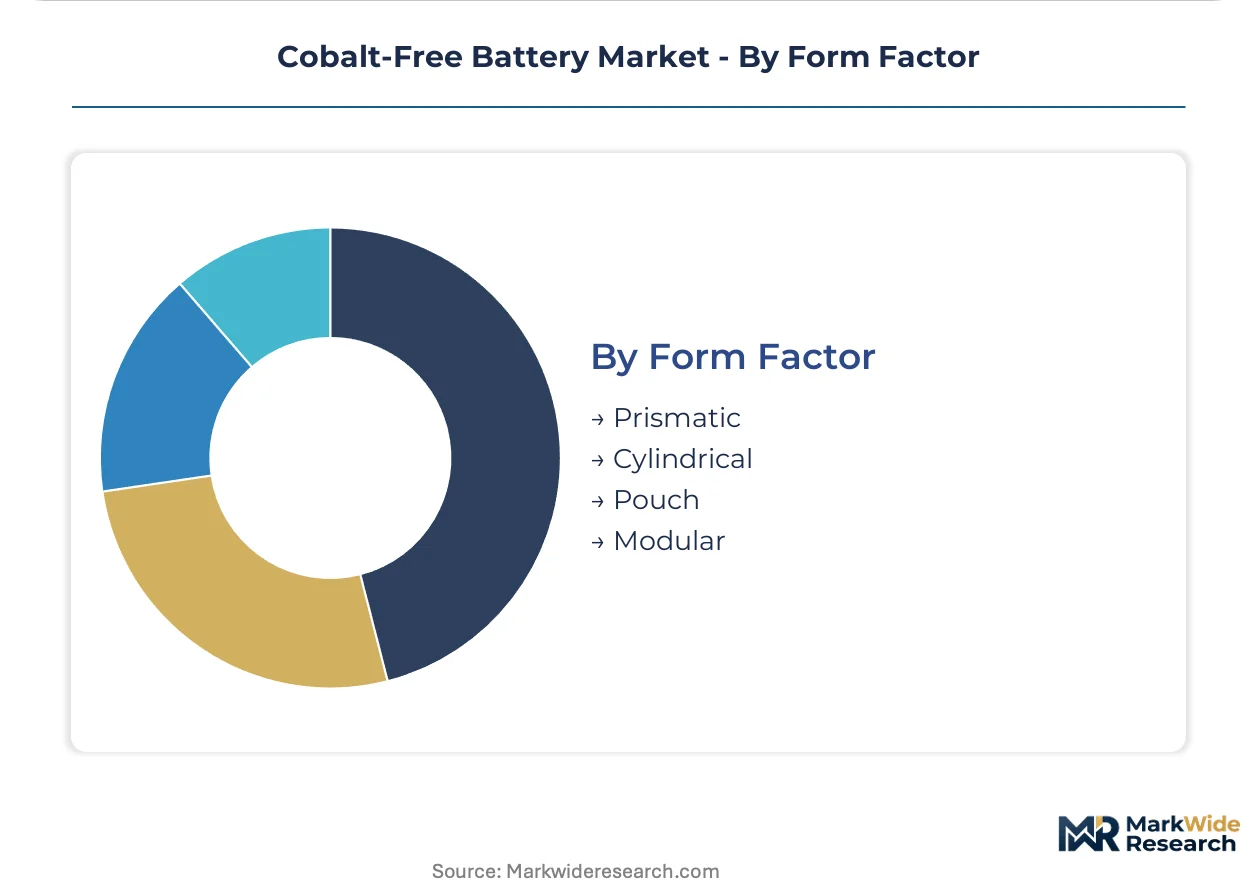
Cobalt-free battery architectures diverge sharply across chemistry classes and form factors, with procurement channels sorting by thermal stability requirements, energy density thresholds, and integration complexity. Cell manufacturers route distinct product streams through automotive OEM direct contracts, industrial system integrators, and consumer electronics distributors based on validation timelines and volume commitments.
Product Type:
Channel flows split between automotive OEM direct procurement for high-volume chemistries and industrial integrators for emerging variants, with certification requirements determining route-to-market economics.
- Lithium Iron Phosphate:Dominant cobalt-free chemistry operating at 3.2V nominal with olivine crystal structure delivering 3,000+ cycle life. Demand concentrates in Chinese electric vehicle production where CATL and BYD supply directly to domestic automakers, constrained by 160-180 Wh/kg gravimetric density ceilings that limit premium segment penetration.
- Nickel Manganese:High-voltage layered oxide cathodes achieving 200+ Wh/kg without cobalt content. European premium automakers are qualifying these cells for 800-volt platforms, with supply agreements increasingly mandating blockchain-tracked material provenance to satisfy EU Battery Regulation due diligence clauses.
- Sodium-Ion:Emerging chemistry leveraging abundant raw materials for stationary storage and entry-level mobility. Chinese producers are scaling dedicated gigafactories for grid applications where energy density requirements relax.
- Solid-State:Early-stage ceramic or polymer electrolyte architectures promising enhanced safety profiles. Japanese and South Korean material suppliers control proprietary sulfide electrolyte formulations, limiting commercial channel access.
By volume, Lithium Iron Phosphate leads. By growth pace, Nickel Manganese is gaining share fastest.
Technology:
Cost tier stratification separates mature rechargeable formats from premium thin-film and specialized flow architectures, with margin structures determining manufacturing investment priorities.
- Rechargeable:Mature lithium-ion derived architectures dominating commercial production. Prismatic and cylindrical formats flow through automotive OEM direct channels with multi-year offtake agreements, while pouch variants serve consumer electronics distributors.
- Thin-Film:Solid-state derived micro-batteries for medical implants and wearable sensors. Swiss and German precision manufacturers control deposition equipment, restricting supply to specialty industrial integrators.
- Flow:Vanadium and organic redox systems for multi-hour grid storage. Project developers in Germany and Australia are procuring containerized systems through engineering-procurement-construction contractors rather than cell suppliers.
- Ultracapacitor:High-power density devices for regenerative braking and fast-cycling applications. Hybrid configurations with lithium-ion cells are penetrating municipal bus fleets through leasing company procurement frameworks.
Rechargeable formats capture the revenue base. Thin-Film architectures are climbing the fastest as medical device OEMs qualify solid-state micro-cells.
End User:
Application-specific duty cycles dictate channel structure, with automotive requiring direct OEM integration and energy storage flowing through project developers.
- Electric Vehicles:Largest demand sink with cell-to-pack architectures requiring 12-18 month validation cycles. Chinese, German, and US automakers are inserting cobalt-free chemistry clauses into multi-year supply agreements.
- Consumer Electronics:Cylindrical and pouch formats for power tools, laptops, and mobile devices. Distribution runs through electronics manufacturing service providers and retail brand supply chains.
- Renewable Energy Storage:Grid-scale and behind-the-meter installations. Independent power producers and utility procurement departments are consolidating around decade-long service agreements bundling cells, inverters, and recycling.
- Industrial Applications:Forklifts, mining equipment, and marine vessels. Leasing companies and municipal transit authorities in Nordic markets are embedding supply chain transparency scoring into tender specifications.
Electric Vehicles anchor volume procurement. Renewable Energy Storage is expanding most quickly as IRA production credits redirect capital toward North American assembly.
Form Factor:
Manufacturing maturity and thermal management requirements segment production capacity across prismatic dominance and cylindrical specialization.
- Prismatic:Aluminum-cased cells favored by Chinese producers for automotive integration. SAMR GB standards on nail penetration and thermal runaway propagation favor ceramic-coated separators in this format.
- Cylindrical:Standardized 2170 and 4680 formats with established winding equipment supply chains. Tesla and South Korean producers are scaling dedicated lines for high-nickel cobalt-free chemistries.
- Pouch:Flexible polymer-cased cells for consumer electronics and aviation applications. European cell producers are redesigning pilot lines to GB-compliant specifications before commercial scale-up.
- Modular:Pre-integrated rack systems for grid storage. Containerized configurations allow project developers to bypass cell-level procurement complexity.
Prismatic formats lead by installed manufacturing capacity. Cylindrical formats are scaling fastest as 4680 production lines achieve yield targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for cobalt-free batteries tilt heavily toward net-exporting manufacturing bases and net-importing automotive assembly regions, with tariff regimes and production tax credits redirecting trade flows across the 2026-2035 window.
China
Domestic electric vehicle procurement absorbs over 60% of national cobalt-free cell output, with CATL and BYD operating integrated precursor-to-pack facilities in Fujian and Shenzhen. SAMR's revised GB standards on nail penetration and thermal runaway propagation filter market access for both imported and domestic producers. The Yangtze River Delta cluster around Ningbo hosts cathode active material foundries supplying European automakers under multi-year offtake agreements.
Germany
Premium automakers in Stuttgart and Munich are qualifying high-nickel manganese cobalt-free cells for 800-volt architectures, inserting chemistry clauses into supplier contracts. The EU Battery Regulation mandates recycled content minimums and due diligence disclosures that reshape procurement criteria by 2030. The North Rhine-Westphalia corridor around Münster hosts pilot lines redesigned to GB-compliant specifications before commercial scale-up.
United States
The IRA's production tax credits redirect capital toward North American assembly and critical mineral sourcing thresholds, stimulating cathode precursor investments in Nevada and North Carolina. NHTSA safety standards intersect with state-level zero-emission vehicle mandates in California and New York to accelerate fleet electrification. The Midwest manufacturing belt around Detroit is consolidating cell procurement around certified cobalt-free supply chains with blockchain-tracked material provenance.
South Korea
Electrolyte formulation expertise for high-voltage nickel-manganese cathodes remains concentrated among Seoul-based chemical suppliers, creating capability scarcity for non-integrated cell producers. METI-aligned R&D programs in battery safety testing favor ceramic-coated separators in prismatic formats. The Gyeonggi-Seoul corridor hosts joint development agreements between material suppliers and European automotive OEMs targeting 2028 qualification timelines.
Japan
Solid-state electrolyte research programs at METI-funded institutes in Tsukuba and Nagoya are advancing sulfide-based formulations, though commercial channel access remains restricted. Domestic automakers are hedging cobalt-free chemistry bets across lithium iron phosphate partnerships and proprietary high-nickel manganese development. The Kansai industrial zone around Osaka maintains precision winding equipment supply chains for cylindrical cell formats.
Cobalt-Free Battery Market Competitive Environment
Listed leaders compete with private specialists across capital access and strategic flexibility, with public cell manufacturers leveraging equity markets for gigafactory financing while private challengers pivot faster on chemistry transitions. The vendor base sorts into three tiers: integrated Chinese producers with captive mining positions, European specialists targeting premium automotive qualification, and North American ventures scaling behind IRA production credits. Dominant competitive moves include backward integration into cathode precursor production and geographic expansion through joint ventures with regional automotive OEMs.
Within the integrated manufacturing tier, CATL and BYD exemplify archetypes of scale-driven cost leadership, with the former representing public-market capital deployment and the latter illustrating private conglomerate vertical control. SVOLT occupies a position between these models, demonstrating European-Asian dual-base expansion. Among North American ventures, SPARKZ anchors the regional specialist archetype targeting IRA-compliant supply chains. Conamix exemplifies the materials-science pivot archetype, transitioning from research-stage formulations toward commercial qualification.
| Leading Market Players |
|---|
| Conamix |
| Lithium Werks |
| SVOLT |
| SPARKZ |
| CATL |
| Cobra |
| BYD |
| AESC |
| CALB |
| Others |
Value Chain & Pricing Dynamics
Cobalt elimination in cathode formulations is simultaneously redrawing mining economics and procurement premiums, compressing margin buffers for non-integrated producers while rewarding cell makers with captive precursor capacity. Iron and manganese substitution is decoupling battery pricing from London Metal Exchange cobalt volatility, though nickel price swings now transmit directly through high-voltage cobalt-free chemistries.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with automotive procurement teams negotiating multi-year cell supply agreements that bundle volume commitments with second-life recycling clauses. Price differentiation stratifies across certification grade and volume scale, with EU Battery Regulation-compliant supply chains commanding premiums over uncertified alternatives. Cost compression in lithium iron phosphate tiers is intensifying because CATL and BYD are flooding automotive channels with integrated precursor output. Fleet operators and municipal transit authorities exhibit highest price sensitivity, while premium European automakers remain least sensitive due to 800-volt platform performance requirements.
Supply Chain Analysis
China, South Korea, and Japan anchor cathode active material production, with Fujian and Shenzhen hosting integrated precursor-to-pack facilities that feed domestic electric vehicle assembly. The cobalt-free battery supply chain draws from Australian spodumene, Indonesian nickel laterite, and Chinese refined lithium carbonate as primary feedstocks. Single-source vulnerability concentrates in electrolyte additive formulations, where Japanese and South Korean chemical suppliers control proprietary high-voltage additives for nickel-manganese cathodes. Distribution runs through automotive OEM direct channels for high-volume chemistries and industrial system integrators for emerging sodium-ion variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around tier-1 automakers inserting chemistry clauses into multi-year agreements, fragmenting spot-market purchasing as fleet operators and leasing companies consolidate procurement around certified supply chains.
For Market Incumbents: Compound backward integration into cathode precursor production to defend margin buffers against nickel price volatility and emerging Chinese capacity floods. CATL and BYD are compressing unit economics through captive mining positions, forcing European and North American incumbents to secure equivalent upstream control or surrender cost leadership. Prioritize GB-compliant certification investments to maintain market access under China's SAMR enforcement regime. For New Entrants and Emerging Players: Differentiate on electrolyte formulation expertise for high-voltage nickel-manganese architectures, where Japanese and South Korean incumbents currently dominate. Target stationary storage deployment as the most penetrable segment, with grid-scale project developers procuring sodium-ion and lithium iron phosphate output where energy density requirements relax. Pursue joint development agreements with European automotive OEMs to bypass direct competition with integrated Chinese giants. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European cell producers redesigning pilot lines to GB-compliant specifications before commercial scale-up. Long-term viability hinges on IRA-compliant North American assembly footprints and critical mineral sourcing thresholds that redirect capital toward domestic cathode precursor investments. Watch electrolyte additive qualification timelines as the inflection indicator for high-nickel cobalt-free chemistry commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | CATL's captive mining positions compress competitor margins across prismatic cell formats. |
| GB-Compliant Certification Investment | SAMR nail penetration and thermal runaway tests filter market access for European producers. |
| Electrolyte Formulation Partnership | Japanese chemical suppliers control proprietary additives for 800-volt nickel-manganese architectures. |
| IRA-Compliant North American Assembly | Production tax credits redirect capital toward Nevada and North Carolina cathode investments. |
| Blockchain-Tracked Material Provenance | EU Battery Regulation due diligence clauses reshape procurement criteria for Nordic fleet operators. |
Study Parameters
Operator-level perspectives from cell manufacturing executives, automotive procurement leads, cathode material R&D directors, and grid storage project developers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SAMR GB standard filings, EU Battery Regulation compliance databases, SEC 10-K disclosures from listed cell producers, and IEA energy storage deployment statistics. Bottom-up cell production capacity estimates triangulated against top-down electric vehicle production forecasts across the analysis window.
Sensitivity analysis tested nickel price volatility scenarios and IRA credit phase-out assumptions throughout the forecast period. The analytical framework modeled chemistry class, form factor, end-use application, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from production capacity buildout timelines, automotive platform electrification roadmaps, and stationary storage procurement pipelines, with electrolyte additive availability and thermal management validation cycles treated as industry-specific constraint variables.
Material uncertainties — nickel price spikes exceeding historical bands, SAMR enforcement intensity variations, and IRA domestic content threshold adjustments — sit outside the modeled envelope. Forecasts reflect assumptions about cathode chemistry qualification timelines and gigafactory yield ramp trajectories. Recalibration cycles align with material shifts in EU Battery Regulation implementation schedules and Chinese dual carbon policy enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Rechargeable Battery Market
Batteries
Disposable Batteries Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
Lead Carbon Battery Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Battery Swapping Market
Batteries
Low Temperature Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
India Battery Market
Batteries
Battery Simulator Market
Batteries
Custom Battery Pack Market
Batteries
India Alkaline Battery Market
Batteries
Global Bio Compatible Battery Market
Batteries
South America Consumer Battery Market