
 Europe Industrial Battery Market | 2026-2036
Europe Industrial Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Battery Market Foresight
Multi-source cathode procurement is expanding across European industrial battery supply chains as manufacturers reduce dependence on single-origin lithium supplies. Saft Groupe SA leverages its French manufacturing base to anchor premium nickel-based systems for aerospace and defense buyers. Northvolt competes through in-house cathode production in northern Sweden, while Enersys sustains a broad service network spanning forklift and telecom backup applications.
An industrial battery is an electrochemical energy storage device engineered for cyclic deep-discharge operation, typically rated between 2V and 48V per cell with capacities from 50 Ah to several thousand Ah, designed to deliver reliable power in material handling, grid stabilization, and emergency backup roles. Lithium-ion configurations are capturing share in renewable energy storage and data center applications where cycle life and energy density offset upfront cost premiums. Lead acid retains dominance in material handling equipment across warehousing facilities, though sodium nickel chloride systems are gaining traction in cold-climate grid stabilization projects where thermal tolerance matters.
The EU Battery Regulation and REACH framework mandate recycled content thresholds and restricted substance declarations, reshaping how suppliers qualify for public transport operator and manufacturing plant contracts. ECHA classification rules for hazardous materials affect nickel cadmium deployment in mining operations and telecommunication systems. Stakeholders must track how the F-Gas Regulation interacts with battery thermal management designs, as cooling system choices increasingly determine compliance pathways and total cost of ownership for stationary installations.
Market Dynamics
The EU Battery Regulation's carbon footprint disclosure mandates are compressing qualification timelines for industrial cell suppliers, forcing manufacturers to restructure cathode sourcing and recycling partnerships ahead of 2027 enforcement thresholds.
Growth Catalysts
- Data center UPS expansion:German and French operators are scaling lithium-ion backup systems to match hyperscale facility construction, creating sustained procurement volume for high-cycle cells.
- REACH recycled content mandates:The framework's threshold requirements are pulling battery-grade nickel and cobalt back into European manufacturing streams through certified recycling channels.
- Cold-climate grid stabilization:Sodium nickel chloride systems are capturing substation contracts in Nordic markets where thermal tolerance eliminates heating infrastructure costs.
Market Restraints
- Lithium carbonate volatility:Raw material price swings compress margin visibility for system integrators bidding multi-year stationary storage contracts.
- Single-origin cathode dependence:Concentrated refining capacity in non-European jurisdictions exposes supply chains to export restriction risks and qualification delays.
- Lead acid substitution ceiling:Material handling equipment's tolerance for weight and maintenance intervals limits lithium-ion penetration in legacy forklift fleets.
Strategic Opportunities
- Eastern European manufacturing:Poland and Hungary offer underutilized industrial zones for cell assembly plants seeking proximity to German automotive demand clusters.
- Marine electrification:Harbor tugs and inland cargo vessels are emerging as high-margin niches for megawatt-hour scale battery systems with specialized saltwater certifications.
- F-Gas thermal management:Cooling system redesigns around low-global-warming-potential refrigerants create differentiation pathways for stationary storage vendors.
Industry Challenges
- Battery management system integration:Legacy industrial equipment lacks standardized communication protocols, forcing custom engineering for each retrofit deployment.
- Fire safety certification timelines:ECHA's evolving hazardous material classifications delay product approvals for nickel-based systems in underground mining applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Battery Market |
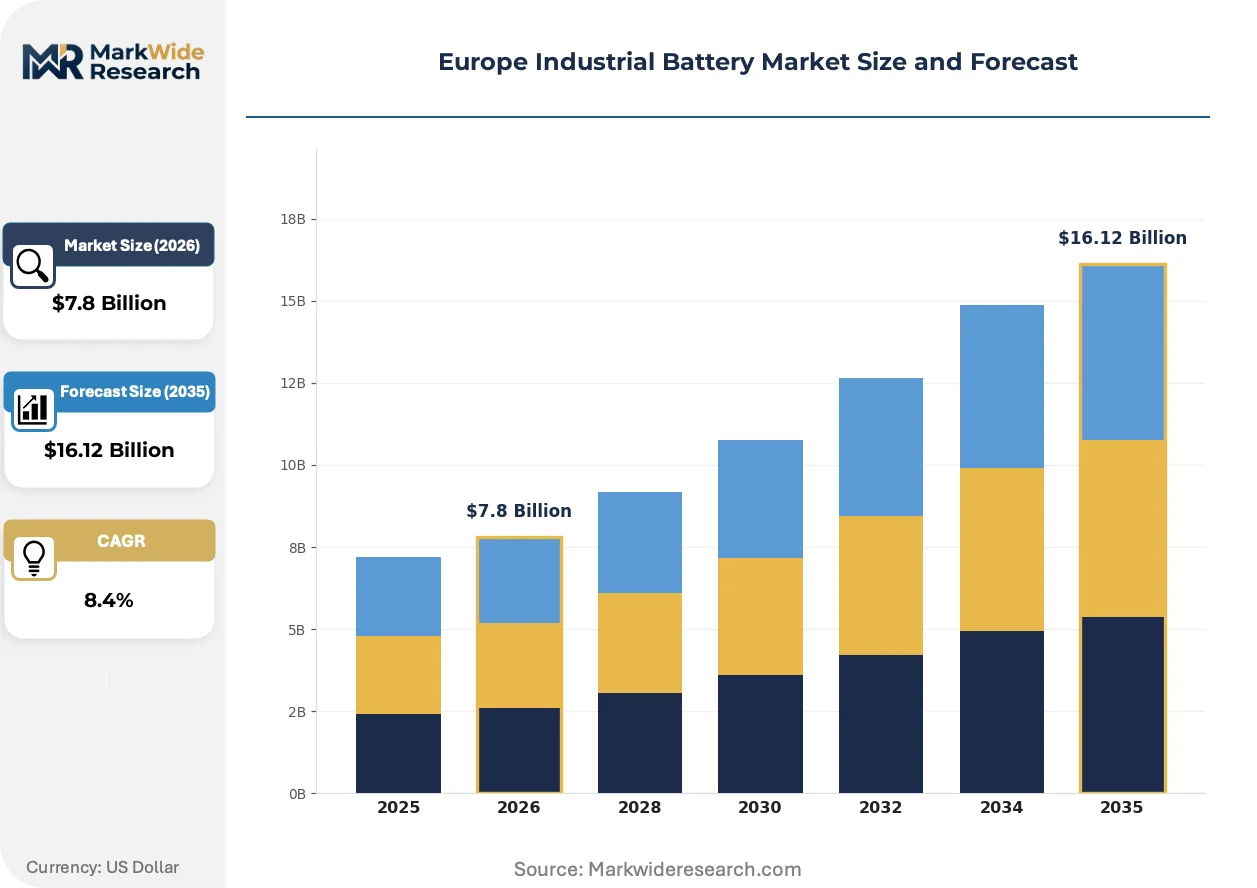
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead Acid, Lithium-ion, Nickel Cadmium, Sodium Nickel Chloride, Flow Batteries Application: Material Handling Equipment, Renewable Energy Storage, Emergency Backup, Telecommunication Systems, Grid Stabilization End User: Manufacturing Plants, Data Centers, Warehousing Facilities, Public Transport Operators, Mining Operations Installation Type: Stationary, Mobile, Fixed Mount, Portable, Rack-mounted |
| Companies Covered | Saft Groupe SA, Exide Industries Ltd, GS Yuasa Corporation, Panasonic Corporation, East Penn Manufacturing Company Inc., Enersys, Robert Bosch GmbH, Northvolt, LG Energy Solution, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Battery Market Shifts & Advancements
Electrochemical storage architectures are fragmenting across voltage classes and duty cycles as end-users reject one-size-fits-all procurement. Three distinct vectors are restructuring competitive positioning.
Solid-state electrolyte research is decentralizing the geographic concentration of high-energy-density cell production. Automotive OEM spin-offs in Germany and France are piloting sulfide-based prototypes for aerospace ground support equipment. These developments are compressing the timeline for liquid electrolyte dominance in premium industrial segments.
REACH substance restrictions are forcing cathode chemistry pivots across European supply chains. The framework's nickel compound classification thresholds are pushing manufacturers toward lithium iron phosphate formulations for material handling applications. Battery-as-a-service providers in Benelux markets are accelerating this shift through lease structures that internalize chemistry transition costs.
Power purchase agreement structures are reshaping how industrial buyers procure storage capacity. Large chemical and automotive plants in Germany's Rhine-Ruhr corridor are bypassing distributors to contract directly with system integrators for 15-year performance guarantees. This disintermediation is squeezing traditional channel margins while rewarding vendors with in-house installation and recycling capabilities.
Europe Industrial Battery Market Segmentation
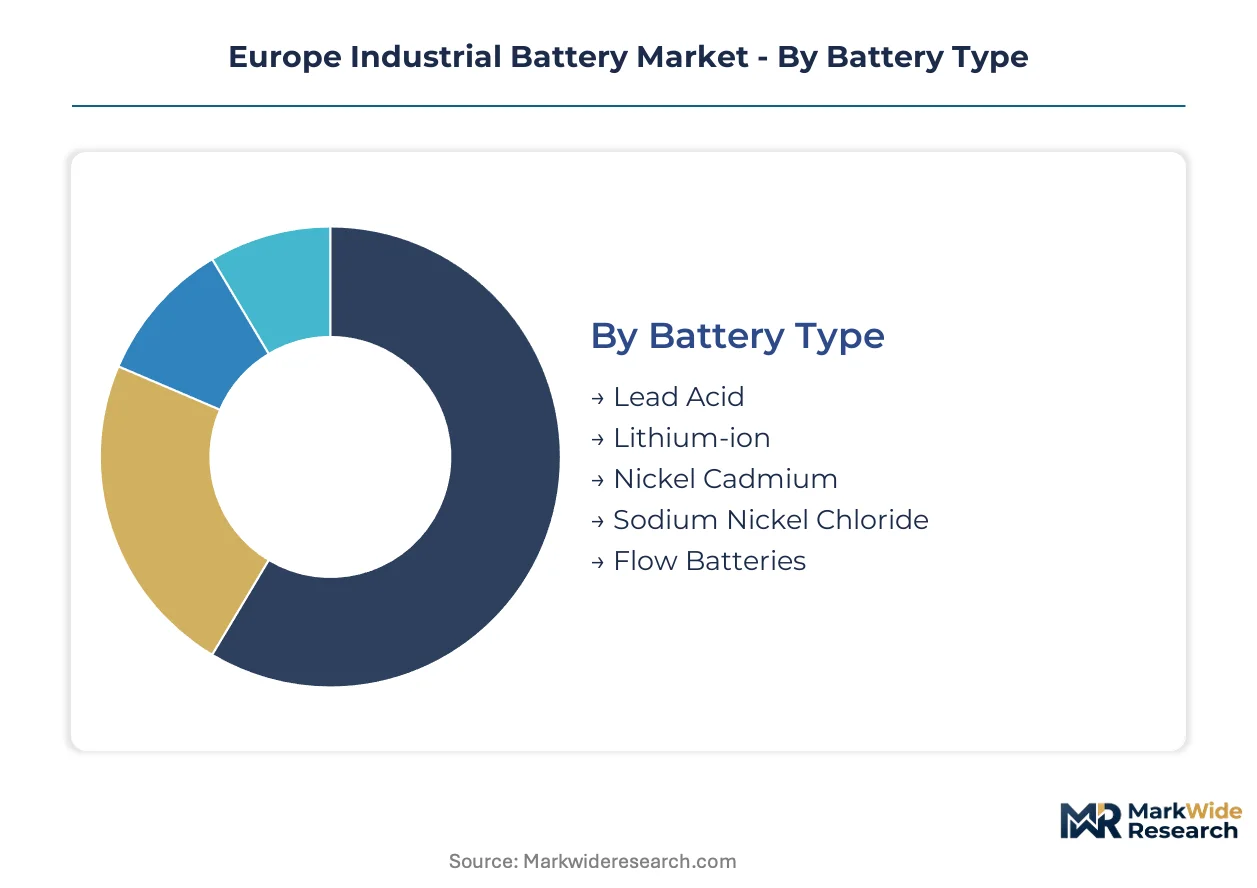
Industrial battery procurement across Europe fragments sharply across chemistry, duty cycle, and installation constraints. Buyers in Germany's automotive corridor and France's data center clusters face divergent specification requirements that reshape supplier qualification pathways.
Battery Type:
Supply concentration for active materials determines competitive positioning across European cell manufacturing.
- Lithium-ion:NMC and LFP formulations dominate renewable energy storage and data center UPS deployments. German chemical plants and French hyperscale facilities are absorbing high-cycle cells despite upfront cost premiums, driven by REACH carbon footprint disclosure mandates compressing supplier timelines.
- Lead Acid:Flooded and VRLA architectures retain cost advantages in material handling equipment across Benelux warehousing networks. Weight tolerance and established maintenance protocols limit substitution pressure from advanced chemistries in legacy forklift fleets.
- Nickel Cadmium:Pocket-plate designs persist in mining operations and emergency lighting where extreme temperature tolerance outweighs cadmium handling restrictions under ECHA classification rules.
- Sodium Nickel Chloride:ZEBRA chemistry eliminates heating infrastructure in Nordic grid stabilization projects. Swedish and Norwegian substation operators are specifying these systems for cold-climate frequency regulation contracts.
- Flow Batteries:Vanadium redox configurations serve multi-hour duration storage for German industrial microgrids seeking to arbitrage day-ahead electricity pricing volatility.
Today's leader: Lead Acid. Tomorrow's challenger: Lithium-ion.
Application:
End-use margins diverge based on certification complexity and contract duration.
- Material Handling Equipment:Electric forklift and automated guided vehicle fleets in German automotive plants require deep-cycle durability under partial state-of-charge operation. Battery-as-a-service providers are capturing maintenance-intensive accounts through chemistry-agnostic lease structures.
- Renewable Energy Storage:Co-located solar and wind projects in Spain and Italy are procuring lithium-ion systems with 15-year performance guarantees. Direct contracting between project developers and system integrators is disintermediating traditional distribution channels.
- Emergency Backup:Hospital and telecommunications installations across France prioritize nickel cadmium for temperature resilience. ECHA substance restrictions are forcing gradual chemistry transitions in public infrastructure tenders.
- Telecommunication Systems:Remote cell tower operators in Eastern Europe favor lead acid for capital constraint compatibility. Extended temperature specifications are emerging as a procurement differentiator for alpine and Mediterranean deployments.
- Grid Stabilization:Transmission system operators in the Nordic region are contracting sodium nickel chloride for frequency containment reserves. Thermal tolerance eliminates auxiliary heating costs in sub-zero operational environments.
Material handling commands current volume. Renewable storage is climbing the fastest.
End User:
Procurement sophistication separates price-sensitive volume buyers from performance-driven premium accounts.
- Data Centers:Hyperscale operators in Frankfurt and Paris are standardizing lithium-ion UPS configurations with 10-minute ride-through capacity. Carbon footprint disclosure requirements under the EU Battery Regulation are filtering supplier pools ahead of enforcement thresholds.
- Manufacturing Plants:Rhine-Ruhr chemical complexes are bypassing distributors for direct system integrator relationships. Fifteen-year performance guarantees and end-of-life recycling commitments are restructuring contract economics.
- Warehousing Facilities:Third-party logistics operators in the Netherlands and Belgium optimize total cost of ownership through multi-shift lead acid fleet rotation. Opportunity charging infrastructure limits lithium-ion penetration in rapid-turnover operations.
- Public Transport Operators:Municipal bus depots across Germany are piloting battery-electric fleet charging with stationary buffer storage. REACH recycled content mandates are pulling battery-grade materials into certified European recycling streams.
- Mining Operations:Underground extraction sites in Poland face ECHA hazardous material classification delays for nickel-based system approvals. Fire safety certification timelines are compressing deployment schedules for electrified equipment.
Data centers anchor premium pricing. Manufacturing plants are expanding most quickly.
Installation Type:
Physical configuration constraints determine thermal management and maintenance access requirements.
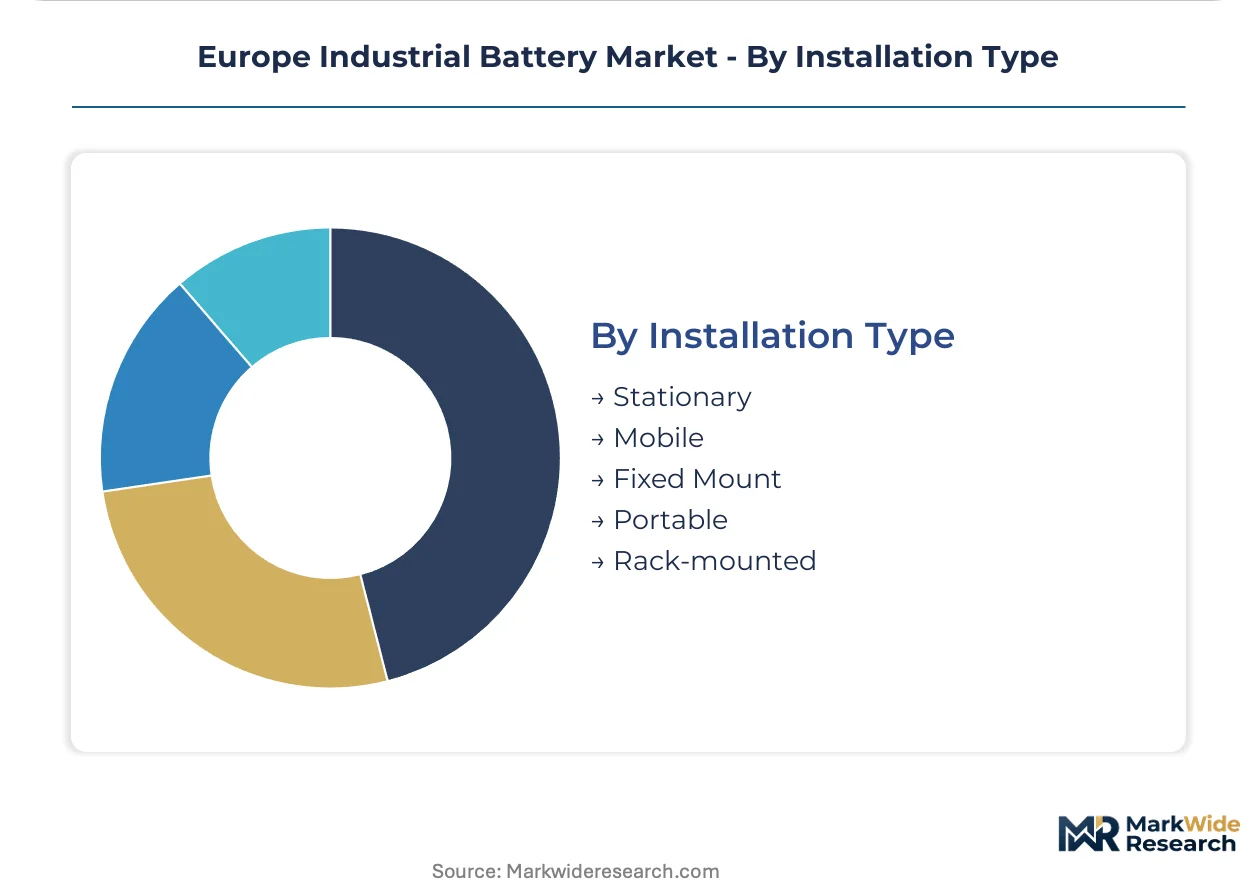
- Stationary:Containerized systems for German industrial microgrids integrate liquid cooling around low-global-warming-potential refrigerants. F-Gas Regulation compliance is driving cooling system redesign differentiation among vendors.
- Rack-mounted:Data center white space deployments in France require front-access servicing and seismic bracing certification. Standardized 19-inch form factors are enabling modular capacity scaling without facility shutdown.
- Mobile:Forklift and ground support equipment applications prioritize rapid connector exchange and spill containment. IP ratings and shock resistance specifications vary across material handling sub-segments.
- Fixed Mount:Telecommunication and emergency lighting installations emphasize vandal resistance and extended temperature operation. Enclosure ratings determine outdoor deployment eligibility without auxiliary shelter.
- Portable:Temporary power for construction and event infrastructure favors lead acid for capital efficiency. Weight and runtime tradeoffs limit lithium-ion penetration in short-duration rental applications.
Stationary systems dominate revenue. Rack-mounted configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as cell producers migrate toward jurisdictions offering streamlined ECHA compliance pathways and proximity to German industrial demand clusters.
Germany
Rhine-Ruhr chemical complexes and Bavarian automotive plants anchor stationary storage procurement for industrial microgrids. REACH carbon footprint disclosure mandates under the EU Battery Regulation are compressing supplier qualification timelines ahead of enforcement thresholds. Stuttgart and Wolfsburg manufacturing corridors are absorbing premium lithium-ion systems for 15-year performance guarantee contracts.
France
Hyperscale data center construction around Paris and Lyon is scaling lithium-ion UPS configurations with 10-minute ride-through capacity. The F-Gas Regulation is driving cooling system redesigns for rack-mounted installations in Ile-de-France white space deployments. Toulouse aerospace clusters sustain demand for nickel-based systems in ground support equipment applications.
Sweden
Nordic frequency containment reserve contracts are pulling sodium nickel chloride systems into substation deployments across Vattenfall and Svenska Kraftnät networks. Cold-climate thermal tolerance eliminates auxiliary heating infrastructure costs in sub-zero operational environments. Northvolt's northern manufacturing base anchors in-house cathode production for regional supply security.
Poland
Eastern European manufacturing zones near Katowice and Wrocław offer underutilized industrial land for cell assembly plants seeking proximity to German automotive demand. Underground mining operations in Silesia face ECHA hazardous material classification delays for nickel-based system approvals. Fire safety certification timelines are compressing deployment schedules for electrified extraction equipment.
Netherlands
Rotterdam and Antwerp warehousing corridors optimize total cost of ownership through multi-shift lead acid fleet rotation in third-party logistics operations. Battery-as-a-service providers are capturing maintenance-intensive accounts through chemistry-agnostic lease structures. REACH recycled content mandates are pulling battery-grade nickel and cobalt into certified European recycling streams.
Europe Industrial Battery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated manufacturing and chemistry specialization vectors. The vendor base stratifies across legacy lead acid fabricators, lithium-ion scale players, and regional champions with captive raw material access. Three archetypes dominate: chemistry-agnostic service networks, vertically integrated cell producers, and niche specialists in temperature-extreme applications. Capacity expansion and strategic recycling partnerships constitute the dominant competitive moves as qualification timelines compress.
Within the integrated manufacturing tier, Northvolt exemplifies the regional champion archetype through its Swedish production base. Saft Groupe SA occupies a position among chemistry specialists with French manufacturing heritage. Enersys represents the service-network archetype, anchoring broad geographic coverage across maintenance-intensive industrial accounts. These three entities collectively illustrate how competitive positioning fragments across manufacturing scale, chemistry focus, and service infrastructure depth.
| Leading Market Players |
|---|
| Saft Groupe SA |
| Exide Industries Ltd |
| GS Yuasa Corporation |
| Panasonic Corporation |
| East Penn Manufacturing Company Inc. |
| Enersys |
| Robert Bosch GmbH |
| Northvolt |
| LG Energy Solution |
| Others |
Supply & Pricing Matrix
REACH carbon footprint disclosure mandates under the EU Battery Regulation are forcing cathode chemistry pivots that compress supplier margins and restructure procurement economics across German and French industrial clusters.
Pricing Analysis
Input-cost pass-through from lithium carbonate volatility feeds directly into multi-year stationary storage contract bidding, squeezing system integrator visibility. Pricing stratifies across premium, standard, and economy tiers based on cycle life certification and after-sales service bundling. Cost compression in standard-tier lithium-ion systems is intensifying because of cathode material spot market swings. Third-party logistics operators in Benelux warehousing corridors exhibit highest price sensitivity, while Rhine-Ruhr chemical plants prioritize performance guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with concentrated lithium refining capacity in China, South Korea, and Japan, exposing European cell assemblers to export restriction risks. Active material procurement draws from Chilean lithium brine, Indonesian nickel laterite, and DRC cobalt hydroxide. Regulatory restriction risk compounds through ECHA substance classification delays for nickel-based chemistries. Distribution runs through certified recycling channels that feed battery-grade nickel and cobalt back into European manufacturing streams under REACH mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where carbon disclosure requirements and 15-year performance guarantees are filtering procurement toward premium-tier suppliers with integrated recycling capabilities.
For Market Incumbents: Acquire in-house cathode production assets to reduce single-origin dependence and defend against Northvolt's regional champion model. Anchor backward integration into Nordic refining partnerships to secure qualified material streams ahead of EU Battery Regulation enforcement. Invest in F-Gas-compliant thermal management R&D to differentiate containerized stationary systems. For New Entrants and Emerging Players: Marine electrification buyers for harbor tugs and inland cargo vessels represent an underserved buyer archetype with specialized saltwater certification requirements and limited incumbent focus. Polish and Hungarian manufacturing zones offer geographic white space for cell assembly plants proximate to German automotive demand. Pursue battery-as-a-service lease structures that internalize chemistry transition costs for maintenance-intensive material handling accounts. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap specialists with captive raw material access and ECHA pre-qualification status. Five-to-ten-year viability favors entities with certified recycling partnerships and direct system integrator relationships bypassing traditional distribution. Watch sodium nickel chloride substation contract awards in Nordic markets as inflection signal for cold-climate chemistry adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Production | Northvolt's Swedish manufacturing base reduces dependence on Asian refining capacity under REACH carbon disclosure rules. |
| Certified Recycling Partnership | Benelux battery-as-a-service providers capture maintenance-intensive accounts through chemistry-agnostic lease structures. |
| F-Gas Thermal Management Redesign | German industrial microgrid vendors differentiate containerized systems through low-global-warming-potential refrigerant compliance. |
| Direct System Integrator Contracting | Rhine-Ruhr chemical plants bypass distributors for 15-year performance guarantees with end-of-life recycling commitments. |
| Marine Electrification Certification | Specialized saltwater-rated systems for harbor tugs command premium pricing in an underpenetrated niche. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and procurement leads at German automotive OEMs, secondary validation through ECHA regulatory filings and EU trade data, and technical specification reviews — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included maintenance directors at Benelux warehousing operators, EPC contractors for Nordic grid stabilization projects, and aftermarket service heads at forklift fleet managers. Secondary sources comprised REACH substance restriction updates, F-Gas Regulation compliance databases, and customs records for lithium compound imports.
Historical capacity deployment patterns were cross-referenced against panel input from system integrators and cathode material suppliers to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include battery chemistry tier, application duty cycle, installation type, and end-user procurement sophistication. CAGRs were derived from demand elasticity analysis for data center UPS and material handling equipment replacement cycles, with inputs from carbon footprint disclosure timeline assumptions and recycling infrastructure buildout schedules.
Underlying measurement precision varies by segment; lithium-ion renewable storage and data center applications carry tighter precision than emerging sodium nickel chloride deployments. Forecasts reflect documented assumptions regarding EU Battery Regulation enforcement thresholds and raw material price normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Industrial Backup Battery Market
Batteries
Battery Simulator Market
Batteries
Molten Salt Battery Market
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Global Industrial Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
South America Consumer Battery Market
Batteries
Industrial Battery Charger Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Romania Rechargeable Battery Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Solid Electrolyte Market
Batteries
Myanmar Battery Market
Batteries
Battery-Powered Riveter Market