
 Global Lightning Arrester Market | 2026-2036
Global Lightning Arrester Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lightning Arrester Market Outlook
Utility procurement channels is narrowing as state-owned grid operators consolidate vendor lists and favor suppliers with proven track records across multiple voltage classes. ABB leverages its installed base in high-voltage substations to sustain recurring replacement demand. Siemens anchors its position through integrated digital monitoring packages bundled with arrester hardware. Eaton competes aggressively on medium-voltage distribution contracts where lifecycle cost metrics dominate purchasing decisions.
A lightning arrester is a protective device designed to intercept and divert high-voltage surge currents to ground, typically incorporating metal oxide varistor blocks that exhibit highly non-linear voltage-current characteristics to clamp transient overvoltages within milliseconds. Its primary purpose is safeguarding transformers, switchgear, and transmission lines from lightning-induced insulation failure. Metal oxide varistor technology dominates installed capacity due to superior energy absorption and faster response times compared to legacy silicon carbide designs. Outdoor installation types command the largest revenue pool given exposure severity, though indoor configurations for data centers and industrial substations represent the fastest-growing application cluster.
IEC 60099-4, IEEE C62.11, and national variants enforced by BIS in India and GB standards in China govern arrester classification, testing protocols, and certification requirements for grid interconnection. These frameworks compel manufacturers to maintain parallel product portfolios and testing capabilities across regulatory jurisdictions. Stakeholders must monitor evolving coordination between renewable interconnection standards and surge protection mandates as distributed generation reshapes fault current profiles.
Market Dynamics
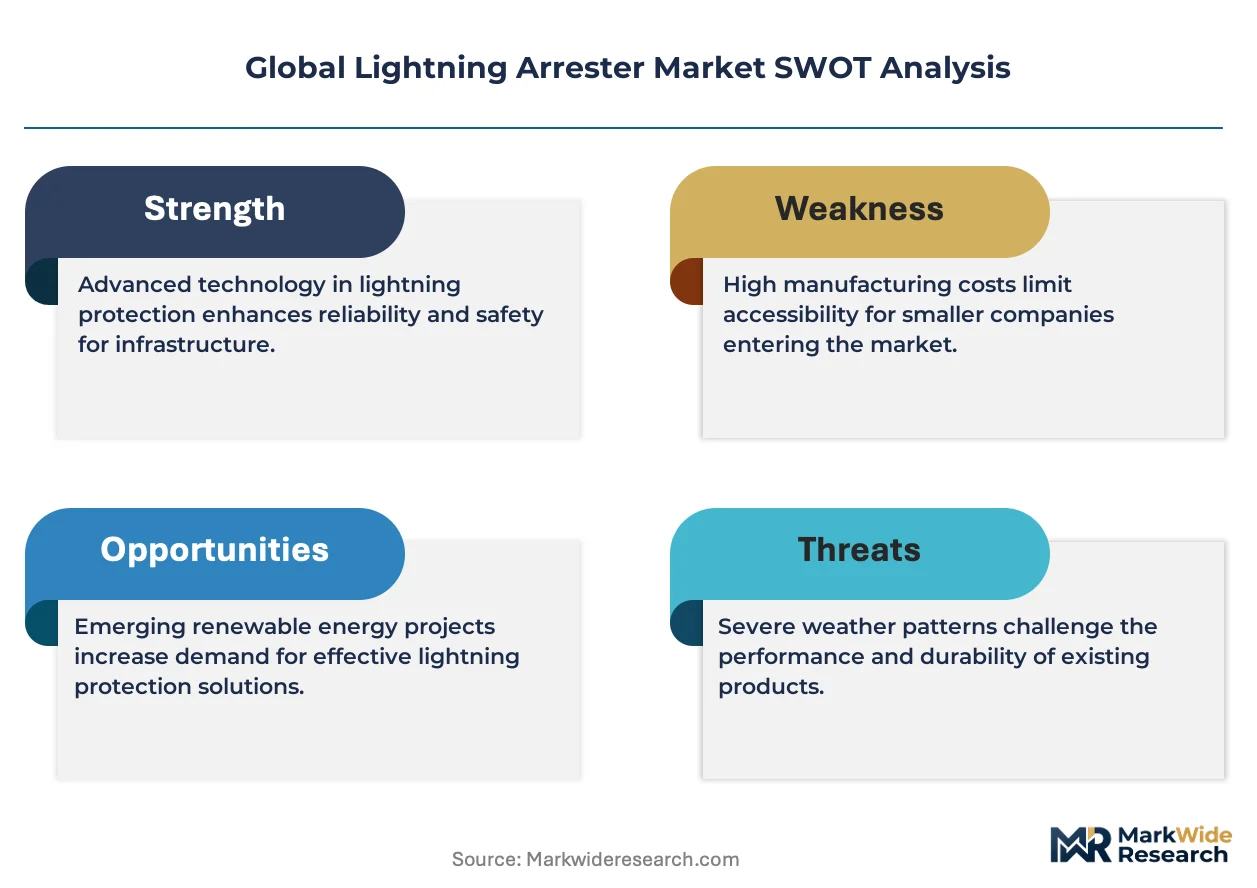
Grid modernization mandates and renewable interconnection requirements are compressing procurement cycles for surge protection equipment, forcing arrester manufacturers to align product roadmaps with evolving fault current profiles from distributed solar and wind assets.
Growth Catalysts
- Rural electrification in India:The country's village electrification programs and renewable integration projects are multiplying procurement volumes for medium-voltage distribution arresters.
- IEC 60099-4 tightening:Revised testing protocols for metal oxide varistor blocks are mandating replacement cycles across European transmission networks.
- Data center buildouts:Hyperscale facilities in Singapore, Ireland, and Virginia are driving demand for indoor surge protection configurations with faster response thresholds.
Market Restraints
- Zinc oxide price volatility:Primary varistor material costs fluctuate with mining output from Peruvian and Australian concentrate suppliers, squeezing margin predictability.
- Consolidated utility procurement:State-owned grid operators in Brazil and South Africa are narrowing vendor lists to three approved suppliers per voltage class.
- Silicon carbide legacy inertia:Aging substations in Eastern Europe and Central Asia delay conversion to metal oxide technology due to incompatible housing standards.
Strategic Opportunities
- Offshore wind surge protection:North Sea and East Asian floating turbine projects require marine-grade arresters with enhanced salt-fog resistance.
- Digital monitoring convergence:Integration of IoT sensors with varistor hardware creates recurring revenue streams through predictive maintenance subscriptions.
- US Inflation Reduction Act:Domestic content bonuses for grid infrastructure are incentivizing local assembly of transmission-class arresters.
Industry Challenges
- High-voltage testing facility scarcity:Only five laboratories worldwide can certify 800kV+ arresters, creating bottlenecks for new product introductions.
- Legacy system integration:Substations with electromechanical relay protection require protocol bridges to communicate with smart arrester monitoring units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lightning Arrester Market |
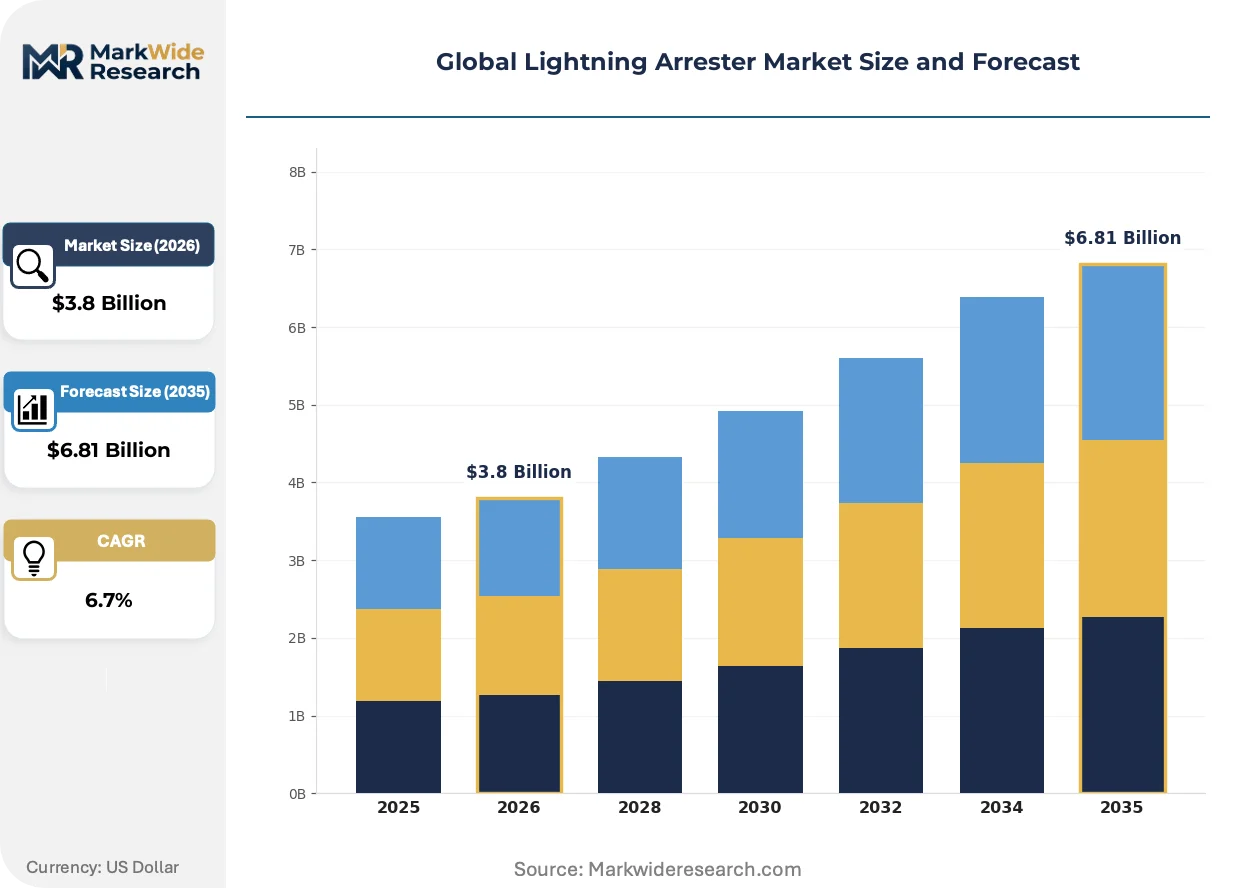
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
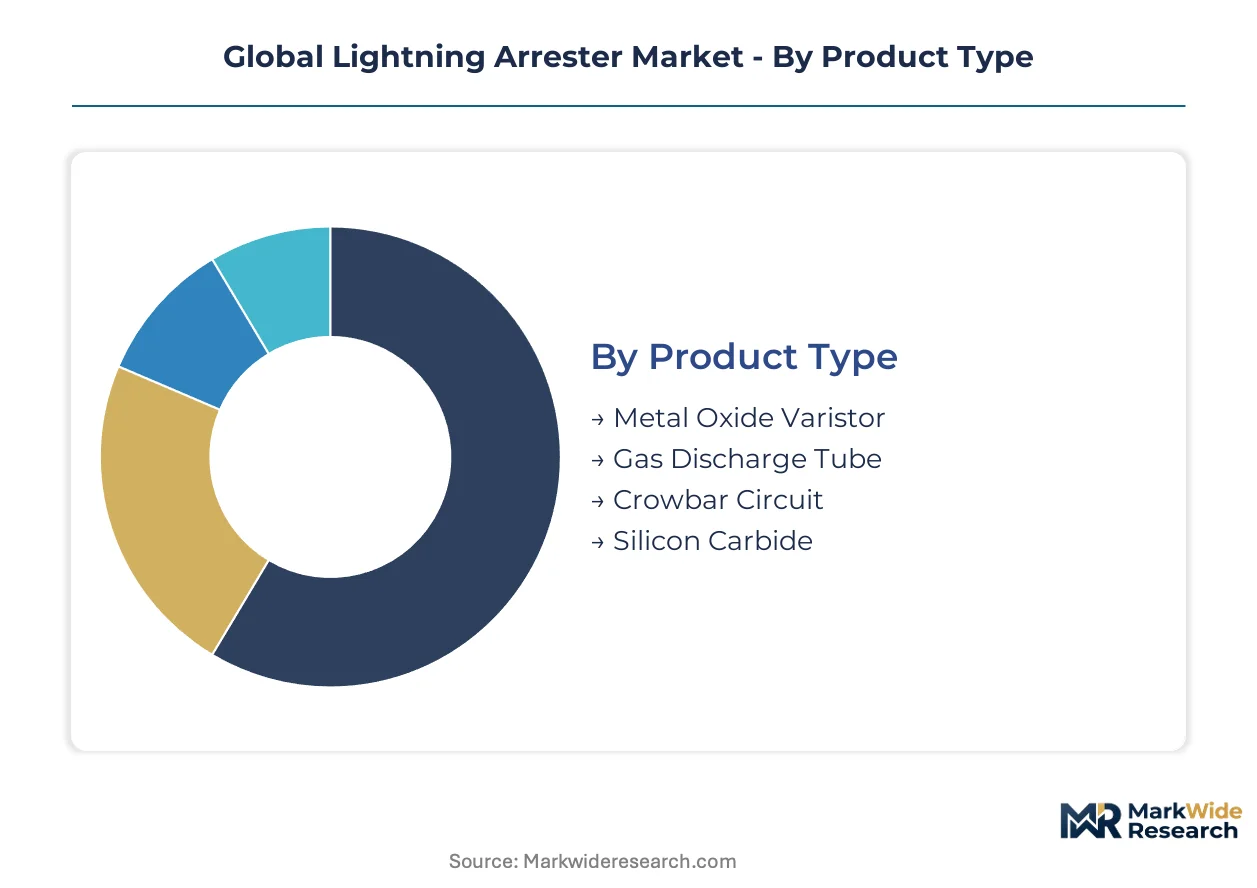
| Segmentation | Product Type: Metal Oxide Varistor, Gas Discharge Tube, Crowbar Circuit, Silicon Carbide End User: Utilities, Transportation, Commercial, Industrial Installation Type: Overhead, Underground, Indoor, Outdoor Application: Telecommunications, Renewable Energy, Power Generation, Distribution |
| Companies Covered | ABB, Siemens, Hubbell, Eaton, Toshiba Corporation, GE, Schneider Electric, Tridelta Meidensha GmbH, Shreem Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lightning Arrester Market Strategic Shifts
Real-time condition monitoring and predictive analytics are embedding intelligence directly into protective hardware, transforming arresters from passive components into data-generating grid assets that enable condition-based maintenance scheduling.
Self-powered wireless sensor modules attached to metal oxide varistor stacks are digitizing failure prediction by continuously measuring leakage current and temperature gradients. Transmission operators in Germany and Japan are deploying these units at 400kV+ substations to eliminate manual inspection rounds. The technology is compressing maintenance intervals from calendar-based to condition-triggered, reducing unplanned outages.
REACH restrictions on hazardous substances are compelling reformulation of polymer housing compounds for European market access. Manufacturers are accelerating validation of silicone rubber alternatives to EPDM for pollution-resistant outdoor installations. The regulatory pressure is elevating certification costs but creating product differentiation for compliant suppliers.
Lifecycle cost modeling now dominates utility tender evaluations, displacing upfront price as the primary award criterion. Procurement teams in India and Saudi Arabia are bundling arrester replacement schedules with transformer maintenance contracts. The shift favors vendors with integrated service capabilities and penalizes pure hardware suppliers lacking field engineering networks.
Global Lightning Arrester Market Segmentation
Lightning arrester procurement patterns diverge sharply across voltage classes, installation environments, and end-use sectors. Each segmentation dimension reveals distinct performance requirements, certification burdens, and supplier competitive dynamics that shape vendor positioning.
Product Type:
Technology selection hinges on energy absorption capacity, response speed thresholds, and legacy infrastructure compatibility across transmission and distribution networks.
- Metal Oxide Varistor:Zinc oxide ceramic discs exhibit highly non-linear voltage-current characteristics, clamping surges within nanoseconds without spark gaps. Indian utilities under CEA mandates are replacing silicon carbide units in rural electrification corridors, compressing replacement cycles.
- Gas Discharge Tube:Hermetically sealed noble gas chambers ionize under overvoltage conditions, handling extremely high surge currents with minimal capacitance. Telecommunications infrastructure in Germany and Japan deploys these for coaxial and DSL protection where signal integrity preservation matters.
- Crowbar Circuit:Thyristor-based shunt devices short-circuit excessive voltage to ground. Industrial motor drives in US manufacturing clusters specify these for coordinated protection with variable frequency drives.
- Silicon Carbide:Legacy spark-gap technology with linear resistance characteristics requires series gaps for voltage grading. Aging substations in Eastern Europe retain these due to incompatible housing dimensions with metal oxide replacements.
The dominant share belongs to Metal Oxide Varistor, while Gas Discharge Tube is closing the gap fastest in telecommunications and data center applications.
End User:
Procurement sophistication varies from centralized utility tenders to fragmented industrial maintenance budgets.
- Utilities:State-owned grid operators in India and Brazil consolidate vendor lists to three approved suppliers per voltage class, favoring integrated digital monitoring packages. IEC 60099-4 compliance is non-negotiable for interconnection approval.
- Industrial:Petrochemical complexes and steel mills prioritize lifecycle cost modeling over upfront price, bundling arrester replacement with transformer maintenance contracts. REACH restrictions on polymer housings elevate European certification costs.
- Transportation:Railway electrification systems and airport ground power units require compact, vibration-resistant configurations. Metro projects in Saudi Arabia specify marine-grade salt-fog resistance for coastal installations.
- Commercial:Data center operators in Singapore, Ireland, and Virginia demand indoor surge protection with sub-microsecond response thresholds. Hyperscale facilities drive specification tightening for server rack protection.
Utilities command the largest procurement volumes, though Industrial end users are expanding most quickly through predictive maintenance subscription models.
Installation Type:
Environmental exposure severity dictates housing material selection, pollution resistance grading, and accessibility for inspection protocols.
- Outdoor:Silicone rubber or EPDM polymer housings withstand UV degradation, salt fog, and industrial pollution. Offshore wind projects in the North Sea specify enhanced marine-grade coatings for floating turbine platforms.
- Indoor:Compact designs for switchgear enclosures and data centers prioritize arc containment and minimal footprint. Singapore hyperscale facilities are driving demand for smart arresters with embedded IoT sensors.
- Overhead:Transmission line arresters mount directly on towers or cross-arms, requiring mechanical strength for conductor tension loads. German operators deploy self-powered wireless monitoring modules at 400kV+ substations.
- Underground:Cable termination arresters for urban distribution networks face thermal management challenges in confined vaults. Tokyo and Seoul metro grids specify these for space-constrained underground substations.
Outdoor configurations generate the largest revenue pool, while Indoor installations are gaining share fastest through data center buildouts.
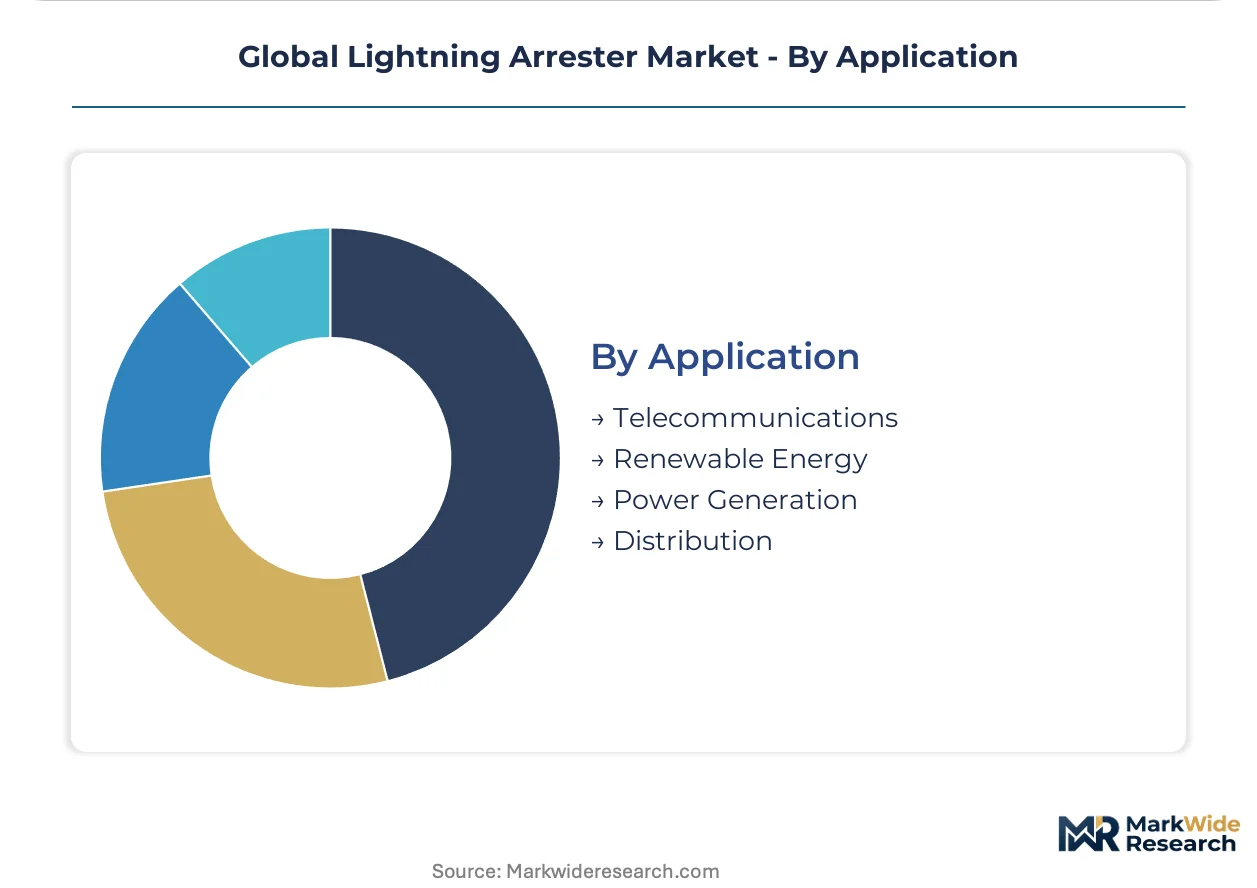
Application:
Fault current profiles and surge magnitude expectations vary dramatically across grid infrastructure layers.
- Power Generation:Generator step-up transformers and switchyard equipment face direct lightning exposure. Only five laboratories worldwide can certify 800kV+ arresters, creating bottlenecks for new product introductions.
- Distribution:Medium-voltage feeders serving rural electrification programs in India multiply procurement volumes. Eaton competes aggressively here on lifecycle cost metrics.
- Renewable Energy:Solar inverters and wind turbine transformers experience switching surges from power electronic converters. US Inflation Reduction Act domestic content bonuses incentivize local assembly for transmission-class units.
- Telecommunications:Base station power feeds and fiber optic terminal equipment require low-capacitance protection. 5G rollouts in South Korea and Japan are accelerating specification updates.
Power Generation retains the dominant installed base, though Renewable Energy is climbing the fastest as distributed generation reshapes protection coordination requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian utilities extract pricing leverage from volume consolidation, while German transmission operators absorb premium costs for digital-monitoring compliance. This asymmetry shapes vendor strategies across procurement cycles.
India
Rural electrification corridors and renewable integration projects multiply procurement volumes for medium-voltage distribution arresters. CEA mandates under BIS certification frameworks compel replacement of legacy silicon carbide units. Gujarat and Maharashtra host concentrated manufacturing clusters where state-owned discoms consolidate vendor lists to three approved suppliers per voltage class.
Germany
Transmission operators at 400kV+ substations deploy self-powered wireless monitoring modules to eliminate manual inspection rounds. REACH restrictions on EPDM polymer housings force reformulation of silicone rubber alternatives for pollution-resistant outdoor installations. The Ruhr industrial zone anchors predictive maintenance subscription pilots bundling arrester replacement with transformer service contracts.
United States
Hyperscale data centers in Virginia and Texas drive demand for indoor surge protection with sub-microsecond response thresholds. FERC interconnection standards and IRA domestic content bonuses incentivize local assembly of transmission-class units. The Southeast manufacturing belt concentrates marine-grade arrester production for offshore wind platforms in the Atlantic.
China
GB standards enforcement and dual carbon goals accelerate grid modernization procurement cycles. State Grid Corporation consolidates vendor qualification to compress supplier bases across 800kV+ certification requirements. The Yangtze River Delta clusters high-voltage testing facilities serving domestic and export certification demands.
Saudi Arabia
Metro electrification systems and coastal renewable projects specify marine-grade salt-fog resistance for outdoor installations. SFDA-equivalent industrial safety frameworks align with IEC 60099-4 for grid interconnection approval. Riyadh and the Eastern Province concentrate procurement for integrated digital monitoring packages bundled with arrester hardware.
Global Lightning Arrester Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying varistor blocks and polymer housings. The vendor base organizes around three strategic archetypes: diversified electrical conglomerates with substation installed bases, pure-play surge protection specialists with testing facility access, and regional fabricators serving consolidated utility procurement channels. Dominant competitive moves include backward integration into zinc oxide ceramic production and technology licensing partnerships for wireless monitoring modules.
Among diversified electrical conglomerates, ABB and Siemens occupy positions anchored by high-voltage substation track records and integrated digital service portfolios. Eaton exemplifies aggressive positioning on medium-voltage distribution contracts where lifecycle cost metrics dominate purchasing decisions. These three represent distinct archetypes: installed-base leverage, bundled digital hardware-software systems, and cost-optimized distribution tier penetration.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Hubbell |
| Eaton |
| Toshiba Corporation |
| GE |
| Schneider Electric |
| Tridelta Meidensha GmbH |
| Shreem Electric |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Rotterdam container freight corridors transmit zinc oxide concentrate cost volatility directly into metal oxide varistor block pricing, compressing margins for distributors while amplifying premium capture for manufacturers with captive Peruvian mining contracts.
Pricing Analysis
Configured-to-order pricing for 800kV+ transmission-class arresters commands substantial premiums over standard medium-voltage distribution units. Three-tier pricing structure across premium, standard, and economy levels stratifies by IEC 60099-4 certification grade and bundled digital monitoring capabilities. Price erosion runs through economy tiers as Indian state-owned discoms consolidate vendor lists and extract volume leverage. Industrial end users in petrochemical and steel sectors exhibit lowest price sensitivity due to lifecycle cost modeling dominance, while rural electrification programs in emerging markets drive acute sensitivity at distribution voltage classes.
Supply Chain Analysis
Export-control restrictions on advanced ceramic processing equipment limit technology transfer to non-allied manufacturing jurisdictions, concentrating high-grade zinc oxide disc production in Germany, Japan, and China. Raw material flows draw from Peruvian and Australian zinc concentrate suppliers, with polymer housing compounds sourced from silicone rubber specialists in the Yangtze River Delta. Single-source vulnerability concentrates in 800kV+ testing certification, where only five laboratories worldwide validate transmission-class units. Distribution runs through state-owned grid operator procurement channels in India and Brazil, with integrated service bundling displacing pure hardware resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lightning arrester demand sits in early-cycle expansion as renewable interconnection mandates and rural electrification programs accelerate replacement cycles beyond traditional infrastructure depreciation schedules.
For Market Incumbents: Insulate core high-voltage transmission positions by deepening backward integration into zinc oxide ceramic production and securing captive testing facility access. State-owned grid operator vendor list consolidation in India and Brazil threatens margin erosion for suppliers lacking integrated digital monitoring portfolios. Priority investment targets wireless sensor module R&D and predictive maintenance subscription infrastructure to lock in recurring revenue streams. For New Entrants and Emerging Players: Establish a beachhead in marine-grade offshore wind surge protection, where salt-fog resistance specifications and floating platform mechanical requirements create specialist barriers insufficiently served by diversified conglomerates. White-space concentrates in North Sea and East Asian floating turbine projects requiring enhanced housing formulations. Go-to-market angle should emphasize IoT-enabled condition monitoring as a differentiated service layer rather than competing on arrester hardware unit economics. For Investors and Strategic Acquirers: Carve-out targets emerge from electrical conglomerates divesting non-core surge protection divisions to refocus on grid software and automation platforms. Long-term viability hinges on positioning upstream of renewable interconnection buildouts and data center power infrastructure expansion. Signal to watch is domestic content bonus utilization under US IRA and equivalent industrial policy frameworks in India and China, which will reshape geographic manufacturing footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Oxide Ceramic Production | Captive concentrate supply from Peruvian mining contracts insulates margin volatility from freight corridor disruptions. |
| Wireless Monitoring Module Development | Self-powered sensor integration transforms hardware into recurring-revenue predictive maintenance platforms for German transmission operators. |
| Marine-Grade Housing Certification | Salt-fog resistance validation unlocks North Sea and East Asian floating offshore wind procurement channels. |
| Domestic Assembly Expansion | US IRA content bonuses and Indian PLI scheme incentives reward localized transmission-class arrester manufacturing. |
| High-Voltage Testing Facility Partnership | Access to 800kV+ certification laboratories eliminates new product introduction bottlenecks for emerging market entrants. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility procurement directors, substation engineering leads, zinc oxide ceramic plant managers, and polymer housing compound specialists. Secondary validation drew from IEC 60099-4 certification registries, IEEE C62.11 technical committee filings, BIS approval databases, customs trade data on zinc concentrate flows, and SEC disclosures from listed electrical equipment manufacturers. Bottom-up unit demand modeling triangulated against top-down grid infrastructure investment forecasts.
Calibration anchored volume projections to disclosed rural electrification program targets, renewable interconnection queue data, and data center power capacity buildouts across Singapore, Ireland, and Virginia. Segmentation dimensions spanned voltage class, installation environment, end-use sector, and technology type. CAGRs were derived from regression analysis against historical replacement cycles and regulatory mandate implementation timelines. Forecast inputs incorporated zinc price volatility indices and testing facility capacity constraints.
Sensitivities concentrate around zinc concentrate supply disruptions, REACH regulatory expansion beyond European jurisdictions, and acceleration of silicon carbide replacement mandates. Forecasts reflect documented assumptions on grid modernization spending trajectories and distributed generation penetration rates. Material shifts in offshore wind deployment schedules or data center construction pauses would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Busbar Protection Market