
 Space Weapons Market | 2026-2036
Space Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Space Weapons Market Analysis
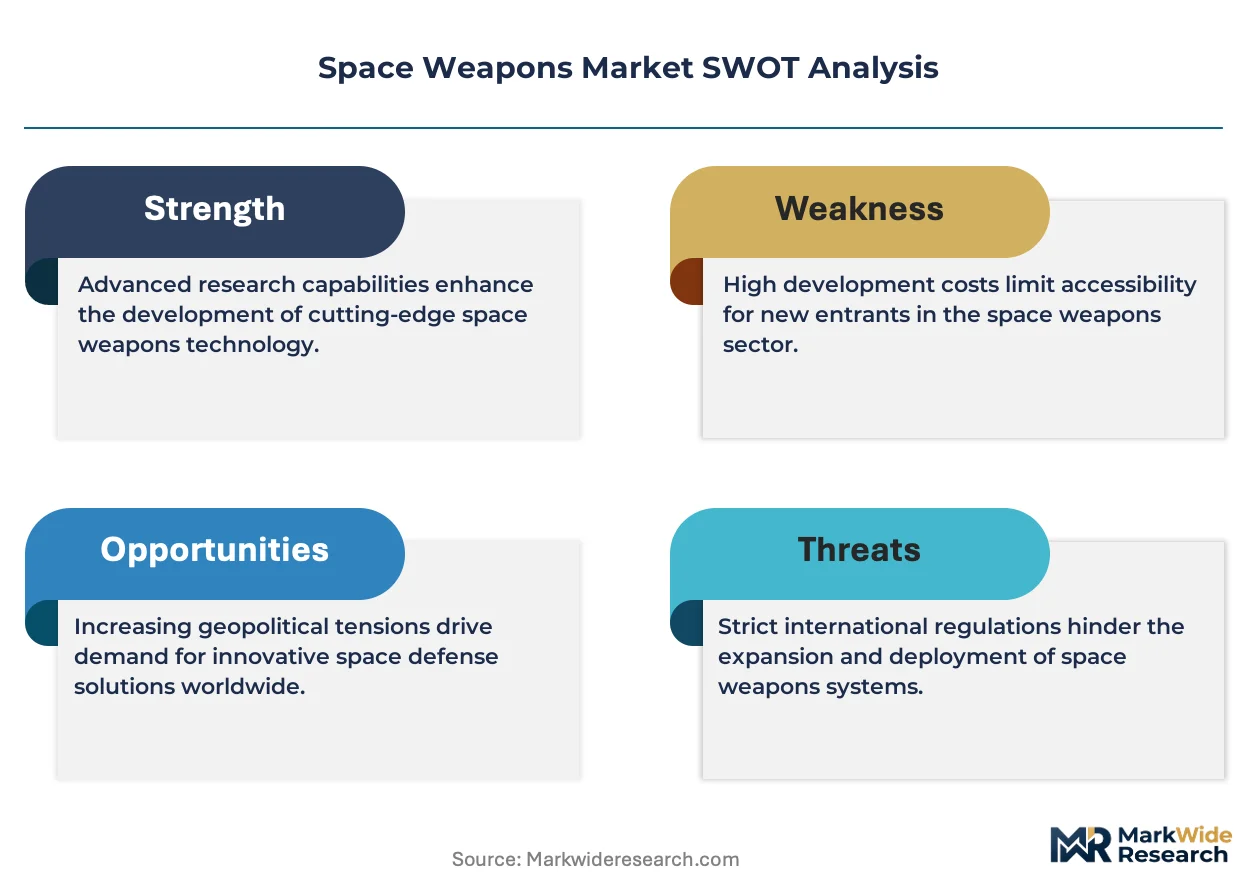
Directed energy miniaturization is narrowing the engineering gap between laboratory prototypes and deployable orbital payloads. Lockheed Martin leverages classified satellite self-defense programs to sustain multi-billion-dollar development pipelines. Northrop Grumman anchors its position through captive production of high-power solid-state laser subsystems. Boeing competes across the full stack from ground-based beam directors to space platform integration.
Space weapons encompass kinetic interceptors, directed energy systems, and electronic warfare payloads engineered for orbital denial or terrestrial strike missions, with laser systems requiring thermal management below 100 degrees Kelvin for sustained beam coherence. Anti-satellite weapons and hypersonic missiles command the largest current procurement envelopes, while directed energy platforms represent the fastest-growing technology segment as military agencies prioritize reusable engagement capacity over single-shot interceptors. Deployment method segmentation tilts toward ground-based systems for near-term readiness, though space-based platforms concentrate long-term margin pools due to integration complexity and sovereign launch infrastructure requirements.
The US Space Force orbital warfare doctrine, NATO space center guidelines, and China's MEE counterspace export controls collectively shape permissible technology transfer boundaries and foreign participation rules. The US Department of Defense restricts laser aperture thresholds above 500 kilowatts under ITAR frameworks, while ESA member states coordinate through the EU Space Programme for dual-use technology governance. Stakeholders must monitor classified budget line migrations between kinetic and directed energy portfolios to anticipate which technology families attract sustained sovereign commitment.
Market Dynamics
Directed energy miniaturization is collapsing the engineering gap between laboratory prototypes and deployable orbital payloads, forcing military procurement agencies to accelerate technology transition timelines.
Growth Catalysts
- ITAR Export Framework:The US Department of Defense's 500-kilowatt laser aperture thresholds create protected domestic production corridors for high-power solid-state systems.
- Orbital Warfare Doctrine:US Space Force directives mandating satellite self-defense capabilities channel sovereign investment toward reusable engagement platforms over kinetic interceptors.
- Counterspace Demonstrations:China's MEE export controls on dual-use space technologies are accelerating NATO member state procurement of indigenous directed energy platforms.
Market Restraints
- Thermal Management Materials:Cryogenic cooling systems requiring sustained operation below 100 degrees Kelvin depend on helium-3 supply chains concentrated in Russia and Qatar.
- Sovereign Launch Infrastructure:Space-based platform deployment requires captive access to heavy-lift vehicles, restricting participation to nations with domestic launch capability.
- Beam Coherence Physics:Atmospheric distortion compensation for ground-based systems demands adaptive optics complexity that extends development cycles.
Strategic Opportunities
- EU Space Programme Coordination:ESA member states are consolidating dual-use technology governance frameworks to pool procurement of high-power laser subsystems.
- Electronic Warfare Convergence:Integration of directed energy with cyber-electromagnetic payloads creates unified orbital denial architectures.
- Ground-to-Orbit Service Models:Laser communication terminals are opening commercial channels for military-grade beam director technology transfer.
Industry Challenges
- Cryogenic Engineering Talent:The specialized workforce for closed-cycle cooling system design remains concentrated in a handful of national laboratories.
- Classified Budget Transparency:Migration of funding between kinetic and directed energy portfolios complicates multi-year supplier planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Weapons Market |
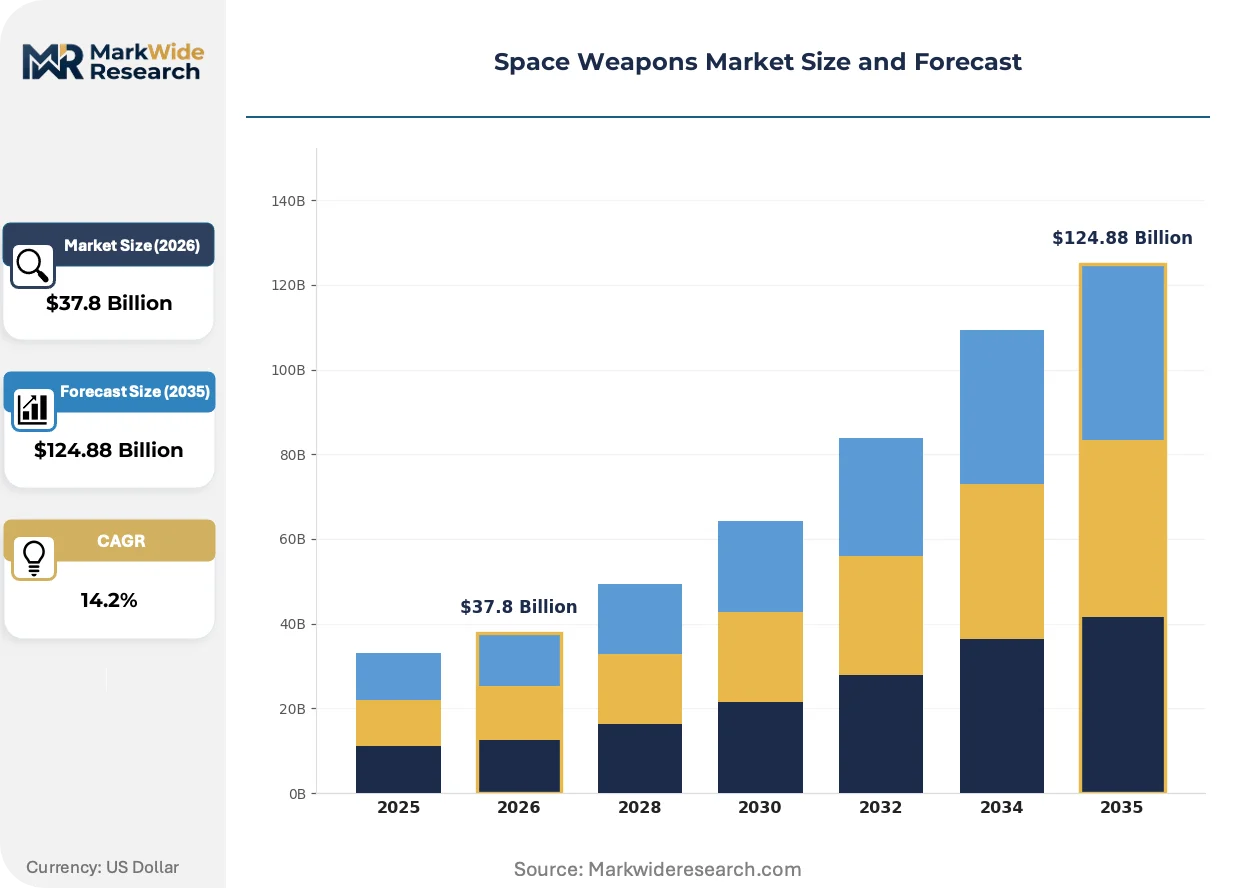
| Market Size in 2026 | $37.8 Billion |
| Market Size in 2035 | $124.88 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Kinetic Kill Vehicles, Directed Energy Weapons, Anti-Satellite Weapons, Hypersonic Missiles Technology: Laser Systems, Electromagnetic Railguns, Particle Beam Technology, Missile Defense Systems Deployment Method: Ground-Based Systems, Space-Based Platforms, Airborne Launchers, Naval Vessels End User: Military Agencies, Defense Contractors, Governmental Organizations, Private Space Firms |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, The Boeing Company, RTX Corporation, Airbus SE, L3Harris Technologies, General Dynamics Corporation, Thales Group, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Weapons Market Emerging Trajectories
Solid-state laser architectures are actively reshaping competitive positioning across orbital and terrestrial strike missions, compressing development timelines while expanding addressable mission profiles.
Diode-pumped alkali laser systems are collapsing the thermal management burden that previously constrained continuous-wave operation in vacuum environments. US Space Force technical requirements now specify these architectures for next-generation satellite self-defense payloads. The structural consequence is collapsing the supplier base from diversified optical component vendors toward integrated subsystem specialists with captive alkali vapor cell production.
China's MEE counterspace export controls are fragmenting technology transfer corridors that previously enabled rapid capability diffusion. Industrial consequence includes accelerated indigenous development programs across NATO member states and Japan. The segment most affected is ground-based beam director manufacturing, where METI-coordinated Japanese suppliers are expanding capacity to backfill restricted Chinese component flows.
Defense procurement agencies are consolidating vendor relationships through multi-year development agreements rather than transactional hardware acquisitions. The prime contractor tier is absorbing increased integration risk while subcontractors face compressed payment cycles. This pattern is most visible in the United States, where the Pentagon's classified space development agency has shifted to milestone-based funding for directed energy platform maturation.
Space Weapons Market Segmentation
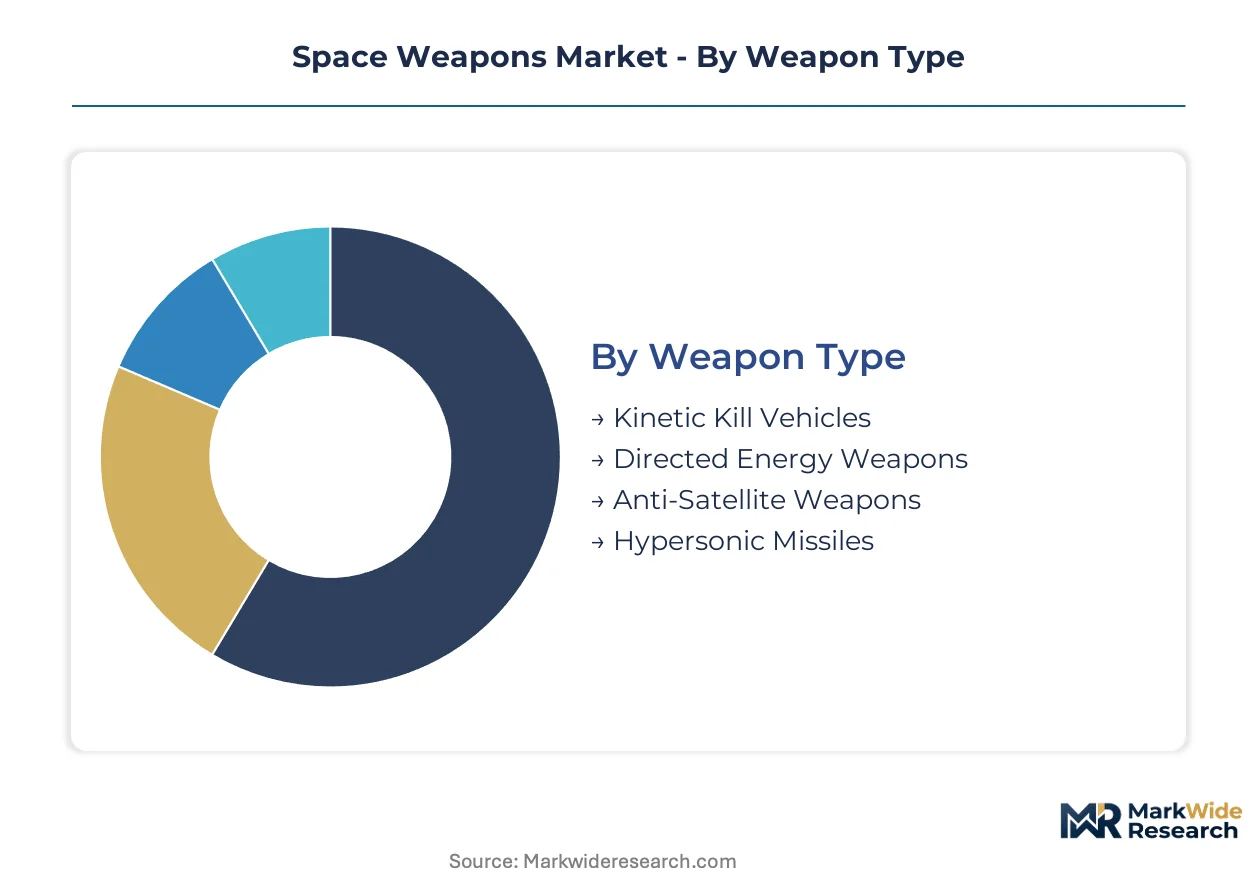
Weapon type and deployment method segmentation reveals where procurement budgets concentrate versus where technology roadmaps point. The divergence between kinetic interceptors and directed energy platforms shapes supplier strategy across every tier of the supply chain.
Weapon Type:
Use-case spectrum spans single-shot orbital denial through reusable terrestrial strike, with thermal and propulsion physics dictating mission suitability.
- Kinetic Kill Vehicles:Impact-based interceptors relying on precise orbital mechanics and terminal guidance for satellite destruction. Procurement concentrates in United States Space Force programs, constrained by debris generation thresholds under orbital sustainability guidelines.
- Directed Energy Weapons:Solid-state and chemical laser platforms delivering scalable effects without physical impact. China's MEE counterspace export controls are accelerating NATO indigenous development timelines for high-power aperture systems.
- Anti-Satellite Weapons:Purpose-built systems for orbital denial through kinetic, electromagnetic, or cyber payloads. Demand clusters in sovereign programs seeking independent counterspace capability.
- Hypersonic Missiles:Atmospheric glide vehicles and boost-glide systems for time-critical terrestrial strike. Thermal protection requirements favor suppliers with captive hypersonic wind tunnel infrastructure.
Established volume favors Kinetic Kill Vehicles; emerging adoption favors Directed Energy Weapons.
Technology:
Cost tier segmentation separates developmental platforms from fielded systems, with subsystem complexity driving prime contractor selection.
- Laser Systems:Diode-pumped alkali and solid-state architectures requiring cryogenic thermal management below 100 Kelvin. US Space Force technical specifications now mandate these for satellite self-defense payloads.
- Electromagnetic Railguns:Kinetic energy launchers using Lorentz force acceleration for hypervelocity projectiles. Power density requirements limit deployment to naval vessels with integrated electrical generation.
- Particle Beam Technology:Charged particle acceleration for deep-space engagement, constrained by atmospheric attenuation and magnetic field interference. Development remains laboratory-bound due to accelerator miniaturization barriers.
- Missile Defense Systems:Layered intercept architectures combining kinetic and directed energy layers. NATO space center coordination is pooling procurement for ground-based beam director integration.
Mature procurement favors Missile Defense Systems; steepest expansion trajectory sits with Laser Systems.
Deployment Method:
Application-based segmentation distinguishes near-term readiness from long-term sovereign capability requirements.
- Ground-Based Systems:Fixed and mobile beam directors with adaptive optics for atmospheric compensation. ITAR restrictions on aperture thresholds above 500 kilowatts protect domestic US production corridors.
- Space-Based Platforms:Orbital payloads requiring sovereign heavy-lift launch infrastructure and on-orbit servicing. Japan's METI-coordinated suppliers are expanding alkali vapor cell capacity for satellite integration.
- Airborne Launchers:High-altitude platforms for boost-phase intercept and rapid repositioning. Boeing competes across this tier from modified commercial airframes to purpose-built military vehicles.
- Naval Vessels:Surface combatants with integrated electrical power for railgun and laser operation. Hull space constraints favor solid-state laser architectures over chemical systems.
Near-term procurement tilts toward Ground-Based Systems; margin concentration accumulates in Space-Based Platforms.
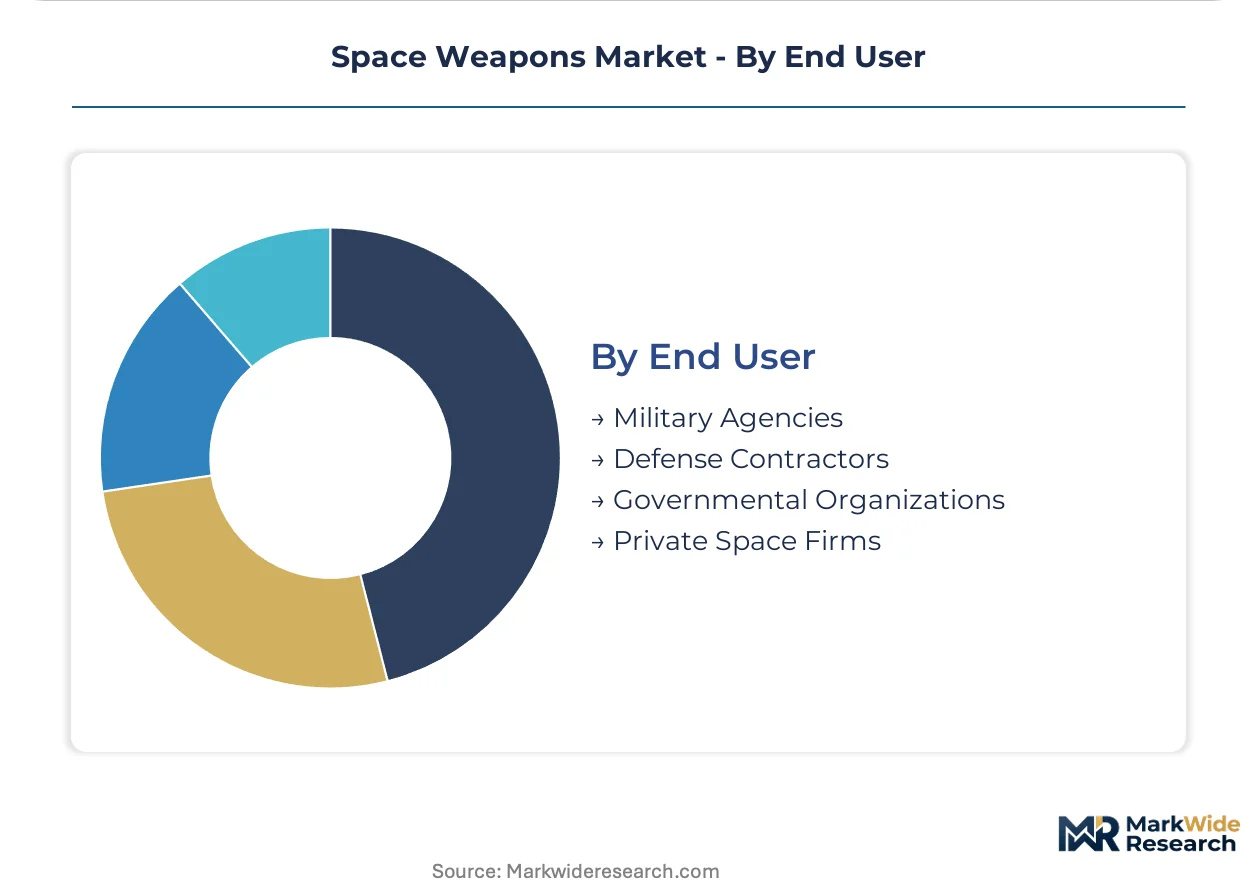
End User:
Customer-type segmentation separates classified sovereign programs from commercial-adjacent technology development.
- Military Agencies:National space forces and joint commands with operational counterspace mandates. The Pentagon's classified space development agency channels milestone-based funding for directed energy maturation.
- Defense Contractors:Prime and tier-one suppliers absorbing integration risk through multi-year development agreements. Lockheed Martin leverages satellite self-defense programs to sustain multi-billion-dollar pipelines.
- Governmental Organizations:Civil space agencies and dual-use technology coordinators. ESA member states consolidate governance through the EU Space Programme for laser subsystem procurement.
- Private Space Firms:Commercial launch providers and satellite operators seeking defensive payloads. Laser communication terminals are opening technology transfer channels for military-grade beam directors.
Budget authority concentrates with Military Agencies; technology diffusion runs through Defense Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-directed energy platforms flow to NATO member states under ITAR-controlled export corridors, while Chinese counterspace demonstrations accelerate indigenous development timelines across allied defense industrial bases.
United States
The Pentagon's classified space development agency channels milestone-based funding toward directed energy maturation, with Boeing competing across ground-based beam directors and space platform integration. ITAR frameworks restrict laser aperture thresholds above 500 kilowatts, creating protected domestic production corridors for high-power solid-state systems. Huntsville, Alabama and El Segundo, California anchor prime contractor engineering clusters for orbital warfare payloads.
China
Counterspace demonstrations under MEE export controls fragment technology transfer corridors that previously enabled rapid capability diffusion. The country's national space regulator coordinates dual-use laser subsystem development through state-directed industrial planning. Beijing-Tianjin-Hebei concentrates alkali vapor cell research facilities supporting diode-pumped laser architectures.
Germany
High-power solid-state laser procurement accelerates through NATO space center coordination and EU Space Programme governance frameworks. KBA and national defense procurement offices pool continental demand for ground-based beam director integration. Bavaria's Munich-Stuttgart corridor hosts captive production of adaptive optics subsystems for atmospheric compensation.
Japan
Indigenous directed energy development expands as METI-coordinated suppliers backfill restricted Chinese component flows for ground-based beam director manufacturing. The country's trade ministry channels industrial policy toward alkali vapor cell capacity expansion for satellite integration. Tokyo-Nagoya industrial corridor concentrates cryogenic engineering talent for closed-cycle cooling system design.
France
Thales Group anchors European prime contractor competition for satellite self-defense payloads, with ANSM-coordinated export controls shaping permissible technology transfer boundaries. ESA member state coordination consolidates dual-use laser subsystem procurement through Paris-Saclay research clusters. Toulouse aerospace engineering base integrates directed energy with cyber-electromagnetic orbital denial architectures.
Space Weapons Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions, with prime contractors absorbing integration risk through multi-year development agreements. The structure concentrates around aerospace-defense conglomerates with captive satellite platform heritage and classified program access. Three archetypes dominate: full-stack integrators spanning ground-to-orbit capabilities, laser subsystem specialists with alkali vapor cell production, and electronic warfare convergence players. Competitive moves center on milestone-based funding capture and sovereign launch infrastructure partnerships.
Among United States-based defense conglomerates, Lockheed Martin Corporation, Northrop Grumman Corporation, and The Boeing Company occupy anchor positions across the prime contractor tier. Lockheed Martin exemplifies the satellite self-defense program archetype, Northrop Grumman represents high-power solid-state laser subsystem specialists, and Boeing sits within the full-stack integration category spanning modified commercial airframes to purpose-built military vehicles. European competition flows through Airbus SE and Thales Group, which anchor EU Space Programme coordination for dual-use technology governance.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| RTX Corporation |
| Airbus SE |
| L3Harris Technologies |
| General Dynamics Corporation |
| Thales Group |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Helium-3 supply chain concentration in Russia and Qatar determines both cryogenic cooling cost spreads and subsystem vendor consolidation across directed energy platforms. ITAR aperture thresholds above 500 kilowatts protect domestic US production corridors while fragmenting international procurement into tiered access levels.
Pricing Analysis
Next-generation diode-pumped alkali systems command substantial premiums over legacy solid-state architectures nearing procurement maturity. Three-tier pricing structure across sovereign-classified, allied-export, and commercial-adjacent laser communication terminals reflects ITAR compliance burden and thermal management complexity. Cost compression in ground-based beam directors intensifies because Japanese METI-coordinated suppliers are expanding alkali vapor cell capacity. Military agencies demonstrate lowest price sensitivity given milestone-based funding structures, while private space firms face acute pressure from launch cost volatility.
Supply Chain Analysis
Tariff exposure between US and Chinese technology corridors dominates supply chain risk calculus for alkali vapor cell and adaptive optics procurement. Manufacturing gravity centers on the United States for ITAR-restricted subsystems, Germany for high-power solid-state laser components, and Japan for cryogenic engineering talent. Raw material dependencies draw from helium-3 isotopes, rare-earth doped gain media, and precision optical substrates. Single-source vulnerability concentrates in closed-cycle cooling system design where workforce scarcity limits vendor diversification. Distribution runs through prime contractor integration channels rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pentagon milestone-based funding consolidation has shifted procurement leverage toward defense contractors absorbing multi-year development risk. Buyer power concentrates in classified sovereign programs with captive launch infrastructure.
For Market Incumbents: Insulate satellite self-defense program pipelines through captive alkali vapor cell production and sovereign launch infrastructure partnerships. Lockheed Martin's classified program access and Northrop Grumman's high-power solid-state laser subsystems demonstrate defensible positioning against emerging subsystem specialists. Backward integration into cryogenic cooling components mitigates helium-3 supply concentration risk. For New Entrants and Emerging Players: Ground-to-orbit laser communication terminals for commercial satellite operators represent the most penetrable entry point for military-grade beam director technology transfer. NATO space center coordination for pooled procurement of adaptive optics subsystems offers second white-space avenue. Go-to-market positioning should emphasize dual-use governance compliance and ESA member state industrial policy alignment. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated subsystem specialists with captive thermal management capabilities over diversified optical component vendors. Long-term viability across the analysis window hinges on sovereign commitment trajectories between kinetic and directed energy portfolio migrations. The signal to watch is classified budget line transparency revealing sustained funding allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Alkali Vapor Cell Capacity Expansion | METI-coordinated Japanese suppliers backfill restricted Chinese component flows for NATO procurement. |
| Sovereign Launch Infrastructure Partnership | Space-based platform deployment requires captive heavy-lift access restricting prime contractor competition. |
| ITAR Compliance Certification Investment | 500-kilowatt aperture thresholds protect domestic US production corridors for high-power systems. |
| Multi-Year Development Agreement Restructuring | Pentagon milestone-based funding shifts integration risk absorption toward prime contractor tier. |
| Cryogenic Engineering Talent Acquisition | Closed-cycle cooling system design workforce scarcity limits vendor base expansion nationally. |
Methodological Framework
Cross-validation between primary defense procurement officer interviews and secondary ITAR regulatory filings anchors the qualitative findings in this study. Program managers at the Pentagon's classified space development agency, prime contractor business development leads, cryogenic engineering directors at national laboratories, and ESA dual-use technology coordinators provided operational perspective. Secondary validation drew from US Space Force technical specifications, NATO space center procurement guidelines, China's MEE export control publications, and EU Space Programme governance documents. Bottom-up subsystem cost build-ups and top-down sovereign budget allocation triangulation ensured analytical coherence.
Calibration against historical program milestone achievement rates and technology readiness level progression patterns shaped the projection framework across the analysis window. Segmentation dimensions modeled include weapon type, deployment method, technology architecture, and end-user classification with geographic regulatory cluster overlay. CAGRs were derived from technology adoption S-curve positioning and procurement pipeline visibility. Industry-specific forecast inputs encompassed ITAR threshold adjustment probabilities and helium-3 supply contract renewal patterns.
Practitioners should monitor sovereign budget transparency migrations and counterspace demonstration frequencies for early signals of technology commitment inflection. Forecasts reflect assumptions regarding sustained NATO coordination and stable export control frameworks that revision in either direction would invalidate. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Close-In Weapon Systems Market