
 Global Artillery Systems Market | 2026-2036
Global Artillery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artillery Systems Market Intelligence
The shift towards modular, open-architecture digital backbones is fragmenting the traditionally monolithic artillery system design. This allows for more specialized component suppliers to enter the value chain. BAE Systems leverages its extensive portfolio in precision-guided munitions to complement its platforms. Hanwha Group dominates the self-propelled howitzer segment through large-scale production capabilities in South Korea.
Artillery systems are large-caliber weapons designed for long-range indirect fire support on the battlefield. These systems are characterized by their caliber, such as the common 155mm standard, and their ability to deliver explosive, smoke, or illumination payloads over significant distances. Self-Propelled Artillery represents the fastest-growing system type, valued for its mobility and rapid deployment capabilities. Within calibers, the 155mm standard maintains its dominance due to interoperability requirements among allied forces.
Procurement is governed by strict national defense standards and export controls, such as the US International Traffic in Arms Regulations (ITAR). NATO Standardization Agreements (STANAGs) dictate interoperability requirements for member nations, influencing design specifications for ammunition and communication systems. Future investment decisions will hinge on balancing the acquisition of next-generation autonomous systems with the sustainment of vast legacy fleets.
Market Dynamics
The imperative to modernize vast Cold War-era artillery inventories defines market dynamics. This is driven by renewed great-power competition, which places a premium on long-range precision fires and rapid deployment capabilities, forcing investment in next-generation platforms and advanced munitions.
Growth Catalysts
- Territorial Defense Postures:Heightened geopolitical risk in Eastern Europe and the Indo-Pacific compels nations like Poland and India to accelerate procurement of new self-propelled and towed howitzers to bolster their defensive capabilities.
- NATO Standardization:Adherence to NATO STANAGs for ammunition and communications mandates continuous upgrades among member states to ensure interoperability, particularly for the common 155mm caliber.
- Technological Obsolescence:The operational inadequacy of aging artillery fleets against modern threats necessitates replacement programs, creating consistent demand for advanced systems with superior range, mobility, and accuracy.
Market Restraints
- Extreme Export Controls:Regulations like the US International Traffic in Arms Regulations (ITAR) severely restrict technology transfer and limit the potential customer base for top-tier systems, fragmenting the addressable market.
- High Input Costs:The manufacturing of artillery barrels and breech mechanisms depends on specialized steel alloys and forging capacities, for which costs are high and the global supply base is concentrated.
- Long Acquisition Timelines:Multi-year defense budgeting and procurement cycles common in most countries delay contract awards and revenue realization, creating significant business uncertainty for manufacturers.
Strategic Opportunities
- Unmanned Ground Systems:Development of robotic or remotely operated artillery platforms offers a new frontier for reducing crew risk and enabling operations in contaminated or high-threat environments.
- Digital Backbone Upgrades:Offering modular, open-architecture fire control and communication upgrades for legacy systems provides a cost-effective modernization path for armed forces with large, older fleets.
- Extended Range Munitions:Investment in rocket-assisted projectiles and advanced propellants creates opportunities for ammunition suppliers to provide significant performance enhancements for existing artillery platforms.
Industry Challenges
- Legacy Fleet Integration:Ensuring new digital command-and-control systems are backward-compatible with vast inventories of older, analog artillery pieces presents a major technical and logistical hurdle for armed forces.
- Cybersecurity Vulnerabilities:The increasing networking of artillery systems and reliance on GPS for targeting creates new attack surfaces that must be secured against sophisticated electronic warfare and cyberattacks.
- Specialized Skills Gap:A shortage of software engineers and data scientists with defense-sector experience hampers the development and deployment of AI-powered targeting and autonomous systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artillery Systems Market |
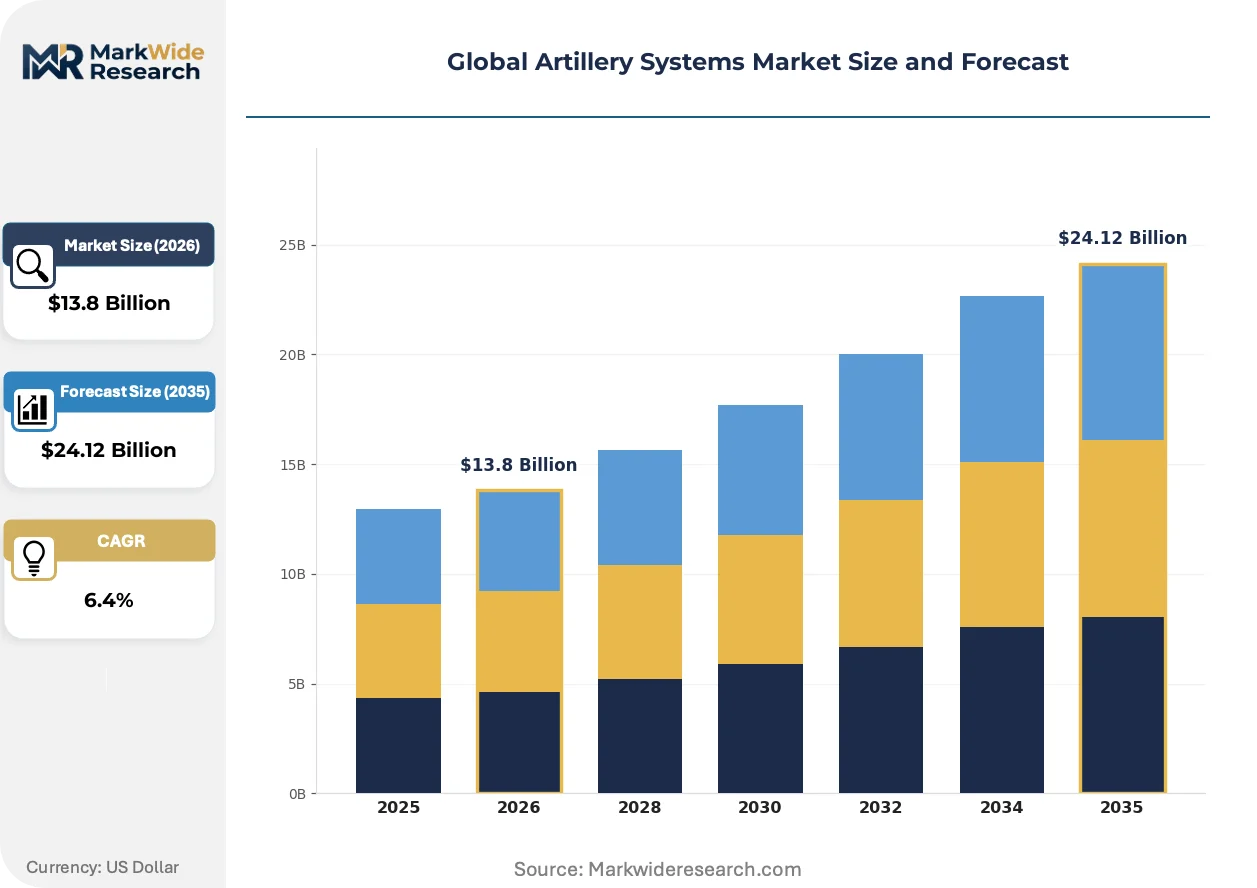
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Towed Artillery, Self-Propelled Artillery, Rocket Launchers, Mortars, Coastal Artillery Caliber: 105mm, 120mm, 155mm, 203mm, 240mm Application: Field Battle, Siege Operations, Coastal Defense, Air Defense Support, Strategic Bombardment End User: Ground Forces, Artillery Brigades, Military Academies, Defense Contractors |
| Companies Covered | Lockheed Martin Corporation, BAE Systems, Hanwha Group, Elbit Systems, Nexter Group, Rheinmetall AG, Leonardo S.p.A, General Dynamics, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artillery Systems Market Strategic Shifts & Innovations
The digital fusion of sensor data with firing platforms is the dominant theme, transforming artillery from an area weapon into a precision-strike asset. This evolution prioritizes speed, data networking, and autonomous functions over sheer explosive power, reshaping operational doctrine and system design requirements.
Artificial intelligence in fire-control systems automates target recognition and solution calculation using diverse sensor inputs. Ground forces in technologically advanced militaries are rapidly adopting these capabilities to shorten engagement timelines. The traditional delay between target detection and projectile impact is collapsing, enabling the effective prosecution of time-sensitive and mobile targets that were previously difficult to engage.
NATO Standardization Agreements governing ammunition interoperability and secure data links dictate design choices for manufacturers. These standards compel non-member states seeking Western alignment to adopt compatible systems, expanding the market for compliant hardware. Ammunition and communication subsystem developers are most affected, facing stringent certification to access NATO and partner nation contracts.
A demand-side shift toward disaggregated procurement is gaining traction, with militaries buying modular subsystems from different vendors. This disrupts the traditional prime contractor model that supplied a complete, closed-architecture weapon system. The trend is pronounced in European modernization programs specifying open-architecture standards to avoid vendor lock-in and encourage specialist innovation.
Global Artillery Systems Market Segmentation
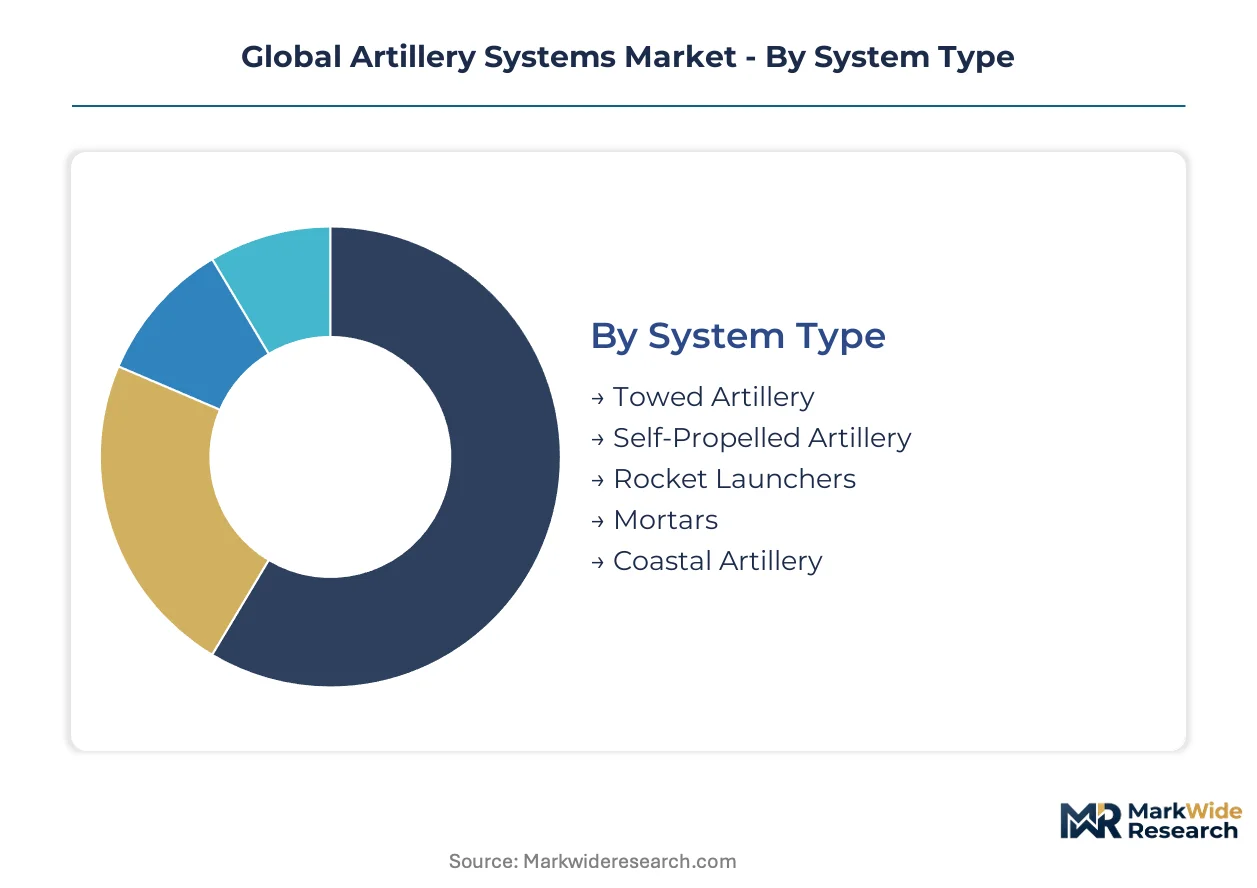
The segmentation of the global artillery systems market is crucial for understanding the diverse procurement strategies and technological adoption pathways across various military organizations. Different system types, calibers, applications, and end-users drive distinct demand patterns and investment priorities within this specialized defense sector.
System Type:
System type segmentation highlights varying procurement cycles and upgrade pathways across different artillery platforms.
- Self-Propelled Artillery:These mobile platforms integrate the gun and its transport into a single armored vehicle, offering rapid deployment and shoot-and-scoot capabilities. Demand concentrates in Eastern Europe and the Indo-Pacific, driven by the need for quick repositioning against modern threats.
- Rocket Launchers:These systems fire unguided or guided rockets, providing area suppression or precision strikes over very long ranges. Procurement efforts in countries like Poland and South Korea focus on these systems for strategic deterrence and deep strike capabilities.
- Towed Artillery:These traditional systems require separate prime movers for transport, offering cost-effectiveness for static or less mobile defense postures.
- Mortars:Mortars are high-angle, short-range indirect fire weapons, typically employed for close support of infantry units.
- Coastal Artillery:These fixed or mobile systems defend maritime approaches and critical shorelines, deterring naval incursions.
Towed Artillery anchors the volume base while Self-Propelled Artillery gains share at the steepest rate.
Caliber:
Caliber segmentation reveals critical interoperability requirements and manufacturing complexities across different artillery ammunition types.
- 155mm:This standard caliber dominates modern artillery, providing a balance of range, destructive power, and interoperability across NATO and allied forces. Demand for 155mm ammunition concentrates in countries adhering to STANAGs, facilitating joint operations.
- 105mm:A lighter, more mobile caliber, 105mm artillery is often used by airborne or light infantry units for rapid deployment and close support. Procurement in countries like India often includes 105mm systems for diverse terrain operations.
- 120mm:This caliber is commonly found in mortar systems, balancing portability with significant explosive effect for infantry support.
- 203mm:Larger 203mm systems offer heavier destructive power, primarily for strategic bombardment or siege operations.
- 240mm:The largest artillery caliber, 240mm systems deliver immense firepower for specialized long-range or heavy siege applications.
The 155mm standard dominates overall market share, while 105mm systems see significant modernization efforts for lighter forces.
Application:
Application segmentation reflects diverse operational doctrines and strategic priorities guiding artillery system deployment.
- Field Battle:This application involves providing indirect fire support for ground maneuvers, suppressing enemy positions, and shaping the battlefield. Demand in Eastern Europe and the Indo-Pacific focuses on systems optimized for rapid, precision engagement in dynamic combat scenarios.
- Coastal Defense:Artillery systems in this application protect maritime borders and critical coastal infrastructure from naval threats. Countries with extensive coastlines, like South Korea, prioritize these capabilities to enhance territorial defense postures.
- Siege Operations:This involves sustained, heavy bombardment of fortified positions or urban areas, requiring powerful, often larger-caliber systems.
- Air Defense Support:Artillery provides complementary fire against low-flying aircraft or drones, augmenting dedicated air defense systems.
- Strategic Bombardment:Long-range artillery delivers deep strikes against high-value enemy assets far behind the front lines, often using rocket launchers.
The Field Battle segment commands the largest operational footprint, while Coastal Defense applications are expanding most quickly.
End User:
End user segmentation highlights distinct procurement processes and training requirements across different military and defense entities.
- Ground Forces:These comprise the primary end users of artillery systems, integrating them into combined arms operations for fire support, suppression, and interdiction. Modernization programs within national Ground Forces globally drive significant procurement of advanced platforms.
- Artillery Brigades:Specialized units within ground forces, these brigades focus exclusively on artillery operations, requiring specific training, equipment, and command-and-control systems. Their procurement decisions heavily influence demand for specialized fire control and ammunition.
- Military Academies:These institutions procure artillery systems for training future officers and specialists in operational procedures and tactical deployment.
- Defense Contractors:These entities act as suppliers or integrators, often acquiring components or full systems for R&D, testing, or export to foreign militaries under license.
Ground Forces represent the largest consumer segment, with Defense Contractors influencing technology adoption and export markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's heightened geopolitical risk drives demand for advanced artillery systems from Western manufacturers. India also seeks modern platforms to bolster its territorial defense capabilities. South Korea emerges as a significant exporter, supplying self-propelled howitzers globally.
Poland
Poland's accelerated procurement of new self-propelled and towed howitzers bolsters its defensive capabilities. Adherence to NATO Standardization Agreements (STANAGs) mandates continuous system upgrades among member states. The Silesian industrial region focuses on integrating advanced Western artillery technologies.
India
India procures 155mm and 105mm systems for diverse terrain operations and territorial defense. The country's Defence Procurement Procedure (DPP) prioritizes indigenous manufacturing and technology transfer. Chennai's defense manufacturing hubs specialize in artillery component production.
South Korea
South Korea focuses on self-propelled howitzers and rocket launchers for strategic deterrence and deep strike capabilities. National defense standards influence the design specifications for domestic systems. The Changwon industrial complex produces large-scale artillery platforms for domestic use and export.
United States
American investment drives next-generation autonomous systems and extended-range munitions development. The US International Traffic in Arms Regulations (ITAR) severely restrict technology transfer and limit the potential customer base. The Aberdeen Proving Ground in Maryland conducts extensive artillery system testing and evaluation.
Germany
German modernization efforts address legacy fleets and integrate digital backbone upgrades. National defense procurement guidelines shape investment decisions for advanced systems. Bavaria's defense manufacturing centers contribute to specialized artillery components and systems integration.
Global Artillery Systems Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure within the artillery systems sector. This dynamic fosters a landscape where large defense primes offering full systems coexist with niche component manufacturers providing specialized technologies. Strategic archetypes include integrated system providers, specialized munitions developers, and digital backbone integrators. Companies prioritize portfolio diversification and strategic partnerships to secure market share and navigate complex export controls.
Integrated system providers like BAE Systems and Hanwha Group anchor the market, exemplifying scale-driven production and platform expertise. BAE Systems leverages its extensive portfolio in precision-guided munitions to complement its platforms, reinforcing its position as a comprehensive defense contractor. South Korea's Hanwha Group dominates the self-propelled howitzer segment through large-scale production capabilities, serving both domestic and international demand. German-based Rheinmetall AG represents a key player in munitions and system components, contributing to various artillery platforms across Europe. These entities navigate stringent national defense standards and export controls, influencing technology adoption and market access for advanced artillery solutions.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems |
| Hanwha Group |
| Elbit Systems |
| Nexter Group |
| Rheinmetall AG |
| Leonardo S.p.A |
| General Dynamics |
| Northrop Grumman |
| Others |
Cost & Logistics Intelligence
Extreme export controls, such as the US International Traffic in Arms Regulations (ITAR), determine pricing tier spreads and the highly fragmented supply chain shape for advanced artillery systems. These regulations restrict technology transfer, directly influencing market access and component sourcing strategies.
Pricing Analysis
The technology-generation pricing gap differentiates between legacy system upgrades, current-generation platforms, and next-generation autonomous artillery solutions. Pricing operates primarily on a contract-based long-term offtake model, driven by extensive customization and brand premium for integrated system providers. Strict NATO STANAG certification also commands a premium, while pricing pressure stems from the need to sustain vast legacy fleets. National defense ministries procuring advanced systems exhibit lower price sensitivity compared to smaller nations upgrading older inventory.
Supply Chain Analysis
Stringent export-control regimes, such as the US International Traffic in Arms Regulations (ITAR), severely limit the global flow of advanced artillery components and finished systems. Supply concentration centers on key manufacturing hubs in South Korea, Germany, and the United States, drawing from specialized steel alloys and advanced electronics. Single-source vulnerability for critical components represents a significant supply chain risk. Distribution runs through direct government-to-government sales or licensed production agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global artillery systems market is in an early-cycle expansion phase, driven by renewed geopolitical tensions compelling nations to modernize their defense capabilities. This dynamic environment creates significant opportunities for innovation and strategic positioning.
For Market Incumbents: Entrench core market positions by diversifying platform and precision-guided munitions portfolios, mitigating the threat of technological obsolescence. Forge strategic partnerships to share R&D costs for next-generation AI-powered targeting systems and autonomous platforms. Investment in STANAG certification for new components ensures interoperability and secures access to NATO member contracts. This proactive approach sustains market share against emerging niche component specialists. For New Entrants and Emerging Players: Modular, open-architecture digital backbone upgrades for legacy artillery systems represent a penetrable entry point for specialized technology firms. Focus on developing extended-range munitions that are compatible with existing 155mm platforms. Eastern European nations with vast Cold War-era fleets offer a significant market for these cost-effective modernization solutions. A go-to-market strategy emphasizing interoperability and rapid integration will gain traction. For Investors and Strategic Acquirers: The market sits at a robust growth phase that favors technology-agnostic investors with a long-term outlook on defense spending. Significant investment in artillery modernization is anticipated over the next decade, ensuring sustained demand. Target acquisition archetypes include specialized component manufacturers focusing on AI-powered targeting, advanced materials for munitions, or cybersecurity solutions for networked platforms. Increased defense budgeting specifically for autonomous artillery R&D serves as a key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Powered Targeting Systems | Automates target recognition and solution calculation, shortening engagement timelines for ground forces. |
| Develop Extended-Range Munitions | Enhances performance of existing artillery platforms, providing deeper strike capabilities against high-value targets. |
| Pursue Open-Architecture Digital Backbone Integration | Allows for cost-effective modernization of legacy systems and avoids vendor lock-in for armed forces. |
| Expand Self-Propelled Howitzer Production Capacity | Addresses rising demand for mobile, rapid-deployment platforms in Eastern Europe and the Indo-Pacific. |
| Strengthen Cybersecurity for Networked Systems | Protects critical fire control and communication systems from sophisticated electronic warfare and cyberattacks. |
Research Approach
Cross-validation between primary interviews and secondary research anchors the qualitative findings and quantitative estimates. This involved engaging defense procurement officers, artillery system engineers, military strategists, and specialized component suppliers. Secondary validation drew from national defense budgets, military doctrine publications, and relevant company filings. A rigorous bottom-up and top-down triangulation process ensured data accuracy across all segments.
The analytical framework was calibrated using a multi-factor regression model across the analysis window, integrating historical data with projected trends. Segmentation dimensions modeled included system type, caliber, application, end user, and regional procurement policies. Compound Annual Growth Rates were derived from an iterative process considering geopolitical risk assessments and military modernization program timelines. This approach provides a robust projection for the market.
Practitioners should monitor major geopolitical shifts and unexpected technological breakthroughs for early signals of market trajectory changes. Forecasts reflect current assumptions regarding defense spending and procurement cycles. Material shifts in national defense budgets or export control regulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Middle East and Africa Ammunition Market