
 Ballistic Missile Market | 2026-2036
Ballistic Missile Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistic Missile Market Analysis
Hypersonic glide vehicle integration is bifurcating the competitive landscape into tier-one strategic systems and legacy modernization programs. Lockheed Martin leverages its dominance in ground-based strategic deterrent engineering to anchor the US modernization pipeline. Northrop Grumman sustains submarine-launched ballistic missile leadership through in-house production of solid rocket motors and reentry vehicle assemblies. RTX Corporation competes across propulsion and guidance subsystems, extending its supplier footprint into allied nuclear deterrent programs.
A ballistic missile is a self-propelled, guided projectile following a ballistic trajectory to deliver conventional or nuclear warheads over intercontinental distances, with modern variants incorporating post-boost vehicle maneuvering and multiple independently targetable reentry vehicle configurations. Its primary purpose is strategic deterrence through assured second-strike capability or precision conventional strike against hardened targets. Land-based segments remain the backbone of nuclear triads in major powers, while submarine-launched systems command the highest capital intensity and longest development cycles. Hypersonic technology represents the fastest-growing technology category, though maneuverable reentry vehicles already occupy mature production lines with established margin pools.
The US Department of Defense, NATO's Nuclear Planning Group, and China's Central Military Commission each impose distinct certification and basing requirements that fragment supplier compliance obligations across export-controlled and sovereign-development pathways. The US Department of Energy's National Nuclear Security Administration encloses warhead integration standards, limiting foreign contractor access to end-to-end system roles. Stakeholders must monitor how export control harmonization between the US State Department and allied defense ministries reshapes subcontractor eligibility for integrated propulsion and guidance packages.
Market Dynamics
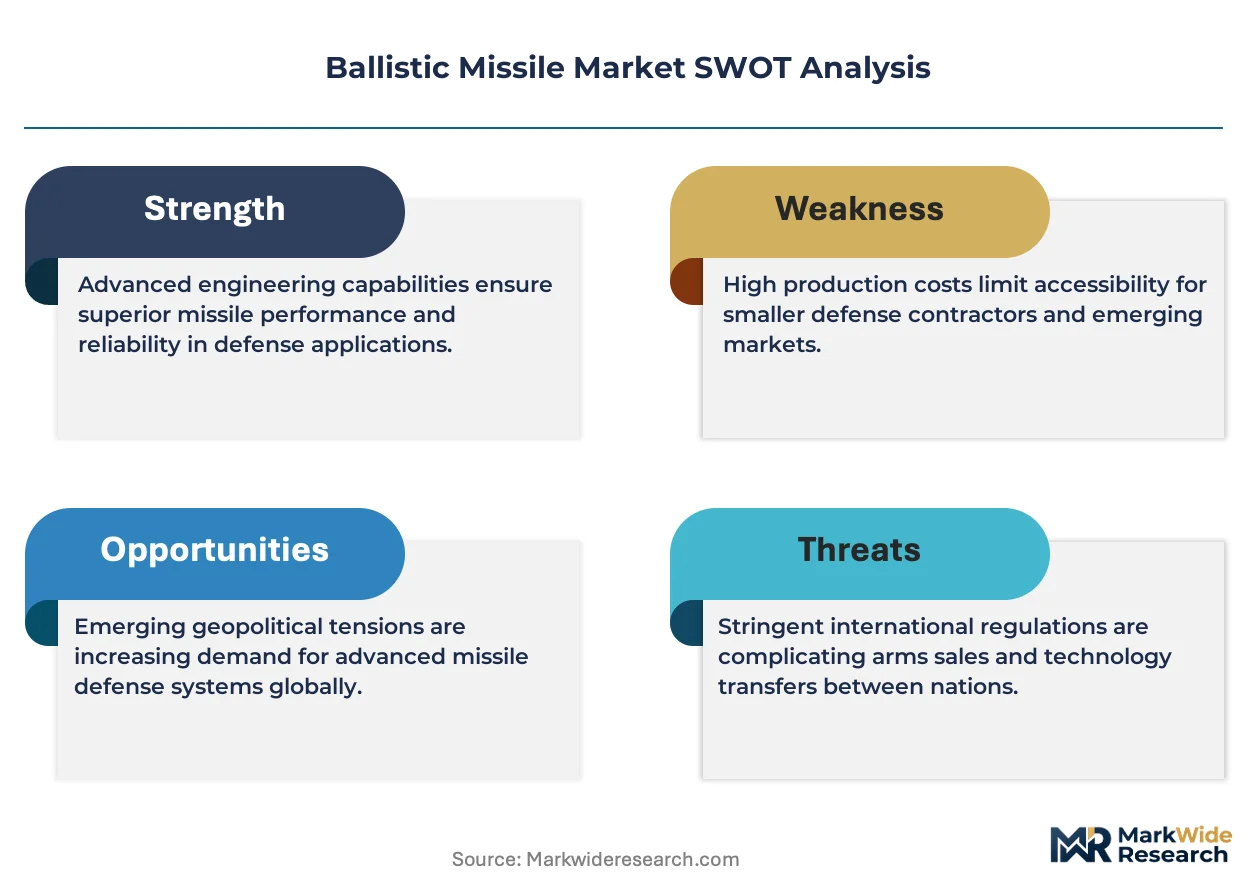
Hypersonic glide vehicle maturation is compressing development cycles across strategic deterrent programs while fragmenting supplier qualification pathways between legacy ballistic architectures and next-generation maneuvering platforms.
Growth Catalysts
- US Nuclear Posture Review mandates:The Pentagon's modernization directives sustain multi-decade procurement commitments for ground-based and sea-based deterrent replacement programs.
- Solid rocket motor capacity expansion:NATO allies are accelerating domestic propulsion industrial base investments to reduce dependency on foreign subsystem sourcing.
- China's Central Military Commission spending:Beijing's defense budget allocations prioritize both quantitative missile force expansion and qualitative hypersonic payload integration.
Market Restraints
- Export control fragmentation:The US State Department's International Traffic in Arms Regulations and allied national disclosure regimes create incompatible compliance matrices for integrated guidance packages.
- Specialized metallurgy supply concentration:High-temperature alloy production for reentry vehicle thermal protection concentrates among a limited supplier base in the United States and Russia.
- Warhead integration certification timelines:The US Department of Energy's National Nuclear Security Administration qualification protocols extend system deployment schedules by seven to twelve years.
Strategic Opportunities
- UK-France deterrent cooperation frameworks:Joint submarine-launched ballistic missile maintenance protocols create openings for shared propulsion and guidance subsystem sourcing.
- India's indigenous submarine deterrent program:New Delhi's pursuit of sea-based nuclear capability generates demand for foreign technical assistance in solid motor and reentry vehicle engineering.
- Hypersonic-conventional payload convergence:Maneuvering reentry vehicle technology originally developed for nuclear delivery is migrating to precision conventional strike applications.
Industry Challenges
- Aerothermal protection engineering talent scarcity:The specialized workforce for carbon-carbon composite nosecone fabrication and ablative material qualification is aging without sufficient replacement pipeline development.
- Legacy silo infrastructure integration:New ground-based strategic deterrent systems must interface with decades-old command-and-control networks hardened against electromagnetic pulse effects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballistic Missile Market |
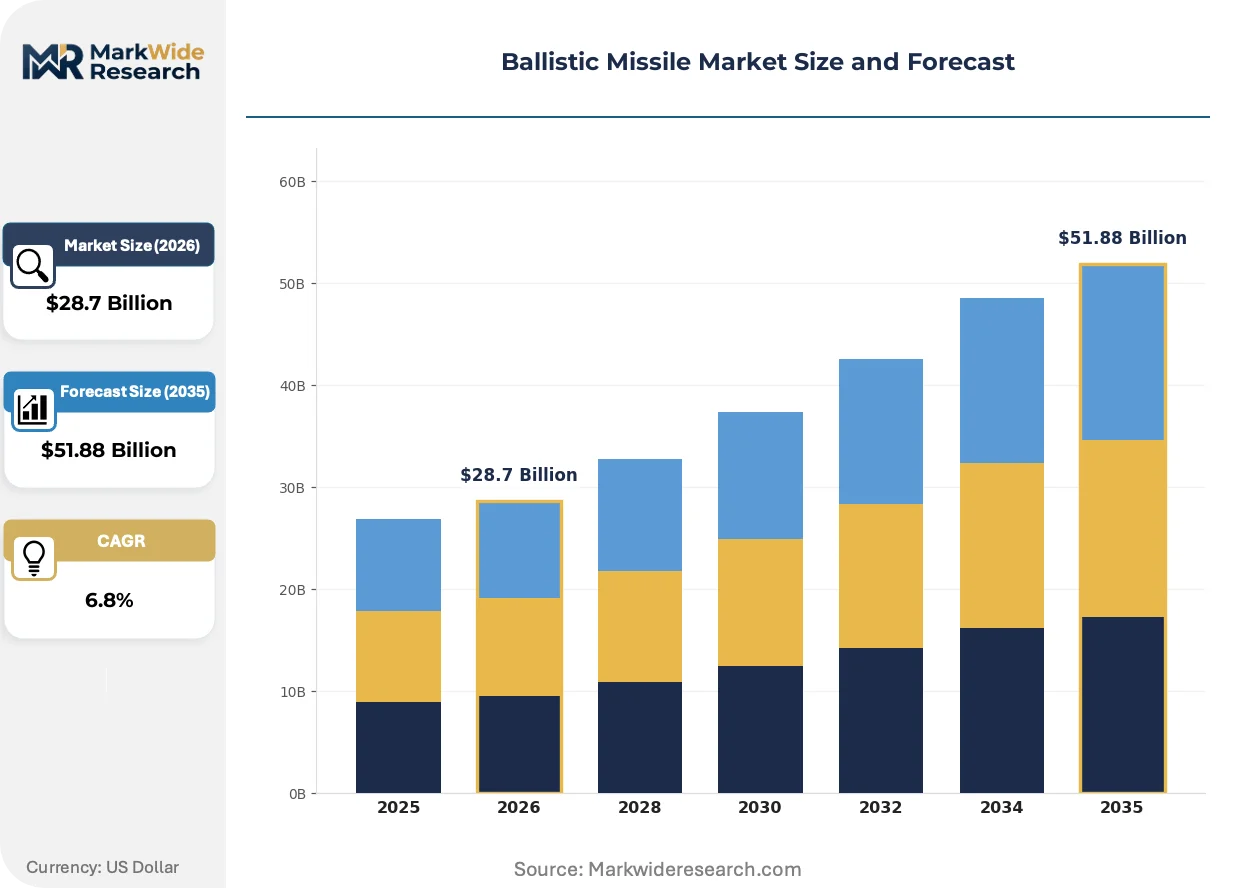
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Land-based, Submarine-launched, Air-launched, Anti-ship Technology: Conventional, Nuclear, Maneuverable, Hypersonic End User: Military, Government, Defense Contractors, Research Institutions Deployment: Fixed, Mobile, Sea-based, Airborne |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, The Boeing Company, RTX Corporation, BAE Systems plc, General Dynamics Corporation, MBDA, Israel Aerospace Industries, China Aerospace Science and Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistic Missile Market Emerging Trajectories
Active development programs are compressing the boundary between traditional ballistic trajectories and aerodynamic maneuverability, forcing contractors to restructure engineering organizations around integrated weapon system architectures rather than discrete component specializations.
Hypersonic glide vehicle technology is bifurcating the strategic systems market into two distinct procurement categories. The US Air Force's AGM-183A and comparable Chinese DF-ZF programs demonstrate operational deployment timelines measured in years rather than decades. Prime contractors are reorganizing propulsion and guidance divisions to serve both legacy ballistic replacement and hypersonic rapid fielding pipelines simultaneously.
REACH chemical restrictions in the European Union are constraining solid propellant formulation options for NATO cooperative programs. The European Chemicals Agency's candidate list of substances of very high concern now includes several legacy curing agents and plasticizers common in ammonium perchlorate composite motors. French and Italian defense ministries are funding alternative binder chemistry research to preserve cross-border supply chain continuity.
Allied defense ministries are consolidating submarine-launched ballistic missile procurement through multi-year framework agreements rather than annual appropriations. The UK Ministry of Defence's Dreadnought program and France's SNLE 3G replacement both employ decade-spanning contracts with cost-plus incentive fee structures. This concentration of buyer power compresses margin recovery for subsystem suppliers while demanding greater upfront engineering investment.
Ballistic Missile Market Segmentation
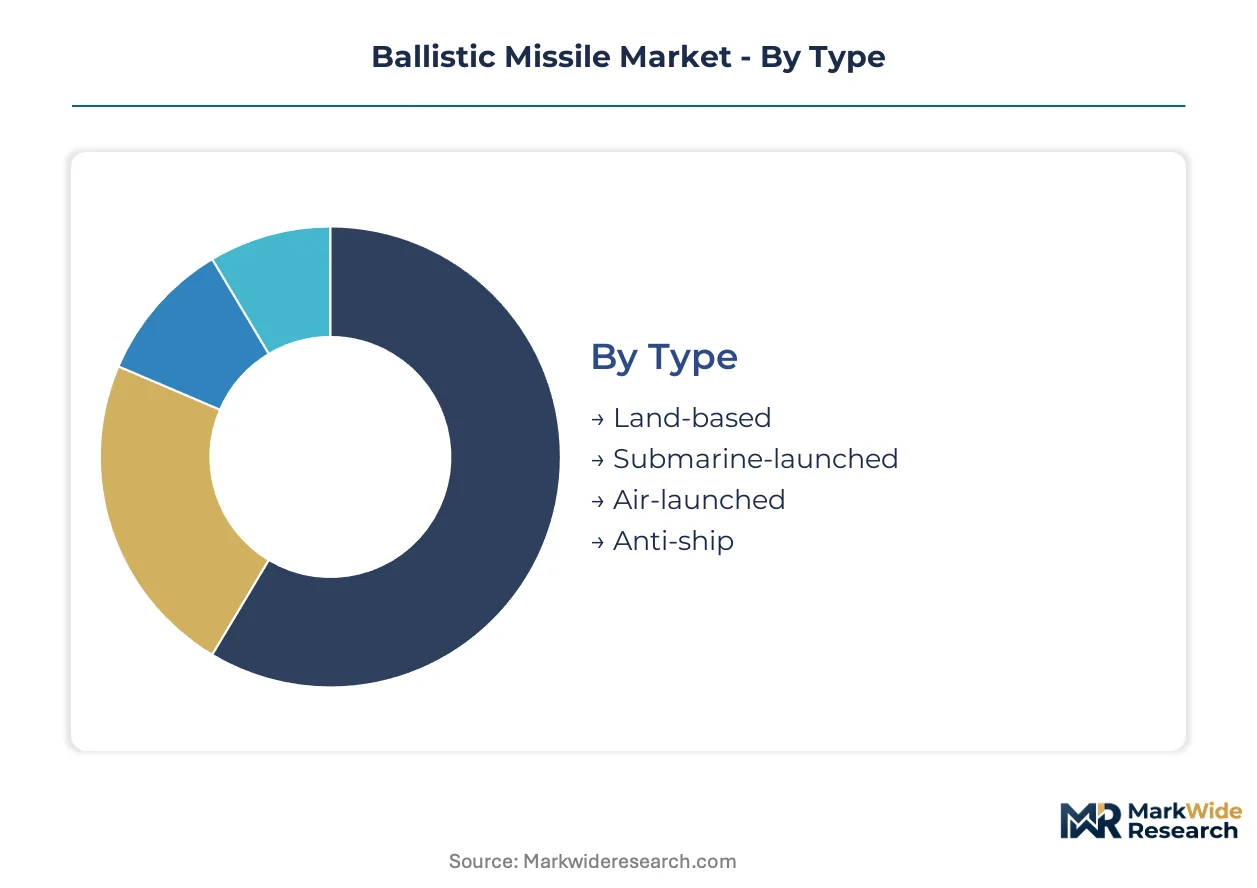
Ballistic missile procurement patterns diverge sharply across basing modes and payload technologies, with each segment carrying distinct certification requirements and capital intensity profiles. Defense ministries structure acquisition budgets around these divisions, creating compartmentalized supplier ecosystems that rarely overlap.
Type:
Regulatory differentiation separates land-based systems governed by national nuclear posture reviews from submarine-launched platforms subject to naval reactor safety protocols and bilateral deterrent cooperation agreements.
- Land-based:Silo and mobile ground systems constitute the backbone of nuclear triads for the United States, Russia, and China. The US Air Force's Ground-Based Strategic Deterrent program channels multi-decade funding through fixed infrastructure hardened against electromagnetic pulse effects.
- Submarine-launched:Sea-based deterrents command the longest development cycles and highest capital intensity per unit. The UK Ministry of Defence and France's DGA coordinate maintenance protocols through shared technical standards that create openings for common subsystem sourcing.
- Air-launched:Strategic bomber delivery systems concentrate in legacy platform integration for the US B-52 and B-2 fleets, with China's H-6N conducting operational trials of air-dropped ballistic payloads.
- Anti-ship:Maritime strike variants prioritize terminal maneuvering against moving targets, with China's DF-21D and comparable systems driving demand for precision guidance packages.
Established volume favors Land-based; emerging adoption favors Anti-ship.
Technology:
Cost tier stratification places hypersonic programs in premium development brackets while conventional ballistic architectures occupy mature production lines with predictable margin structures.
- Conventional:Unitary high-explosive warheads serve precision strike missions against hardened targets. NATO conventional deterrent planning and China's regional escalation management both sustain procurement of non-nuclear ballistic systems.
- Nuclear:Strategic warhead delivery systems face the most stringent integration certification through the US Department of Energy's National Nuclear Security Administration protocols, extending deployment timelines substantially.
- Maneuverable:Post-boost vehicle control and independently targetable reentry vehicles enable multiple aimpoint coverage from single launch events, with mature production lines established across US and Russian industrial bases.
- Hypersonic:Glide vehicle and scramjet propulsion architectures compress development cycles measured in years rather than decades. The US Air Force's AGM-183A and China's DF-ZF programs demonstrate operational deployment trajectories expanding most quickly across all technology categories.
Margin stability favors Conventional; technology transition favors Hypersonic.
End User:
Customer type determines access tier, with sovereign military operators controlling end-to-end system integration while research institutions participate only in component-level development.
- Military:National armed forces operate the complete spectrum of ballistic capabilities from tactical theater systems to intercontinental strategic deterrents, with procurement concentrated in the United States, China, and Russia.
- Government:Civilian defense ministries and nuclear energy agencies manage warhead integration and stockpile stewardship, with the US Department of Energy and comparable Russian entities enclosing access to fissile material handling.
- Defense Contractors:Prime system integrators and subsystem suppliers execute production under government contract, with Lockheed Martin and Northrop Grumman anchoring US modernization pipelines.
- Research Institutions:National laboratories and university-affiliated centers conduct aerothermal protection and guidance algorithm development, with Sandia National Laboratories and comparable facilities limiting full-system access.
Contract volume favors Military; technology access favors Research Institutions.
Deployment:
Maturity gradients separate fixed silo infrastructure with decades of operational history from mobile and airborne platforms requiring continuous relocation logistics.
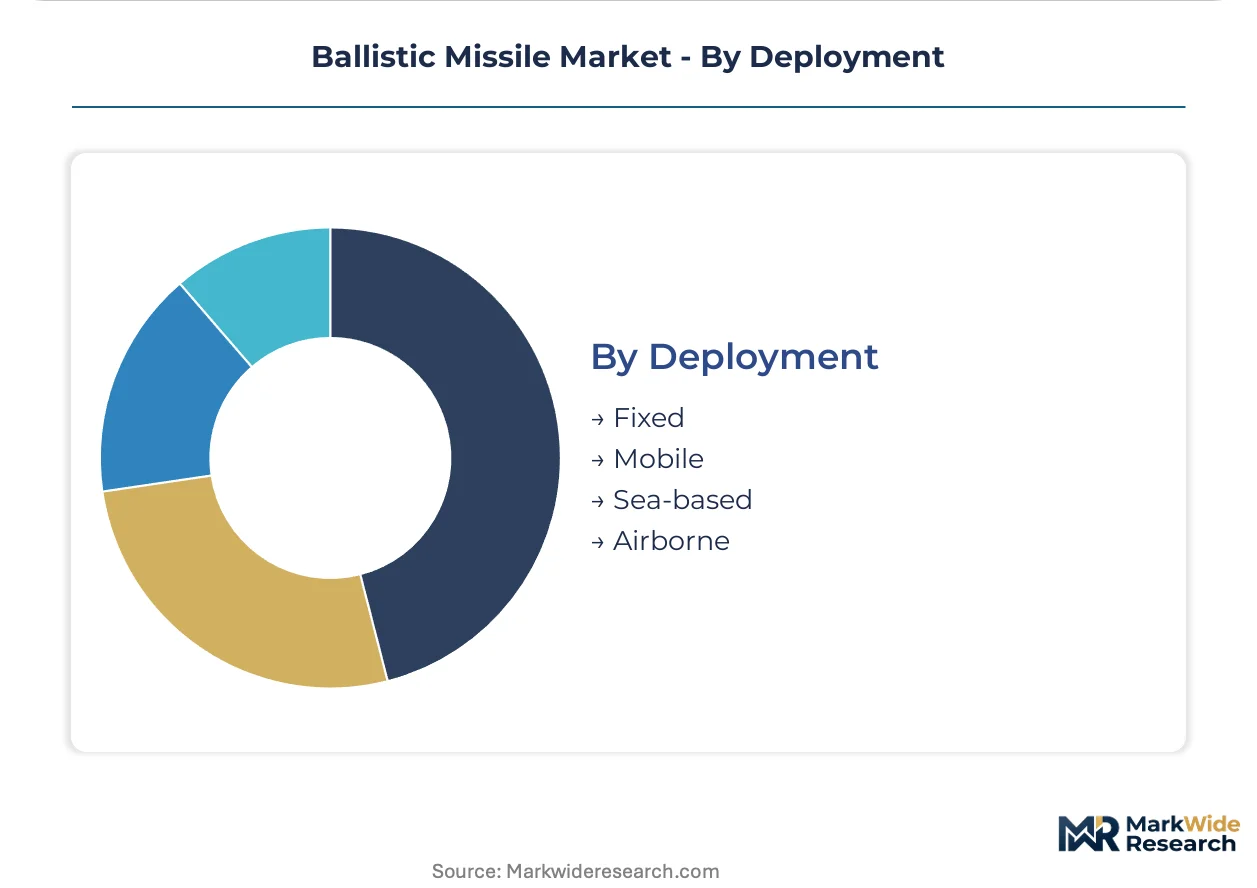
- Fixed:Hardened underground silos provide maximum survivability against conventional attack, with the US Minuteman III replacement and Russian Sarmat programs sustaining this deployment mode's dominance in strategic deterrence.
- Mobile:Road-mobile and rail-based launchers complicate adversary targeting through relocation, with China's DF-41 and Russia's Yars systems demonstrating operational patterns across vast territorial expanses.
- Sea-based:Continuous at-sea deterrence patrols require submarine hull availability rates above sixty percent, with the UK and France both pursuing replacement programs for aging Vanguard and Triomphant classes.
- Airborne:Bomber-delivered systems concentrate in rapid response scenarios below strategic nuclear thresholds, with platform availability constraining operational tempo compared to ground-based alternatives.
Survivability doctrine favors Sea-based; responsiveness requirements favor Airborne.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in ballistic missile systems remain tightly constrained by multilateral technology control regimes, with domestic production mandates dominating procurement patterns across major powers. Sovereign development pathways limit cross-border subsystem trade despite NATO cooperative frameworks. The United States, China, and Russia maintain near-complete autarky in strategic deterrent manufacturing.
United States
The US Department of Defense channels multi-decade funding through the Ground-Based Strategic Deterrent and Columbia-class submarine programs. The Department of Energy's National Nuclear Security Administration encloses warhead integration standards, limiting foreign contractor access. Huntsville, Alabama anchors solid rocket motor production with Northrop Grumman's in-house manufacturing facilities.
China
Beijing's Central Military Commission prioritizes quantitative missile force expansion alongside qualitative hypersonic payload integration. The country's national defense industrial regulator imposes strict technology transfer prohibitions on foreign entities. The Xian and Chengdu aerospace clusters concentrate development of road-mobile and air-launched ballistic systems.
Russia
Roscosmos and the Ministry of Defense sustain Sarmat and Avangard program investments despite international sanctions pressure. The country's national export control authority restricts subsystem sourcing to domestic and select allied suppliers. The Moscow Oblast and Ural Mountain industrial regions maintain thermal protection metallurgy and liquid propulsion manufacturing.
United Kingdom
The Ministry of Defence's Dreadnought program employs decade-spanning contracts for submarine-launched ballistic missile replacement. The UK's national nuclear regulator coordinates with the US Department of Energy on warhead certification protocols. Barrow-in-Furness concentrates submarine hull construction with shared technical standards enabling Franco-British maintenance cooperation.
France
The Direction Générale de l'Armement manages SNLE 3G replacement through cost-plus incentive fee structures with prime contractors. France's national defense procurement agency encloses access to fissile material handling under strict sovereignty protocols. The Île-de-France region houses MBDA and ArianeGroup facilities for missile system integration and solid motor production.
Ballistic Missile Market Vendor Landscape
Concentration sits with prime system integrators possessing end-to-end strategic deterrent capabilities. The vendor base structures around three tiers: nuclear-certified primes with warhead integration access, propulsion and guidance subsystem specialists, and materials suppliers with high-temperature alloy monopolies. Two competitive moves dominate: backward integration into solid rocket motor production and strategic partnerships for hypersonic glide vehicle development.
Within the prime integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the engineering organizations restructured around integrated weapon system architectures. RTX Corporation occupies a position across propulsion and guidance subsystems, extending supplier footprints into allied nuclear deterrent programs. These three anchors represent the competitive archetypes shaping procurement dynamics: strategic system primes, subsystem breadth players, and sovereign-development champions.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| RTX Corporation |
| BAE Systems plc |
| General Dynamics Corporation |
| MBDA |
| Israel Aerospace Industries |
| China Aerospace Science and Technology Corporation |
| Others |
Supply Flow & Price Mechanics
The US Department of Energy's National Nuclear Security Administration qualification protocols gate both supplier eligibility and price stratification simultaneously. Contractors without warhead integration certification face exclusion from premium-tier system contracts regardless of technical capability, compressing margin recovery into narrow propulsion and materials niches.
Pricing Analysis
Military end users anchor contract-based long-term offtake structures across decade-spanning framework agreements. Price differentiation rests on certification level—nuclear-certified primes command substantial premiums over subsystem specialists—and volume scale, with NATO cooperative programs leveraging multi-national procurement for cost compression. Pricing pressure stems from buyer consolidation in the UK and France, where the Ministry of Defence and DGA concentrate submarine-launched ballistic missile replacement into single-source negotiations. Research institutions exhibit highest price sensitivity due to restricted funding pools, while sovereign military operators demonstrate lowest sensitivity given mission-critical procurement mandates.
Supply Chain Analysis
The United States and Russia anchor high-temperature alloy production for reentry vehicle thermal protection systems. China's domestic aerospace clusters feed from ammonium perchlorate composite propellant supply chains, while France and Italy draw from shared European Chemicals Agency-regulated binder chemistry research. Single-source vulnerability concentrates in specialized carbon-carbon composite nosecone fabrication, where aging workforce pipelines constrain capacity expansion. Distribution runs through government-owned prime contractor facilities with classified handling requirements, limiting commercial logistics participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story. Decades-long certification protocols and warhead integration access create switching costs that protect incumbent positions against displacement.
For Market Incumbents: Compound certification depth through backward integration into solid rocket motor production, capturing margin pools currently diverted to specialized metallurgy suppliers. Expand capacity in Huntsville, Alabama and Barrow-in-Furness to anchor NATO cooperative program sourcing. Counter emerging entrant pressure from China's state-backed aerospace clusters by accelerating hypersonic glide vehicle fielding timelines through dedicated rapid-prototyping facilities. For New Entrants and Emerging Players: Anchor in allied nuclear deterrent maintenance protocols, where UK-France technical standard convergence creates openings for shared propulsion subsystem sourcing. India's indigenous submarine deterrent program represents the most penetrable geography, with New Delhi actively soliciting foreign technical assistance in reentry vehicle engineering. Pursue precision conventional strike applications as the go-to-market angle, where maneuverable reentry vehicle technology migrates without nuclear certification barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hypersonic programs, where development cycles compress from decades to years and demand sustained engineering investment. Long-term viability favors acquisition targets with established aerothermal protection engineering talent pipelines and existing National Nuclear Security Administration facility access. Monitor UK Ministry of Defence and French DGA contract award timing as the signal to watch for inflection in submarine-launched ballistic missile replacement funding velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solid Motor Production | Northrop Grumman's in-house manufacturing at Huntsville eliminates supplier margin extraction and accelerates Columbia-class propulsion delivery timelines. |
| Hypersonic Glide Vehicle Rapid Fielding | AGM-183A program compression from decades to years demands restructured engineering organizations serving dual legacy and next-generation pipelines. |
| NATO Cooperative Subsystem Sourcing | UK-France shared technical standards for Dreadnought and SNLE 3G replacement create cross-border propulsion and guidance contract opportunities. |
| Alternative Binder Chemistry Investment | French and Italian defense ministry funding responds to REACH restrictions threatening ammonium perchlorate composite motor supply continuity. |
| Aerothermal Protection Workforce Development | Carbon-carbon composite nosecone fabrication talent scarcity requires dedicated pipeline investment to replace aging specialist retirement waves. |
Methodological Framework
Initial hypotheses were tested against primary input from program managers at prime system integrators, procurement officers in the US Department of Defense and NATO defense ministries, solid rocket motor production engineers, and reentry vehicle thermal protection specialists and refined through secondary validation. Defense budget appropriation documents, US Department of Energy National Nuclear Security Administration certification protocols, NATO nuclear planning guidance, customs and trade data on high-temperature alloy movements, and SEC filings from publicly traded defense contractors anchored quantitative baselines. Bottom-up contract value aggregation triangulated against top-down defense expenditure allocation models.
Variance decomposition across the projection horizon isolates technology transition effects from baseline replacement demand. Segmentation dimensions modeled include basing mode, payload technology, end-user access tier, and deployment maturity gradient, with hypersonic-conventional payload convergence tracked as an industry-specific cross-cutting dynamic. CAGRs derived from contract award velocity analysis and production capacity expansion announcements, with warhead integration certification timelines and solid motor industrial base investments serving as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained US Nuclear Posture Review modernization commitments and continued China Central Military Commission spending acceleration; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in allied defense ministry multi-year framework agreement structures and hypersonic operational deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Global Submarine Launched Missile Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Command Fuzes Market