
 Passive Radar Market | 2026-2036
Passive Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Radar Market Outlook
Defense procurement channels is narrowing as sovereign buyers consolidate vendor lists around proven dual-use suppliers. Hensoldt AG leverages its German manufacturing base to anchor European passive radar contracts. Leonardo S.p.A. competes through integrated electronic warfare portfolios that extend into naval and airborne applications. Thales Group dominates French and NATO-aligned demand with end-to-end sensor-to-shooter architectures.
Passive radar detects and tracks objects by processing reflections from third-party illuminators of opportunity rather than emitting its own signal, typically operating across VHF through L-band frequencies with bistatic geometries spanning tens of kilometers. The technology serves military and civil surveillance operators seeking electromagnetic spectrum concealment against anti-radiation threats. Multistatic configurations lead in defense budgets due to their triangulation accuracy and jamming resilience, while maritime security applications represent the fastest-expanding segment as coastal agencies deploy shore-based networks for vessel tracking without spectrum licensing burdens. Fixed installations still occupy the largest deployment share, though mobile platforms are gaining traction among expeditionary military units requiring rapid theater repositioning.
FAA coordination with military spectrum managers shapes U.S. civil-military interoperability standards for passive radar deployments near commercial aviation corridors. EASA's emerging drone detection mandates and the EU AI Act's algorithmic transparency requirements are pressing European suppliers to document target-classification logic for regulatory audit. Stakeholders must monitor how spectrum allocation rulings from national regulators in Germany, France, and the United Kingdom determine which illuminator bands remain legally exploitable for passive sensing architectures.
Market Dynamics
EU Green Deal emissions standards are compressing power budgets for receiver architectures, forcing manufacturers to redesign signal processing chains around low-consumption FPGA fabrics and liquid-cooled RF front-ends.
Growth Catalysts
- EU Green Deal power mandates:Military procurement offices in Germany and France now require sub-500-watt receiver stations, accelerating adoption of gallium nitride low-noise amplifiers.
- Maritime drone detection:Coastal agencies across Italy and Spain deploy shore-based multistatic networks to track unmanned surface vessels without active emissions that reveal sensor positions.
- Illuminator densification:Commercial 5G base stations and digital broadcast towers proliferate across urban corridors, expanding the exploitable signal landscape for bistatic geometries.
Market Restraints
- Gallium nitride substrate costs:Single-crystal GaN wafers from Japanese suppliers command premiums that inflate receiver front-end bills of materials by substantial margins.
- Signal ambiguity resolution:Dense urban multipath environments degrade target classification confidence, limiting deployment in metropolitan air-defense roles.
- Spectrum reallocation uncertainty:National regulators in Germany and the United Kingdom threaten to repurpose L-band broadcast allocations, jeopardizing long-term illuminator availability.
Strategic Opportunities
- Poland's eastern flank expansion:NATO infrastructure investments position Polish territory as the next major passive radar deployment corridor for border surveillance networks.
- Machine learning target classification:Neural network inference at the edge enables real-time discrimination between drones and birds, opening civil airport markets previously closed to passive sensing.
- Expeditionary mobile platforms:Containerized systems mounted on tactical vehicles address rapid theater repositioning requirements from French and British expeditionary units.
Industry Challenges
- Bistatic radar physicist scarcity:The specialized knowledge required to model non-cooperative illuminator geometries resides in a shrinking cohort of defense laboratory veterans approaching retirement.
- EU AI Act algorithmic documentation:Automated target classification systems must submit decision-logic audit trails to national regulators, extending certification timelines by quarters.
- Legacy active radar integration:NATO command centers demand seamless data fusion between passive detections and existing active radar tracks, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Radar Market |
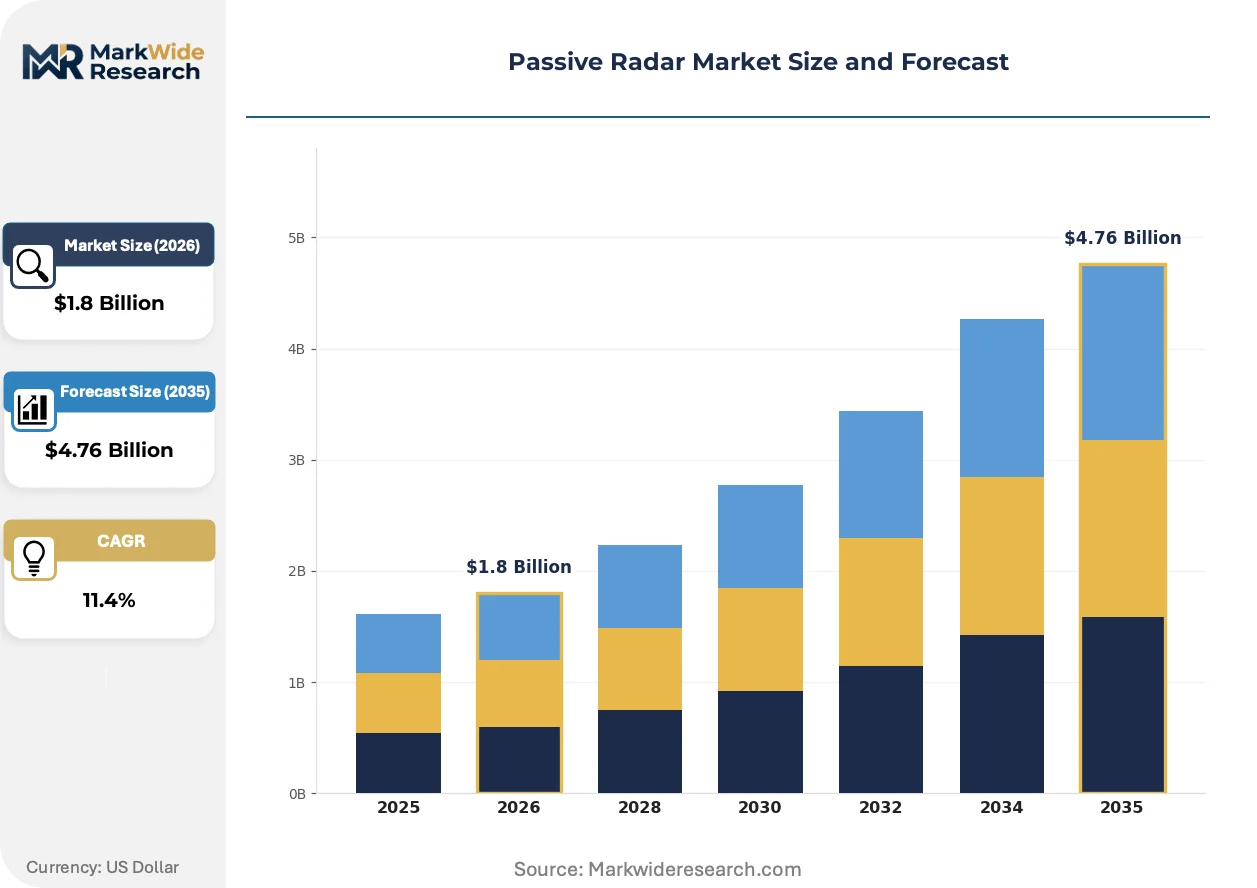
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Multistatic, Monostatic, Coherent, Non-Coherent Application: Aviation Surveillance, Maritime Security, Ground-Based Surveillance, Border Security End User: Military, Civil Aviation, Coastal Agencies, Security Firms Deployment: Fixed Installation, Mobile Installation, Airborne System, Space-Based System |
| Companies Covered | Raytheon Technologies Corporation, Hensoldt AG, Leonardo S.p.A., Indra Sistemas S.A., L3Harris Technologies, Thales Group, Airbus SE, SRC Inc., BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Radar Market Strategic Shifts
Signal processing architectures are migrating toward software-defined radio platforms that decouple hardware refresh cycles from capability upgrades, compressing procurement timelines for defense electronics integrators.
Machine learning inference engines are migrating from centralized server racks to field-programmable gate arrays embedded at the antenna array, enabling sub-second target classification without backhaul latency. Naval procurement offices in France and Italy prioritize these edge-computing configurations for frigate-based deployments where satellite bandwidth remains contested. The shift is compressing the competitive advantage of vendors with legacy centralized-processing product lines.
EASA's emerging drone detection mandates for critical infrastructure operators are mandating passive radar integration alongside traditional active sensors at civil airports across Germany, France, and the Netherlands. The regulation forces system architects to document electromagnetic compatibility between passive receivers and existing primary surveillance radars. Category C and D aerodromes in the United Kingdom face the steepest compliance deadlines, driving concentrated procurement activity through 2027.
Defense buyers are consolidating vendor lists around dual-use suppliers with proven civilian aviation credentials, displacing specialized military-only contractors from tender shortlists. The United Kingdom's Strategic Command now requires passive radar bidders to demonstrate prior FAA or EASA certification for airport surface surveillance. This behavioral shift privileges European electronics conglomerates with diversified civil-military portfolios over pure-play defense startups.
Passive Radar Market Segmentation
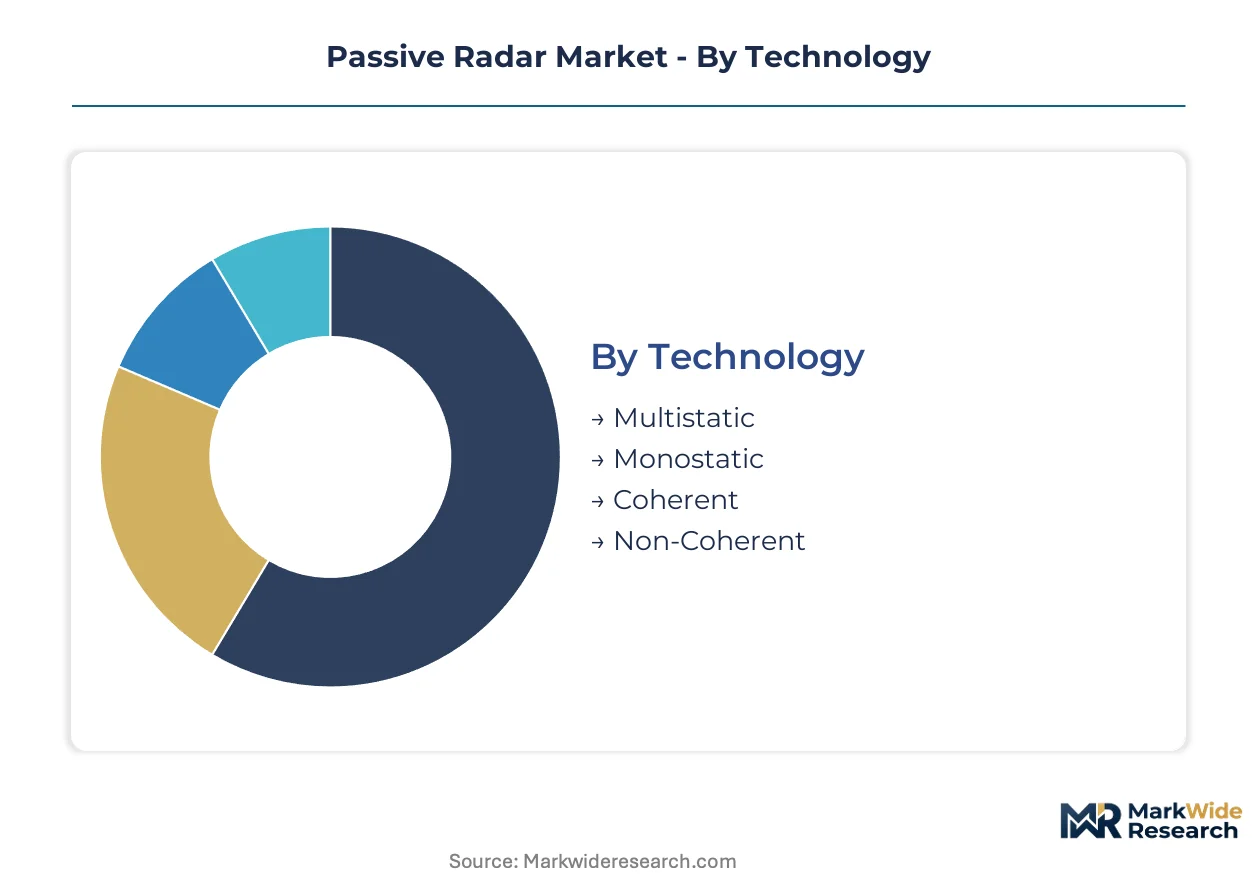
Passive radar architectures vary sharply in signal processing complexity and field service requirements. Technicians trained on multistatic geometries command premium deployment rates, while monostatic variants require less specialized calibration support.
Technology:
After-sales service intensity climbs with receiver synchronization complexity, driving vendor investment in regional field engineering teams.
- Multistatic:Triangulates targets across three or more spatially separated receivers for jamming resilience and geolocation precision. Defense procurement offices in Germany and France prioritize these configurations for NATO border surveillance networks, despite demanding biannual calibration cycles that inflate total cost of ownership.
- Monostatic:Employs single-receiver bistatic geometry with simplified illuminator-of-opportunity processing. Coastal agencies across Italy and Spain favor this architecture for rapid shore-based deployment where maintenance infrastructure remains limited.
- Coherent:Preserves phase information across signal paths to enable Doppler-based target discrimination. Military end users in Poland require coherent processing for drone detection contracts.
- Non-Coherent:Discards phase data in favor of amplitude-only detection, reducing computational load. Civil aviation operators in the Netherlands deploy non-coherent systems for cost-sensitive airport perimeter monitoring.
Multistatic configurations hold the largest share; momentum sits with coherent processing as drone detection specifications tighten.
Application:
Application selection determines illuminator density requirements and spectrum licensing obligations.
- Maritime Security:Tracks surface vessels using digital broadcast and cellular tower reflections without revealing sensor positions to hostile observers. Shore-based networks across Spain and Italy represent the expanding use case as unmanned surface vessel threats multiply in Mediterranean corridors.
- Aviation Surveillance:Detects aircraft near commercial corridors by exploiting DVB-T2 and 5G NR downlink signals. EASA mandates at German and French Category C aerodromes are compressing procurement timelines for integrated passive-active surveillance architectures.
- Ground-Based Surveillance:Monitors vehicle and personnel movement across extended perimeters using FM radio illuminators. Security firms in the United Kingdom deploy these for critical infrastructure protection.
- Border Security:Detects low-altitude penetrations in electromagnetically contested environments. Polish eastern flank installations under NATO infrastructure investment represent concentrated demand.
Aviation surveillance commands the largest deployment base; maritime security is expanding most quickly as coastal agency budgets reallocate toward asymmetric threat detection.
End User:
End user type dictates security clearance requirements and export control classification.
- Military:Requires TEMPEST-hardened receivers and NATO-standard data interfaces. French and British expeditionary units prioritize containerized mobile platforms for rapid theater repositioning.
- Civil Aviation:Demands EASA-certified electromagnetic compatibility with primary surveillance radar. German airport operators face the steepest compliance deadlines under emerging drone detection mandates.
- Coastal Agencies:Operates under national maritime authority budgets with limited spectrum licensing. Italian Guardia Costiera deployments emphasize shore-based multistatic networks.
- Security Firms:Procures commercial-off-the-shelf systems for private critical infrastructure protection. United Kingdom nuclear facility operators represent a concentrated customer cluster.
Military end users dominate procurement volume; civil aviation shows the steepest expansion trajectory as regulatory mandates proliferate.
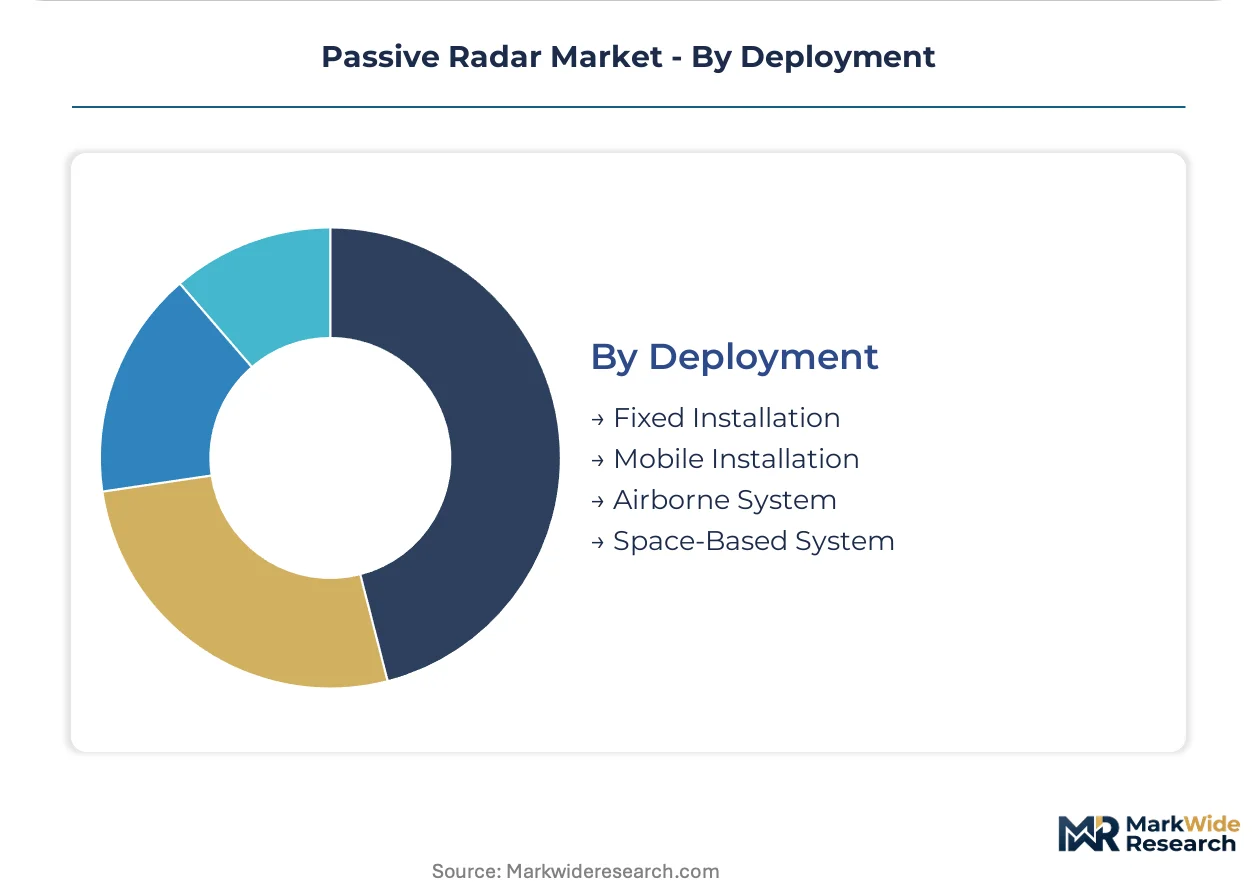
Deployment:
Deployment mode constrains power budget and antenna aperture trade-offs.
- Fixed Installation:Maximizes baseline length and integration time for detection sensitivity. Permanent shore-based networks across the United Kingdom and Germany constitute the established installed base.
- Mobile Installation:Containerized or vehicle-mounted systems sacrifice aperture for repositioning speed. French and British expeditionary units drive specification requirements.
- Airborne System:Embeds receivers on manned or unmanned platforms for forward-deployed sensing. Italian and French naval aviation programs evaluate these for carrier strike group protection.
- Space-Based System:Orbital receivers exploit terrestrial illuminators for wide-area coverage. Research programs within European Space Agency frameworks explore feasibility.
Fixed installations retain the largest share; airborne systems are gaining share fastest as contested logistics scenarios reshape military planning assumptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Baltic Pipe interconnector underwrites Poland's emergence as NATO's eastern flank surveillance hub. German port infrastructure at Wilhelmshaven and Bremerhaven anchors maritime passive radar deployment corridors. French nuclear facility perimeters drive civil-military dual-use demand clusters.
Germany
Bundeswehr procurement offices prioritize sub-500-watt receiver stations for border surveillance networks. EU Green Deal mandates from Brussels compel gallium nitride low-noise amplifier adoption across defense electronics tenders. The Munich-Stuttgart corridor concentrates Hensoldt AG manufacturing and subsystem integration activity.
United Kingdom
Strategic Command requirements for containerized mobile platforms reshape expeditionary unit specifications. EASA drone detection deadlines at Category C and D aerodromes compress procurement timelines through 2027. The Bristol-Bath electronics cluster hosts BAE Systems passive radar development programs.
France
Naval procurement offices prioritize edge-computing FPGA configurations for frigate-based deployments. EU AI Act algorithmic transparency rules extend certification timelines for automated target classification systems. The Toulouse aerospace cluster anchors Thales Group sensor-to-shooter architecture integration.
Poland
NATO infrastructure investments position Polish territory for multistatic border surveillance network expansion. The country's national defense regulator aligns spectrum allocation with allied electromagnetic compatibility standards. The Tri-City metropolitan area concentrates coastal agency deployments for unmanned surface vessel tracking.
Italy
Guardia Costiera budgets reallocate toward shore-based multistatic networks for Mediterranean corridor monitoring. EASA emerging mandates for critical infrastructure drone detection force airport operator compliance investments. The Rome-Florence defense electronics corridor hosts Leonardo S.p.A. integrated electronic warfare portfolio development.
Passive Radar Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in RF front-end and signal processing modules. The vendor base concentrates around dual-use suppliers with proven civilian aviation credentials, displacing specialized military-only contractors. Two strategic archetypes dominate: diversified electronics conglomerates with civil-military portfolios, and sovereign defense champions anchored to national procurement channels. Competitive moves center on strategic partnerships with illuminator infrastructure operators and geographic expansion into NATO eastern flank territories.
Within the diversified conglomerate tier, Raytheon Technologies Corporation and Thales Group exemplify platform integrators with end-to-end sensor architectures. Hensoldt AG occupies a position among sovereign champions leveraging German manufacturing bases for European contract anchoring. Leonardo S.p.A. represents the integrated electronic warfare specialist archetype extending into naval and airborne applications.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Hensoldt AG |
| Leonardo S.p.A. |
| Indra Sistemas S.A. |
| L3Harris Technologies |
| Thales Group |
| Airbus SE |
| SRC Inc. |
| BAE Systems |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's container rate volatility shapes cost structures for gallium nitride substrate shipments from Japanese suppliers to German receiver manufacturers, compressing margins at the RF front-end tier while enabling price differentiation between volume defense procurement and small-batch coastal agency orders.
Pricing Analysis
Three-tier pricing structure across TEMPEST-hardened military configurations, EASA-certified civil aviation systems, and commercial-off-the-shelf security firm packages separates premium receiver stations from mid-range shore-based networks from economy perimeter monitors. Price differentiation hinges on certification grade and after-sales service bundling, with biannual calibration contracts commanding substantial premiums over hardware-only transactions. Cost compression in the civil aviation tier is intensifying as EASA drone detection mandates force airport operators toward integrated passive-active architectures. Security firms exhibit highest price sensitivity due to limited capital expenditure budgets, while military procurement offices prioritize electromagnetic resilience over unit cost.
Supply Chain Analysis
Tariff exposure between Japan and Germany dominates supply chain risk for single-crystal GaN wafer procurement, with alternative sourcing from South Korean substrate vendors remaining underdeveloped for defense-grade specifications. Manufacturing concentrates in Germany, France, and the United Kingdom for final system integration, while liquid-cooled RF front-end components draw from Japanese and South Korean specialist suppliers. Distribution runs through sovereign defense procurement channels with NATO-standard data interface requirements, supplemented by direct coastal agency contracting for maritime security deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities concentrate in biannual multistatic calibration contracts and edge-computing FPGA firmware update subscriptions, both expanding faster than receiver hardware sales as coastal agencies and expeditionary units prioritize operational availability over capital replacement cycles.
For Market Incumbents: Insulate market position through backward integration into gallium nitride low-noise amplifier design capabilities and captive field engineering teams across Poland and the Baltic states. The scarcity of bianstic radar physicists approaching retirement threatens long-term service delivery quality, making specialist workforce retention the critical defensive lever against emerging software-defined radio entrants. For New Entrants and Emerging Players: Mid-market coastal agencies in Mediterranean corridors represent the most penetrable entry point, with Italian Guardia Costiera and Spanish maritime authority budgets reallocating toward unmanned surface vessel detection without legacy active radar integration burdens. Machine learning target classification modules for bird-drone discrimination at civil airports offer a second white-space vector. Go-to-market positioning should emphasize rapid shore-based deployment with minimal biannual calibration requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates seeking to divest non-core passive radar divisions lacking civil aviation certification credentials. Long-term viability across the analysis window rests on dual-use supplier status with proven EASA or FAA airport surface surveillance deployments. The signal to watch is NATO eastern flank infrastructure investment announcements indicating multistatic border surveillance network expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing FPGA Migration | Naval procurement offices in France prioritize sub-second target classification without satellite backhaul dependency. |
| Gallium Nitride Amplifier Integration | EU Green Deal sub-500-watt mandates force receiver front-end redesign around low-consumption architectures. |
| Machine Learning Classification Module Development | EASA drone detection mandates at German Category C aerodromes require real-time bird-drone discrimination capabilities. |
| Containerized Mobile Platform Engineering | French and British expeditionary units demand rapid theater repositioning for contested logistics scenarios. |
| Illuminator Infrastructure Partnership | 5G base station densification across urban corridors expands exploitable signal landscape for bistatic geometries. |
Study Parameters
Initial hypotheses were tested against primary input from defense procurement officers, coastal agency technical directors, RF front-end manufacturing engineers, and airport surface surveillance managers, and refined through secondary validation against NATO standardization documents, EASA emerging mandate drafts, EU Green Deal implementation guidelines, and customs trade data for gallium nitride substrate flows. Bottom-up segment sizing triangulated against top-down defense electronics budget allocations across the analysis window.
Demand-supply-balance framing anchored the quantitative model, with segmentation dimensions spanning multistatic-monostatic-coherent-non-coherent technology variants, maritime-aviation-ground-border application clusters, and fixed-mobile-airborne-space deployment modes. CAGRs derived from deployment pipeline visibility across NATO infrastructure investments and EASA regulatory compliance deadlines. Industry-specific inputs included illuminator density projections from 5G rollout schedules and bistatic radar physicist workforce demographics.
Macroeconomic conditions sit as an overlay; deviation in defense budget allocation priorities or spectrum reallocation rulings from German and United Kingdom regulators would shift the trajectory. Forecasts reflect documented assumptions regarding EU AI Act certification timeline extensions and gallium nitride substrate cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Global Radar Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
UXO Detection Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Military Manportable Surveillance Radar Market