
 Anti-Jamming Market | 2026-2036
Anti-Jamming Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Jamming Market Analysis
Civil aviation and telecommunications infrastructure is decoupling from legacy military-only demand patterns as commercial GPS dependency deepens. Raytheon Technologies Corporation leverages its radar cross-section expertise to anchor integrated electronic warfare portfolios. BAE Systems sustains long-term platform integration contracts with European defense ministries through specialized anti-jam module production. Thales Group competes across dual-use spectrum management, positioning its Galileo-compatible receivers for both defense and transport applications.
Anti-jamming systems employ signal processing techniques including frequency hopping sequences, null-steering antenna arrays, and adaptive filtering algorithms to suppress intentional electromagnetic interference across L-band and S-band frequencies. These systems protect position-navigation-timing services in contested spectrum environments where adversarial jamming threatens operational continuity. Frequency hopping technology dominates current procurement volumes due to proven interoperability with existing military waveforms, while beamforming solutions represent the fastest-growing segment as active electronically scanned arrays shrink in cost and size. Civil applications remain comparatively nascent, though margin pools concentrate in integrated systems combining hardware receivers with real-time threat detection software.
The U.S. Department of Defense mandates Military Standard 188-164B compliance for satellite communications terminals, while the EU's Radio Equipment Directive imposes electromagnetic compatibility testing on commercial navigation receivers. NATO's Standardization Agreement 4658 further shapes interoperability requirements for coalition electronic warfare operations. Stakeholders must monitor emerging national spectrum resilience frameworks and decide whether to prioritize software-defined architectures or dedicated hardware solutions as regulatory scopes diverge between defense-critical and commercial-critical infrastructure classifications.
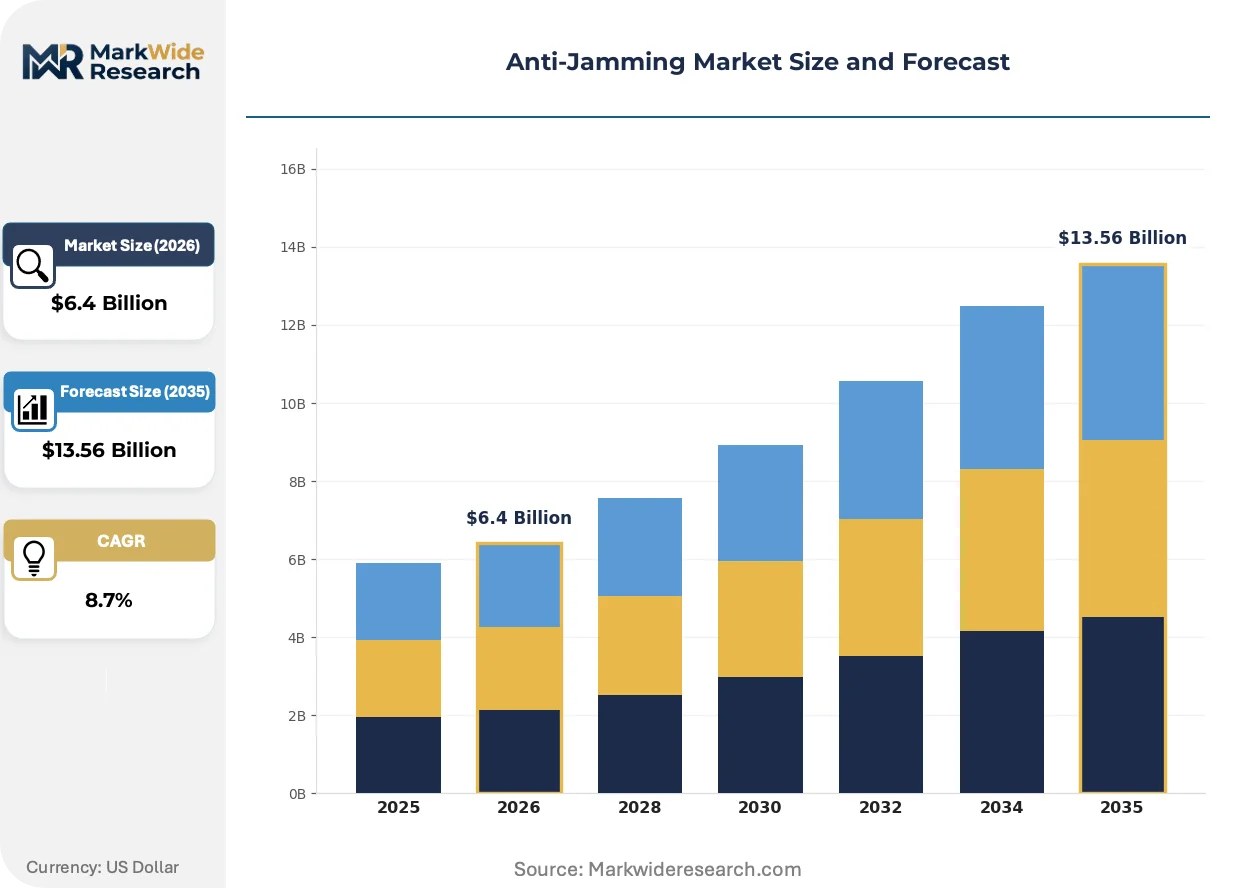
Market Dynamics
Defense procurement cycles are compressing as NATO member states accelerate electronic warfare modernization, forcing anti-jamming suppliers to recalibrate production timelines around military readiness mandates rather than traditional platform replacement schedules.
Growth Catalysts
- Military Standard 188-164B:The U.S. Department of Defense mandate for satellite communications terminal compliance creates a binding procurement floor across defense contractor supply chains.
- Autonomous platform proliferation:Unmanned ground vehicles and maritime drones require GPS-denied navigation systems, expanding addressable hardware volumes beyond crewed platforms.
- Galileo receiver compatibility:Thales Group and European integrators leverage EU positioning infrastructure to penetrate dual-use transport and defense applications simultaneously.
Market Restraints
- Gallium nitride substrate costs:Active electronically scanned arrays depend on specialized semiconductor materials with concentrated supply from East Asian foundries.
- ITAR classification friction:U.S. State Department export controls restrict beamforming algorithm transfers to allied defense programs, fragmenting R&D collaboration.
- Software-defined radio substitution:General-purpose signal processing platforms threaten dedicated anti-jam hardware margins in cost-sensitive civil applications.
Strategic Opportunities
- Critical infrastructure protection:The EU's Radio Equipment Directive creates mandatory electromagnetic resilience testing for commercial aviation and telecommunications receivers.
- Urban air mobility:Electric vertical take-off and landing aircraft operators in Israel and the United Kingdom seek integrated navigation protection for low-altitude corridor operations.
- Real-time threat detection convergence:Machine learning inference at the edge is unifying hardware receivers with predictive jamming classification software.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave design expertise concentrates in defense hubs around Boston and Tel Aviv, constraining supplier scaling.
- NATO Standardization Agreement 4658 compliance:Coalition interoperability testing extends certification timelines for multi-national platform integrations.
- Legacy waveform integration:Frequency hopping sequences must maintain backward compatibility with fielded military radios, complicating algorithm modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Jamming Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Frequency Hopping, Direct Sequence Spread Spectrum, Adaptive Array, Beamforming Application: Military Communication, Aerospace, Telecommunications, Civil Applications End User: Defense Forces, Commercial Enterprises, Government Agencies, Research Institutions Solution: Hardware Solutions, Software Solutions, Integrated Systems, Consulting Services |
| Companies Covered | Raytheon Technologies Corporation, Lockheed Martin Corporation, BAE Systems, Thales Group, L3Harris Technologies, Northrop Grumman Corporation, Cobham, Israel Aerospace Industries, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Jamming Market Emerging Trajectories
Signal processing architectures are converging with artificial intelligence inference engines, compressing the traditional separation between analog front-end hardware and digital threat response systems.
Adaptive null-steering antenna arrays are unifying spatial filtering with real-time beam pattern optimization. Defense integrators in the United Kingdom and Israel are embedding these arrays into compact unmanned platforms previously constrained by size and power budgets. This unification is compressing the performance gap between fixed-installation and mobile anti-jam systems.
REACH chemical restrictions and emerging EU spectrum resilience frameworks are mandating lead-free solder and recyclable RF components in commercial navigation receivers. Manufacturers serving dual-use markets must maintain parallel production lines to satisfy divergent defense and civil certification pathways. Transport sector suppliers face the steepest compliance cost escalation.
Platform operators are consolidating vendor relationships around integrated electronic warfare portfolios rather than discrete component procurement. System integrators now bundle anti-jam modules with radar warning receivers and countermeasure dispensers under unified support contracts. This consolidation is most pronounced in U.S. Army and Marine Corps ground vehicle modernization programs.
Anti-Jamming Market Segmentation
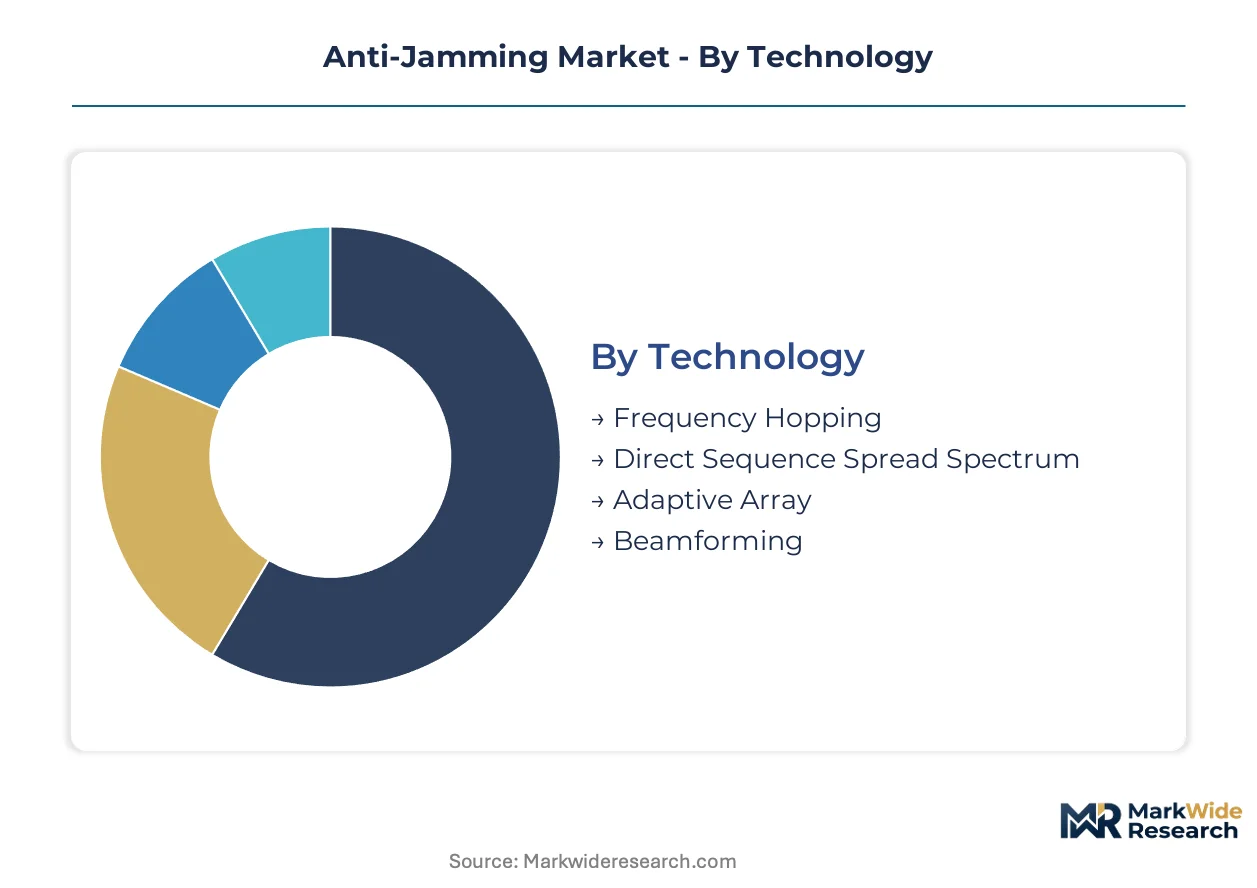
Anti-jamming procurement patterns diverge sharply across defense, civil infrastructure, and commercial aviation verticals, with each buyer category imposing distinct certification burdens and interoperability requirements. Technology selection follows platform constraints rather than pure performance optimization, compressing supplier margins in cost-sensitive segments.
Technology:
Defense contractors prioritize proven waveform compatibility over spectral efficiency, while civil operators weight power consumption and form factor more heavily in platform integration decisions.
- Frequency Hopping:Rapid pseudo-random switching between transmission frequencies masks signal presence from narrowband jammers. NATO procurement cycles favor this technology for backward compatibility with legacy military radios fielded across member state arsenals.
- Beamforming:Active electronically scanned arrays dynamically steer nulls toward interference sources while maintaining gain on desired satellites. Israeli and United Kingdom defense integrators embed these arrays into unmanned platforms where size and power constraints previously excluded spatial filtering solutions.
- Direct Sequence Spread Spectrum:Spreading codes distribute signal energy below noise floors, resisting broadband jamming through processing gain.
- Adaptive Array:Multi-element antennas adjust weights in real-time to suppress interference without prior knowledge of threat waveforms.
Frequency Hopping leads volumes today; Beamforming is gaining share fastest.
Application:
Platform certification timelines stretch longest in aerospace, where FAA and EASA airworthiness standards impose multi-year validation cycles on navigation protection systems.
- Military Communication:Satellite terminals protecting strategic and tactical networks demand MIL-STD-188-164B compliance as a non-negotiable procurement threshold. United States Army and Marine Corps ground vehicle modernization programs bundle these systems with electronic warfare suites under unified vendor contracts.
- Aerospace:Commercial aviation receivers integrate anti-jam modules to maintain GPS integrity during approach and landing in contested electromagnetic environments. EU Radio Equipment Directive mandates are tightening electromagnetic resilience testing for transport category aircraft operating across European airspace.
- Telecommunications:Cellular base stations and timing networks require protection against intentional interference and accidental spectrum congestion.
- Civil Applications:Maritime navigation and precision agriculture represent emerging demand pockets where cost sensitivity limits hardware penetration.
Military Communication dominates current procurement value; Aerospace exhibits the steepest expansion trajectory as civil aviation mandates proliferate.
End User:
Budget cycle predictability separates defense procurement from commercial enterprise buying patterns, with government agencies occupying an intermediate position on funding stability.
- Defense Forces:NATO member state electronic warfare modernization programs operate on compressed readiness timelines rather than traditional platform replacement schedules. Multi-year platform integration contracts with BAE Systems and Thales Group lock in supplier relationships across European ministries.
- Commercial Enterprises:Telecommunications carriers and aviation operators prioritize total cost of ownership over initial acquisition price, favoring integrated systems with predictive maintenance software.
- Government Agencies:Critical infrastructure protection mandates in the United States and European Union are expanding addressable markets beyond traditional defense boundaries.
- Research Institutions:Academic and government laboratories test algorithmic approaches before transfer to production hardware.
Defense Forces anchor procurement volumes; Commercial Enterprises are climbing the fastest as civil infrastructure protection mandates expand.
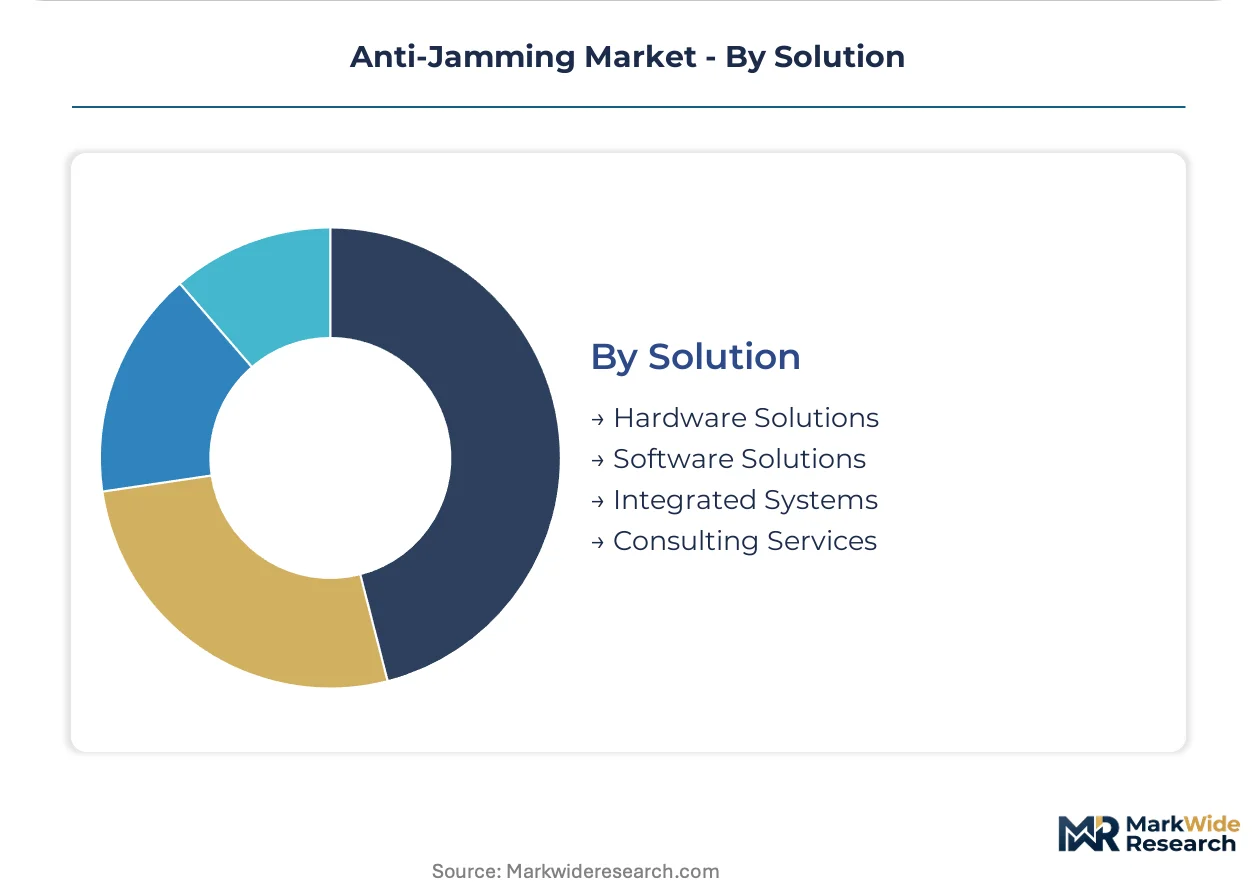
Solution:
Margin concentration follows integration depth, with pure hardware plays facing substitution pressure from software-defined radio platforms.
- Integrated Systems:Bundled hardware receivers with real-time threat detection software command premium pricing in applications requiring sub-second jamming classification. Machine learning inference at the edge unifies analog front-end processing with predictive response algorithms.
- Hardware Solutions:Dedicated anti-jam modules with fixed signal processing architectures retain cost advantages in high-volume military procurement.
- Software Solutions:Algorithm licensing and firmware updates generate recurring revenue streams from fielded platforms.
- Consulting Services:Spectrum resilience audits and certification support address regulatory compliance burdens under EU Radio Equipment Directive and emerging United States national frameworks.
Hardware Solutions leads shipment volumes today; Integrated Systems is expanding most quickly as platform operators consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with established defense procurement frameworks and lower certification friction, creating a compliance-arbitrage gradient that favors established Western manufacturing clusters over emerging entrants.
United States
The Department of Defense compresses procurement cycles for electronic warfare modernization, accelerating satellite communications terminal replacement. Military Standard 188-164B mandates bind contractor supply chains to domestic sourcing requirements. Defense hubs around Boston and the Washington corridor concentrate RF engineering talent for beamforming algorithm development.
United Kingdom
Ministry of Defence platform integration contracts sustain long-term supplier relationships for specialized anti-jam module production. NATO Standardization Agreement 4658 shapes interoperability testing for coalition electronic warfare operations. Defense clusters in Bristol and Stevenage host unmanned platform integrators embedding adaptive null-steering arrays.
Israel
Israel Defense Forces prioritize GPS-denied navigation for autonomous maritime and ground platforms, expanding hardware volumes beyond crewed systems. National spectrum resilience frameworks tighten electromagnetic compatibility requirements for critical infrastructure. Tel Aviv-area engineering centers drive compact active electronically scanned array miniaturization for drone applications.
Germany
Bundeswehr electronic warfare programs align with NATO readiness mandates, forcing accelerated production timelines. EU Radio Equipment Directive compliance costs escalate for dual-use manufacturers maintaining parallel defense and civil certification pathways. Bavarian and Baden-Württemberg industrial clusters balance automotive precision manufacturing with defense subcontractor relationships.
France
Direction Générale de l'Armement consolidates vendor relationships around integrated electronic warfare portfolios rather than discrete component procurement. Galileo receiver compatibility requirements penetrate both defense and transport applications through Thales Group platform integration. Paris-Saclay research corridors test machine learning inference for real-time jamming classification at the network edge.
Anti-Jamming Market Vendor Landscape
Platform integration contracts dominate the current landscape as system bundling displaces discrete component procurement. The vendor base concentrates around five major defense conglomerates with established military relationships, supplemented by specialized RF engineering boutiques in Israel and the United Kingdom. Two strategic archetypes prevail: full-spectrum electronic warfare integrators pursuing unified support contracts, and component specialists defending niche positions in antenna array miniaturization. M&A activity and multi-year platform integration partnerships represent the dominant competitive moves, compressing opportunities for standalone hardware entrants.
Within the full-spectrum integrator tier, Raytheon Technologies Corporation and BAE Systems exemplify archetypes anchored in radar cross-section expertise and European defense ministry relationships respectively. Thales Group occupies a dual-use positioning that leverages Galileo infrastructure to span defense and civil transport applications simultaneously. These three entities represent the competitive core around which smaller specialists orbit, seeking entry points through unmanned platform miniaturization or software-defined radio substitution threats.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Lockheed Martin Corporation |
| BAE Systems |
| Thales Group |
| L3Harris Technologies |
| Northrop Grumman Corporation |
| Cobham |
| Israel Aerospace Industries |
| Leonardo S.p.A. |
| Others |
Supply Flow & Price Mechanics
Gallium nitride substrate costs cascade through three distinct pricing tiers, with defense-grade active electronically scanned arrays commanding premiums over commercial navigation modules as East Asian foundry concentration limits supplier negotiation leverage.
Pricing Analysis
Distributor margins compress most severely at the civil aviation tier, where EU Radio Equipment Directive compliance costs force three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on MIL-STD-188-164B certification grade and volume scale, with NATO procurement aggregations securing substantial direct-to-OEM discounts. Cost compression in the civil telecommunications segment is intensifying because software-defined radio platforms threaten dedicated hardware margins. Commercial enterprises exhibit highest price sensitivity, while defense forces prioritize performance over acquisition cost.
Supply Chain Analysis
Photoresist and specialized semiconductor substrate supply rests on Japanese, Taiwanese, and South Korean specialty chemical producers, with gallium nitride wafers and microwave-grade laminates forming critical input dependencies. Single-source vulnerability concentrates in East Asian foundries serving active electronically scanned array production. Distribution runs through defense contractor primes and specialized RF component distributors, with long-term platform integration contracts locking in volume allocations ahead of spot market exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement shifts toward integrated systems bundling hardware receivers with real-time threat detection software rather than discrete component sourcing.
For Market Incumbents: To counter software-defined radio substitution threats, Raytheon Technologies Corporation and BAE Systems should deepen backward integration into gallium nitride substrate supply through captive foundry partnerships or long-term offtake agreements with Taiwanese suppliers. Certification investment in NATO Standardization Agreement 4658 interoperability testing creates switching-cost barriers against emerging entrants. For New Entrants and Emerging Players: Urban air mobility operators in Israel and the United Kingdom present the most penetrable white-space target, with electric vertical take-off and landing aircraft manufacturers seeking compact anti-jam modules for low-altitude corridor operations. Precision agriculture and maritime navigation represent secondary civil application entry points where cost sensitivity currently limits incumbent penetration. A direct-to-OEM channel strategy bypassing defense contractor primes accelerates initial traction. For Investors and Strategic Acquirers: Roll-up economics work for specialized RF engineering boutiques because platform integration contracts increasingly favor vendors offering unified electronic warfare portfolios over discrete component suppliers. Five-to-ten year viability hinges on machine learning inference capabilities at the network edge. The signal to watch is ITAR classification relaxation enabling cross-border algorithm collaboration.| Strategic Initiative | Industry Significance |
|---|---|
| Beamforming Algorithm Development | Active electronically scanned array miniaturization unlocks unmanned platform integration for Israeli and UK defense contractors. |
| Galileo Receiver Compatibility Investment | Dual-use positioning infrastructure penetration enables Thales Group to span defense and civil transport applications simultaneously. |
| Machine Learning Edge Inference Integration | Real-time jamming classification software unifies analog front-end hardware with predictive threat response systems. |
| Critical Infrastructure Protection Certification | EU Radio Equipment Directive compliance creates mandatory electromagnetic resilience testing revenue for commercial aviation suppliers. |
| Gallium Nitride Supply Security Partnership | East Asian foundry concentration risk mitigation secures substrate allocation for NATO electronic warfare modernization programs. |
Methodological Framework
Coverage spans the United States, the United Kingdom, Israel, Germany, and France, with primary inputs from each combining interviews with RF engineering directors, defense procurement officers, electronic warfare program managers, and civil aviation certification specialists with secondary validation against U.S. Department of Defense budget submissions, NATO standardization documents, EU regulatory filings, and customs trade data. Bottom-up platform deployment estimates triangulate against top-down defense expenditure allocations.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with segmentation modeling spanning technology type, application vertical, end-user category, and solution architecture. CAGRs derive from fitted growth curves applied to defense procurement cycle data and civil infrastructure mandate implementation timelines. Industry-specific forecast inputs include NATO readiness mandate acceleration schedules and EU spectrum resilience framework adoption curves.
Revisions become necessary when ITAR classification regimes shift, gallium nitride supply disruptions materialize, or software-defined radio performance thresholds cross hardware substitution boundaries. Forecasts reflect documented assumptions about defense budget continuity and regulatory implementation pacing. A small set of named triggers—export control relaxation, foundry capacity expansion, and civil aviation mandate enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market