
 Naval Navigation and Communication Systems Market | 2026-2036
Naval Navigation and Communication Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Navigation and Communication Systems Market Foresight
The capability gap between prime contractors and mid-tier sensor suppliers is unwinding as sovereign navies demand end-to-end combat system integration. Northrop Grumman Corporation leverages its shipboard inertial navigation heritage to anchor large-deck carrier programs. Kongsberg Gruppen ASA dominates integrated bridge technology for Arctic-capable surface vessels. Thales Group specializes in satellite communication terminals that sustain blue-water operational reach for European naval operators.
Naval navigation and communication systems encompass integrated suites of GPS receivers, AIS transponders, phased-array RADAR, multibeam sonar, and encrypted satellite links engineered for maritime command, control, and situational awareness in contested electromagnetic environments. These systems fuse real-time positioning data with tactical messaging to enable coordinated fleet maneuvering, anti-submarine warfare, and precision logistics in GPS-denied conditions. Sonar and RADAR technology segments lead procurement volume given submarine proliferation in the Indo-Pacific and surface fleet modernization across NATO members. Communication devices within the component dimension concentrate margin pools as software-defined radios and low-probability-of-intercept waveforms replace legacy hardware. Military end users drive absolute spending, though coast guard operators represent the fastest-growing category as maritime law enforcement missions expand territorial water patrol requirements.
The U.S. Navy's NAVSEA certification process, NATO STANAG interoperability protocols, and the International Maritime Organization's SOLAS amendments collectively shape product standards and market access for system integrators. The U.S. Federal Communications Commission regulates spectrum allocation for naval satellite communication, while the EU's Radio Equipment Directive imposes electromagnetic compatibility requirements on European-sourced navigation hardware. Stakeholders must monitor shifting export control classifications under the U.S. International Traffic in Arms Regulations and corresponding EU dual-use regulations as allied nations accelerate indigenous manufacturing mandates.
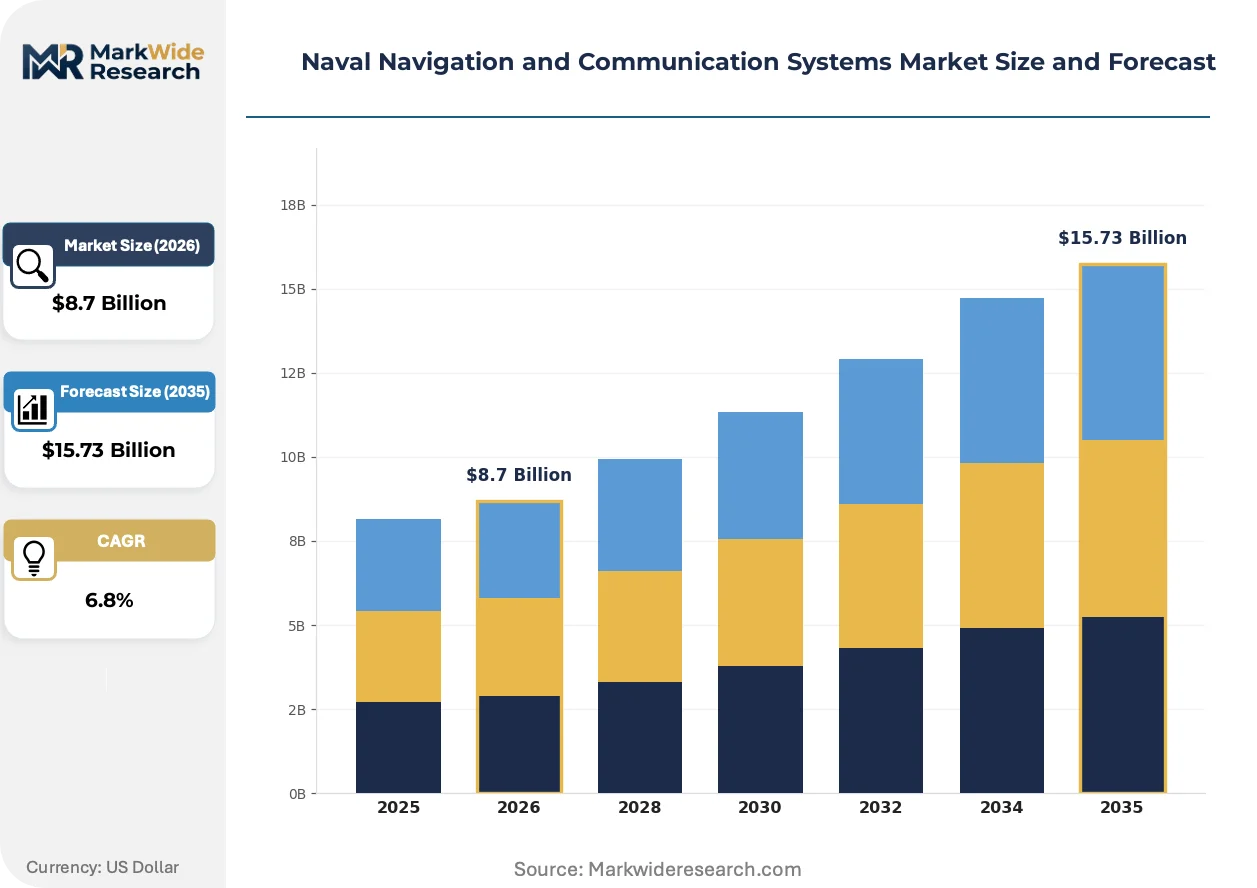
Market Dynamics
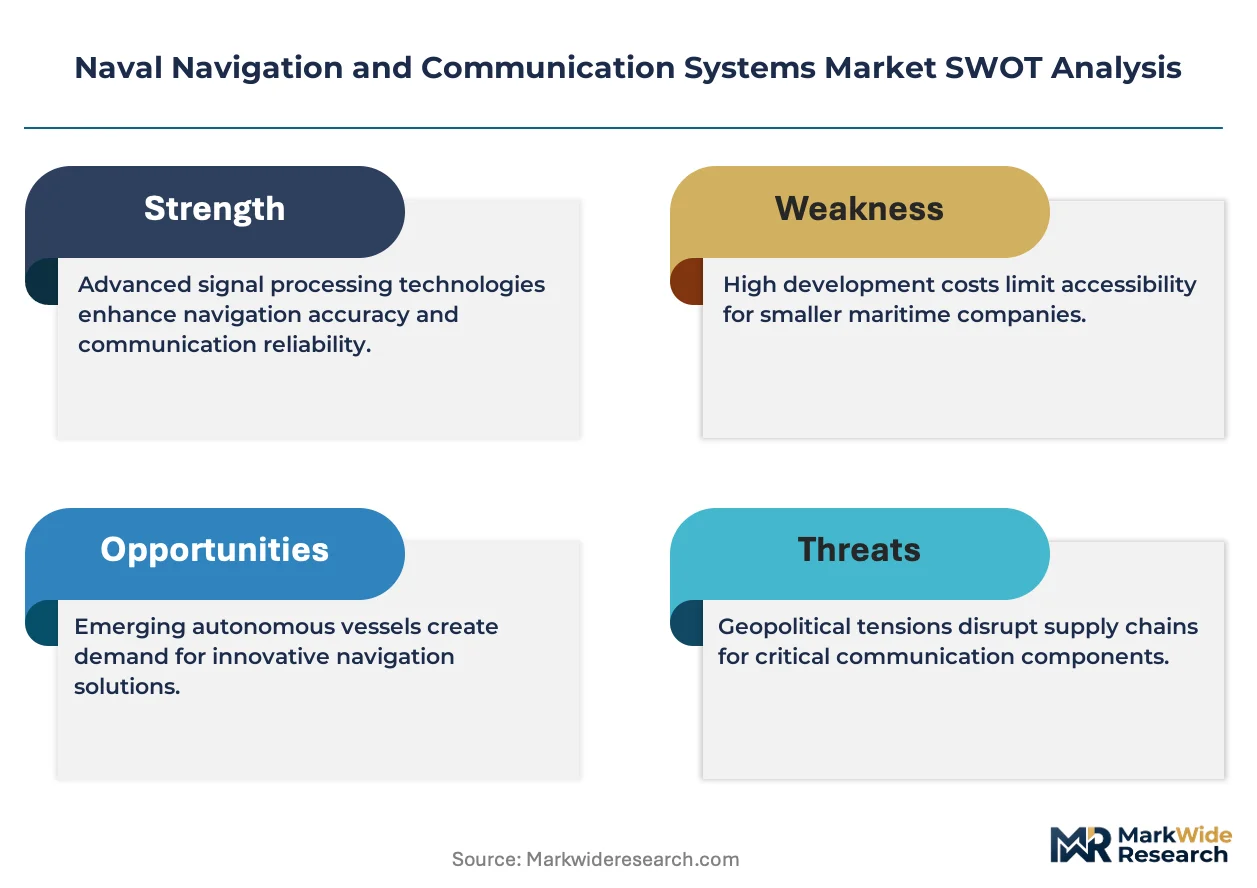
The U.S. Navy's NAVSEA certification process and NATO STANAG interoperability mandates are compressing supplier qualification timelines while elevating integration complexity requirements for combat system architectures.
Growth Catalysts
- Pacific Fleet Expansion:The United States is accelerating procurement of next-generation electronic chart display and information systems to support carrier strike group deployment rotations.
- SOLAS Amendment Compliance:The International Maritime Organization's safety mandates are forcing legacy fleet retrofits that expand addressable demand for integrated bridge systems across NATO member navies.
- Software-Defined Radio Adoption:Low-probability-of-intercept waveform protocols are displacing hardware-dependent legacy communication stacks in blue-water operational environments.
Market Restraints
- Gallium Nitride Supply Concentration:Phased-array RADAR manufacturing depends on Chinese-processed rare earth substrates subject to export licensing volatility.
- ITAR Classification Friction:The U.S. International Traffic in Arms Regulations impose multi-year technology release timelines that stall allied joint development programs.
- GPS Denial Vulnerability:Inertial navigation system drift rates require continuous satellite recalibration, limiting operational effectiveness in contested electromagnetic environments.
Strategic Opportunities
- Arctic Surface Vessel Demand:Norway and Denmark are commissioning ice-capable frigates requiring Kongsberg-class integrated bridge technology with enhanced cold-weather sensor reliability.
- Coast Guard Modernization:Maritime law enforcement agencies represent an underpenetrated category with territorial water patrol requirements expanding faster than naval fleet procurement.
- AI-Assisted Threat Detection:Machine learning convergence with multibeam sonar processing is opening new performance tiers for anti-submarine warfare system integrators.
Industry Challenges
- Embedded Systems Engineering Talent:Real-time operating system programming expertise for military-grade hardware remains concentrated among defense-prime engineering teams with limited labor pool mobility.
- Multi-Year Certification Cycles:NAVSEA qualification protocols for new combat management system releases extend development timelines beyond commercial technology refresh rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Navigation and Communication Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, AIS, RADAR, Sonar End User: Military, Coast Guard, Commercial Shipping, Research Institutions Application: Strategic Operations, Search and Rescue, Logistic Support, Navigation Training Component: Transponders, Communication Devices, Display Systems, Sensors |
| Companies Covered | Northrop Grumman Corporation, Honeywell International Inc., Teledyne FLIR LLC, Kongsberg Gruppen ASA, Safran, Raytheon Technologies Corporation, Thales Group, BAE Systems, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Navigation and Communication Systems Market Shifts & Advancements
Quantum-enhanced positioning and software-defined electronic warfare architectures are compressing the capability gap between strategic naval powers and mid-tier maritime forces.
Solid-state inertial measurement units are replacing mechanical gyroscopes in shipboard navigation suites. Coast guard operators and littoral combat ship programs are adopting these sensors at accelerated procurement cycles. The technology is miniaturizing bridge system footprints while extending maintenance intervals beyond traditional mechanical alternatives.
The EU's Radio Equipment Directive now mandates electromagnetic compatibility testing for all navigation hardware sourced from European suppliers. This regulatory friction is elevating compliance costs for non-EU system integrators seeking NATO procurement contracts. Surface vessel electronics manufacturers are responding by establishing certified test facilities in Germany and France.
Lifecycle service contracts are displacing discrete hardware procurement as the dominant revenue mechanism for integrated combat system providers. Prime contractors are unbundling sensor maintenance from platform construction, creating dedicated sustainment revenue streams. This shift is most visible in U.S. Navy carrier and amphibious assault ship programs where operational availability metrics now drive supplier selection.
Naval Navigation and Communication Systems Market Segmentation
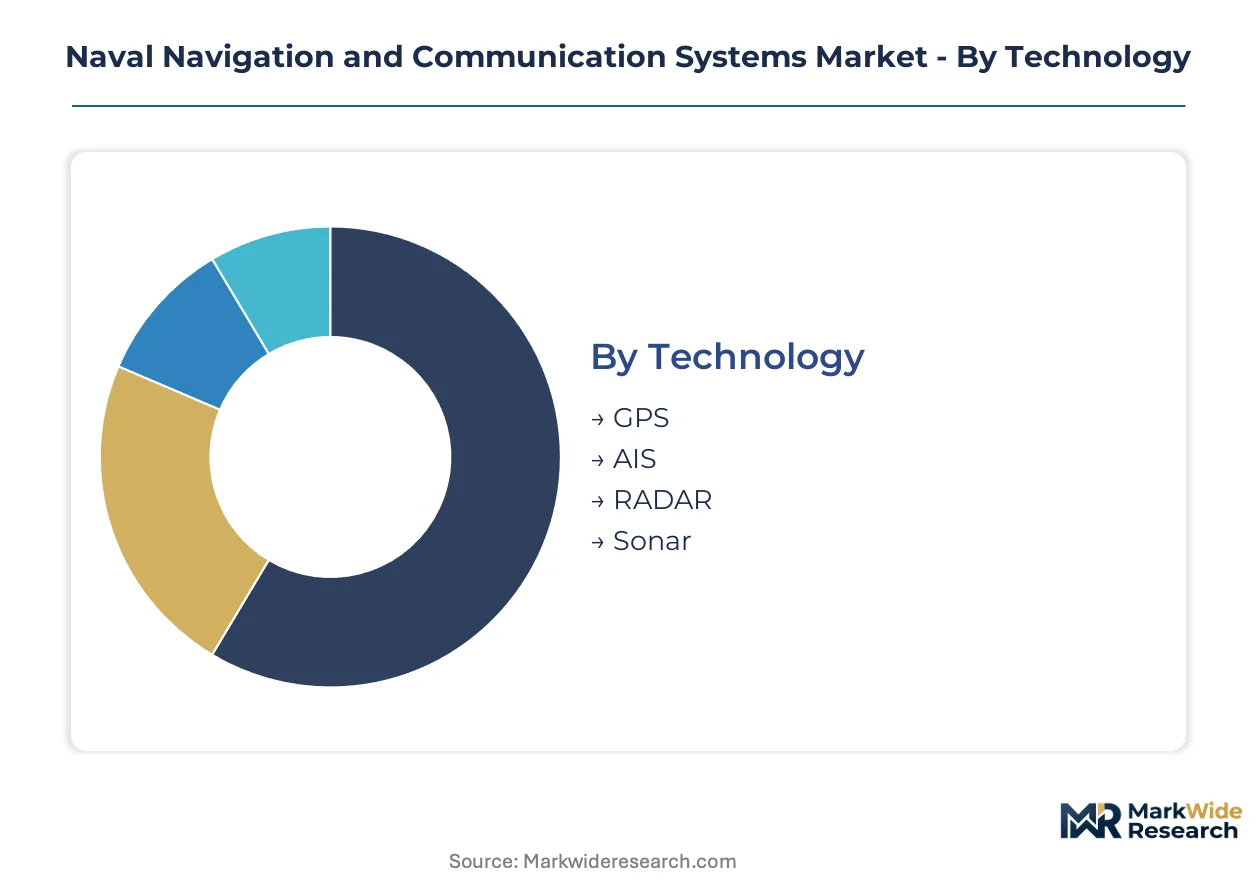
Segmentation in naval navigation and communication systems reveals how procurement priorities diverge across sovereign defense budgets, commercial maritime operators, and dual-use technology pathways. Understanding these fault lines exposes where integration complexity concentrates margin capture and where commoditization pressures erode supplier returns.
Technology:
Margin pools concentrate in sensor fusion architectures where multi-modal positioning systems command premium pricing against standalone navigation modules.
- GPS:Military-grade encrypted receivers with anti-spoofing firmware anchor carrier strike group navigation suites. The U.S. Pacific Fleet drives procurement of next-generation military code-capable terminals as GPS denial tactics proliferate in contested waterways.
- AIS:Automatic Identification System transponders integrate collision avoidance with encrypted tactical messaging for coalition fleet coordination. NATO STANAG interoperability mandates are accelerating dual-band transponder retrofits across European surface combatants.
- RADAR:Active electronically scanned arrays dominate phased-array procurement for integrated bridge systems.
- Sonar:Multibeam hull-mounted systems lead anti-submarine warfare sensor procurement volume.
Sonar holds installed capacity. AIS is rotating up the share rankings.
End User:
Volume concentration sits with military fleet modernization programs, though procurement velocity is shifting toward maritime security agencies with compressed acquisition cycles.
- Military:Naval operators demand end-to-end combat system integration spanning encrypted satellite links, inertial navigation backup, and electronic warfare-resistant command interfaces. The U.S. Navy NAVSEA certification process elevates supplier qualification barriers that freeze out mid-tier competitors lacking platform-scale integration heritage.
- Coast Guard:Maritime law enforcement agencies are expanding territorial water patrol requirements faster than naval fleet procurement, creating dedicated demand for littoral-capable navigation suites with reduced signature profiles. Arctic-capable cutters commissioned by Norway and Denmark specify Kongsberg-class integrated bridge technology with enhanced cold-weather sensor reliability.
- Commercial Shipping:SOLAS amendment compliance is forcing legacy fleet retrofits that expand addressable demand for integrated bridge systems.
- Research Institutions:Academic and government research vessels require precision positioning for seabed mapping and oceanographic survey operations.
Military end users hold installed capacity. Coast Guard is rotating up the share rankings.
Application:
Revenue concentration tracks operational tempo, with sustained deployment missions generating lifecycle service contracts that displace discrete hardware procurement.
- Strategic Operations:Blue-water carrier strike group deployments require encrypted satellite communication terminals with low-probability-of-intercept waveform protocols. Thales Group specializes in these systems for European naval operators sustaining operational reach across contested electromagnetic environments.
- Search and Rescue:Distress beacon integration with multibeam sonar for submerged object location commands specialized procurement from coast guard operators. The EU's Radio Equipment Directive mandates electromagnetic compatibility testing that elevates compliance costs for non-EU system integrators seeking NATO SAR contracts.
- Logistic Support:Precision positioning for underway replenishment and amphibious assault ship operations demands tight GPS-inertial fusion.
- Navigation Training:Simulation-based bridge system instruction requires replicated sensor environments for crew certification.
Strategic Operations holds installed capacity. Search and Rescue is rotating up the share rankings.
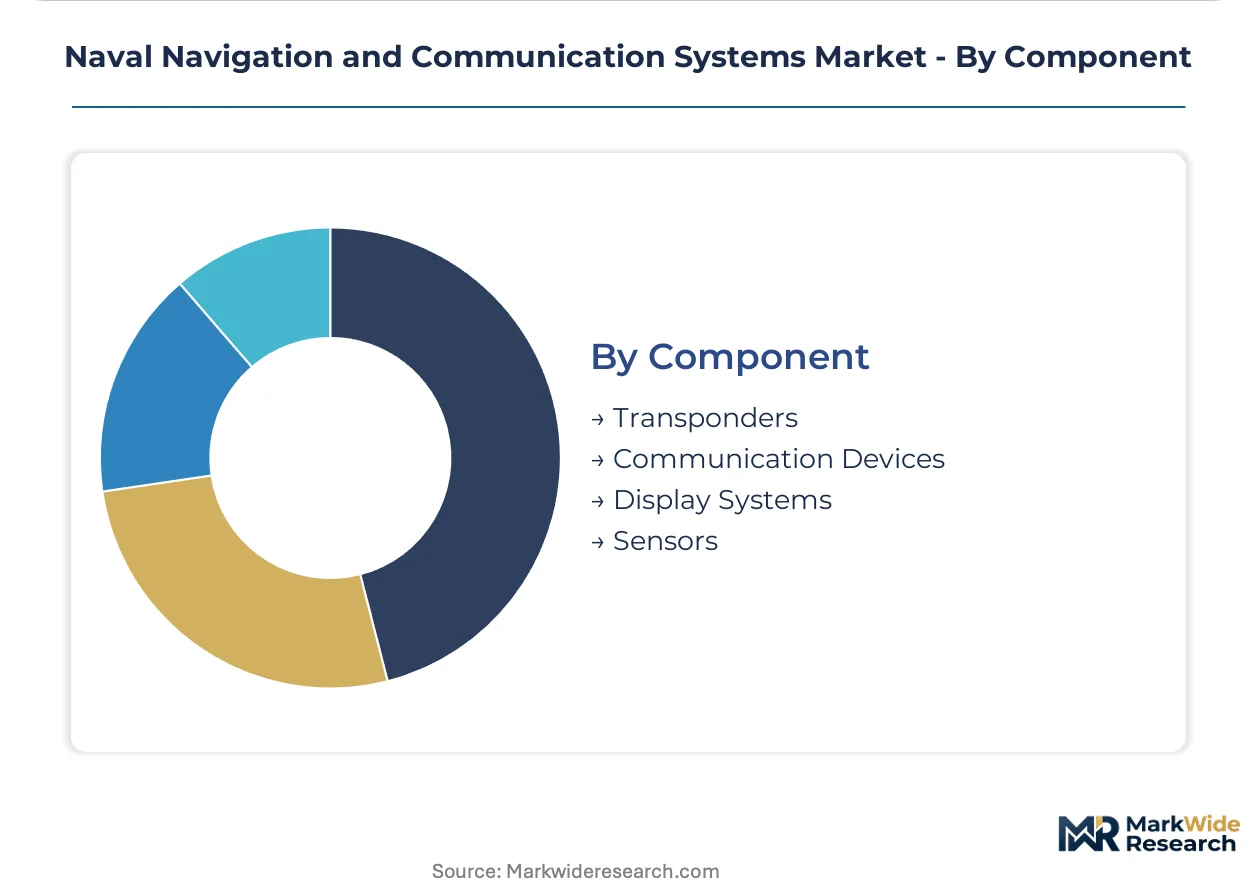
Component:
Software-defined architectures are displacing hardware-dependent legacy stacks, concentrating value capture in firmware and waveform development rather than discrete electronics manufacturing.
- Communication Devices:Software-defined radios with reprogrammable encryption protocols are replacing fixed-frequency hardware across NATO member fleets. Gallium Nitride substrate supply concentration in Chinese processing facilities creates export licensing volatility that constrains phased-array RADAR manufacturing timelines.
- Transponders:Dual-use AIS-military tactical messaging fusion units bridge commercial maritime safety mandates with naval interoperability requirements.
- Display Systems:Electronic chart display and information systems integrate real-time positioning with tactical overlays for bridge crew situational awareness.
- Sensors:Solid-state inertial measurement units are replacing mechanical gyroscopes, miniaturizing bridge system footprints while extending maintenance intervals.
Display Systems holds installed capacity. Communication Devices is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States defense procurement while European suppliers absorb compliance cost premiums from the EU's Radio Equipment Directive. This asymmetry shapes where system integrators locate certified test facilities and sustainment operations.
United States
Pacific Fleet carrier strike group rotations drive NAVSEA-certified electronic chart display and information system procurement at accelerated cycles. The FCC regulates naval satellite communication spectrum allocation under defense priority protocols. Virginia Beach and San Diego anchor prime contractor engineering clusters where combat management system integration talent pools concentrate.
Norway
Arctic-capable frigate programs commission ice-hardened integrated bridge technology for sustained polar operations. National procurement guidelines align with NATO STANAG interoperability mandates for coalition fleet coordination. Kongsberg-based engineering teams specialize in cold-weather sensor reliability specifications that exceed standard marine environmental ratings.
United Kingdom
Submarine fleet modernization and Type 26 frigate programs sustain multibeam sonar procurement volume. BAE Systems operates under Ministry of Defence export licensing frameworks that parallel U.S. ITAR classification structures. Glasgow and Barrow-in-Furness maintain platform-scale integration heritage for nuclear and conventional submarine combat systems.
Japan
Maritime Self-Defense Force destroyer procurement prioritizes phased-array RADAR integration for integrated air and missile defense. METI industrial policy channels domestic content requirements toward shipboard inertial navigation and satellite communication terminal production. Yokohama and Kobe harbor defense prime manufacturing clusters with captive supply chain relationships.
Australia
Hunter-class frigate and nuclear-powered submarine programs import combat system architectures under AUKUS technology-sharing agreements. The country's defense export control office administers parallel classification reviews to U.S. ITAR and UK export licensing timelines. Adelaide hosts platform integration facilities where sovereign workforce development targets combat system engineering autonomy.
Naval Navigation and Communication Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with defense primes commanding integration complexity premiums while mid-tier sensor suppliers compete on component specialization. The market structure tiers around platform-scale system integrators, subsystem specialists, and component technology providers. Two dominant strategic archetypes have emerged: combat system integrators with NAVSEA certification heritage, and sensor fusion specialists with Arctic or electronic warfare domain expertise. Competitive moves concentrate on multi-year sustainment contract capture and sovereign manufacturing mandate compliance rather than discrete hardware procurement.
Within the platform-integrator tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify defense prime positioning anchored by shipboard inertial navigation and carrier program heritage. Kongsberg Gruppen ASA occupies a specialist position reflecting Norwegian Arctic capability concentration. Thales Group represents European satellite communication terminal expertise aligned with blue-water operational requirements. These three companies illustrate how geographic defense industrial base policy shapes competitive archetype formation.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Honeywell International Inc. |
| Teledyne FLIR LLC |
| Kongsberg Gruppen ASA |
| Safran |
| Raytheon Technologies Corporation |
| Thales Group |
| BAE Systems |
| Lockheed Martin Corporation |
| Others |
Supply & Pricing Matrix
Lifecycle service contracts with embedded hardware refresh clauses lock in multi-year revenue visibility for NAVSEA-certified integrators while insulating prime contractors from spot-market component volatility. This structure concentrates pricing power with platform-scale providers who bundle sustainment into carrier and amphibious assault ship programs.
Pricing Analysis
The customization-premium spread between configured-to-order integrated bridge systems and standard catalog navigation modules runs wide in this market. Project-based contracting with milestone payments dominates procurement for military end users, while coast guard operators increasingly favor subscription-style sustainment agreements. Price differentiation hinges on NAVSEA certification tier and Arctic environmental rating, with ice-hardened Kongsberg-class systems commanding substantial premiums over standard marine specifications. Cost compression in commercial shipping retrofits is intensifying as SOLAS amendment deadlines force accelerated fleet upgrades, making this segment the most price-sensitive buyer pool. Military fleet modernization programs show lowest price sensitivity given operational availability metrics driving supplier selection.
Supply Chain Analysis
Gallium Nitride substrate processing in Chinese rare earth facilities creates a single-source vulnerability for active electronically scanned array manufacturing. Phased-array RADAR production draws from Chinese-processed substrates, Norwegian sensor integration expertise, and U.S. combat system certification heritage. Raw material dependencies span rare earth elements for RADAR substrates, precision inertial measurement unit components, and encrypted satellite communication chipsets. Tariff exposure on Chinese-processed materials constrains manufacturing timelines for allied defense programs. Distribution runs through prime contractor engineering clusters in Virginia Beach, San Diego, and Kongsberg with captive sustainment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cyclicality is entering an upswing phase as Pacific Fleet expansion drives carrier strike group rotation schedules and AUKUS submarine programs accelerate combat system integration demand.
For Market Incumbents: Shield NAVSEA certification heritage through accelerated workforce development in real-time operating system programming, where talent scarcity threatens platform-scale integration capacity. Deepen backward integration into solid-state inertial measurement unit production to reduce dependence on mechanical gyroscope supply chains. Prioritize multi-year sustainment contract capture over discrete hardware procurement as lifecycle service revenue displaces transactional sales. For New Entrants and Emerging Players: Differentiate on Arctic-capable sensor reliability specifications where Norwegian and Danish coast guard procurement creates white-space demand beyond established prime contractor strongholds. Target maritime law enforcement agencies with compressed acquisition cycles and territorial water patrol expansion requirements. Pursue software-defined radio firmware development as legacy hardware-dependent communication stacks face displacement from low-probability-of-intercept waveform protocols. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier sensor fusion specialists with submarine or electronic warfare domain expertise that primes can acquire for combat system integration capability gaps. Long-term viability in this market rests on sovereign manufacturing mandate compliance and multi-year sustainment contract visibility rather than transactional hardware margins. Monitor ITAR technology release timeline compression as the signal for allied joint development program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Manufacturing Mandate Compliance | Establishes market access under EU dual-use regulations and U.S. ITAR frameworks for allied procurement. |
| Multi-Year Sustainment Contract Capture | Locks in recurring revenue streams as U.S. Navy operational availability metrics drive supplier selection. |
| Arctic Environmental Rating Certification | Opens Norwegian and Danish coast guard procurement channels for ice-capable integrated bridge systems. |
| Software-Defined Radio Platform Development | Displaces fixed-frequency hardware across NATO fleets with reprogrammable encryption protocols. |
| Real-Time Operating System Talent Acquisition | Addresses embedded systems engineering scarcity that limits mid-tier competitor qualification timelines. |
Research Methodology
Operator-level perspectives from naval program managers, NAVSEA certification engineers, coast guard procurement officers, and satellite communication terminal specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with platform integrators and subsystem specialists across the United States, Norway, United Kingdom, and Japan. Secondary validation drew from U.S. Navy budget justification documents, NATO STANAG interoperability protocols, EU Radio Equipment Directive filings, and customs trade data for navigation hardware imports. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Sensitivity analysis tested forecast outputs against alternative scenarios for Pacific Fleet expansion pacing and Gallium Nitride supply disruption duration. The analytical framework modeled technology adoption curves, end-user procurement velocity, and application-specific lifecycle patterns across the projection horizon. Segmentation dimensions included GPS receiver grade tier, RADAR array architecture, military versus coast guard versus commercial end-use, and strategic operations versus search and rescue application intensity. CAGRs derived from fitted growth curves calibrated to historical defense procurement cyclicality and documented platform modernization schedules.
Material uncertainties — ITAR technology release timeline extensions, Chinese rare earth export licensing volatility, and GPS denial tactic proliferation — sit outside the modeled envelope. Forecasts reflect documented procurement assumptions and sovereign defense budget trajectories. Practitioners should keep alternative scenarios live as allied joint development program momentum and Arctic surface vessel commissioning rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Global Antenna Market