
 Global Next-Generation Sequencing (NGS) Services Market | 2026-2036
Global Next-Generation Sequencing (NGS) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Next-Generation Sequencing (NGS) Services Market Foresight
Oncology research is consolidating as the dominant demand vertical for NGS services, displacing earlier reliance on basic academic sequencing contracts. Illumina, Inc. leverages its installed base of sequencing instruments to anchor captive service revenue streams. Thermo Fisher Scientific competes through integrated sample-to-data workflows that sustain higher throughput per contract. BGI Genomics dominates price-sensitive bulk sequencing with manufacturing scale across multiple continents.
Next-generation sequencing services encompass laboratory processing of DNA or RNA samples using massively parallel sequencing platforms, typically generating read lengths from 50 to 300 base pairs on short-read systems or exceeding 10 kilobases on long-read platforms, with primary commercial purpose of delivering actionable genomic datasets for research and clinical decision-making. Targeted sequencing captures the largest volume share as oncology panels and carrier screening programs standardize on focused gene sets. RNA sequencing represents the fastest-expanding service category as transcriptomic profiling penetrates immuno-oncology biomarker discovery and drug response monitoring. Whole genome sequencing remains premium-priced and concentrated in rare disease diagnostic programs where reimbursement pathways are still forming.
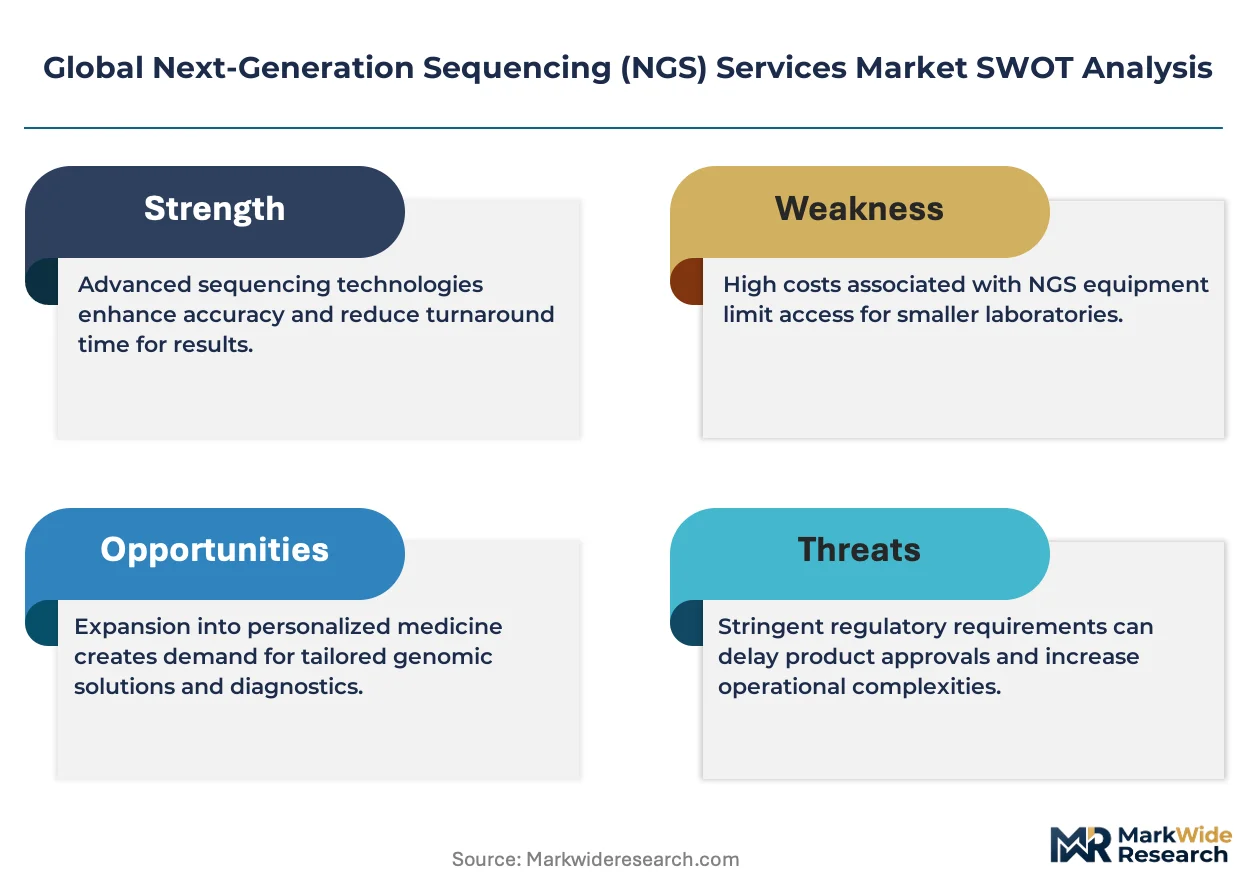
FDA oversight of laboratory-developed tests and EMA's In Vitro Diagnostic Regulation reshape service provider obligations around analytical validation and clinical evidence documentation. China's NMPA accelerates review pathways for innovative sequencing-based diagnostics while enforcing domestic data localization requirements. ISO 15189 accreditation and CAP proficiency standards operate as baseline market access filters that determine contract eligibility with major pharmaceutical sponsors. Stakeholders must monitor evolving payer coverage decisions for somatic and germline sequencing as these determine which service lines achieve sustainable reimbursement.
Market Dynamics
Pharmaceutical outsourcing of genomic validation work is compressing contract timelines and forcing service providers to reconfigure laboratory networks around sponsor manufacturing footprints.
Growth Catalysts
- Oncology pipeline expansion:Drug developers now mandate companion diagnostic sequencing for Phase II trials, embedding NGS services into regulatory submission pathways.
- FDA analytical validation guidance:Tighter standards for laboratory-developed tests compel sponsors to contract with accredited service providers rather than maintain in-house capabilities.
- Long-read platform maturation:Pacific Biosciences and Oxford Nanopore systems resolve structural variants that short-read platforms miss, opening clinical diagnostic applications.
Market Restraints
- Reagent supply concentration:Illumina's control over sequencing-by-synthesis chemistry creates vulnerability for non-integrated service laboratories.
- EMA In Vitro Diagnostic Regulation compliance costs:Small and mid-size providers face capital requirements for notified body certification that strain operating margins.
- Interpretation bottleneck:Variant classification expertise scarcity limits throughput expansion even where sequencing capacity exists.
Strategic Opportunities
- China's NMPA accelerated review pathways:Domestic data localization requirements favor local laboratory partnerships for multinational sponsors seeking market access.
- RNA-seq immuno-oncology biomarker discovery:Transcriptomic profiling for CAR-T monitoring and checkpoint inhibitor response prediction commands premium pricing.
- Pharmacy-based sample collection networks:Retail health chains in the United States now offer blood draw logistics that bypass traditional hospital-based biobank channels.
Industry Challenges
- Bioinformatics pipeline standardization:Lack of harmonized variant calling algorithms across platforms complicates multi-site clinical trial data integration.
- CAP proficiency testing cycles:Extended timelines for accreditation renewal delay contract eligibility with institutional review board-mandated studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Next-Generation Sequencing (NGS) Services Market |
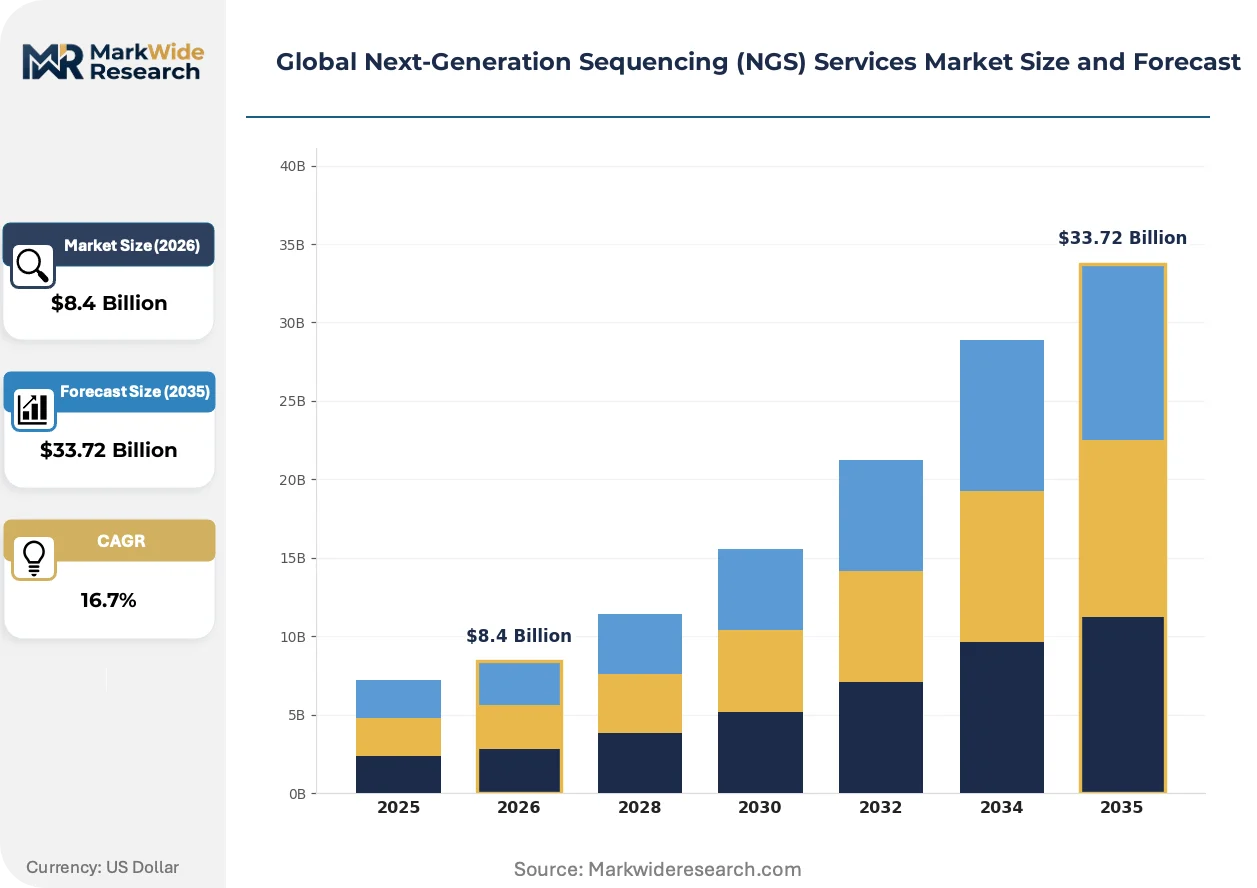
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Whole Genome Sequencing, Targeted Sequencing, Exome Sequencing, RNA Sequencing, Epigenetic Sequencing, Metagenomic Sequencing Application Area: Oncology Research, Genetic Disorder Screening, Drug Development, Agricultural Genomics, Microbial Analysis, Personalized Medicine End User: Pharmaceutical Companies, Academic Research Institutions, Agricultural Labs, Biotechnology Firms, Forensic Laboratories, Public Health Agencies Technology Platform: Illumina Sequencing, Ion Torrent, Pacific Biosciences, Oxford Nanopore, BGI Sequencing, Roche 454 |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific, BGI Genomics, Eurofins Scientific, Novogene Co. Ltd., Azenta Life Sciences, Macrogen, Inc., QIAGEN, Revvity, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Next-Generation Sequencing (NGS) Services Market Shifts & Advancements
Cloud-native bioinformatics architectures and artificial intelligence-assisted variant interpretation are compressing analysis timelines and reshaping how sponsors evaluate service provider capabilities.
Multi-omics integration is electrifying competitive positioning among tier-one providers. Service laboratories now combine genomic, transcriptomic, and epigenetic profiling into unified data packages for immuno-oncology trials. Pharmaceutical sponsors in the United States and Germany are prioritizing vendors offering integrated dashboards over point-solution sequencing contracts. This convergence is compressing pricing for standalone RNA-seq services as buyers demand bundled analytics.
REACH chemical safety requirements for laboratory reagents are forcing European providers to reformulate sample preparation workflows. The regulation mandates substitution of hazardous substances in nucleic acid extraction kits, increasing validation burden for existing protocols. German and Swiss laboratories are responding by qualifying alternative magnetic bead chemistries ahead of compliance deadlines.
Direct-to-physician reporting models are displacing traditional principal investigator channels in academic medical center contracting. Service providers now sell molecular tumor boards and variant interpretation directly to oncology departments, bypassing centralized procurement offices. This pattern is most visible in United States health systems where value-based care contracts reward rapid turnaround times.
Global Next-Generation Sequencing (NGS) Services Market Segmentation
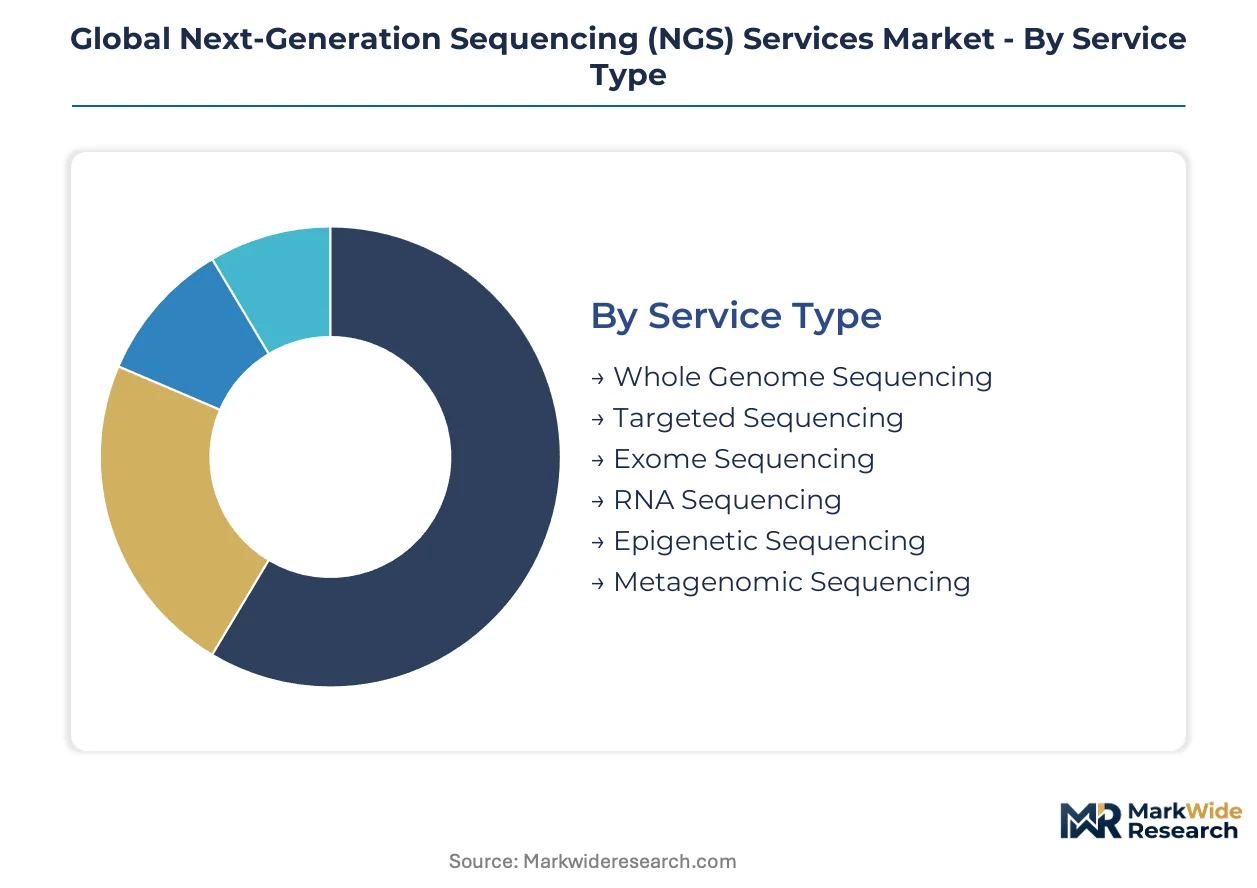
Service specialization determines contract pricing and accreditation requirements across the NGS services landscape. Pharmaceutical sponsors segment vendors by analytical validation depth, while academic buyers prioritize cost per gigabase and turnaround flexibility.
Service Type:
Platform upgrade cycles and reagent chemistry refreshes drive contract renegotiation patterns across service categories.
- Targeted Sequencing:Oncology panels and carrier screening programs dominate contract volumes through standardized gene sets that compress analytical validation costs. United States clinical laboratories process the highest panel throughput where FDA oversight of laboratory-developed tests mandates accredited service partnerships.
- RNA Sequencing:Transcriptomic profiling for immuno-oncology biomarker discovery commands premium pricing as CAR-T monitoring and checkpoint inhibitor response prediction require specialized bioinformatics pipelines. Germany's academic medical centers are expanding RNA-seq procurement for precision oncology programs.
- Whole Genome Sequencing:Rare disease diagnostic programs in the United States and China concentrate demand where reimbursement pathways remain under development.
- Exome Sequencing:Research applications in undiagnosed genetic disorders sustain steady contract flow from academic institutions.
- Epigenetic Sequencing:DNA methylation profiling for cancer subtyping attracts pharmaceutical sponsor investment.
- Metagenomic Sequencing:Microbiome analysis for infectious disease and environmental monitoring generates specialized contract demand.
Volume placements concentrate in Targeted Sequencing; the faster expansion belongs to RNA Sequencing.
Application Area:
Cost tier differentiation separates validated clinical services from research-grade contracts.
- Oncology Research:Companion diagnostic sequencing for Phase II trials embeds NGS services into regulatory submission pathways. Pharmaceutical sponsors in the United States and Germany mandate accredited providers for biomarker validation work.
- Drug Development:Genomic validation contracts compress timelines as sponsors reconfigure laboratory networks around manufacturing footprints. China's NMPA accelerated review pathways favor local partnerships for multinational market access.
- Genetic Disorder Screening:Newborn and prenatal screening programs in public health systems generate recurring contract demand.
- Personalized Medicine:Pharmacogenomic testing for drug response prediction expands through pharmacy-based sample collection networks.
- Agricultural Genomics:Crop improvement and livestock breeding programs in China and Germany sustain research sequencing contracts.
- Microbial Analysis:Infectious disease surveillance and antimicrobial resistance tracking supports public health agency procurement.
Contract value concentrates in Oncology Research; steepest expansion trajectory belongs to Drug Development.
End User:
Customer type dictates service level agreements, turnaround requirements, and data security protocols.
- Pharmaceutical Companies:Outsourced genomic validation work demands ISO 15189 accreditation and CAP proficiency standards as baseline contract eligibility filters. Sponsors prioritize integrated sample-to-data workflows that sustain higher throughput per contract.
- Academic Research Institutions:Price-sensitive bulk sequencing contracts favor BGI Genomics manufacturing scale across multiple continents. Germany's dense biobank networks and clinical research infrastructure concentrate European academic demand.
- Biotechnology Firms:Venture-funded development programs require flexible contract structures and rapid turnaround for investor milestones.
- Public Health Agencies:Population-scale screening programs and infectious disease surveillance generate large-volume, standardized contracts.
- Agricultural Labs:Crop and livestock research programs sustain steady demand for plant and animal genomic services.
- Forensic Laboratories:DNA profiling for criminal justice applications requires specialized chain-of-custody protocols and accreditation.
Revenue concentration sits with Pharmaceutical Companies; fastest share gains belong to Biotechnology Firms.
Technology Platform:
Supply concentration in sequencing chemistry shapes service provider vulnerability and pricing power.
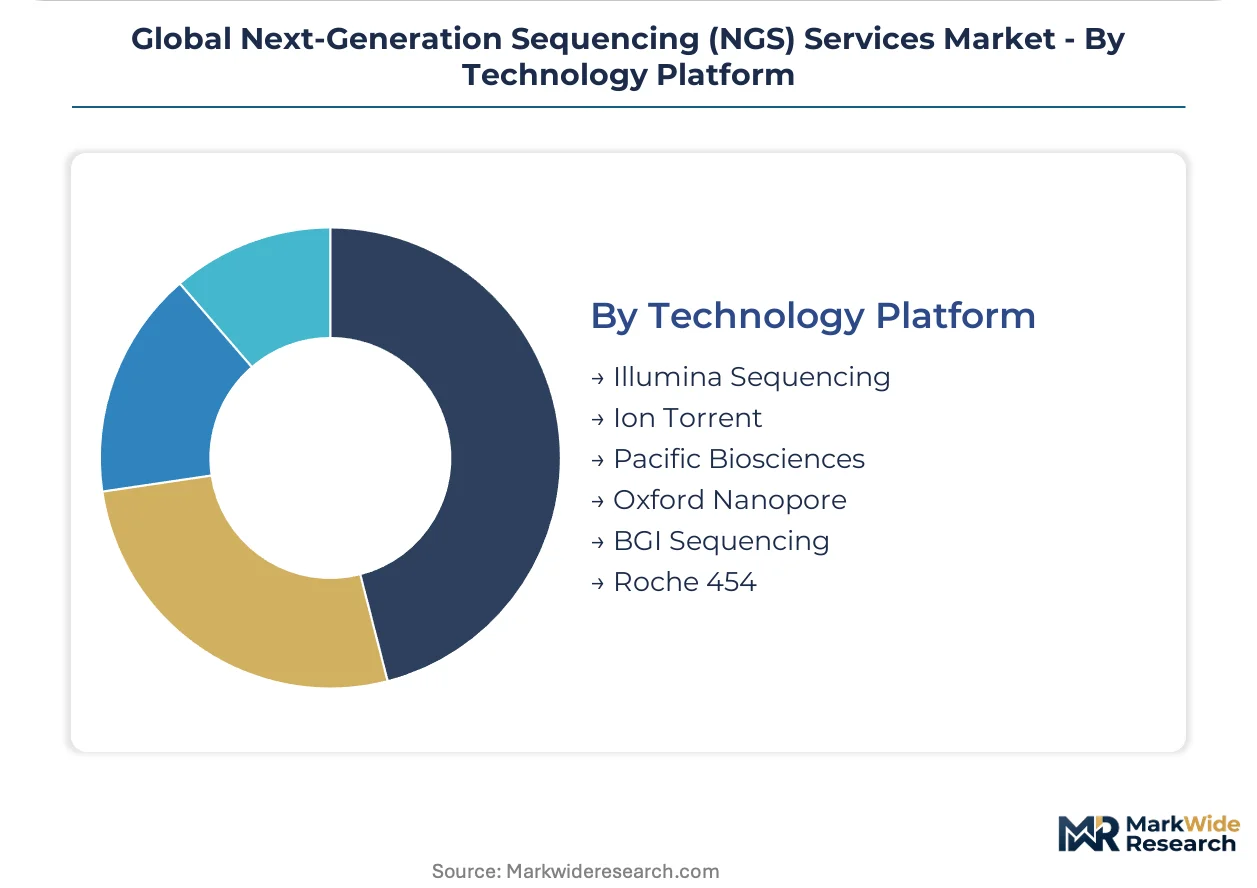
- Illumina Sequencing:Sequencing-by-synthesis chemistry dominates short-read contract volumes through installed base density and reagent ecosystem lock-in. United States service laboratories anchor captive revenue streams on Illumina instrument fleets.
- Pacific Biosciences:Long-read systems resolve structural variants that short-read platforms miss, opening clinical diagnostic applications for rare disease and complex genomic regions.
- Oxford Nanopore:Portable sequencing devices enable point-of-care and field-based applications with real-time data generation.
- Ion Torrent:Semiconductor sequencing maintains niche presence in targeted panel applications.
- BGI Sequencing:Domestic Chinese platforms align with NMPA data localization requirements and state-supported research programs.
- Roche 454:Legacy pyrosequencing systems sustain limited contract demand for specific amplicon applications.
Installed base dominance concentrates in Illumina Sequencing; capability expansion is climbing the fastest for Pacific Biosciences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotechnology special economic zones in the United States, China, and Germany concentrate sequencing infrastructure through tax incentives and streamlined regulatory pathways. These jurisdictions anchor pharmaceutical outsourcing contracts and academic research procurement. Dense clinical trial networks and biobank systems sustain regional demand differentiation.
United States
FDA oversight of laboratory-developed tests and companion diagnostic mandates drive pharmaceutical sponsors toward accredited service partnerships. The Research Triangle Park in North Carolina and Greater Boston corridor host dense clusters of contract research organizations integrating sequencing into Phase II trial workflows. Pharmacy-based sample collection networks in retail health chains now bypass traditional hospital biobank channels.
China
NMPA accelerated review pathways for innovative sequencing-based diagnostics attract multinational sponsor investment despite data localization requirements. State-supported research programs and domestic platform development concentrate capacity in Beijing-Tianjin-Hebei and Yangtze River Delta clusters. Local laboratory partnerships prove essential for market access under evolving cybersecurity regulations.
Germany
EMA In Vitro Diagnostic Regulation compliance costs and REACH chemical safety requirements for laboratory reagents reshape provider obligations. Munich and Heidelberg academic medical centers expand precision oncology programs with transcriptomic profiling procurement. German biobank networks sustain European leadership in population-scale genomic research contracts.
United Kingdom
Genomics England and NHS infrastructure standardize rare disease diagnostic pathways while reimbursement frameworks mature for whole genome sequencing. London and Cambridge life science clusters attract pharmaceutical biomarker validation work. Post-Brexit regulatory divergence from EMA frameworks creates parallel compliance tracks for service providers.
Switzerland
Swissmedic oversight and ISO 15189 accreditation standards position Basel and Zurich laboratories as premium-tier partners for European pharmaceutical sponsors. Precision medicine initiatives in academic hospital networks sustain demand for integrated multi-omics service packages. Swiss neutrality in data governance attracts international clinical trial centralization.
Global Next-Generation Sequencing (NGS) Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with instrument-anchored providers capturing premium pricing while independent laboratories compete on turnaround flexibility. The vendor base concentrates around three tiers: integrated platform owners with captive chemistry supply, accredited clinical laboratories with regulatory validation depth, and price-sensitive bulk processors with manufacturing scale. Strategic moves center on multi-omics service bundling and cloud-native bioinformatics architecture deployment.
Within the integrated platform tier, Illumina, Inc. and Thermo Fisher Scientific anchor competitive positioning through installed instrument bases and reagent ecosystem control. BGI Genomics occupies a distinct scale-driven position with manufacturing presence across multiple continents. These three entities exemplify how supply-side concentration in sequencing chemistry shapes service provider vulnerability and pricing power in contract negotiations.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific |
| BGI Genomics |
| Eurofins Scientific |
| Novogene Co. Ltd. |
| Azenta Life Sciences |
| Macrogen, Inc. |
| QIAGEN |
| Revvity, Inc. |
| Others |
Supply & Pricing Matrix
Sequencing reagent spot prices and Illumina chemistry contract benchmarks cascade through laboratory networks into three distinct pricing tiers for pharmaceutical sponsors, academic institutions, and price-sensitive bulk processors. Long-term reagent offtake agreements anchor cost structures for integrated platform owners while independent service laboratories absorb volatility through spot procurement exposure.
Pricing Analysis
Lead-time compression commands substantial premiums in clinical trial sequencing contracts, with sponsors paying standard rates for 14-day turnaround and economy tiers accepting 30-day windows for non-validated research applications. Three-tier pricing structure across premium, standard, and economy levels separates CAP-accredited clinical services from research-grade contracts and bulk academic processing. Pricing pressure stems from BGI Genomics manufacturing scale and Chinese platform competition eroding margins in standardized panel sequencing. Academic research institutions exhibit highest price sensitivity, while pharmaceutical sponsors prioritize analytical validation depth over per-sample cost.
Supply Chain Analysis
Cold-chain logistics costs for biosample transport and temperature-controlled reagent distribution consume 8-12% of contract value in transcontinental arrangements, compressing margins for non-integrated laboratories. Supply concentration centers on the United States for Illumina instrument manufacturing, China for BGI platform production and domestic reagent supply, and Germany for precision consumables and European distribution hubs. Raw material dependencies include modified nucleotides, polymerase enzymes, and magnetic bead chemistries subject to REACH substitution mandates. Single-source vulnerability in sequencing-by-synthesis chemistry creates exposure for non-captive laboratories. Distribution runs through direct pharmaceutical sponsor contracts, academic procurement consortia, and regional laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EMA In Vitro Diagnostic Regulation compliance costs and CAP proficiency standard investments force sub-scale laboratories toward acquisition or exit. Regulatory validation depth and integrated multi-omics capability separate viable competitors from stranded assets.
For Market Incumbents: Cement market position through captive reagent supply integration and cloud-native bioinformatics architecture deployment that pharmaceutical sponsors now mandate for trial data integration. Threat exposure from Pacific Biosciences long-read platform maturation demands capability expansion into structural variant resolution. Priority lever rests on multi-omics service bundling that compresses standalone RNA-seq pricing and locks sponsor relationships through integrated dashboards. For New Entrants and Emerging Players: NMPA accelerated review pathways in China open a window for domestic laboratory partnerships serving multinational sponsors navigating data localization requirements. White-space targets include pharmacy-based sample collection logistics bypassing hospital biobank channels and AI-assisted variant interpretation services addressing the classification bottleneck. Most penetrable segment sits with biotechnology firms requiring flexible contract structures for investor milestone timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 15189-accredited mid-cap laboratories in Germany and Switzerland facing EMA compliance cost pressures but possessing validated clinical trial relationships. Long-term viability frames around five-to-ten year windows for consolidation plays in European precision oncology infrastructure. Acquisition target archetype combines accredited clinical validation depth with underinvested bioinformatics scale. Signal to watch: CAP proficiency testing cycle delays that strand sub-scale providers from contract eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Omics Service Integration | Pharmaceutical sponsors in the United States and Germany prioritize unified genomic-transcriptomic-epigenetic data packages for immuno-oncology trials. |
| Cloud-Native Bioinformatics Deployment | AI-assisted variant interpretation and distributed computing architectures compress analysis timelines for regulatory submission pathways. |
| Long-Read Platform Capability Expansion | Pacific Biosciences and Oxford Nanopore systems resolve structural variants that short-read platforms miss, opening rare disease diagnostic applications. |
| Domestic Laboratory Partnership Formation | China's NMPA data localization requirements favor local partnerships for multinational sponsors seeking accelerated review pathway access. |
| Direct-to-Physician Reporting Model Development | Molecular tumor board services sold directly to oncology departments bypass centralized academic medical center procurement offices. |
Research Methodology
SEC filings, FDA 510(k) submissions, and ClinicalTrials.gov protocol registries formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with drug development executives, regulatory affairs leads at sequencing service providers, hospital procurement managers, and payer access specialists validated demand assumptions and pricing dynamics. Bottom-up triangulation across service type volumes and top-down cross-check against pharmaceutical R&D expenditure allocations anchored forecast integrity.
Historical trendline analysis across instrument placement data, reagent consumption patterns, and contract research organization sequencing revenue disclosures established baseline growth trajectories. The analytical framework modeled segmentation dimensions including service type, application area, end user category, and technology platform adoption curves across the projection horizon. CAGRs derived from regression analysis of segment-specific growth drivers including oncology pipeline expansion, regulatory validation requirement tightening, and long-read platform capability maturation.
The model assumes a particular technology adoption path; alternative pathways for Oxford Nanopore portable sequencing or BGI domestic platform expansion would alter the outlook for service provider competitive positioning. Forecasts reflect assumptions around reimbursement pathway development for whole genome sequencing and EMA regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Genomics Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Japan Next Generation Sequencing Market
Genomics
Europe DNA Sequencing Products Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
China Genetic Testing Market
Genomics
Global Nutrigenomics Market
Genomics
Single-Cell Omics Market
Genomics
Spatial OMICS Market
Genomics
Apolipoprotein Test Market
Genomics
Forensic Genomics Market
Genomics
Hereditary Testing Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Whole Exome Sequencing (WES) Market