
 Trailer Stabilizer Market | 2026-2036
Trailer Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Stabilizer Market Intelligence
Fleet procurement among commercial haulers is pivoting toward integrated stabilizer platforms as large transport operators consolidate vendor lists around single-source chassis suppliers. Lippert Components dominates aftermarket distribution through its RV dealer network, while Dexter Axle Company anchors OEM supply agreements with major trailer manufacturers. Robert Bosch GmbH leverages automotive sensor expertise to compete in electric stabilizer actuation systems.
Trailer stabilizers are load-bearing support devices, typically fabricated from hardened steel with zinc-phosphate corrosion coating, that extend from trailer frames to ground level to prevent tip-over during loading, unloading, and stationary storage. Mechanical stabilizers, the most mature segment, face margin compression as fleet buyers shift specification toward hydraulic units that offer faster deployment cycles and higher load ratings. Electric stabilizers represent the fastest-growing product category, driven by integration with telematics platforms that allow remote deployment monitoring by fleet managers.
The US FMCSA, NHTSA, and OSHA collectively shape stabilizer demand through trailer safety inspection mandates, rollover prevention guidelines, and workplace loading dock standards that elevate equipment specification requirements. The EU's CE marking and Machinery Directive impose parallel conformity obligations on stabilizer mechanisms sold in European markets. Stakeholders must monitor regulatory harmonization between North American and European load stability standards as export-oriented manufacturers face divergent certification pathways.
Market Dynamics
Fleet consolidation among commercial haulers is compressing vendor lists and forcing stabilizer manufacturers to integrate with single-source chassis platforms. The US FMCSA inspection protocol tightening is accelerating replacement cycles for non-compliant mechanical units.
Growth Catalysts
- FMCSA Safety Mandates:The US Department of Transportation's updated trailer inspection protocols are compelling fleet operators to upgrade aging stabilizer hardware before enforcement deadlines.
- Hydraulic Deployment Speed:Oilfield services in Texas and intermodal terminals are specifying hydraulic stabilizers for their 40% faster ground-contact cycles versus mechanical alternatives.
- Telematics Integration:Electric stabilizer systems with remote monitoring capabilities are capturing fleet management contracts that prioritize real-time equipment visibility.
Market Restraints
- Hardened Steel Input Volatility:Zinc-phosphate coated steel pricing fluctuations are squeezing margins for mechanical stabilizer producers locked into annual fleet contracts.
- OEM Supply Concentration:Dexter Axle's anchor position in manufacturer supply agreements limits aftermarket penetration for independent stabilizer vendors.
- Load Rating Technical Ceiling:Current hydraulic cylinder designs face physical constraints above 50,000-pound static load thresholds for specialized heavy-haul applications.
Strategic Opportunities
- EU Machinery Directive Alignment:Stabilizer producers achieving CE marking conformity can access European intermodal freight markets with harmonized safety specifications.
- Sensor-Actuator Convergence:Integration of automotive-grade position sensors with electric stabilizer motors enables predictive maintenance contracts.
- RV Dealer Network Expansion:Lippert Components' distribution infrastructure offers a proven channel template for premium stabilizer lines targeting recreational trailer segments.
Industry Challenges
- Cross-Discipline Talent Scarcity:Fleet procurement teams lack personnel fluent in both hydraulic systems and telematics platform integration.
- FMCSA Compliance Timeline Compression:The gap between protocol announcement and enforcement is forcing rushed certification cycles for redesigned stabilizer models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Stabilizer Market |
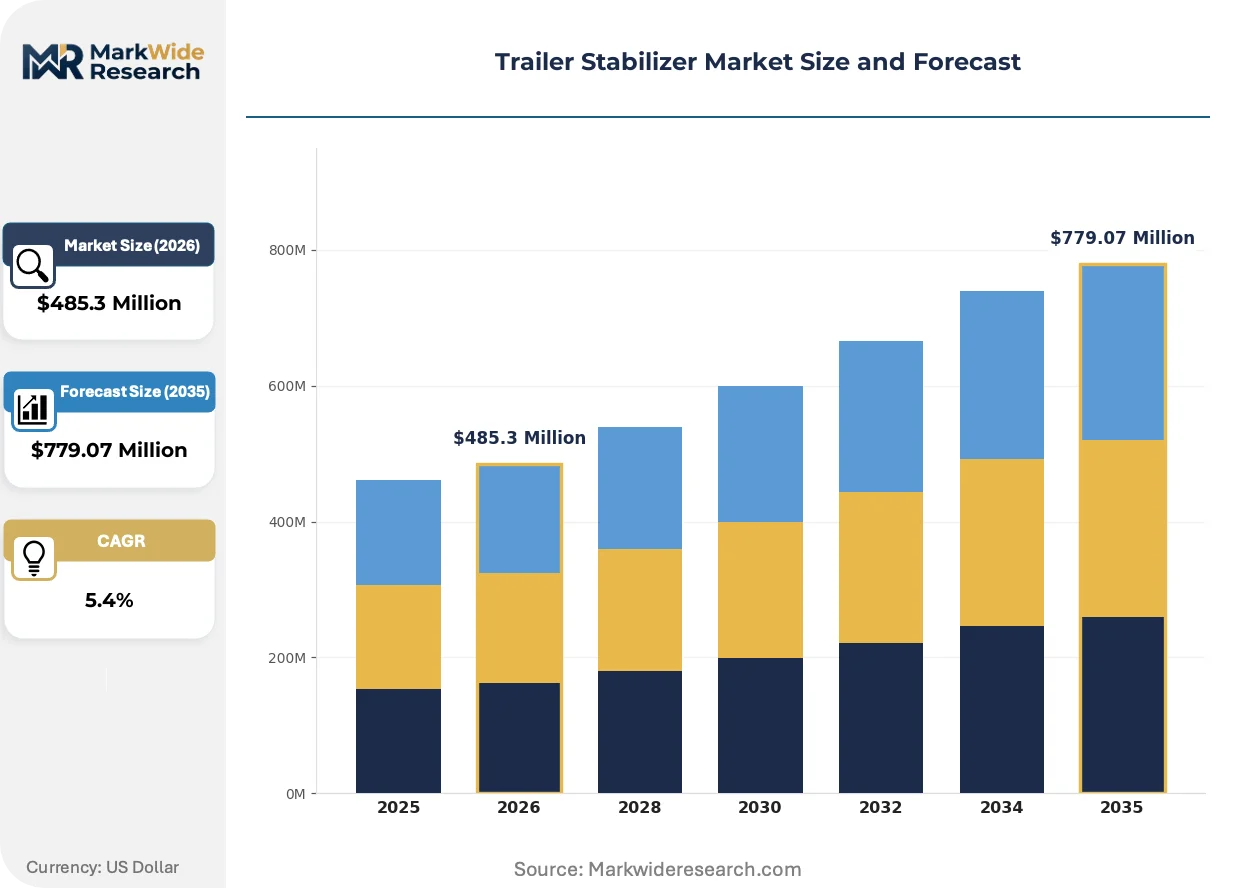
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $779.07 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Stabilizers, Hydraulic Stabilizers, Electric Stabilizers, Manual Stabilizers Deployment: Onboard Installation, Portable Solutions, Retrofit Systems, Integrated Platforms Application: Recreational Trailers, Commercial Haulers, Construction Trailers, Agricultural Trailers End User: Transport Operators, Fleet Managers, Equipment Rental Services, Independent Operators |
| Companies Covered | Lippert Components, Dexter Axle Company, Progress Manufacturing Inc., Fastway Trailer Products, Valterra Products LLC, Eaz Lift, Aldon Company Inc, Futura Trailers, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Stabilizer Market Strategic Shifts & Innovations
Stabilizer technology is bifurcating between premium electric-actuated systems with embedded diagnostics and cost-optimized hydraulic units for price-sensitive fleet segments. This divergence is reshaping R&D allocation and manufacturing footprints across the supplier base.
Electric stabilizer actuation is absorbing fleet telematics infrastructure investments by enabling remote deployment verification and automated maintenance scheduling. Large transport operators with centralized dispatch centers are specifying these units for 100% of new trailer orders. The technology is absorbing service revenue that previously flowed to third-party inspection contractors.
OSHA workplace loading dock standards are mandating documented ground-contact verification for all commercial trailers during unloading operations. This regulatory pressure is disqualifying legacy mechanical stabilizers lacking position-confirmation sensors. Heavy-duty freight terminals in California and Illinois are responding fastest due to state-level workplace safety enforcement intensity.
Single-source chassis procurement is collapsing the traditional two-step distributor-OEM channel for stabilizer sales. Fleet managers now negotiate stabilizer specifications directly with trailer manufacturers during build-to-order cycles. This pattern is most pronounced among Texas-based oilfield services firms consolidating vendor relationships under enterprise procurement mandates.
Trailer Stabilizer Market Segmentation
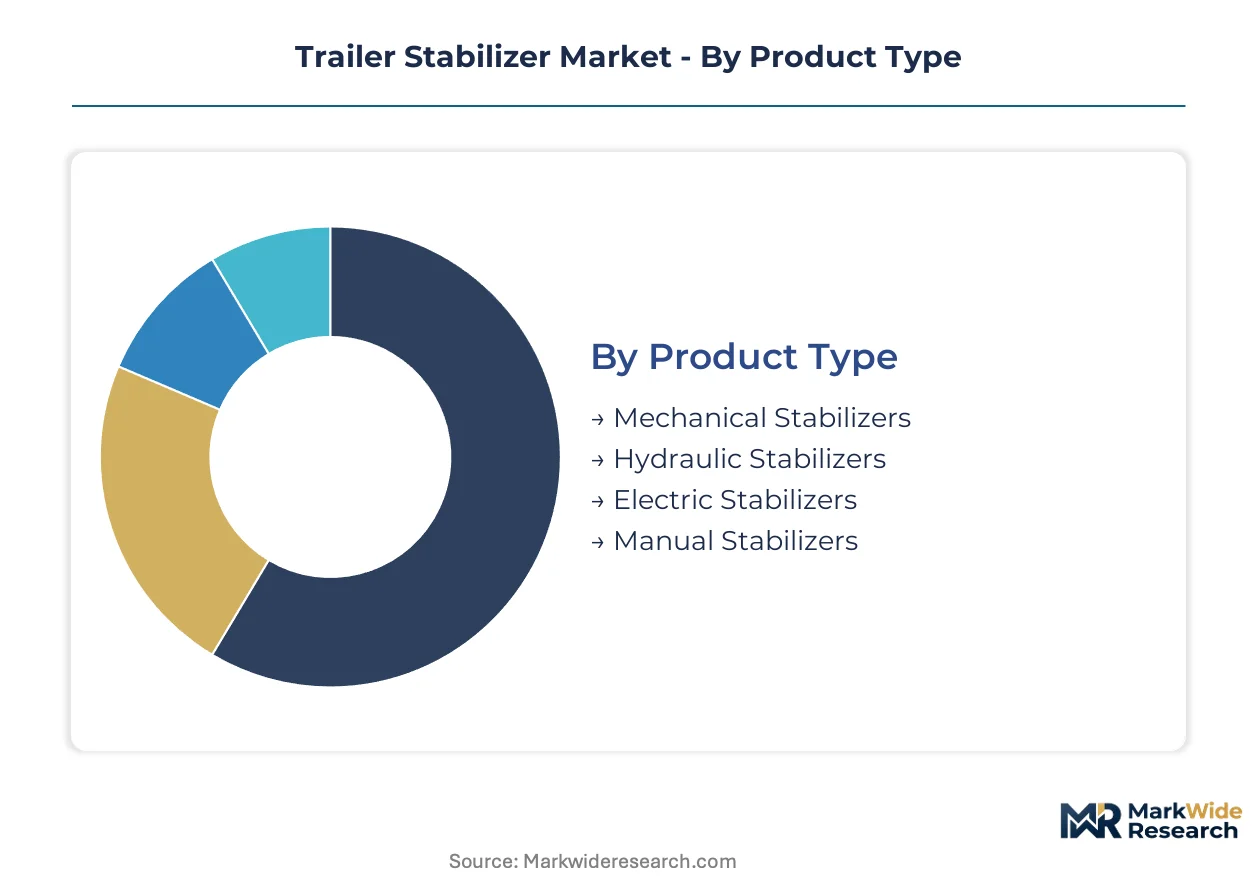
Trailer stabilizer procurement patterns diverge sharply across product architectures and deployment models. Fleet operators prioritize upgrade cycles that align with FMCSA inspection deadlines, while rental services favor portable configurations for asset flexibility.
Product Type:
Replacement cycles for aging mechanical units are accelerating as hydraulic and electric alternatives demonstrate superior deployment speed and telematics compatibility.
- Mechanical Stabilizers:Fabricated from hardened steel with zinc-phosphate corrosion coating, these units rely on manual crank mechanisms for ground contact. Texas oilfield services firms are retiring mechanical fleets ahead of FMCSA enforcement deadlines due to slower deployment cycles and lack of position verification sensors.
- Hydraulic Stabilizers:Cylinder-actuated systems deliver 40% faster ground-contact cycles through pressurized fluid deployment. Intermodal freight terminals in California and Illinois specify hydraulic units for high-throughput loading operations where dock turnaround time directly impacts revenue.
- Electric Stabilizers:Motor-driven actuation with embedded position sensors enables remote deployment monitoring via fleet telematics platforms. Transport operators with centralized dispatch centers are absorbing these units into enterprise procurement mandates.
- Manual Stabilizers:Entry-grade crank-operated devices serve price-sensitive independent operators and small agricultural fleets with limited annual mileage requirements.
Hydraulic stabilizers sit at the top of the volume ranking, with electric stabilizers climbing the fastest as telematics integration reshapes fleet procurement specifications.
Deployment:
Cost tier differentiation separates factory-integrated premium configurations from aftermarket retrofit alternatives serving extended asset life cycles.
- Onboard Installation:Factory-mounted stabilizer systems specified during trailer manufacturing deliver seamless chassis integration and warranty alignment. OEM supply agreements with Dexter Axle Company dominate this configuration for commercial hauler production lines.
- Portable Solutions:Detachable stabilizer units with quick-attach mounting brackets serve equipment rental services requiring cross-fleet deployment flexibility. Agricultural contractors in seasonal markets favor this architecture for shared asset pools.
- Retrofit Systems:Aftermarket conversion kits upgrade legacy mechanical stabilizers to hydraulic or electric actuation without full chassis replacement. Fleet managers facing compressed FMCSA compliance timelines are accelerating retrofit procurement.
- Integrated Platforms:Single-source chassis procurement now bundles stabilizer specification with trailer manufacturing, collapsing traditional distributor channels for large transport operators.
Onboard installation commands the highest revenue per unit, while integrated platforms are expanding most quickly as fleet consolidation compresses vendor lists.
Application:
Volume concentration varies by trailer duty cycle severity and regulatory exposure intensity across commercial and consumer segments.
- Commercial Haulers:Heavy-duty freight terminals and long-haul fleets subject to OSHA loading dock standards and FMCSA inspection mandates. California and Illinois terminals lead specification of sensor-equipped stabilizers for documented ground-contact verification.
- Recreational Trailers:RV dealer networks distribute stabilizer upgrades for leisure travel trailers and fifth-wheel configurations. Lippert Components anchors aftermarket penetration through established dealer infrastructure.
- Construction Trailers:Mobile office and equipment trailers require stabilization on uneven terrain where standard load ratings face stress testing.
- Agricultural Trailers:Seasonal grain and livestock haulers prioritize cost-optimized mechanical units with manual deployment for low-frequency usage patterns.
Commercial haulers anchor segment volume, with recreational trailers gaining share fastest as RV ownership expands and dealer service networks deepen stabilizer attachment rates.
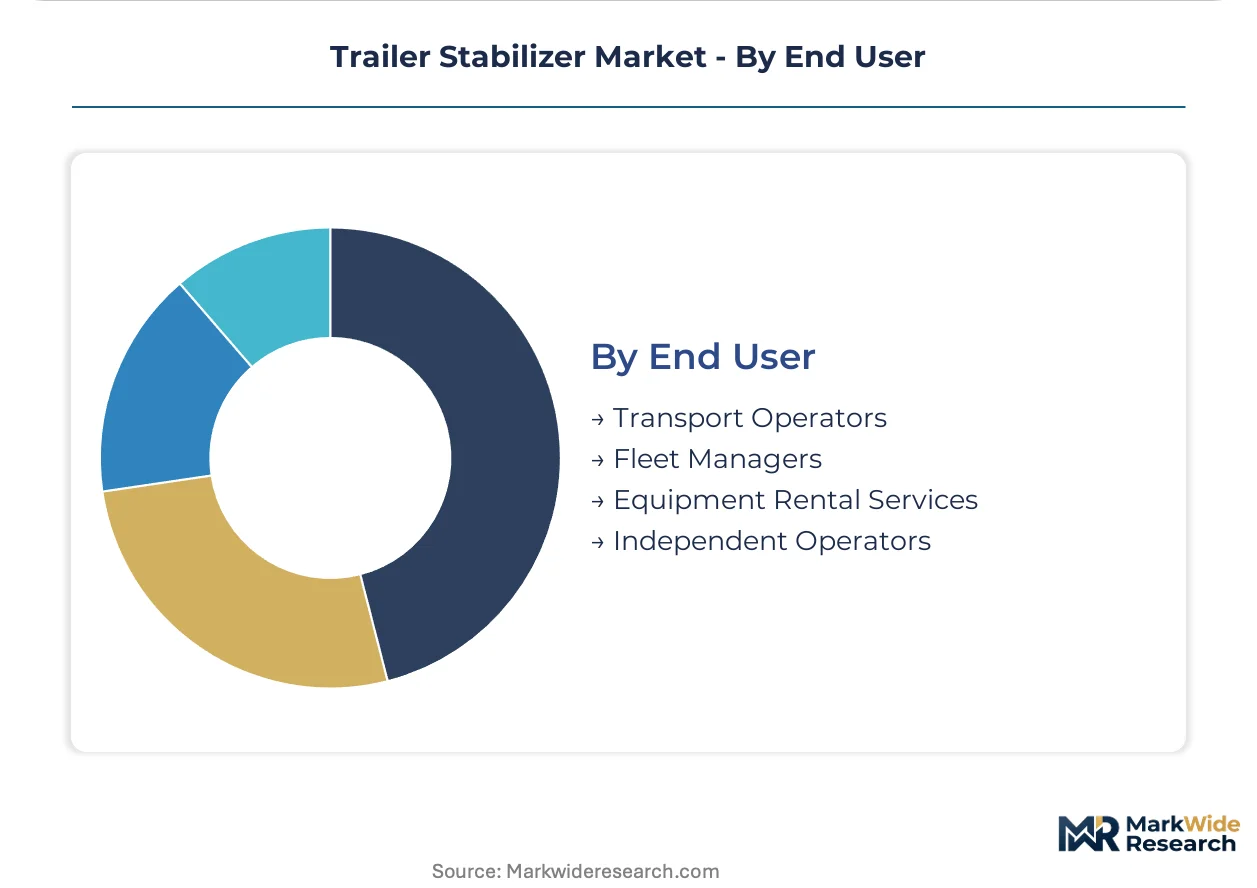
End User:
Customer type determines procurement authority concentration and specification sophistication across centralized and decentralized purchasing structures.
- Fleet Managers:Enterprise procurement teams at consolidated transport operators negotiate direct stabilizer specification with trailer manufacturers during build-to-order cycles. Texas-based oilfield services firms exemplify this pattern under enterprise vendor consolidation mandates.
- Transport Operators:Owner-operators and small fleet proprietors rely on aftermarket channels for stabilizer replacement and upgrade decisions.
- Equipment Rental Services:National rental chains specify portable stabilizer configurations for cross-fleet deployment and maintenance centralization.
- Independent Operators:Price-sensitive buyers with limited technical staff favor mechanical and manual stabilizer categories for capital expenditure minimization.
Fleet managers control the largest procurement volume, with equipment rental services expanding most quickly as asset-light logistics models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas oilfield services firms outpace California intermodal terminals in hydraulic stabilizer procurement velocity, while German automotive component expertise shapes electric actuation standards across European freight corridors.
United States
Texas oilfield services and California-Illinois intermodal terminals anchor domestic demand through enterprise fleet consolidation mandates. The FMCSA trailer safety inspection protocol tightening compels replacement of aging mechanical units before enforcement deadlines. Houston-Gulf Coast logistics clusters specify hydraulic stabilizers for 40% faster deployment cycles at high-throughput loading docks.
Germany
Industrial automation heritage positions German fabricators as electric stabilizer technology architects for European export markets. The EU Machinery Directive and CE marking requirements impose conformity obligations that filter non-compliant competitors from cross-border supply chains. Stuttgart-Munich automotive component corridors transfer sensor-actuator expertise into trailer telematics integration.
China
Domestic construction trailer and agricultural equipment production scales drive cost-optimized mechanical stabilizer fabrication. GB standards and MIIT industrial equipment regulations establish baseline safety specifications for domestic and Belt-and-Road export shipments. Yangtze River Delta manufacturing clusters concentrate hardened steel component forging capacity for regional trailer OEM supply.
India
Agricultural trailer fleets and emerging logistics infrastructure create bifurcated demand across manual mechanical and entry-hydraulic segments. BIS certification requirements and PLI scheme incentives for automotive component localization reshape import substitution patterns. Maharashtra-Gujarat industrial corridors anchor domestic fabrication capacity for price-sensitive independent operators.
Japan
Precision manufacturing culture translates into high-reliability electric stabilizer modules for premium commercial hauler exports. METI industrial standards and JIS certification frameworks elevate equipment specification thresholds for domestic fleet procurement. Nagoya-Osaka automotive supplier networks channel position-sensor expertise into predictive maintenance-enabled stabilizer designs.
Trailer Stabilizer Market Key Industry Players
United States producers anchor the OEM supply tier; German and Japanese specialists hold premium electric actuation segments. The vendor base stratifies across consolidated chassis-integrated suppliers, diversified automotive component conglomerates, and focused aftermarket distributors. Three archetypes dominate: single-source chassis bundlers, sensor-technology integrators, and dealer-network distributors. Competitive intensity concentrates on M&A consolidation for captive OEM access and strategic partnerships for telematics platform integration.
Within the chassis-integrated tier, Lippert Components and Dexter Axle Company exemplify divergent channel strategies—one leveraging RV dealer network density, the other anchoring manufacturer supply agreements. Robert Bosch GmbH occupies a position representing automotive sensor-actuator convergence into electric stabilizer architectures. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Lippert Components |
| Dexter Axle Company |
| Progress Manufacturing Inc. |
| Fastway Trailer Products |
| Valterra Products LLC |
| Eaz Lift |
| Aldon Company Inc |
| Futura Trailers |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
EU Machinery Directive conformity requirements gate both qualified supply and premium-tier pricing access for stabilizer producers seeking cross-border European freight contracts, compressing margins for non-certified fabricators while elevating price floors for CE-marked electric actuation systems.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for hardened steel mechanical stabilizers, forcing incumbent producers toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade—FMCSA-compliant sensor-equipped units command substantial premiums over baseline mechanical alternatives—and volume scale, with enterprise fleet contracts securing 15-20 point discounts versus spot procurement. Cost compression in the mechanical tier is intensifying because zinc-phosphate coated steel input volatility transfers directly to margin pressure, while electric stabilizer buyers exhibit lowest price sensitivity due to telematics integration mandates.
Supply Chain Analysis
Dual-sourcing requirements from Texas oilfield services firms and California intermodal terminals mandate multi-supplier qualification for hydraulic cylinder actuators, preventing single-source capture despite Dexter Axle's OEM anchor position. Geographic supply concentration centers on the United States for chassis-integrated platforms, Germany for automotive-grade position sensors, and China for cost-optimized hardened steel forging. Raw material dependencies draw from zinc-phosphate coated steel, hydraulic fluid formulations, and electric motor assemblies. Single-source vulnerability in OEM supply agreements poses structural risk as fleet consolidation compresses vendor lists. Distribution runs through trailer manufacturer direct procurement for commercial haulers and RV dealer networks for recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: German electric actuation expertise commands premium pricing in European corridors, while Chinese mechanical fabrication undercuts US domestic production on input costs.
For Market Incumbents: Lock in chassis-integrated supply agreements with trailer manufacturers before FMCSA enforcement deadlines accelerate replacement cycles, and anchor captive forging capacity for hardened steel components to offset zinc-phosphate input volatility. Vertical integration into sensor-actuator modules defends margin position against Bosch's automotive technology migration. For New Entrants and Emerging Players: Equipment rental services represent the most penetrable channel partner type, with portable stabilizer configurations offering white-space entry before fleet telematics integration hardens specification requirements. Target agricultural contractors in India's Maharashtra-Gujarat corridors through price-optimized manual units, and wedge into aftermarket retrofit demand among Texas oilfield services firms facing compressed compliance timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional hydraulic fabricators because fleet consolidation is collapsing distributor channels and creating captive OEM access premiums. Five-to-ten year viability favors sensor-technology integrators with CE marking pathways. Watch FMCSA enforcement intensity as the inflection signal—accelerated inspection protocols would shift replacement demand materially.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Conformity Investment | Unlocks European intermodal freight corridors under Machinery Directive specifications. |
| Telematics Platform Integration | Captures fleet management contracts requiring remote deployment verification capabilities. |
| Backward Integration into Steel Forging | Insulates margin from zinc-phosphate coated input volatility in mechanical tier. |
| RV Dealer Network Expansion | Replicates Lippert Components' aftermarket penetration template for recreational segments. |
| Hydraulic Cylinder Capacity Buildout | Addresses 50,000-pound load rating constraints for specialized heavy-haul oilfield applications. |
Research Approach
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market combining interviews with fleet procurement directors, trailer manufacturer platform engineers, aftermarket service heads, and hydraulic systems integrators, validated against FMCSA regulatory filings, EU Machinery Directive documentation, SEC 10-K disclosures from chassis suppliers, and hardened steel trade flow data, with bottom-up unit economics triangulated against top-down fleet replacement cycle modeling.
Rate-of-change decomposition separates volume growth from value mix-shift across the projection horizon, modeling segmentation dimensions including product architecture (mechanical/hydraulic/electric), deployment configuration (onboard/portable/retrofit/integrated), application severity (commercial hauler/recreational/construction/agricultural), and end-user procurement structure (fleet manager/operator/rental/independent). CAGRs derive from fleet size expansion, replacement cycle compression, and specification upgrade intensity, with electric stabilizer penetration rates and FMCSA compliance deadlines as industry-specific forecast inputs.
Revisions become necessary when FMCSA enforcement timelines compress, EU Machinery Directive harmonization shifts, or hardened steel input volatility exceeds historical bands, as deviation in regulatory implementation schedules or commodity cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
Rear Axle Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Automotive Steering Shaft Market