
 Navigation Switches Market | 2026-2036
Navigation Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Navigation Switches Market Foresight
EU Green Deal compliance is broadening the cost-of-entry calculus for navigation switch suppliers targeting European automotive and marine OEMs. Alps Alpine leverages captive manufacturing in Japan to sustain its position in precision rotary switches for aerospace applications. C&K Components anchors its competitiveness through deep specialization in tactile switch miniaturization for embedded installations. Bosch competes by extending its automotive channel control into hybrid electronic-mechanical switch architectures for next-generation cockpit systems.
Navigation switches are electromechanical or solid-state devices that convert physical operator input into discrete electrical signals, typically rated for operational lives exceeding one million cycles and environmental sealing to IP67 standards for marine and industrial deployment. Their primary purpose is to provide reliable human-machine interface control in vibration-intensive, moisture-exposed, or electromagnetic-interference-heavy environments where touchscreen alternatives fail. Tactile switches command the largest product type volume due to their ubiquity in industrial equipment control panels, while hybrid technology represents the fastest-expanding segment as OEMs seek to bridge mechanical durability with electronic signal processing capabilities. Panel mount installations retain the dominant share of value given their replacement-driven aftermarket in aerospace and marine sectors, though embedded configurations are capturing margin pools through integration into sealed electronic control modules.
FCC electromagnetic interference standards in the US, CE marking requirements under the EU Machinery Directive, and METI technical standards in Japan collectively shape product certification roadmaps and factory audit protocols for navigation switch manufacturers. REACH substance restrictions and RoHS hazardous material limits further constrain material selection for contact plating and housing polymers, elevating compliance costs for suppliers without in-house analytical laboratories. Stakeholders must monitor divergence between US and EU electromagnetic compatibility test methodologies when designing single-SKU global product platforms.
Market Dynamics
Hybrid electronic-mechanical architectures are compressing procurement cycles for navigation switches as automotive OEMs consolidate supplier bases to meet stricter electromagnetic compatibility mandates under EU and Japanese frameworks.
Growth Catalysts
- EU Green Deal compliance:Marine and automotive OEMs in Germany and France are expanding specifications for sealed, recyclable switch housings to satisfy circular economy mandates, pulling demand toward certified suppliers with in-house polymer testing.
- Industrial automation density:Contract manufacturers in China's Yangtze River Delta cluster are scaling output of IP67-rated tactile switches for export-oriented marine navigation system builders serving North American and European distributors.
- METI technical standards:Japanese aerospace subsystem integrators are qualifying domestic rotary switch suppliers against revised electromagnetic interference protocols, sustaining premium procurement for million-cycle-rated precision components.
Market Restraints
- Contact plating input costs:Palladium and gold price volatility for electrical contact surfaces is compressing margin pools for mid-tier suppliers without long-term precious metal hedging arrangements or captive refining partnerships.
- Supply concentration in East Asian molding:High-performance liquid crystal polymer housing production concentrates among specialized compounders in South Korea and Taiwan, creating single-source vulnerability for IP67 sealing grades.
- Touchscreen substitution ceiling:Capacitive interface modules are displacing mechanical switches in consumer automotive infotainment, though vibration and moisture limitations preserve navigation switch demand in commercial marine and heavy industrial segments.
Strategic Opportunities
- Embedded module integration:Sealed electronic control unit manufacturers in Germany are soliciting switch suppliers capable of co-molding contacts directly into thermally conductive polymer substrates, collapsing assembly steps.
- India industrial equipment buildout:Domestic construction machinery OEMs under PLI scheme incentives are qualifying imported navigation switches for operator control pods, creating first-mover positioning for certified exporters.
- REACH substance restriction tailwinds:RoHS and REACH compliance investments by European suppliers are creating certification barriers that favor incumbents with established analytical laboratories against new Asian entrants.
Industry Challenges
- Cross-jurisdiction certification timelines:Simultaneous FCC electromagnetic interference validation, CE Machinery Directive conformity, and METI technical standard alignment requires dedicated regulatory affairs capacity that strains mid-scale engineering teams.
- Legacy system integration friction:Aerospace and marine retrofit markets demand switch form factors compatible with decades-old panel cutout standards, constraining miniaturization roadmaps and forcing parallel product line maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Navigation Switches Market |
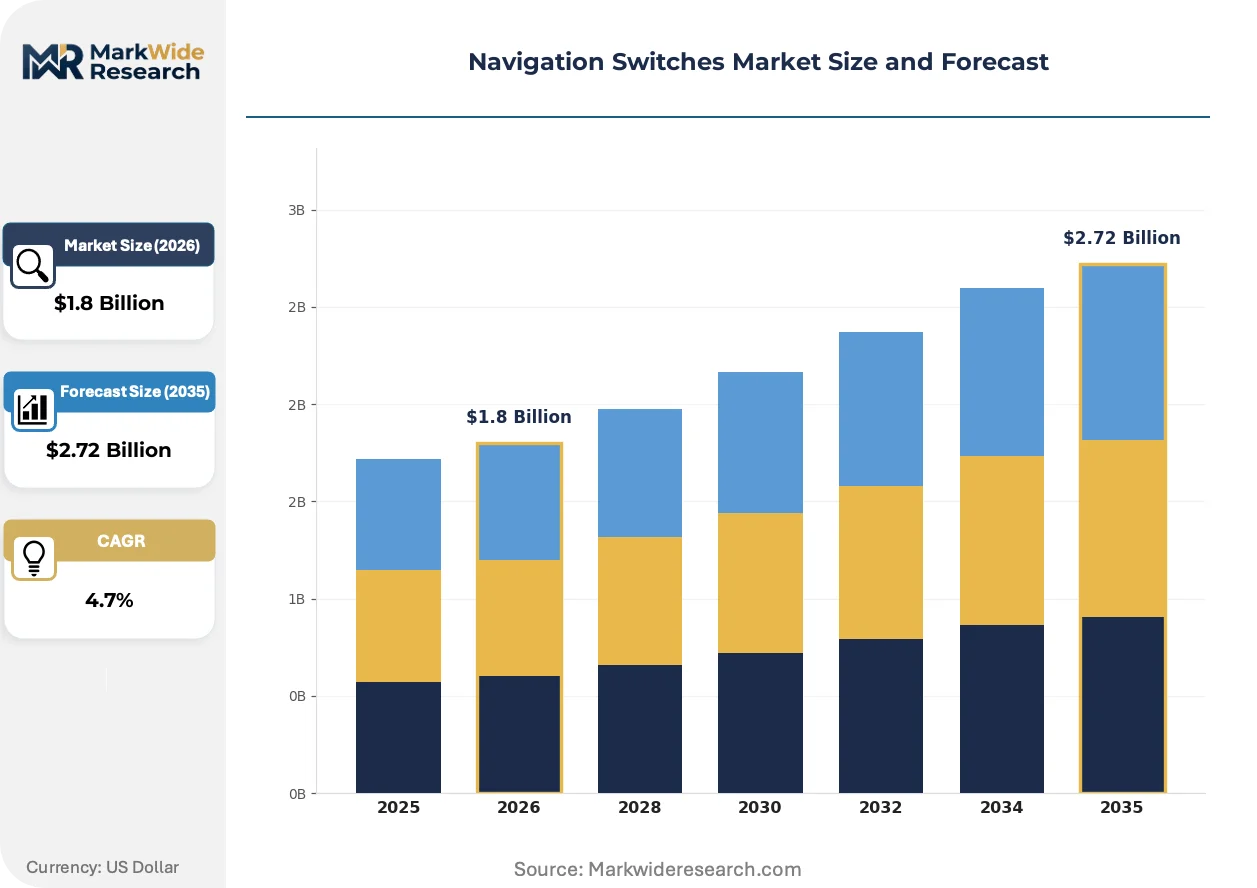
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rocker Switches, Tactile Switches, Rotary Switches, Pushbutton Switches End User: Aerospace, Automotive, Marine, Industrial Equipment Technology: Mechanical, Electronic, Optical, Hybrid Installation Type: Panel Mount, Surface Mount, Embedded, Portable |
| Companies Covered | APEM, Adafruit Industries, C&K Components, E-Switch, Grayhill, Bosch, Panasonic Corporation, Continental AG, Alps Alpine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Navigation Switches Market Shifts & Advancements
Signal processing integration is collapsing the boundary between mechanical durability and electronic functionality in navigation switch architectures, with hybrid designs capturing procurement preference across vibration-intensive applications.
Magnetoresistive position sensing is unifying angular measurement with contactless actuation in rotary navigation switches. German automotive Tier-1 suppliers are adopting these modules for next-generation cockpit controller applications at compressed development cycles. This convergence is unifying formerly separate mechanical switch and sensor supplier tiers into single-source qualification relationships.
REACH substance restrictions are tightening acceptable thresholds for hexavalent chromium in contact plating processes across EU member states. Surface treatment houses in Stuttgart and Milan are investing in trivalent chromium conversion coating capacity to preserve market access. Marine switch suppliers serving North Sea offshore vessel operators face the most acute reformulation pressure given salt-spray corrosion requirements.
Buyer consolidation among industrial equipment OEMs is compressing supplier negotiation leverage and extending payment terms. Distributor-held inventory in the US Midwest and German Ruhr industrial clusters is thinning as direct procurement between switch manufacturers and end-use equipment builders expands. This channel restructuring is most visible in material handling and agricultural machinery verticals where specification standardization has matured.
Navigation Switches Market Segmentation
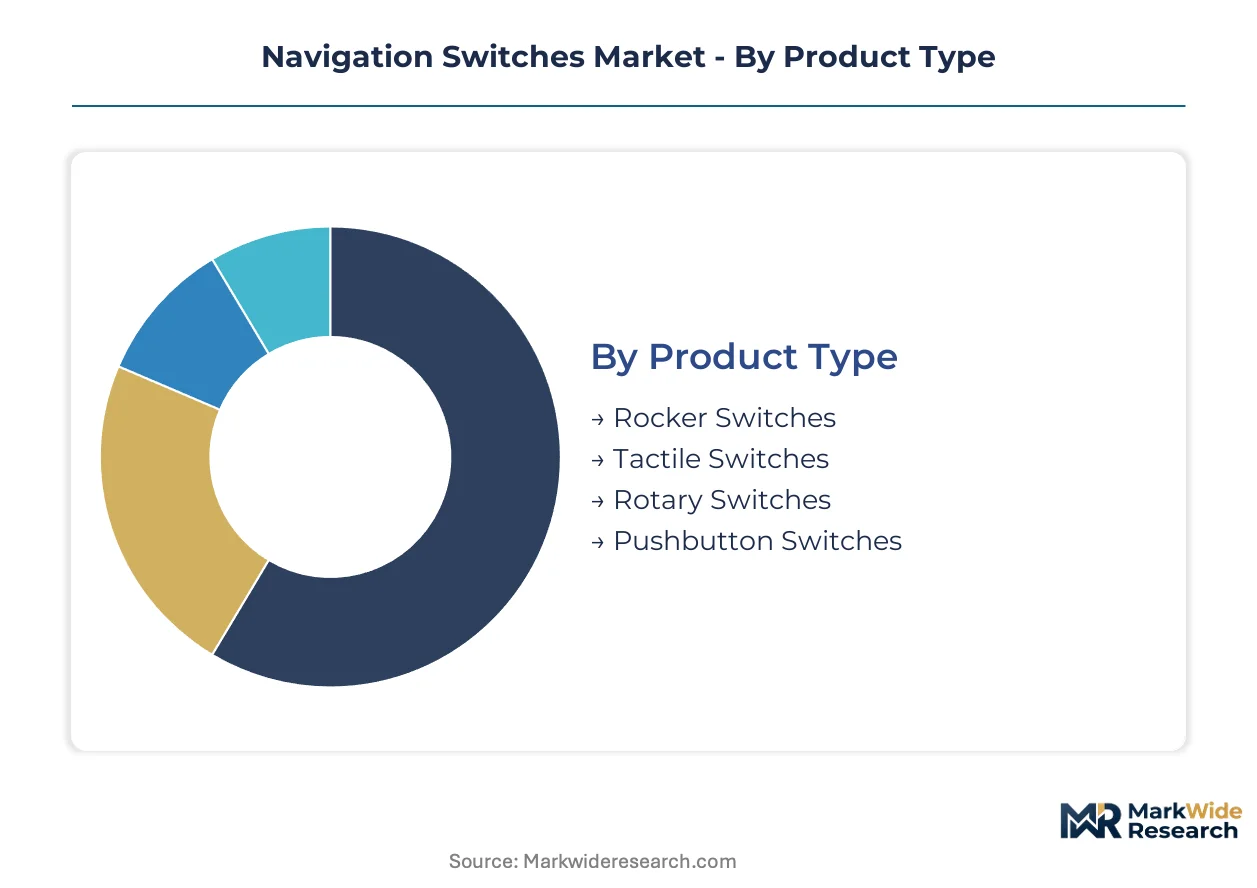
Navigation switch procurement diverges sharply across application environments, with marine and aerospace buyers demanding IP67 sealing and million-cycle durability while automotive programs prioritize electromagnetic compatibility certification. Segmentation reveals how certification burdens, material specifications, and integration complexity reshape supplier qualification requirements.
Product Type:
FCC electromagnetic interference validation applies differentially across product types, with rotary and hybrid configurations facing the most stringent signal integrity testing for aerospace and automotive deployment.
- Tactile Switches:Momentary-contact mechanisms with audible feedback and defined actuation force, typically 1-5N operating range. Demand concentrates in China's Yangtze River Delta cluster, where contract manufacturers supply industrial equipment control panels for export to North American distributors facing OSHA electrical safety compliance.
- Rotary Switches:Multi-position selectors with detent mechanisms rated for angular precision and rotational durability. Japanese aerospace subsystem integrators under METI technical standards sustain premium procurement for million-cycle-rated precision components from domestic suppliers.
- Rocker Switches:Bistable actuators with visual position indication and high current capacity.
- Pushbutton Switches:Linear-actuation devices with spring-return or latching configurations.
Leading the category by volume: Tactile Switches. Growing fastest: Rotary Switches.
End User:
Cost tiers separate qualification-intensive aerospace programs from price-sensitive industrial equipment procurement, with marine applications occupying a mid-tier position defined by corrosion resistance requirements.
- Automotive:Cockpit and center console controls subject to vibration, temperature cycling, and electromagnetic compatibility mandates. German OEMs expanding hybrid electronic-mechanical switch procurement to satisfy EU Green Deal circular economy specifications for sealed, recyclable housings.
- Marine:Salt-spray-resistant controls for navigation systems and deck equipment. North Sea offshore vessel operators drive reformulation pressure on contact plating processes under tightening REACH substance restrictions for hexavalent chromium.
- Aerospace:Precision flight deck and cabin management controls with extreme reliability requirements.
- Industrial Equipment:Factory automation and material handling controls where standardization enables multi-source procurement.
Highest certification burden: Aerospace. Largest absolute volume: Automotive.
Technology:
Application maturity determines technology adoption curves, with established mechanical platforms defending installed base against hybrid architectures in next-generation programs.
- Hybrid:Electronic-mechanical convergence combining contact durability with signal processing flexibility. German automotive Tier-1 suppliers adopt magnetoresistive position sensing modules for cockpit controllers at compressed development cycles, unifying mechanical switch and sensor supplier tiers.
- Mechanical:Pure electromechanical actuation with proven field reliability and straightforward replacement protocols. Legacy system integration friction in aerospace and marine retrofit markets preserves demand for form factors compatible with decades-old panel cutout standards.
- Electronic:Solid-state switching with no moving parts and programmable output characteristics.
- Optical:Photoelectric position sensing with inherent immunity to electromagnetic interference.
Widest installed base: Mechanical. Steepest expansion trajectory: Hybrid.
Installation Type:
Supply concentration in East Asian molding operations shapes availability of high-performance housing materials for sealed embedded configurations.
- Panel Mount:Through-hole or threaded fasteners securing switches to equipment enclosures with user-accessible actuators. Replacement-driven aftermarket in aerospace and marine sectors sustains dominant value share despite slower growth.
- Embedded:Direct integration into sealed electronic control modules with co-molded contacts in thermally conductive polymer substrates. German sealed ECU manufacturers solicit suppliers capable of collapsing assembly steps through advanced insert molding.
- Surface Mount:Solder attachment to printed circuit boards for high-density electronic assemblies.
- Portable:Handheld or detachable configurations for temporary or auxiliary control functions.
Highest margin pool: Embedded. Greatest aftermarket depth: Panel Mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate contract manufacturing for industrial navigation switch exports, while Germany's automotive corridor and Japan's precision component clusters anchor premium-tier supply.
Germany
Automotive OEMs in Stuttgart and Munich are expanding hybrid electronic-mechanical switch procurement to satisfy EU Green Deal circular economy mandates for sealed, recyclable housings. KBA vehicle certification requirements under EU electromagnetic compatibility frameworks elevate qualification barriers for imported components. The Baden-Württemberg industrial cluster hosts subsystem integrators co-developing next-generation cockpit controller modules with domestic switch suppliers.
China
Contract manufacturers in Suzhou and Ningbo scale IP67-rated tactile switch output for marine navigation system builders serving North American and European distributors. GB standards administered by SAMR govern electromagnetic compatibility testing protocols for export-bound production. The Yangtze River Delta concentration enables just-in-time supply to industrial equipment exporters facing OSHA electrical safety compliance at destination markets.
Japan
Aerospace subsystem integrators in Nagoya and Tokyo qualify domestic rotary switch suppliers against revised METI electromagnetic interference protocols. JIS standards for precision electromechanical components sustain premium procurement for million-cycle-rated navigation switches. The Chubu region's manufacturing density supports captive supply relationships between switch fabricators and tier-one cockpit system builders.
United States
Marine navigation system assemblers in the Great Lakes region and Pacific Northwest source sealed panel-mount switches for commercial vessel retrofit programs. FCC electromagnetic interference validation requirements shape product development roadmaps for suppliers targeting domestic OEMs. Midwest distributor-held inventory is thinning as direct procurement between switch manufacturers and end-use equipment builders expands in material handling verticals.
South Korea
High-performance liquid crystal polymer compounders in Seoul and Busan supply specialized housing grades for IP67 sealing applications, creating critical input concentration for embedded switch configurations. MIIT-aligned export quality frameworks govern batch consistency for thermally conductive polymer substrates. The Seoul Capital Area's materials science infrastructure supports insert molding capabilities sought by German sealed ECU manufacturers.
Navigation Switches Market Competitive Landscape
Japanese producers anchor the precision-tier supply base; German automotive-channel specialists hold the hybrid-architecture segment. The vendor base fragments across three tiers: diversified electromechanical conglomerates with captive aerospace and automotive channels, precision component specialists focused on million-cycle durability ratings, and contract manufacturers serving industrial price-sensitive procurement. Strategic moves concentrate on backward integration into high-performance polymer compounding and co-development partnerships with sealed ECU manufacturers.
Among diversified industrial conglomerates, Bosch and Panasonic Corporation exemplify scale-driven positions spanning automotive cockpit systems and industrial automation channels. Alps Alpine occupies a specialist tier focused on precision rotary configurations for aerospace and premium automotive applications. C&K Components represents the miniaturization-focused archetype, with component architectures designed for embedded installation densities. These three anchors illustrate how competitive positioning diverges between durability-certification depth and channel-control breadth.
| Leading Market Players |
|---|
| APEM |
| Adafruit Industries |
| C&K Components |
| E-Switch |
| Grayhill |
| Bosch |
| Panasonic Corporation |
| Continental AG |
| Alps Alpine |
| Others |
Supply & Pricing Matrix
Palladium and gold contact plating costs flow from South African and Russian mining operations through Tokyo and Stuttgart precious metal refiners into three-tier pricing structures across premium, standard, and economy levels for navigation switch manufacturers. This upstream concentration grants compounders in Seoul and Busan outsized leverage over IP67 sealing grade availability, compressing margin pools for mid-tier suppliers without captive refining partnerships or long-term offtake arrangements.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with German automotive Tier-1s paying premiums for four-week delivery windows on hybrid electronic-mechanical configurations while spot inventory in US Midwest distributors trades at discounts. Price differentiation hinges on METI electromagnetic interference certification tier and volume scale, with million-cycle-rated rotary switches commanding substantial premiums over standard industrial grades. Pricing pressure stems from touchscreen substitution in consumer automotive infotainment, eroding mechanical switch volumes in price-sensitive cockpit segments while marine and aerospace buyers show minimal price elasticity due to regulatory mandates.
Supply Chain Analysis
Single-source vulnerability sits with high-performance liquid crystal polymer housing production concentrated among specialized compounders in South Korea and Taiwan, creating critical input bottlenecks for embedded switch configurations. Raw material dependencies center on palladium and gold for electrical contact surfaces, copper alloys for conductive substrates, and engineered thermoplastics for sealed housings. Supply chain risk manifests as tariff exposure on precision-machined components from East Asian molding operations. Distribution runs through direct procurement channels expanding between switch manufacturers and end-use equipment builders, displacing traditional distributor-held inventory in German Ruhr and US Midwest industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Navigation switch procurement consolidation among industrial equipment OEMs is compressing supplier negotiation leverage and forcing weaker players without certification depth or polymer compounding capabilities toward exit. REACH substance restrictions and electromagnetic compatibility mandates are elevating cost-of-entry barriers that favor incumbents with established analytical laboratories.
For Market Incumbents: Lock in captive supply relationships with Seoul-based liquid crystal polymer compounders to secure IP67 sealing grade allocation ahead of capacity constraints. Deepen backward integration into contact plating operations through partnerships with Stuttgart surface treatment houses investing in trivalent chromium conversion coating capacity. Channel control expansion into sealed electronic control unit co-development partnerships with German Tier-1 suppliers offers defensive positioning against touchscreen substitution threats in automotive cockpit applications. For New Entrants and Emerging Players: India's domestic construction machinery OEMs under PLI scheme incentives represent the most penetrable buyer archetype for certified navigation switch exporters seeking first-mover positioning. Target industrial equipment retrofit markets in North American material handling verticals where specification standardization has matured and distributor inventory thinning creates direct procurement access. A go-to-market angle anchored to REACH and RoHS compliance certification investments differentiates against Asian competitors lacking established analytical laboratory infrastructure. For Investors and Strategic Acquirers: Japanese aerospace subsystem integrators qualifying domestic rotary switch suppliers against revised METI electromagnetic interference protocols is the leading indicator that precision-tier supply relationships are consolidating around million-cycle-rated specialists. The five-to-ten-year viability window favors acquisition targets with captive manufacturing in Japan or Germany and established channels into cockpit system builders. Watch for German sealed ECU manufacturers soliciting switch suppliers capable of co-molding contacts directly into thermally conductive polymer substrates as the inflection signal for embedded module integration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Seoul compounders' IP67 grade concentration creates captive supply advantages for embedded switch manufacturers. |
| Co-Development Partnership with Sealed ECU Manufacturers | German Tier-1 cockpit controller modules collapse assembly steps through advanced insert molding capabilities. |
| Certification Investment in METI Electromagnetic Interference Standards | Japanese aerospace integrators sustain premium procurement for domestically qualified precision rotary suppliers. |
| Geographic Manufacturing Footprint Expansion | India PLI scheme incentives open qualification pathways for imported navigation switches in construction machinery. |
| Long-Term Supply Agreement with Precious Metal Refiners | Palladium price volatility hedging preserves margin pools for mid-tier suppliers without captive refining partnerships. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this navigation switches market analysis, supplemented by primary interviews with Tier-1 automotive procurement officers, aerospace subsystem integrators, marine navigation system assemblers, and industrial equipment OEM engineering directors. Bottom-up triangulation across product type volumes and end-use segment qualification requirements reconciled with top-down validation against electromagnetic compatibility certification databases maintained by FCC, EU notified bodies, and METI technical standards divisions.
Data-stream reconciliation across shipment volumes, certification timelines, and raw material input costs informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-use application, technology architecture, installation configuration, and regional regulatory cluster. CAGRs derived from historical shipment trajectories adjusted for procurement cycle compression effects and OEM supplier base consolidation patterns. Industry-specific forecast inputs incorporated REACH substance restriction phase-in schedules and EU Green Deal circular economy mandate implementation timelines.
Revisions become necessary when palladium and gold price volatility exceeds historical bands, when liquid crystal polymer compounder capacity constraints materialize, or when electromagnetic compatibility test methodology divergence between US and EU jurisdictions widens. Forecasts reflect documented assumptions about OEM procurement consolidation velocity and touchscreen substitution ceiling persistence in commercial marine and heavy industrial segments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
UK Reed Sensors Switches Market
Switches
Reed Switches Sensors Market
Switches
South America Low Voltage Switchgear Market
Switches
Differential Pressure Switches Market
Switches
Global Electrical Switches Market
Switches
United States Circuit Breaker Market
Switches
DC Circuit Breaker Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
5G Solid State Switches Market
Switches
Panel Mounted Disconnect Switch Market
Switches
ASEAN Switchgear Market
Switches
Low Voltage Disconnect Switch Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Pad-Mounted Switchgear Market