
 Panel Mounted Disconnect Switch Market | 2026-2036
Panel Mounted Disconnect Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Panel Mounted Disconnect Switch Market Insights
The split between premium fused disconnect switches and commodity non-fused variants is realigning procurement patterns across utility and industrial accounts. ABB leverages its IEC-rated portfolio to dominate European infrastructure retrofits. Schneider Electric anchors North American utility spending through its Square D brand and UL-certified safety switch lines. Siemens competes on integrated power distribution platforms that bundle disconnect functions with smart monitoring.
A panel mounted disconnect switch is an enclosed switching device permanently affixed to an electrical panel or switchboard, typically rated between 30 and 1200 amperes with visible blade contact indication for lockout-tagout compliance. Its primary purpose is to isolate downstream circuits for maintenance, emergency shutdown, or sectionalized protection in industrial and commercial power systems. The fuse switch segment leads absolute volume due to mandatory overcurrent protection in legacy manufacturing plants and mining operations. Solid state technology variants represent the fastest-growing technology category as semiconductor-based isolation reduces arc flash hazards and extends operational life in data center and telecommunications applications. Rotary switch configurations occupy stable replacement demand across commercial buildings where manual operation and mechanical simplicity reduce training burdens.
UL 98 and IEC 60947-3 govern product certification and directly determine market access for suppliers targeting North American and European installations respectively. OSHA lockout-tagout regulations and the EU Machinery Directive compel end users in manufacturing plants and machinery control to specify visible-break disconnect switches over less expensive alternatives. Utility providers face additional pressure from NERC reliability standards and national grid codes that mandate proven fault-current interruption capability. Stakeholders must monitor evolving arc flash energy reduction requirements and semiconductor material supply constraints as they weigh R&D allocation between electromechanical durability and solid state integration.
Market Dynamics
Data center electrification and tightening fault-current certification standards are compressing procurement cycles for high-ampacity disconnect switches while fragmenting supplier power across regional certification regimes.
Growth Catalysts
- IEC 60947-3 certification mandates:European infrastructure retrofits require visible-break isolation for machinery safety compliance under the EU Machinery Directive, forcing replacement of legacy non-compliant switches in German and French manufacturing plants.
- Data center power density:Hyperscale facilities in the United States are specifying 800-1200 ampere fused disconnects for critical busway distribution as rack densities exceed 30kW per cabinet.
- Solid-state semiconductor isolation:Silicon carbide-based disconnect modules eliminate arc flash hazards in telecommunications central offices, extending operational life beyond electromechanical alternatives.
Market Restraints
- Copper and silver contact material volatility:Spot price swings for conductive alloys compress margin buffers for mid-tier manufacturers sourcing from Chilean and Peruvian concentrate markets.
- UL 98 certification timeline friction:Extended fault-current withstand testing protocols delay North American market entry for European suppliers lacking pre-certified component platforms.
- Integrated circuit breaker substitution:Molded case circuit breakers with electronic trip units capture share in commercial building applications where visible-break isolation is not mandated.
Strategic Opportunities
- India industrial corridor electrification:CEA mandates for dedicated feeder isolation in steel and cement plants create demand for 400-800 ampere rotary disconnects in Gujarat and Tamil Nadu manufacturing clusters.
- Smart monitoring convergence:Integration of disconnect switches with IIoT-enabled thermal sensing and predictive maintenance platforms opens premium pricing in semiconductor fabrication facilities.
- Direct utility procurement channels:Bypassing traditional electrical distributors, manufacturers are contracting directly with state grid operators in China for substation sectionalizing switchgear.
Industry Challenges
- Arc flash energy calculation expertise:Shortage of qualified engineers capable of IEEE 1584 compliance documentation slows specification support for complex industrial installations.
- Legacy electromechanical integration:Retrofitting solid-state disconnects into 1980s-era MCCs requires custom busbar adaptation, extending project timelines and contractor liability exposure.
- Dual certification inventory burden:Maintaining parallel UL 98 and IEC 60947-3 product lines strains working capital for suppliers serving both North American and European accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panel Mounted Disconnect Switch Market |
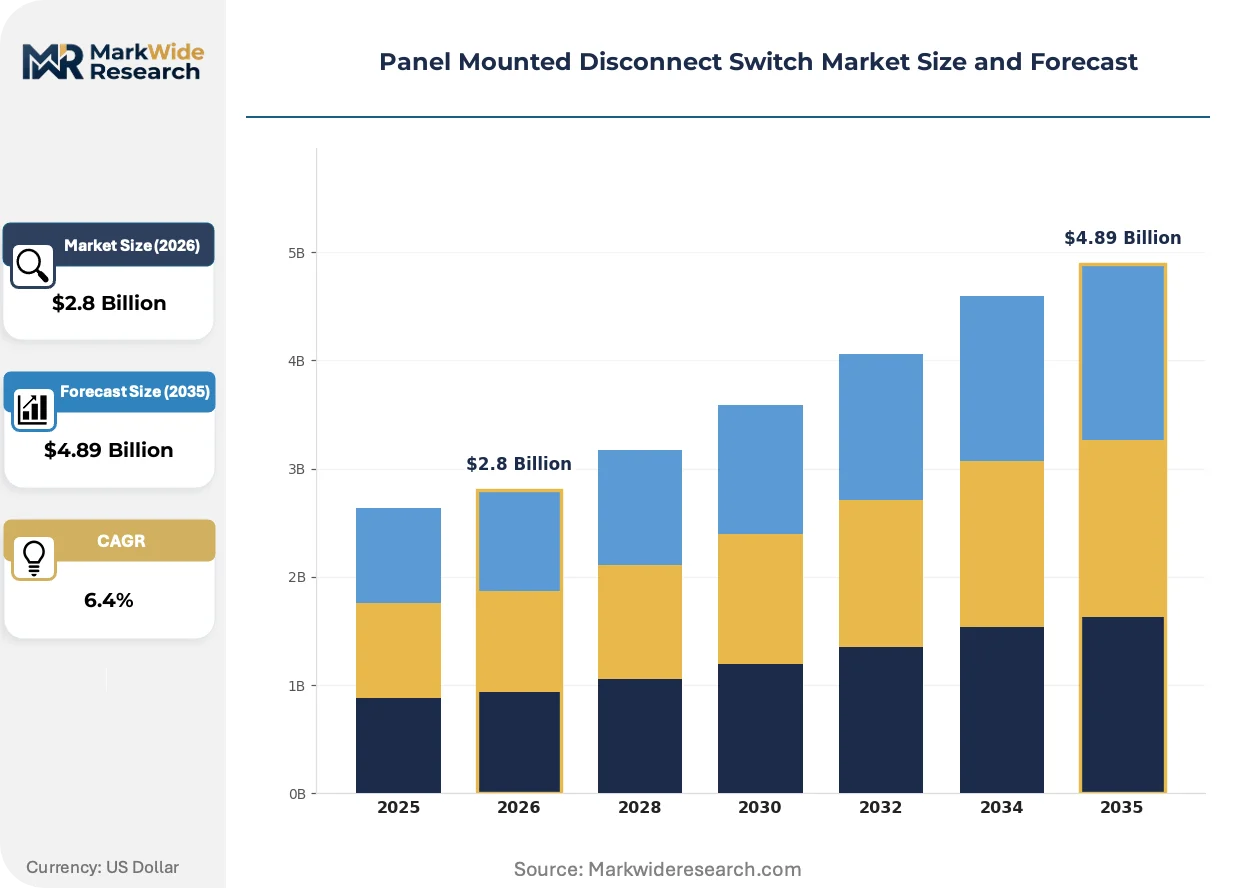
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuse Switch, Knife Switch, Rotary Switch, Safety Switch, Cam Switch, Snap Switch Technology: Electromechanical, Solid State, Magnetic, Thermal, Electronic, Manual Application: Power Generation, Electrical Distribution, Machinery Control, Warehouse Automation, Data Centers, Telecommunications End User Industry: Manufacturing Plants, Mining Operations, Transportation Facilities, Utility Providers, Commercial Buildings, Government Facilities |
| Companies Covered | ABB, Schneider Electric, Siemens, Eaton, Rockwell Automation, Legrand, Socomec, Littelfuse, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panel Mounted Disconnect Switch Market Trends and Innovations
Solid-state isolation, arc flash energy reduction mandates, and procurement centralization by hyperscale data center operators are compressing traditional electromechanical switch lifecycles and rewiring channel economics.
Silicon carbide power semiconductors are rewriting the technical basis for circuit isolation. Data center operators in Northern Virginia and Frankfurt are specifying solid-state disconnect modules for 480V busway distribution, eliminating mechanical wear and enabling sub-cycle interruption. This compression of switching physics is forcing incumbent electromechanical suppliers to defend installed base through service contracts rather than replacement hardware.
OSHA's updated enforcement emphasis on documented lockout-tagout procedures is tightening specification standards for visible-break indication. Industrial facilities in Texas and Ohio are rejecting non-fused alternatives that lack blade visibility, even where code minimums would permit them. The compliance premium is widening price spreads between certified safety switches and commodity imports.
Consolidated procurement by cloud infrastructure operators is disintermediating traditional electrical distributors. Amazon Web Services and Microsoft Azure are negotiating direct master service agreements with ABB and Schneider Electric for standardized disconnect specifications across their global facility portfolios, compressing distributor margins and forcing channel partners toward service bundling.
Panel Mounted Disconnect Switch Market Segmentation
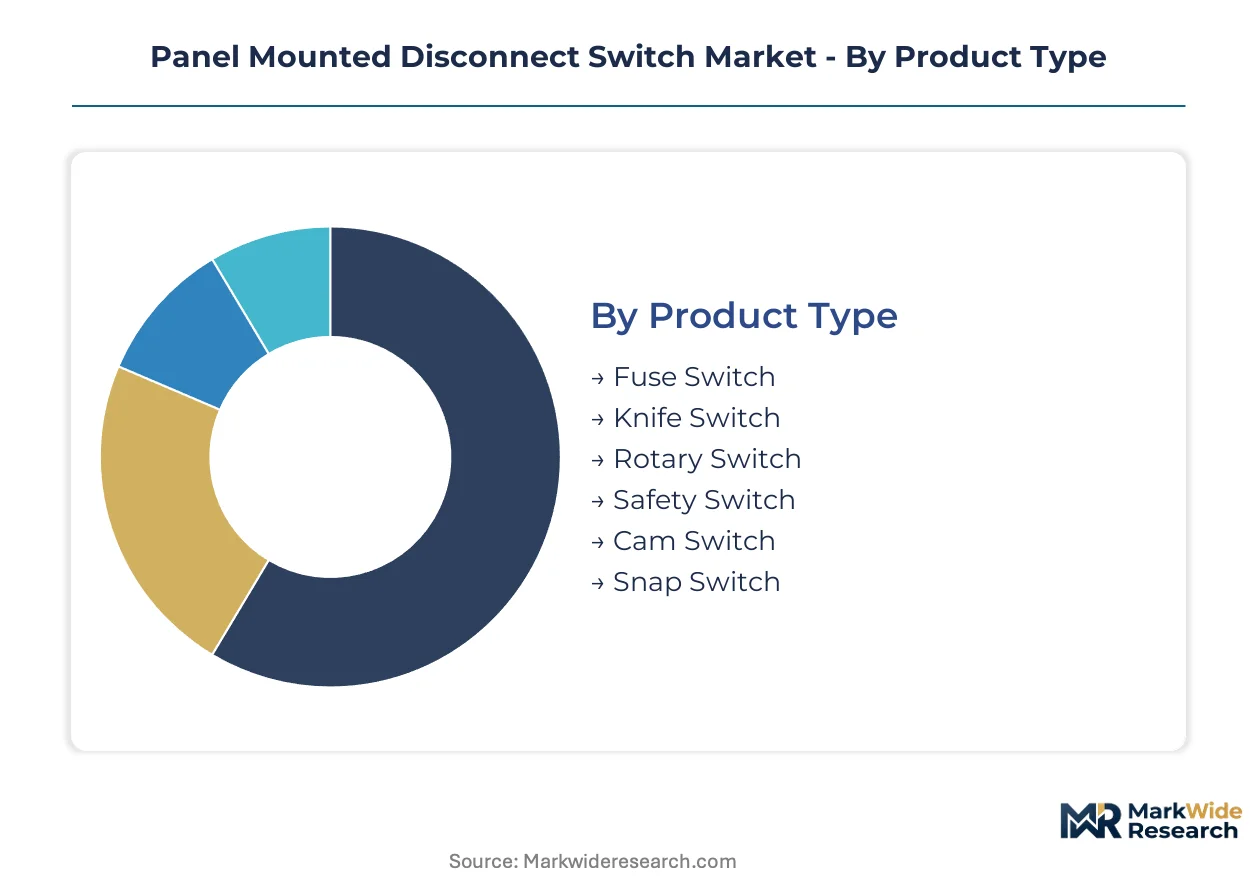
Segmentation in the panel mounted disconnect switch market reflects divergent engineering requirements across voltage ratings, operational environments, and regulatory jurisdictions. Procurement specifications vary sharply between legacy industrial retrofits demanding mechanical simplicity and hyperscale data centers prioritizing semiconductor-based isolation. Understanding these fault lines enables suppliers to align certification investments with actual demand concentration.
Product Type:
Standardization dominates at the commodity end of this spectrum, while premium fused variants require extensive customization for fault-current coordination.
- Fuse Switch:Integrates overcurrent protection with visible-break isolation in a single enclosure, typically rated 30-1200 amperes. German and French manufacturing plants under EU Machinery Directive mandates are replacing legacy non-fused alternatives, sustaining replacement demand despite longer lifecycles of competing technologies.
- Rotary Switch:Employs a rotating cam mechanism to open and close circuits with mechanical simplicity that reduces training burdens. Commercial buildings across Texas and Ohio specify these for HVAC and lighting isolation where OSHA lockout-tagout compliance requires visible blade indication without premium fused protection.
- Knife Switch:Open-blade design offers lowest-cost visible-break isolation for non-critical applications.
- Safety Switch:Enclosed construction with interlocked covers prevents access under load; common in utility substations.
- Cam Switch:Multi-position rotary contact system supports complex switching sequences in control circuits.
- Snap Switch:Quick-make/quick-break action reduces arcing in lower-amperage commercial installations.
Most installed capacity flows through fuse switch configurations. Expansion is steepest in safety switch variants as NERC reliability standards tighten utility procurement.
Technology:
Cost tiers separate mature electromechanical platforms from emerging semiconductor architectures that command 3-4x price premiums.
- Electromechanical:Physical contact opening via springs, solenoids, or manual force remains the volume foundation. Indian steel and cement plants in Gujarat and Tamil Nadu under CEA mandates specify 400-800 ampere rotary electromechanical units for feeder isolation, prioritizing field serviceability over advanced features.
- Solid State:Silicon carbide power semiconductors enable sub-cycle interruption without mechanical wear. Northern Virginia and Frankfurt data centers specify these for 480V busway distribution to eliminate arc flash hazards and extend operational life beyond electromechanical alternatives.
- Magnetic:Electromagnetic force drives contact separation; common in high-speed switching applications.
- Thermal:Bimetallic elements provide time-delayed response for motor protection circuits.
- Electronic:Microprocessor-controlled trip units enable programmable protection curves.
- Manual:Direct operator action without powered assistance; lowest cost for infrequent switching.
Electromechanical platforms retain the largest installed base. Solid state technology is climbing the fastest as semiconductor fabrication facilities adopt IIoT-enabled thermal sensing integration.
Application:
Customer type fragmentation splits between centralized utility procurement and distributed industrial specification.
- Data Centers:Hyperscale operators in the United States specify 800-1200 ampere fused disconnects for critical busway distribution as rack densities exceed 30kW per cabinet. Amazon Web Services and Microsoft Azure negotiate direct master service agreements with manufacturers, bypassing traditional electrical distributors.
- Machinery Control:Manufacturing plants require visible-break isolation for lockout-tagout compliance on production equipment. OSHA enforcement emphasis on documented procedures is tightening rejection of non-visible alternatives even where code minimums would permit them.
- Power Generation:Conventional and renewable generation facilities need sectionalizing capability for maintenance.
- Electrical Distribution:Utility and commercial substations rely on disconnects for feeder isolation.
- Warehouse Automation:Automated material handling systems demand reliable isolation for conveyor and robotic systems.
- Telecommunications:Central offices and cell towers require compact isolation for DC power distribution.
Electrical distribution absorbs the greatest unit volume. Data center applications are gaining share fastest as cloud infrastructure procurement centralizes.
End User Industry:
Geographic concentration in industrial electrification corridors determines regional specification preferences.
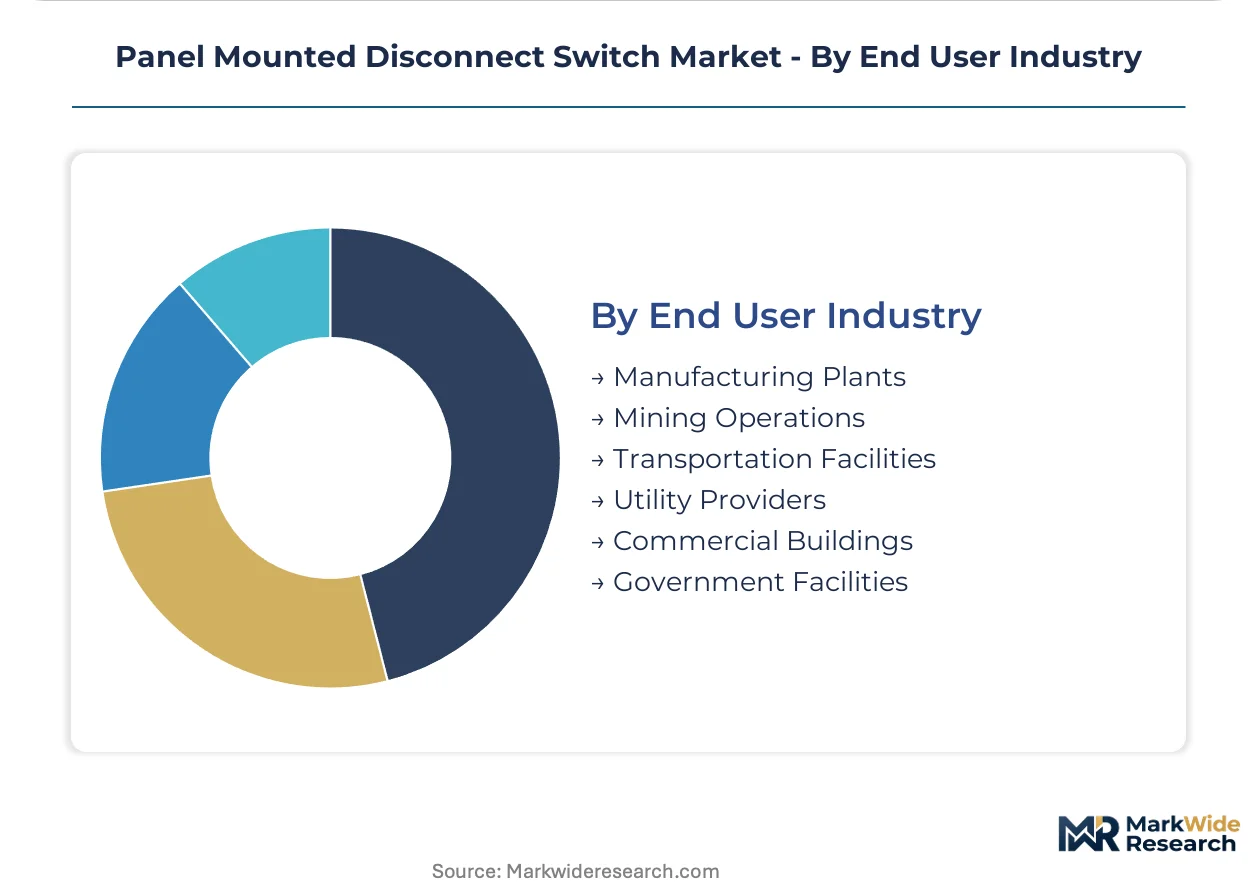
- Manufacturing Plants:Legacy facilities across the United States, Germany, and China drive replacement cycles as IEC 60947-3 and UL 98 standards tighten certification requirements for fault-current withstand ratings. Retrofitting solid-state disconnects into 1980s-era motor control centers requires custom busbar adaptation, extending project timelines.
- Utility Providers:State grid operators in China contract directly with manufacturers for substation sectionalizing switchgear, compressing distributor margins. NERC reliability standards and national grid codes mandate proven fault-current interruption capability.
- Mining Operations:Harsh environments demand sealed enclosures and corrosion-resistant contacts.
- Transportation Facilities:Airports and rail systems require high-availability isolation for critical loads.
- Commercial Buildings:Office and retail installations prioritize cost-minimization where visible-break mandates do not apply.
- Government Facilities:Federal and military procurement emphasizes domestic content and extended warranties.
Manufacturing plants represent the largest current deployment. Utility provider procurement is expanding most quickly as grid modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical engineers and power systems specialists concentrate in industrial corridors where manufacturing electrification and data center construction create sustained demand for certified disconnect solutions.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives procurement of 800-1200 ampere fused disconnects for critical busway distribution. OSHA lockout-tagout enforcement tightens rejection of non-visible alternatives in Texas and Ohio manufacturing plants. Cloud infrastructure operators negotiate direct master service agreements with manufacturers, compressing traditional distributor margins.
Germany
EU Machinery Directive mandates force replacement of legacy non-compliant switches in manufacturing plants across Baden-Württemberg and Bavaria. IEC 60947-3 certification requirements dominate procurement specifications for machinery safety compliance. Industrial retrofits in the Stuttgart and Munich manufacturing clusters sustain replacement demand for premium fused variants despite longer solid-state lifecycles.
China
State grid operators contract directly with manufacturers for substation sectionalizing switchgear, bypassing traditional distribution channels. National grid codes and reliability standards mandate proven fault-current interruption capability for utility infrastructure. Manufacturing electrification accelerates in Jiangsu and Guangdong provinces where industrial parks upgrade feeder isolation systems.
India
CEA mandates for dedicated feeder isolation in steel and cement plants create demand for 400-800 ampere rotary disconnects. Central Electricity Authority regulations drive specification standardization across heavy industry installations. Manufacturing clusters in Gujarat and Tamil Nadu prioritize field serviceability in electromechanical units for cement and steel production facilities.
France
ANSM machinery safety oversight reinforces EU Machinery Directive compliance for visible-break isolation in industrial equipment. Manufacturing plants in the Île-de-France and Auvergne-Rhône-Alpes regions replace legacy switches to meet tightened certification timelines. Nuclear and aerospace industrial bases in these clusters demand proven fault-current withstand ratings for critical power distribution.
Panel Mounted Disconnect Switch Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across certification-bound market segments. The supplier base fragments across regional certification regimes, with UL 98 and IEC 60947-3 standards creating parallel product line requirements. Three archetypes dominate: integrated power distribution platform providers, certification-specialized safety switch manufacturers, and semiconductor-based isolation technology developers. Competitive moves center on direct utility procurement channel development and IIoT-enabled predictive maintenance platform integration.
Among European-originated industrial conglomerates, ABB, Schneider Electric, and Siemens occupy positions spanning multiple certification jurisdictions. ABB represents the integrated platform archetype with broad IEC-rated portfolios. Schneider Electric anchors North American utility spending through established safety switch lines. Siemens exemplifies the bundled solution approach combining disconnect functions with smart monitoring capabilities. These three anchor the premium tier where dual certification inventory requirements strain working capital for smaller competitors.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton |
| Rockwell Automation |
| Legrand |
| Socomec |
| Littelfuse |
| Mitsubishi Electric |
| Others |
Pricing and Supply Chain Analysis
Hyperscale data center operators negotiating direct master service agreements with manufacturers have collapsed traditional distributor markups and forced pricing stratification across certification tiers rather than brand premiums.
Pricing Analysis
Service bundling separates pure hardware transactions from predictive maintenance contracts. Premium-mid-economy pricing differentiation rests on dual UL 98 and IEC 60947-3 certification status, with fault-current withstand ratings commanding substantial uplifts. Cost compression in commodity electromechanical tiers is intensifying because copper and silver contact material volatility erodes margin buffers. Mid-tier manufacturers serving Indian cement and steel plants exhibit the highest price sensitivity, while Northern Virginia data center operators prioritize arc flash elimination over unit cost.
Supply Chain Analysis
Container freight rates from Chinese and German manufacturing hubs directly impact landed costs for North American utility procurement. Silicon carbide semiconductor substrates draw from Japanese and American wafer fabrication, while copper contact alloys source from Chilean and Peruvian concentrate markets. Single-source vulnerability in semiconductor-grade silicon carbide threatens solid-state disconnect production scaling. Distribution runs through direct utility contracting channels that bypass traditional electrical distributors in China and increasingly in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as OSHA enforcement and EU Machinery Directive mandates shift procurement toward visible-break certified safety switches over commodity alternatives.
For Market Incumbents: Anticipate solid-state substitution pressure by deepening IIoT-enabled predictive maintenance platforms that extend electromechanical installed base retention. Capture stranded asset value in 1980s-era motor control centers through service contracts rather than hardware replacement. Prioritize dual certification inventory optimization to reduce working capital strain from parallel UL 98 and IEC 60947-3 product lines. For New Entrants and Emerging Players: Enter via semiconductor-based isolation modules for telecommunications central offices where electromechanical incumbents lack technical credibility. Target Indian steel and cement clusters in Gujarat and Tamil Nadu where CEA mandates create specification windows for 400-800 ampere rotary disconnects. Lead with field serviceability and rapid busbar adaptation capabilities that accelerate retrofit timelines. For Investors and Strategic Acquirers: Electrical distributors with captive utility relationships are the most active acquirer in this space as channel disintermediation threatens traditional margin structures. Five-to-ten year viability favors suppliers with demonstrated dual certification platforms and direct procurement capabilities with state grid operators. Monitor hyperscale data center capex announcements as the critical inflection signal for solid-state demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Platform Investment | Parallel UL 98 and IEC 60947-3 approval opens access to both North American and European utility procurement channels. |
| Solid-State Module Development | Silicon carbide-based isolation eliminates arc flash hazards and extends operational life beyond electromechanical alternatives in data centers. |
| Direct Utility Contracting Capability | Bypassing electrical distributors captures margin compression from hyperscale operator procurement centralization. |
| IIoT Predictive Maintenance Integration | Thermal sensing platforms enable premium pricing in semiconductor fabrication facilities requiring continuous uptime. |
| Indian Industrial Corridor Localization | CEA-mandated feeder isolation in Gujarat and Tamil Nadu steel and cement plants creates specification-driven demand. |
Research Methodology
Bottom-up data center and manufacturing plant modeling reconciled against top-down utility procurement tracking forms the analytical core of this study. Primary interviews with plant maintenance directors, OEM procurement teams, electrical distributor category managers, and utility planning officers combined with secondary validation from SEC filings, EIA infrastructure databases, CEA regulatory notifications, and customs trade records. Triangulation across stakeholder perspectives and documentary sources ensures segment-level accuracy.
Input-output matrices connect installed base estimates, replacement cycle assumptions, and specification trend trajectories across the projection horizon. Segmentation dimensions include product type, technology platform, application vertical, end-user industry, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to base-year sizing, with sensitivity testing against copper price volatility and semiconductor material supply constraints.
The model holds under steady regulatory enforcement intensity and continued hyperscale data center expansion; deviation in OSHA audit frequency or cloud infrastructure capex retrenchment would shift replacement demand timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Touchpad Market
Switches
Canada Switch Gear Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Transfer Switch Market
Switches
Optical Switches Market
Switches
Intelligent Power Switches Market
Switches
Rotary Limit Switches Market
Switches
Vibration Level Switch Market
Switches
Mexico Rocker Switch Market
Switches
Matrix Switches Market
Switches
Surface Mount Switch Market
Switches
Smart Home Switches Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Tactile Switch Keyboard Market
Switches
Membrane Switch Market