
 United States X by Wire Systems Market | 2026-2036
United States X by Wire Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United States X by Wire Systems Market Analytics
Michigan is rewriting the competitive map for X by wire systems as Detroit-area suppliers expand electromechanical actuator capacity. Nexteer Automotive leverages its steering-system heritage to anchor position in steer-by-wire modules. Tesla Inc. dominates integrated vehicle-control architectures with in-house wire-system development. Robert Bosch GmbH sustains R&D intensity across braking and steering electronics for US OEM programs.
X by wire systems replace mechanical linkages with electronic signal transmission, typically employing redundant copper conductors, fiber optic channels, and real-time control algorithms to execute driver or autonomous-system commands at actuators. These architectures eliminate hydraulic fluids and mechanical rods, reducing vehicle weight while enabling software-defined vehicle dynamics. Copper Wires occupy the largest product share given conductivity requirements in power-hungry brake and steering actuators, while Fiber Optic Wires represent the fastest-growing product type as latency-sensitive autonomous systems demand electromagnetic-interference immunity. Automotive End Users command the dominant demand pool, though Energy sector applications in grid modernization are expanding fastest for remote actuation and monitoring.
NHTSA, the EPA, and FCC standards collectively shape US market access, with NHTSA mandating functional-safety validation for drive-by-wire systems and FCC regulating wireless redundancy channels. State-level zero-emission vehicle rules in California and New York indirectly accelerate wire-system adoption by expanding electric vehicle platforms that rely on electronic control architectures. Stakeholders must monitor pending NHTSA rulemakings on automated driving system redundancy requirements and assess supplier readiness for mixed-material wire harnesses that integrate copper power conductors with fiber optic data pathways.
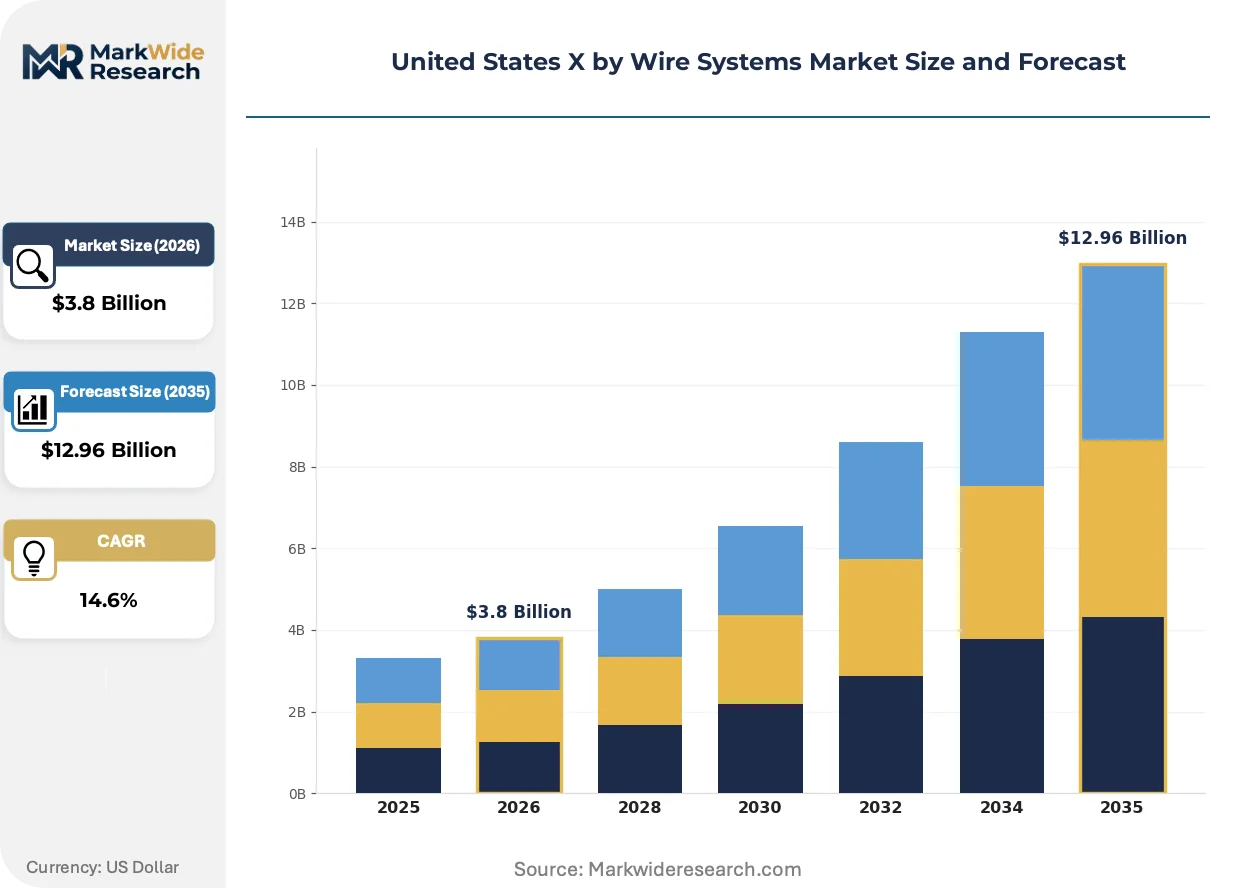
Market Dynamics
NHTSA's pending automated driving system redundancy requirements are compressing supplier certification timelines while Michigan and Ohio OEMs accelerate steer-by-wire procurement to lock in electromechanical actuator capacity ahead of compliance deadlines.
Growth Catalysts
- California ZEV Mandates:State-level zero-emission vehicle rules in California and New York expand electric vehicle platforms that rely on electronic control architectures, pulling wire-system demand from Detroit-area suppliers.
- FCC Wireless Redundancy Channels:FCC regulations governing wireless backup pathways for drive-by-wire systems enable failover architectures that satisfy NHTSA functional-safety validation requirements.
- Texas Grid Modernization:Energy sector applications in remote actuation and monitoring for grid infrastructure represent expanding demand outside automotive verticals.
Market Restraints
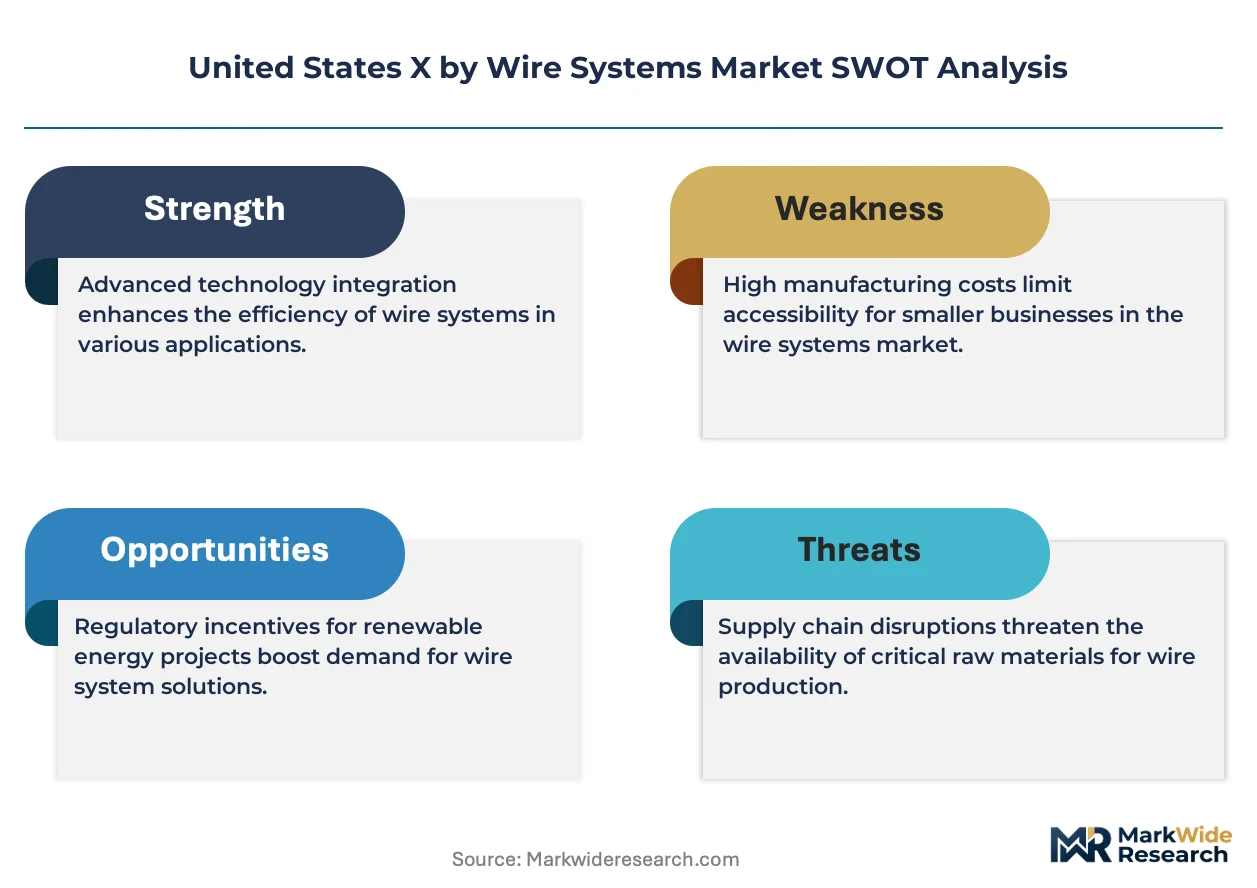
- Copper Price Volatility:Power-hungry brake and steering actuators depend on copper conductors, exposing OEMs to commodity input cost swings that compress module margins.
- Michigan Supply Concentration:Electromechanical actuator capacity clusters in Detroit-area suppliers, creating geographic single-point-of-failure risk for national OEM programs.
- Hydraulic Legacy Substitution:Conventional hydraulic braking and steering systems retain cost advantages in heavy-duty commercial segments, slowing wire-system penetration in fleet applications.
Strategic Opportunities
- Autonomous Vehicle Testing Corridors:California's designated autonomous testing zones concentrate latency-sensitive fiber optic demand for electromagnetic-interference immunity in sensor fusion architectures.
- Mixed-Material Harness Integration:Supplier readiness for copper-fiber hybrid wire pathways creates white space in harness manufacturing for software-defined vehicle dynamics.
- IRA Clean Energy Incentives:Federal production tax credits for domestic manufacturing of advanced automotive components accelerate reshoring of wire-system module assembly.
Industry Challenges
- ISO 26262 Functional Safety Expertise:Shortage of ASIL-D certified systems engineers extends development cycles for steer-by-wire and brake-by-wire validation.
- Legacy Fleet Retrofit Integration:Compliance-driven NHTSA retrofits face mechanical interface incompatibility with existing chassis architectures, forcing custom engineering per vehicle platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States X by Wire Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Wires, Fiber Optic Wires, Aluminum Wires, Specialty Wires End User: Telecommunications, Automotive, Aerospace, Energy Installation Type: Indoor, Outdoor, Industrial, Residential Application: Data Transfer, Power Distribution, Signal Transmission, Control Systems |
| Companies Covered | Nexteer Automotive, ZF Friedrichshafen AG, Infineon Technologies, Orscheln Products LLC, General Motors, Tesla Inc., Torc Robotics, Lokar Performance Products, Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States X by Wire Systems Market Evolving Landscape
Software-defined vehicle dynamics are compressing hardware refresh cycles as automakers decouple mechanical linkages from control logic, enabling over-the-air updates that extend system functionality without physical redesign.
Redundant fiber optic data pathways are migrating from aerospace-grade heritage to automotive steer-by-wire architectures. Tier 1 suppliers in Michigan are adopting these channels for autonomous vehicle programs. The technology is migrating from defense-industry cost structures to mass-production pricing models that enable mainstream OEM deployment.
NHTSA rulemakings on automated driving system redundancy requirements are mandating dual-channel validation for safety-critical actuators. This regulatory pressure forces suppliers to maintain parallel copper and fiber development tracks. Brake-by-wire modules face the steepest compliance burden as stopping systems trigger the most stringent functional-safety thresholds.
Fleet procurement departments are consolidating supplier relationships around full-system integrators capable of delivering combined steering, braking, and powertrain control modules. This buyer concentration displaces component-level sourcing for discrete wire-system elements. Texas energy utilities and California autonomous shuttle operators exhibit the most advanced consolidated procurement patterns.
United States X by Wire Systems Market Segmentation
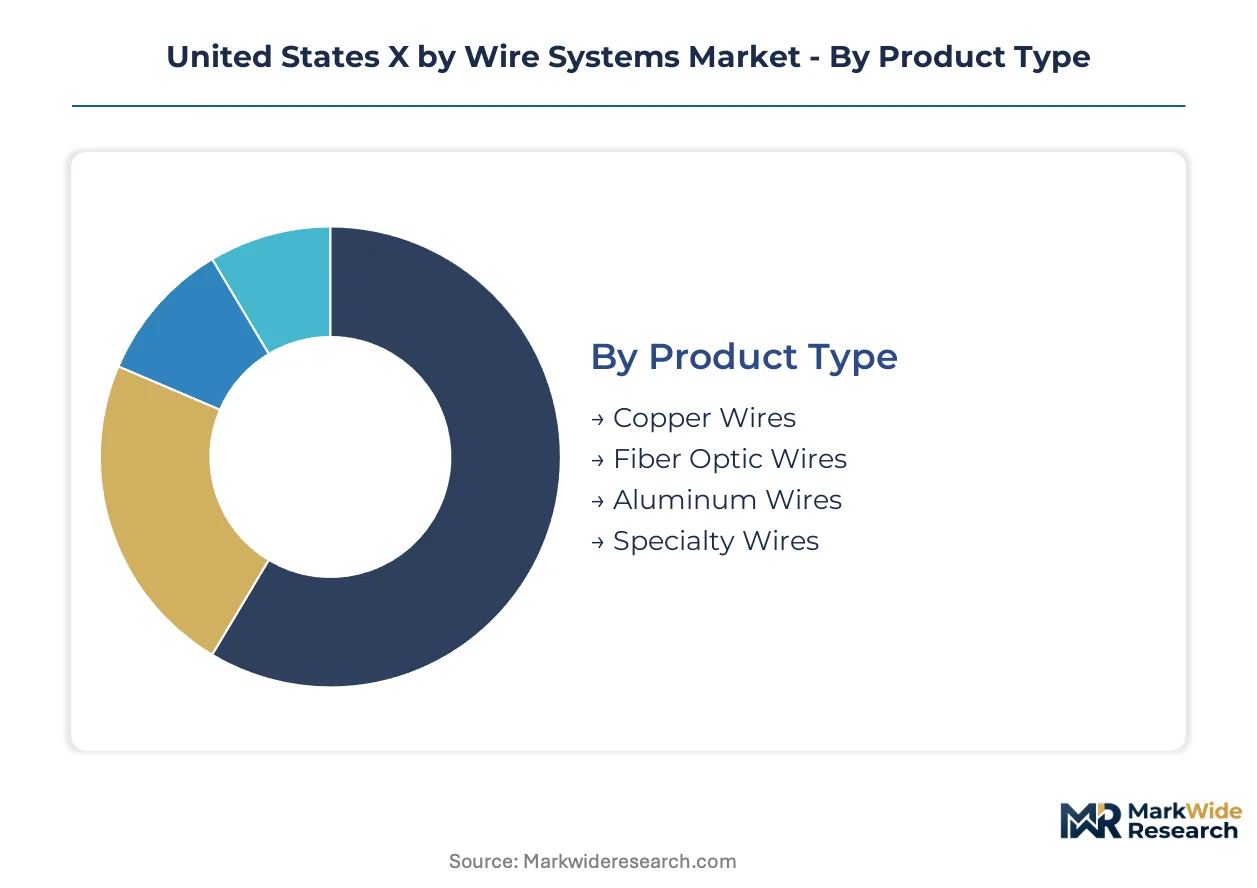
X by wire systems fragment across material, end-use, and installation contexts that dictate procurement cycles and certification burdens. Copper and fiber optic pathways operate on fundamentally different replacement timelines, while automotive and energy verticals impose divergent safety-validation requirements.
Product Type:
Copper wires turn over fastest due to commodity pricing exposure and thermal cycling fatigue, while specialty wires persist longest through custom engineering lock-in.
- Copper Wires:High-conductivity oxygen-free copper conductors dominate brake-by-wire and steer-by-wire actuators where current loads exceed 50 amps. Michigan OEMs and Texas grid operators concentrate procurement here, though copper price volatility compresses module margins quarterly.
- Fiber Optic Wires:Electromagnetic-interference-immune silica-core pathways transmit sensor-fusion data at sub-millisecond latency for California autonomous vehicle testing corridors. NHTSA functional-safety validation for redundant channels is accelerating adoption fastest here.
- Aluminum Wires:Lightweight conductors serve cost-sensitive power distribution segments where conductivity-per-dollar outweighs efficiency maximization.
- Specialty Wires:Hybrid copper-fiber constructions and shielded coaxial variants address military-aerospace crossover specifications with extended qualification cycles.
Copper wires dominate installed base. Fiber optic wires are where expansion concentrates.
End User:
Automotive programs demand ASIL-D functional safety certification that extends development cycles, while telecommunications refresh infrastructure on compressed capital-deployment schedules.
- Automotive:Drive-by-wire architectures for electric vehicles and autonomous platforms require redundant electromechanical actuators with ISO 26262 validation. Detroit-area suppliers and California testing corridors anchor demand concentration.
- Energy:Grid modernization initiatives in Texas deploy remote actuation and monitoring systems for substation automation, expanding fastest outside automotive verticals.
- Telecommunications:Data center interconnects and 5G fronthaul networks drive high-volume fiber deployment with standardized termination protocols.
- Aerospace:Fly-by-wire heritage systems impose DO-178C software assurance requirements that limit supplier participation to defense-certified manufacturers.
Automotive commands revenue concentration. Energy is climbing the fastest.
Installation Type:
Industrial environments impose the most severe environmental qualification burdens, while residential installations permit commodity-grade sourcing.
- Indoor:Climate-controlled vehicle cabins and server facilities deploy standard-grade insulation with predictable thermal performance envelopes.
- Outdoor:Automotive underhood compartments and utility pole-mounted equipment demand UV-resistant jacketing and moisture-sealed connectors.
- Industrial:Heavy-vibration factory floors and oilfield automation sites require armored conduit and extended temperature-range specifications.
- Residential:Smart home automation and distributed energy resources utilize cost-optimized copper conductors with simplified termination tooling.
Industrial captures premium pricing. Outdoor is gaining share fastest.
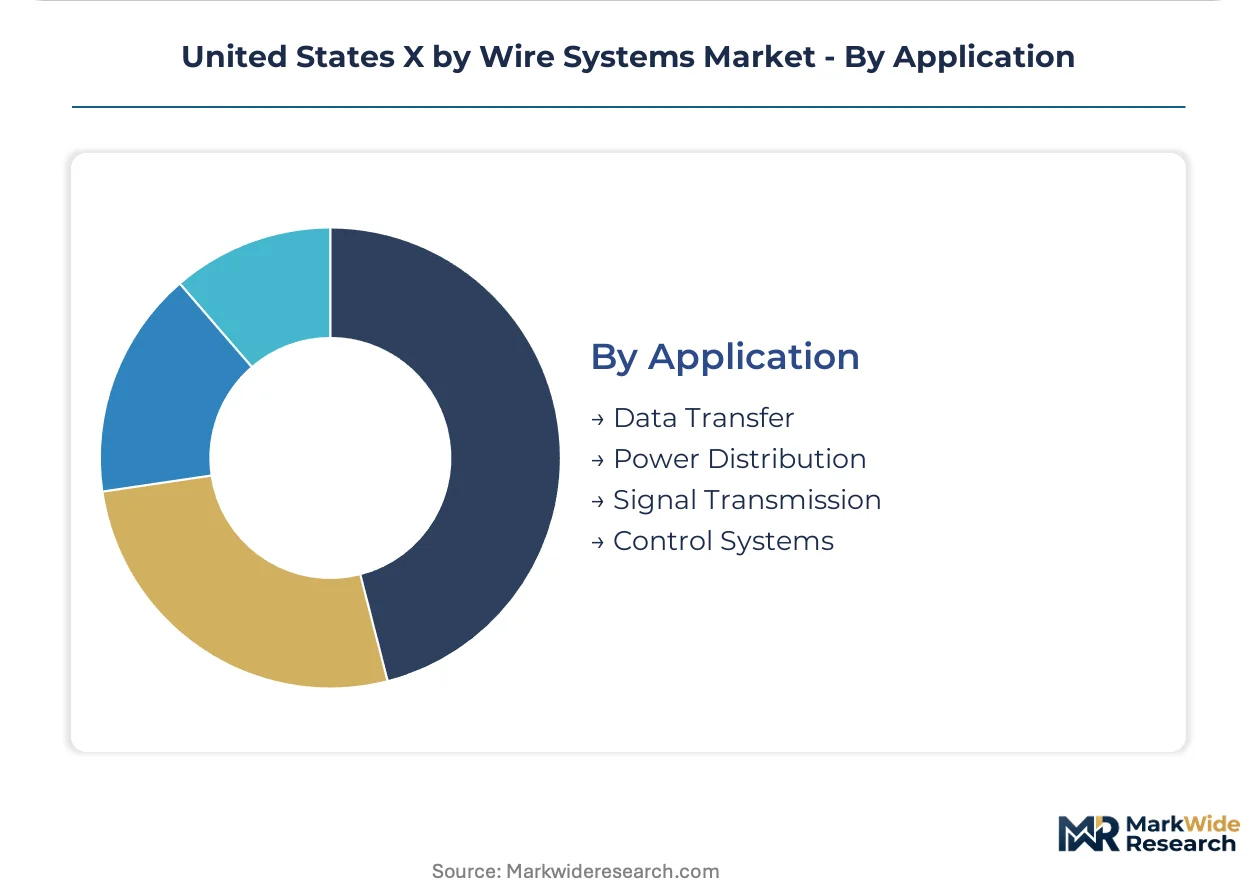
Application:
Power distribution applications refresh on asset-life cycles measured in decades, while data transfer infrastructure upgrades on technology-obsolescence timelines.
- Data Transfer:High-bandwidth fiber optic channels aggregate lidar, radar, and camera feeds in autonomous vehicle sensor fusion architectures. California testing corridors and Michigan OEM development programs concentrate demand.
- Power Distribution:Copper-intensive brake-by-wire and steer-by-wire actuators draw sustained current loads that dominate wire-mass allocation in electric vehicle platforms.
- Signal Transmission:Low-voltage control buses for HVAC and lighting systems utilize mixed-gauge harness constructions with standardized connector footprints.
- Control Systems:Real-time electromechanical actuator commands require deterministic latency guarantees that favor fiber optic redundancy in safety-critical loops.
Power distribution anchors volume. Data transfer is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA functional-safety mandates anchor demand concentration in Michigan and California, while Texas grid modernization and Ohio automotive clusters expand procurement footprints across distinct regulatory and industrial zones.
Michigan
Detroit-area suppliers expand electromechanical actuator capacity for steer-by-wire and brake-by-wire architectures. NHTSA updated vehicle safety standards accelerate compliance-driven retrofits across OEM programs. Warren and Auburn Hills anchor supplier engineering concentration for next-generation wire-system modules.
California
Autonomous vehicle testing corridors concentrate latency-sensitive fiber optic demand for electromagnetic-interference immunity. State-level zero-emission vehicle rules expand electric vehicle platforms that rely on electronic control architectures. Silicon Valley and Los Angeles Basin host sensor fusion development programs pulling wire-system procurement.
Texas
Energy sector applications in grid modernization deploy remote actuation and monitoring systems for substation automation. FERC reliability standards shape utility procurement specifications for industrial-grade wire harnesses. Houston and Dallas-Fort Worth anchor energy utility headquarters driving consolidated supplier relationships.
Ohio
Automotive OEMs accelerate procurement of brake-by-wire architectures to lock in electromechanical capacity ahead of NHTSA compliance deadlines. State manufacturing incentives support supplier facility expansion for domestic module assembly. Cleveland and Columbus corridors concentrate Tier 1 supplier engineering operations.
United States X by Wire Systems Market Competitive Landscape
Capability concentration sits with electromechanical actuator specialists; scale advantage sits with integrated vehicle-control architects. The market structures around three tiers: heritage steering-system suppliers, in-house OEM development arms, and diversified braking-electronics conglomerates. Dominant competitive moves include strategic partnerships for mixed-material harness integration and capacity expansion in Michigan and Ohio to preempt NHTSA certification bottlenecks.
Among heritage-tier steering specialists, Nexteer Automotive and ZF Friedrichshafen AG occupy positions anchored to Detroit-area engineering legacies. Tesla Inc. exemplifies the integrated-architecture archetype through captive wire-system development. Robert Bosch GmbH represents the diversified-electronics conglomerate model sustaining R&D intensity across braking and steering programs for US OEMs.
| Leading Market Players |
|---|
| Nexteer Automotive |
| ZF Friedrichshafen AG |
| Infineon Technologies |
| Orscheln Products LLC |
| General Motors |
| Tesla Inc. |
| Torc Robotics |
| Lokar Performance Products |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
Copper conductor supply from Chilean and Peruvian mining operations concentrates pricing power with wire-harness assemblers serving Michigan OEM programs, while fiber optic silica sourcing from Corning and Prysmian facilities anchors premium tier margins for California autonomous vehicle corridors.
Pricing Analysis
Michigan-to-California price spreads of 15-20% reflect freight differentials and NHTSA certification premiums for ASIL-D validated modules. Three-tier pricing structure across premium, standard, and economy levels separates fiber optic redundancy channels from commodity copper brake actuators and aluminum power distribution. Cost compression in copper-intensive segments is intensifying because LME price volatility feeds directly into module quotations. Fleet procurement departments exhibit highest price sensitivity, while autonomous vehicle developers prioritize latency performance over unit economics.
Supply Chain Analysis
Extended payment terms from Detroit-area OEMs now stretch to 90-120 days, forcing Tier 2 wire suppliers into supply-chain finance facilities backed by automotive-focused lenders. Manufacturing concentrates in Mexico, China, and South Korea for electromechanical actuators, while fiber optic draw towers cluster in USA, Japan, and Germany. Raw material dependencies span copper cathodes, silica preforms, and rare-earth magnet alloys for motor integration. Single-source vulnerability sits with Corning's specialty fiber capacity for automotive-grade electromagnetic immunity. Distribution runs through consolidated Tier 1 integrators rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around full-system integrators capable of delivering combined steering, braking, and powertrain modules, displacing component-level sourcing relationships that fragmented procurement leverage across the supplier base.
For Market Incumbents: Harden certification moats by accelerating ASIL-D validation for steer-by-wire modules ahead of NHTSA's pending redundancy rulemakings. Lock in electromechanical actuator capacity through backward integration into copper wire drawing or fiber optic preform manufacturing. Tesla's captive wire-system development and Bosch's diversified braking electronics represent the consolidation threat; vertical integration into mixed-material harness production is the priority lever to defend margin position. For New Entrants and Emerging Players: Build out specialty wire capabilities for Texas grid modernization substations, where FERC reliability standards create procurement barriers lower than automotive ASIL-D thresholds. Target energy sector remote actuation as the most penetrable vertical, with industrial-grade armored harnesses for oilfield automation as the entry wedge. A go-to-market angle through utility engineering consultants bypasses consolidated automotive supplier relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics platforms that aggregated brake-by-wire specialists during the last decade. Long-term viability hinges on exposure to software-defined vehicle architectures rather than discrete component replacement cycles. Watch NHTSA automated driving system redundancy finalization as the signal for certification-bottleneck valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Mixed-Material Harness Integration | Combines copper power conductors with fiber optic data pathways for NHTSA-compliant redundancy. |
| ASIL-D Certification Investment | Accelerates supplier qualification for steer-by-wire and brake-by-wire OEM programs. |
| Domestic Manufacturing Footprint | Captures IRA production tax credits for reshoring wire-system module assembly. |
| Energy Sector Vertical Expansion | Diversifies revenue beyond automotive into Texas grid modernization substation automation. |
| Software-Defined Vehicle Partnership | Enables over-the-air functionality extension without physical hardware redesign cycles. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement patterns anchors the qualitative findings. Primary interviews with Detroit-area electromechanical actuator specialists, California autonomous vehicle sensor fusion engineers, Texas utility substation automation managers, and NHTSA regulatory affairs consultants informed demand-side validation. Secondary sources include NHTSA rulemaking dockets, FERC reliability standards filings, vehicle production databases, and copper trade flow customs records. Bottom-up segment sizing triangulates against top-down OEM platform penetration assumptions.
Calibration against historical ASIL-D certification timelines and copper price elasticity studies shapes the projection framework. Segmentation models disaggregate by material type, end-use vertical, installation environment, and application function across the analysis window. CAGRs derive from regression analysis of OEM procurement commitments and energy utility capital deployment schedules. Industry-specific inputs include NHTSA automated driving system redundancy rulemaking progression and IRA domestic content credit qualification thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by silicon photonics entrants or battery-electric platform disruptors would shift outcomes. Macroeconomic copper price spikes, accelerated NHTSA compliance deadlines, or breakthroughs in wireless actuation redundancy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Solid State Relay Market
Switches
Power Load Switches Market
Switches
Vibration Level Switch Market
Switches
Micro Switch Market
Switches
India Switchgear Market
Switches
Proximity Switches Market
Switches
Fixed Switch Cabinet Market
Switches
UK Reed Sensors Switches Market
Switches
Asia Pacific Transfer Switches Market
Switches
Disconnect Switch Market
Switches
DC Switchgear Market
Switches
Drive Mode Selector Switch and Controller Systems Market
Switches
Australia and New Zealand Medium Voltage Switchgear Market
Switches
5G Electromechanical RF Switch Market
Switches
5G Solid State Switches Market