

Outdoor Boundary Vacuum Load Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Boundary Vacuum Load Switch Market Insights
Aftermarket service revenue is reshaping margin pools across the Outdoor Boundary Vacuum Load Switch industry, pulling value from hardware sales toward lifecycle maintenance contracts. ABB leverages its installed base in European substations to capture recurring retrofit demand. Siemens anchors its position through captive vacuum interrupter production. Schneider Electric differentiates via digital monitoring integration across its switch portfolios.
An outdoor boundary vacuum load switch is a medium-voltage switching device that uses vacuum as the dielectric medium to interrupt load currents, typically rated between 12 kV and 36 kV with short-circuit making capacity up to 50 kA. Its primary purpose is to provide safe isolation and operational switching in overhead distribution networks and ring-main units. Triple-pole configurations dominate utility procurement due to three-phase distribution prevalence, while vacuum interruption technology leads on reliability metrics and maintenance intervals. Electronic control modules represent the fastest-expanding technology segment as grid operators demand remote operability and fault diagnostics.
IEC 62271-103 governs switch testing protocols across European markets, while China's GB standards mandate vacuum interrupter endurance cycles for state grid tenders. India's CEA technical standards prescribe insulation coordination requirements for 33 kV boundary installations. Stakeholders must weigh regional certification burdens against the volume premiums available in national utility procurement frameworks.
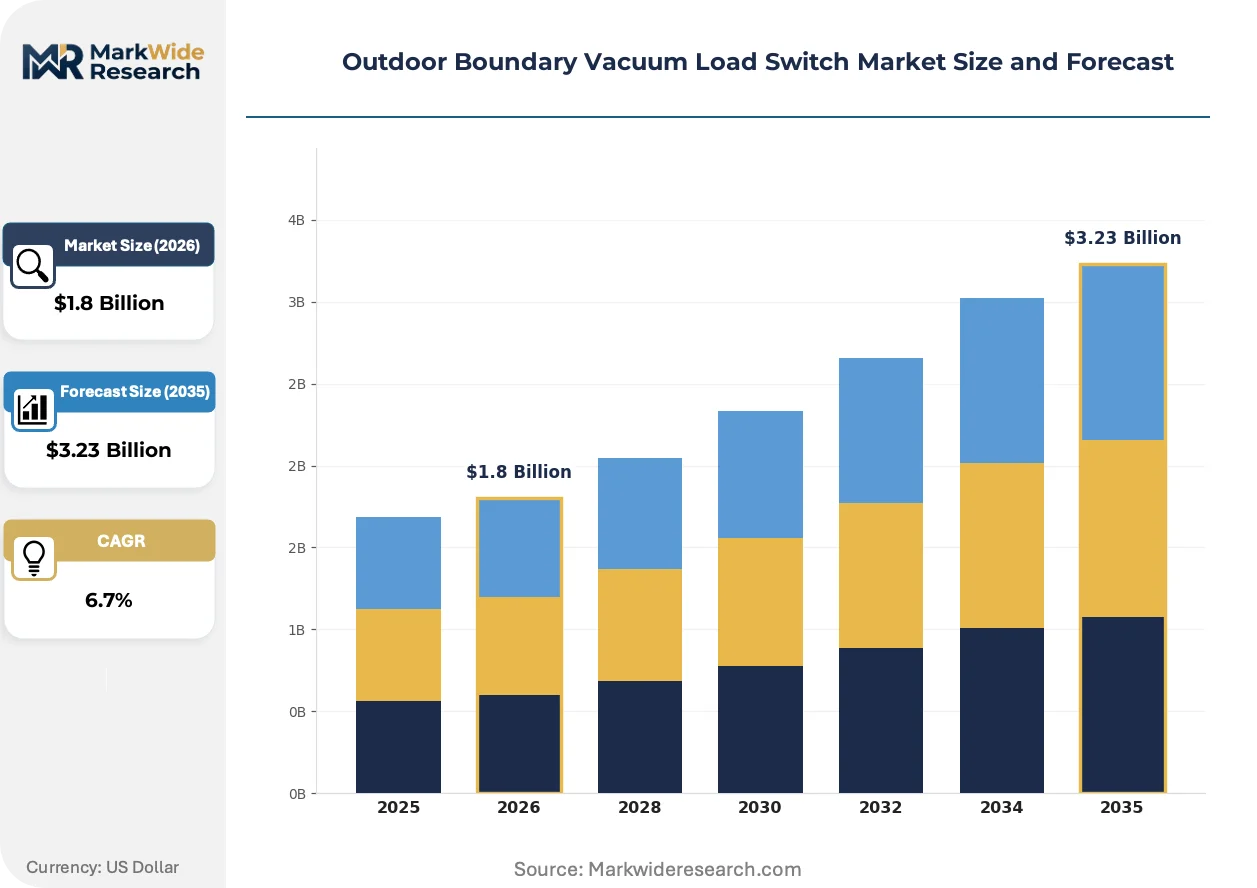
Market Dynamics
Utility procurement of outdoor boundary vacuum load switches is pivoting from price-per-unit metrics toward lifecycle cost frameworks. Grid operators now weight 20-year maintenance intervals and remote diagnostic capability as heavily as initial capital outlay.
Growth Catalysts
- IEC 62271-103 arc-quenching mandates:European utilities are replacing oil-immersed switches with vacuum interruption technology to meet tightened fault-current performance thresholds.
- India's rural electrification programs:State distribution companies are procuring 33 kV boundary switches for overhead line extensions into unserved agricultural zones.
- Electronic control modules:Embedded sensor arrays and motorized operators are enabling SCADA integration that manual switches cannot support.
Market Restraints
- Copper and ceramic price volatility:Vacuum interrupter production depends on oxygen-free copper contacts and alumina insulators subject to commodity swings.
- Captive vacuum interrupter supply:Three European and two Japanese manufacturers control the majority of high-reliability interrupter production.
- Sulfur hexafluoride substitution limitations:SF6 gas-insulated alternatives retain cost advantages in 36 kV+ applications where vacuum bottle sizing becomes prohibitive.
Strategic Opportunities
- Philippines grid resilience investments:Typhoon-hardened distribution networks are specifying vacuum load switches for salt-spray corrosion resistance.
- EU Green Deal circularity requirements:End-of-life take-back mandates favor vacuum technology over oil-filled units with hazardous fluid disposal obligations.
- Digital twin convergence:Integration of switch telemetry with asset management platforms creates recurring software revenue streams alongside hardware sales.
Industry Challenges
- Vacuum interrupter sealing expertise:Hermetic brazing and getter activation require specialized technicians in short supply outside East Asian manufacturing clusters.
- Legacy electromechanical retrofit compatibility:New electronic control modules must interface with decades-old substation wiring standards without full infrastructure replacement.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Boundary Vacuum Load Switch Market Trends and Innovations
Product development in outdoor boundary vacuum load switches is converging on three vectors: solid-state sensing replacing mechanical indicators, predictive algorithms substituting scheduled maintenance, and modular architectures enabling field-upgradable capability.
Solid-state current and voltage sensors embedded directly within switch housings are rendering obsolete separate instrument transformer installations. European ring-main unit manufacturers are adopting these integrated packages to reduce footprint and wiring complexity. The elimination of magnetic cores and secondary wiring is compressing total installed cost structures while expanding diagnostic data streams available to distribution management systems.
China's GB standards for vacuum interrupter endurance cycles are tightening procurement specifications for state grid tenders. Manufacturers must now demonstrate 10,000 electrical operation cycles under standardized fault conditions to qualify for high-volume framework agreements. Domestic suppliers are responding with accelerated wear-testing protocols and ceramic metallurgy improvements to secure placement in annual centralized procurement batches.
Lifecycle service contracts are displacing transactional hardware sales in Nordic utility markets. Danish and Swedish distribution operators now procure switch functionality on availability-based terms, transferring operational risk to manufacturers. This restructuring concentrates vendor relationships around firms with captive service networks and remote monitoring infrastructure rather than pure equipment specialists.
Outdoor Boundary Vacuum Load Switch Market Segmentation
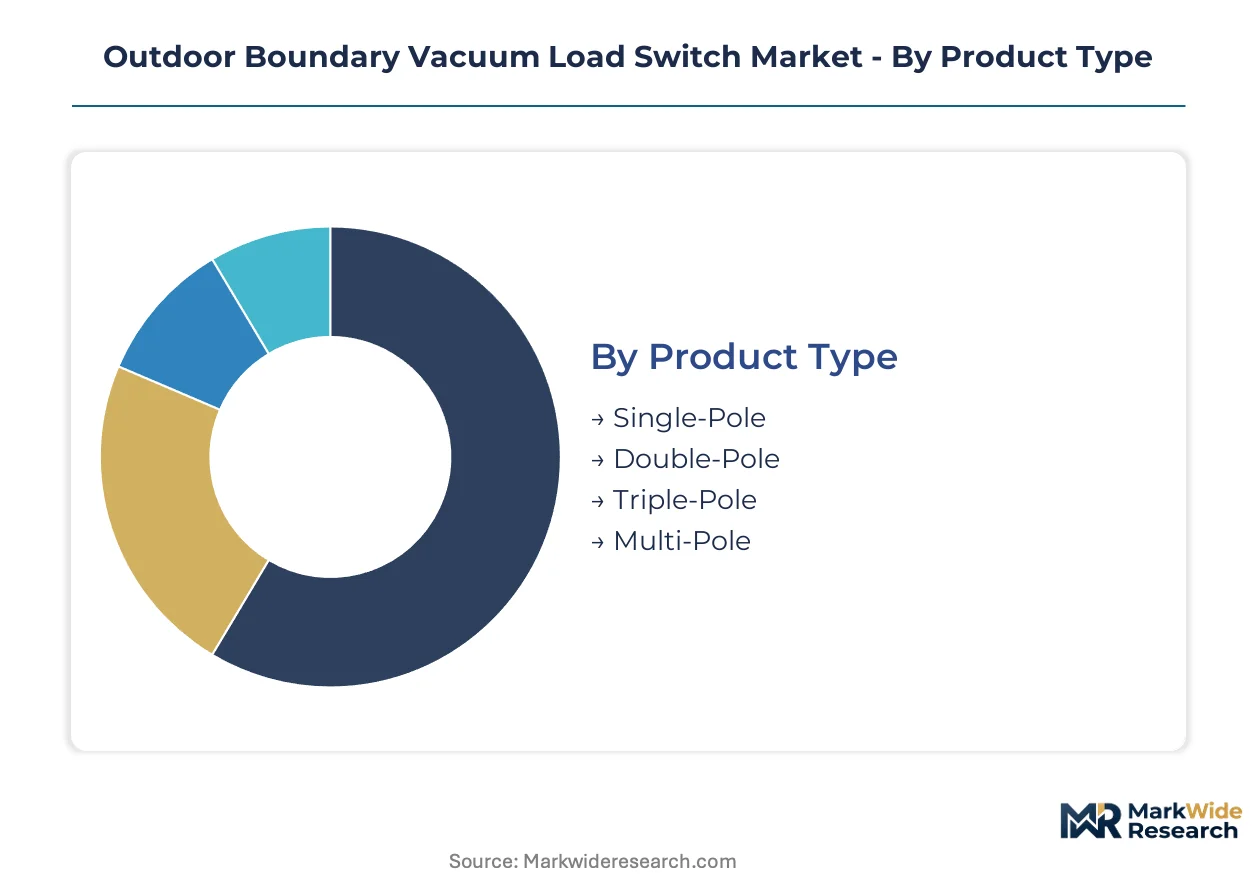
Segmentation in outdoor boundary vacuum load switches reveals distinct procurement patterns across pole configurations, actuation technologies, and end-user sophistication levels. Understanding these divisions exposes where margin pools concentrate and which technical specifications drive competitive differentiation in medium-voltage distribution networks.
Product Type:
Mature utility specifications dominate pole configuration selection, with electrification density and phase requirements dictating procurement volumes across distribution architectures.
- Single-Pole:Designed for single-phase lateral taps and spur line extensions in rural distribution networks. India's state distribution companies specify these for agricultural feeder isolation where three-phase infrastructure remains uneconomical.
- Double-Pole:Supports two-phase distribution segments or phase-splitting configurations in legacy European networks. German municipal utilities deploy double-pole switches for urban ring-main unit retrofits where space constraints preclude triple-pole alternatives.
- Triple-Pole:The standard configuration for three-phase overhead distribution and substation feeder control. China's State Grid centralized procurement channels specify triple-pole vacuum load switches for 95% of 12-36 kV framework agreements, reflecting three-phase distribution prevalence across East Asian grids.
- Multi-Pole:Custom-configured arrays exceeding three poles for specialized industrial substations and complex busbar arrangements. Mining operations in Australia's Pilbara region specify four-pole configurations for neutral switching in ungrounded delta systems.
Triple-Pole retains volume leadership; Multi-Pole holds the steepest expansion curve as industrial electrification demands custom switching topologies.
Technology:
Actuation and interruption mechanisms stratify across cost tiers, with electronic sophistication determining remote operability and maintenance interval economics.
- Vacuum Interruption:Hermetically sealed vacuum bottles extinguish arcs through metal vapor condensation on contact surfaces. IEC 62271-103 mandates this technology for new European installations, displacing oil-immersed alternatives in Scandinavian utility frameworks.
- Magnetic Actuation:Electromagnetic operators provide rapid closing and opening cycles without mechanical linkages. Japanese utilities specify magnetic actuation for coastal substations where corrosion resistance outweighs initial cost premiums.
- Thermal Release:Bimetallic overload protection integrated into switch mechanisms for standalone fault clearing. Brazilian distribution concessionaires deploy thermal-release switches in remote Amazonian networks lacking SCADA backhaul.
- Electronic Control:Microprocessor-based modules enable motorized operation, fault recording, and communication protocol integration. Electronic control is climbing the fastest as grid operators mandate remote switching capability for distributed energy resource integration.
Vacuum Interruption anchors installed base economics; Electronic Control commands the steepest expansion trajectory through digitalization mandates.
Application:
Functional deployment contexts segment procurement specifications, with fault-current duty and switching frequency determining interrupter sizing and contact metallurgy.
- Power Distribution:Routine load-breaking and sectionalizing in overhead line networks. South African municipalities prioritize power distribution switches for informal settlement electrification programs requiring frequent reconfiguration.
- Substation Control:Feeder isolation and busbar coupling in outdoor switchyards. Substation control applications concentrate in Germany's Energiewende infrastructure, where renewable integration demands higher switching cycles.
- Load Management:Peak shaving and demand response switching for industrial tariff optimization. Load management deployment is gaining share fastest as time-of-use pricing spreads through Southeast Asian manufacturing zones.
- Fault Protection:Coordinated protection schemes with upstream reclosers and downstream fuses. Fault protection specifications tighten in the Philippines as typhoon-hardening standards mandate 50 kA short-circuit withstand.
Power Distribution sustains volume dominance; Load Management exhibits the most rapid ascent through demand-side flexibility programs.
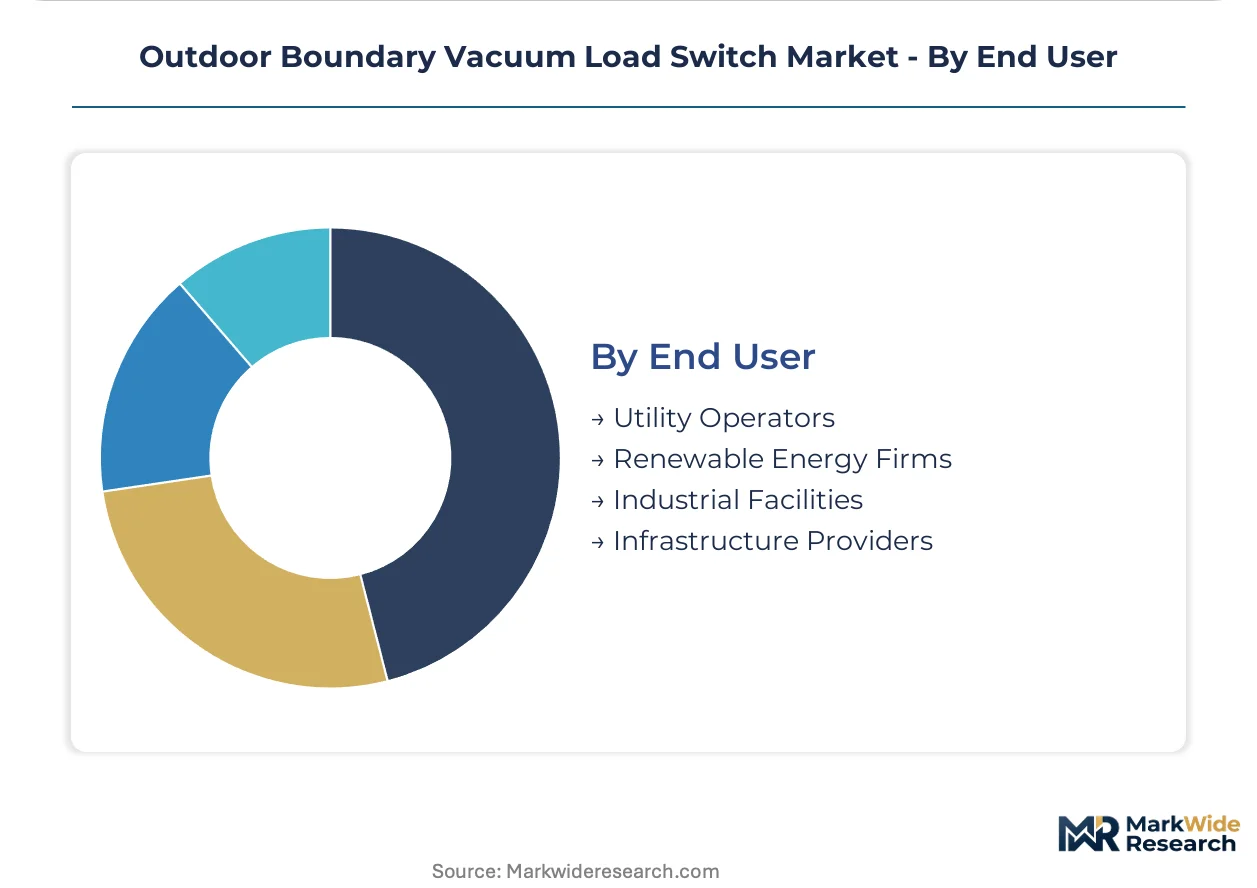
End User:
Customer sophistication and procurement scale create divergent specification requirements, from standardized utility frameworks to customized industrial performance guarantees.
- Utility Operators:State and municipal distribution companies procuring through centralized tenders with lifecycle cost evaluation criteria. Utility operators in Denmark now contract switch availability rather than unit purchase, transferring operational risk to manufacturers.
- Renewable Energy Firms:Solar and wind developers requiring switching compatibility with inverter-based generation and variable power flows. Renewable energy procurement concentrates in Spain's solar parks, where vacuum load switches manage reverse power conditions.
- Industrial Facilities:Mining, petrochemical, and manufacturing sites specifying switches for captive substations and process-critical reliability. Industrial facilities in Saudi Arabia's mining belt specify dust-ingress protection exceeding standard IP ratings.
- Infrastructure Providers:Railway, airport, and port authorities procuring for electrification networks with specialized voltage and frequency requirements. Infrastructure providers are expanding fastest as high-speed rail electrification accelerates across Turkey's Anatolian corridor.
Utility Operators maintain procurement volume leadership; Infrastructure Providers demonstrate the steepest demand expansion through transportation electrification investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vacuum interrupter sealing expertise concentrates in East Asian manufacturing clusters, while procurement frameworks in Europe and South Asia are tightening certification requirements. Distribution network investments now favor lifecycle service contracts over transactional hardware sales.
China
State Grid Corporation's centralized procurement channels drive triple-pole vacuum load switch volumes for 12-36 kV framework agreements. GB standards mandate 10,000 electrical operation cycles for vacuum interrupter endurance qualification. Yangtze River Delta manufacturers dominate ceramic metallurgy improvements for annual tender batches.
Germany
Municipal utilities deploy double-pole configurations for urban ring-main unit retrofits constrained by space limitations. Energiewende infrastructure mandates higher switching cycles for renewable integration at substation control points. Bavarian distribution operators now contract switch availability rather than unit purchase, transferring operational risk.
India
State distribution companies procure 33 kV boundary switches for overhead line extensions into agricultural zones under rural electrification programs. CEA technical standards prescribe insulation coordination requirements for boundary installations. Gujarat and Maharashtra utilities concentrate procurement for feeder isolation in single-phase lateral taps.
United States
FERC grid modernization incentives accelerate vacuum interruption adoption for arc-quenching performance in utility distribution networks. California and Texas utilities prioritize electronic control modules for SCADA integration with distributed energy resources. Pacific Northwest substation operators specify vacuum technology for 20-year maintenance interval economics.
Japan
Magnetic actuation specifications dominate coastal substation procurement where corrosion resistance outweighs initial cost premiums. METI efficiency standards drive retrofit demand from oil-immersed legacy switches. Kansai region utilities concentrate lifecycle service contract negotiations with captive interrupter suppliers.
Outdoor Boundary Vacuum Load Switch Market Competitive Landscape
Integrated electrical conglomerates and specialized switchgear fabricators split the market based on captive component production versus modular assembly flexibility. The vendor base stratifies across three tiers: multinational platforms with vacuum interrupter foundries, regional specialists with licensed interruption technology, and local assemblers serving price-sensitive tenders. Dominant competitive moves include backward integration into ceramic contact metallurgy and geographic expansion through framework agreement positioning in state utility channels.
Among European-based integrated platforms, ABB, Siemens, and Schneider Electric exemplify the captive-production archetype. ABB leverages installed base positioning in Scandinavian substations for recurring retrofit demand. Siemens anchors its market presence through in-house vacuum interrupter manufacturing. Schneider Electric occupies a position emphasizing digital monitoring integration across switch portfolios. These three conglomerates represent the premium-tier competitive vector where lifecycle service contracts and remote diagnostic capability determine vendor selection.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Eaton |
| Fuji Electric |
| Legrand |
| SOCOMEC |
| Ensto |
| Lucy Group |
| Others |
Pricing and Supply Chain Analysis
Commodity volatility in oxygen-free copper and alumina ceramics determines both pricing tier spreads and supply chain shape across vacuum interrupter production. Manufacturers absorbing input cost swings through long-term offtake contracts command premium positioning, while spot-market dependent assemblers compete on transactional economics in price-sensitive tenders.
Pricing Analysis
IEC 62271-103 dictates the pricing tier structure through certification-grade differentiation. Three-tier pricing stratifies across premium, standard, and economy levels based on vacuum interrupter endurance cycle ratings and electronic control module integration. Cost compression in the economy tier is intensifying because Chinese state grid tenders prioritize unit economics over lifecycle service bundling. Municipal utilities in Northern Europe exhibit lowest price sensitivity, procuring availability-based contracts that transfer operational risk to manufacturers.
Supply Chain Analysis
Export-control regimes on advanced ceramic metallurgy equipment limit technology transfer to emerging manufacturing clusters. Vacuum interrupter production draws from specialized brazing expertise concentrated in Japan, Germany, and China's Yangtze River Delta. Raw material dependencies center on oxygen-free copper contacts, alumina insulators, and getter materials for hermetic sealing. Single-source vulnerability runs through Japanese suppliers of high-purity getter alloys. Distribution runs through state utility framework agreements in China and India, with European channels favoring direct manufacturer relationships for lifecycle contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid modernization cycles are driving capital deployment recovery, with utility procurement budgets expanding after deferred maintenance periods. State-mandated electrification programs across South Asia provide demand visibility through multi-year framework commitments.
For Market Incumbents: Entrench through captive vacuum interrupter production and regional service network density. Secure placement in China's annual centralized procurement batches by demonstrating 10,000-cycle endurance qualification under GB standards. Deepen backward integration into ceramic contact metallurgy to offset copper price volatility and defend margin position against modular assemblers.
For New Entrants and Emerging Players: Build out electronic control module capabilities to capture fastest-expanding technology segment demand. Target India's rural electrification programs for 33 kV boundary switch procurement, where state distribution companies prioritize cost efficiency over established brand preference. Pursue licensing arrangements with Japanese magnetic actuation specialists to differentiate in coastal corrosion-resistant specifications.
For Investors and Strategic Acquirers: The market sits at a capital-investment phase that favors vertically integrated manufacturers with captive interrupter foundries. Long-term viability rests on lifecycle service contract penetration in Nordic utility markets. Acquisition targets should demonstrate remote monitoring infrastructure and SCADA integration capabilities. The signal to watch is framework agreement positioning in China's State Grid centralized procurement channels as market share inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Metallurgy Backward Integration | Captive supply of alumina insulators insulates margins from commodity volatility in Chinese tender markets. |
| Electronic Control Module Development | Microprocessor-based platforms enable SCADA integration required by California and Texas grid operators. |
| Lifecycle Service Contract Expansion | Availability-based terms with Danish utilities create recurring revenue streams displacing transactional hardware sales. |
| Philippines Grid Resilience Positioning | Typhoon-hardened specifications for salt-spray corrosion resistance open premium procurement channels. |
| EU Green Deal Circularity Compliance | End-of-life take-back mandates favor vacuum technology over oil-filled units with hazardous fluid disposal obligations. |
Research Methodology
Operator-level perspectives from utility planning officers, substation maintenance directors, vacuum interrupter manufacturing engineers, and state procurement managers anchored the qualitative base. Primary interview findings combined with secondary validation from IEC 62271-103 testing protocols, GB standards documentation, CEA technical standards, and state grid tender announcements. Bottom-up demand modeling triangulated against top-down grid investment forecasts across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include pole configuration, actuation technology, application function, and end-user sophistication tier. CAGRs derived from regression analysis of historical procurement volumes against grid modernization spending patterns. Industry-specific forecast inputs incorporated vacuum interrupter endurance cycle requirements and electronic control module adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic suppliers would shift outcomes. Material shifts in copper and ceramic commodity pricing, IEC arc-quenching mandate enforcement timing, or state utility procurement centralization reforms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.