
 Global Switchgear Market | 2026-2036
Global Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Switchgear Market Outlook
Utility procurement consolidation among European transmission system operators is repositioning contract structures toward long-term service agreements. Siemens AG leverages its digital switchgear portfolio to anchor high-margin aftermarket revenue streams. Schneider Electric competes through integrated energy management software layered across its medium-voltage hardware. ABB Ltd. dominates the gas-insulated segment with proprietary SF6-free alternatives.
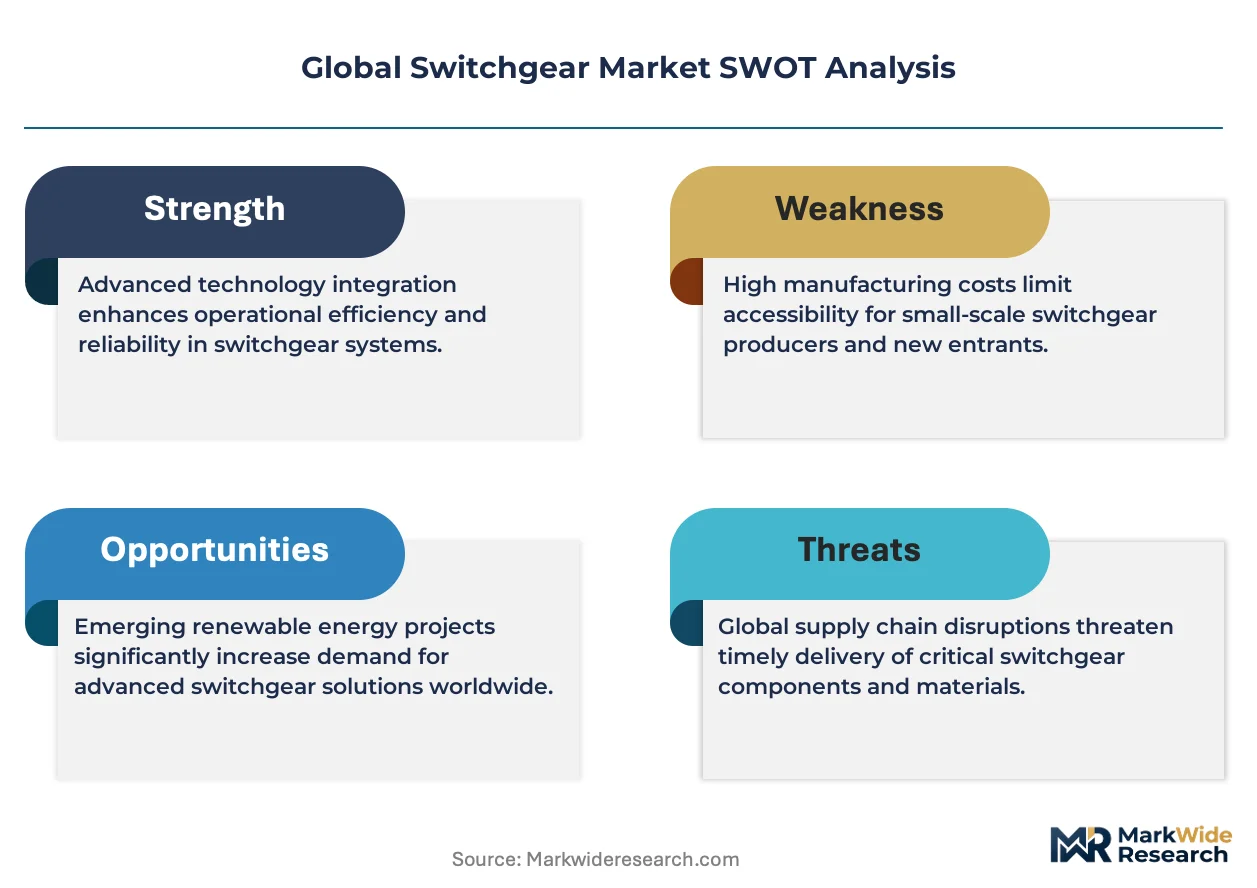
Switchgear encompasses electrical apparatus designed to control, protect, and isolate power circuits, typically operating at voltages from low-voltage residential levels to ultra-high-voltage transmission ratings exceeding 800 kV, with insulating media including air, vacuum, sulfur hexafluoride, or solid dielectrics. Its primary purpose is ensuring grid reliability by interrupting fault currents and enabling safe maintenance of downstream equipment. Circuit breakers command the largest product-type revenue pool due to their critical protection function and higher unit complexity. Vacuum switchgear is displacing legacy SF6 designs in medium-voltage applications as environmental regulations tighten. The utilities end-user segment sustains the deepest replacement cycle demand, though industrial captive power installations are expanding faster in absolute unit terms.
The EU F-Gas Regulation, EPA greenhouse gas reporting requirements, and IEC 62271-200 standards collectively mandate reduced SF6 emissions and enhanced arc-fault containment specifications. These frameworks compel manufacturers to redesign insulation systems and certify alternative gas mixtures for grid-equivalent performance. India's Central Electricity Authority and China's MEE are imposing parallel localization and environmental compliance conditions on switchgear imports. Stakeholders must monitor regulatory divergence between European phase-out timelines and emerging-market enforcement capacity to calibrate product platform investments.
Market Dynamics
SF6 phase-out mandates are compressing product development cycles while vacuum and fluoronitrile alternatives capture medium-voltage share, forcing manufacturers to rebuild insulation platforms around environmental compliance rather than incremental performance gains.
Growth Catalysts
- EU F-Gas Regulation:Binding emission reduction targets for sulfur hexafluoride are accelerating replacement demand across German and French transmission networks, pulling forward upgrade timelines by several years.
- Data center buildouts:Hyperscale operators in Virginia, Singapore, and Ireland are procuring medium-voltage switchgear at 38-72 kV ratings to support 100+ MW campus power requirements.
- India's renewable integration:CEA-mandated grid code compliance for solar and wind farms is driving procurement of gas-insulated switchgear with compact footprints for substation land constraints.
Market Restraints
- Copper and rare earth volatility:Contact material costs swing with commodity markets, compressing margins on fixed-price utility contracts signed 18-24 months ahead of delivery.
- SF6 inventory stranding:European utilities face write-down risks on installed gas-insulated equipment as phase-out timelines accelerate, creating balance-sheet pressure that delays discretionary replacement programs.
- Technical limitation of air insulation:Dielectric performance constraints at voltages above 145 kV prevent air-insulated switchgear from displacing gas-filled alternatives in high-voltage transmission applications.
Strategic Opportunities
- Southeast Asia grid expansion:Vietnam and Indonesia are tendering transmission infrastructure with localization requirements that favor joint-venture manufacturing over pure import.
- Digital twin integration:Convergence of switchgear hardware with asset performance management software creates recurring revenue streams through predictive maintenance subscriptions.
- US IRA manufacturing incentives:Domestic content bonuses for electrical infrastructure are prompting greenfield assembly investments to serve North American utility procurement.
Industry Challenges
- Arc interruption physics expertise:Vacuum interrupter design requires specialized plasma physics and material science talent that concentrates in legacy industrial regions of Germany and Japan.
- Type certification timelines:IEC 62271-200 and IEEE C37 series testing protocols extend 12-18 months for new insulation gas formulations, delaying product launches behind regulatory deadlines.
- Legacy protocol integration:IEC 61850 communication retrofitting of installed switchgear fleets demands interoperability engineering that strains OEM service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Switchgear Market |
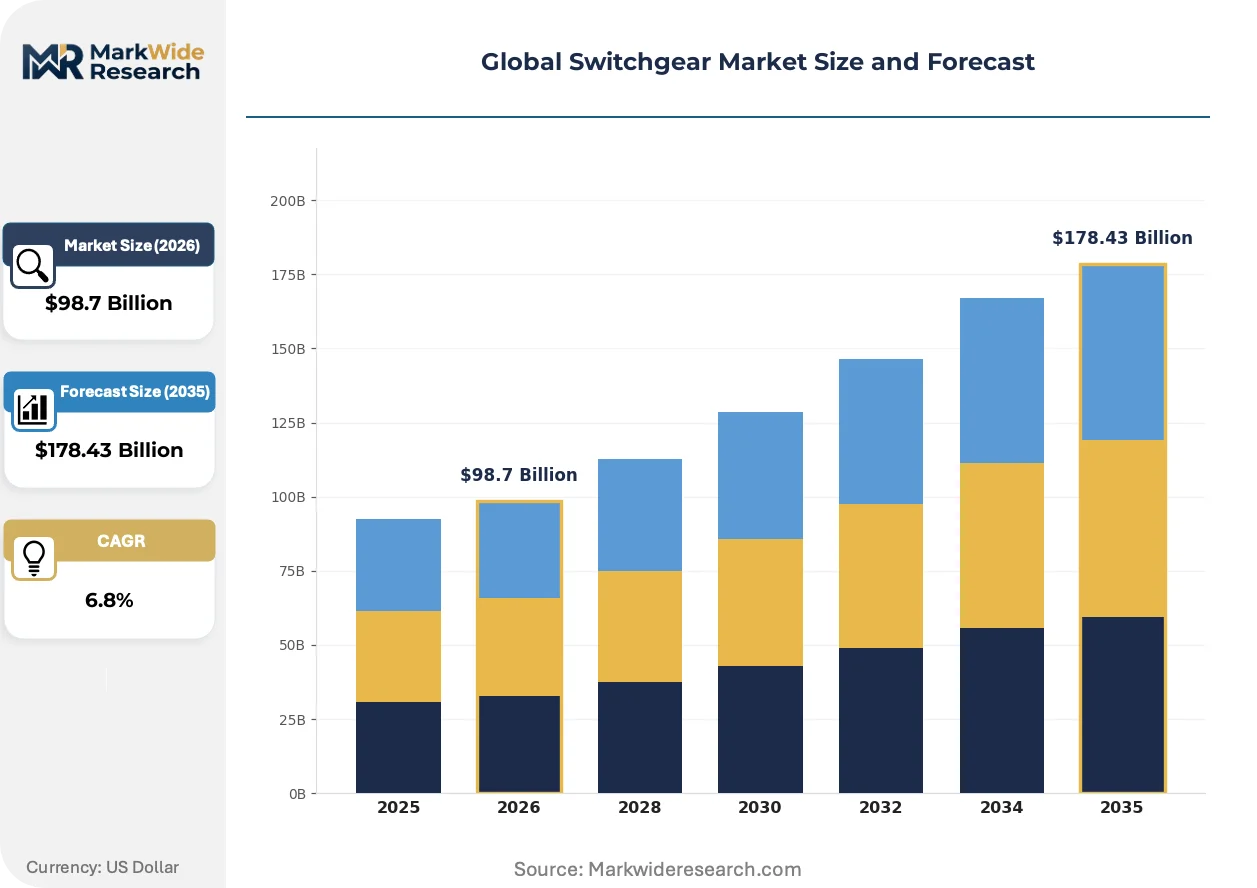
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Switch Fuses, Disconnectors, Panel Boards Technology: Gas Insulated Switchgear, Air Insulated Switchgear, Hybrid Switchgear, Vacuum Switchgear End User: Utilities, Industrial, Commercial, Residential Installation: Indoor, Outdoor, Mobile, Modular |
| Companies Covered | ABB Ltd., Schneider Electric, Siemens AG, Eaton Corporation, General Electric, Hitachi Ltd., Mitsubishi Electric Corporation, Toshiba Corporation, Fuji Electric Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Switchgear Market Strategic Shifts
Vacuum interrupter technology is consolidating market position while digitalization layers transform switchgear from passive protection equipment into grid-edge computing nodes with embedded sensing and control capabilities.
Fluorinated gas alternatives are consolidating technical validation efforts as ABB, Siemens, and Schneider Electric converge on fluoronitrile (C4-FN) and fluoroketone (C5-FK) mixtures for medium-voltage applications. European transmission system operators in Germany, Italy, and the Netherlands are piloting these blends at 145 kV ratings, with field data now sufficient to support IEC standardization. The technology is consolidating supplier R&D spending away from incremental SF6 efficiency improvements toward fundamentally new insulation system architectures.
The EU F-Gas Regulation's 2030 phase-down steps are forcing inventory management overhauls across the switchgear supply chain. Manufacturers must now certify leak-tightness to 0.1% annual loss rates and implement cradle-to-grave gas tracking through QR-coded asset registries. Gas-insulated switchgear above 52 kV faces the steepest compliance burden, with French and Spanish utilities already specifying SF6-free alternatives in tender documents.
Long-term service agreements are displacing transactional equipment sales in European and North American utility procurement. Siemens and Schneider Electric now anchor contracts with 15-20 year performance guarantees covering maintenance, digital monitoring, and end-of-life gas recovery. This model concentrates in German and UK distribution networks where regulatory asset base treatment rewards predictable opex over lumpy capex.
Global Switchgear Market Segmentation
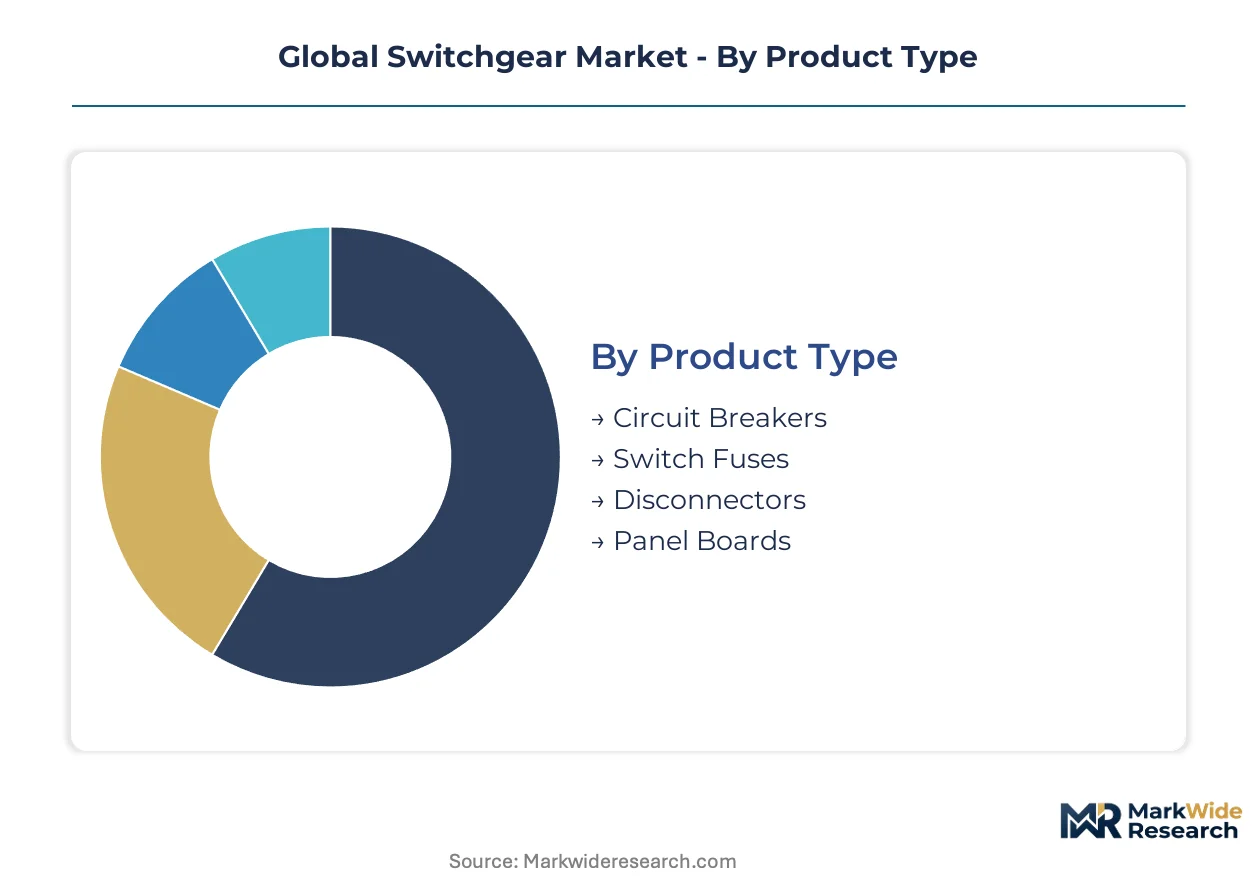
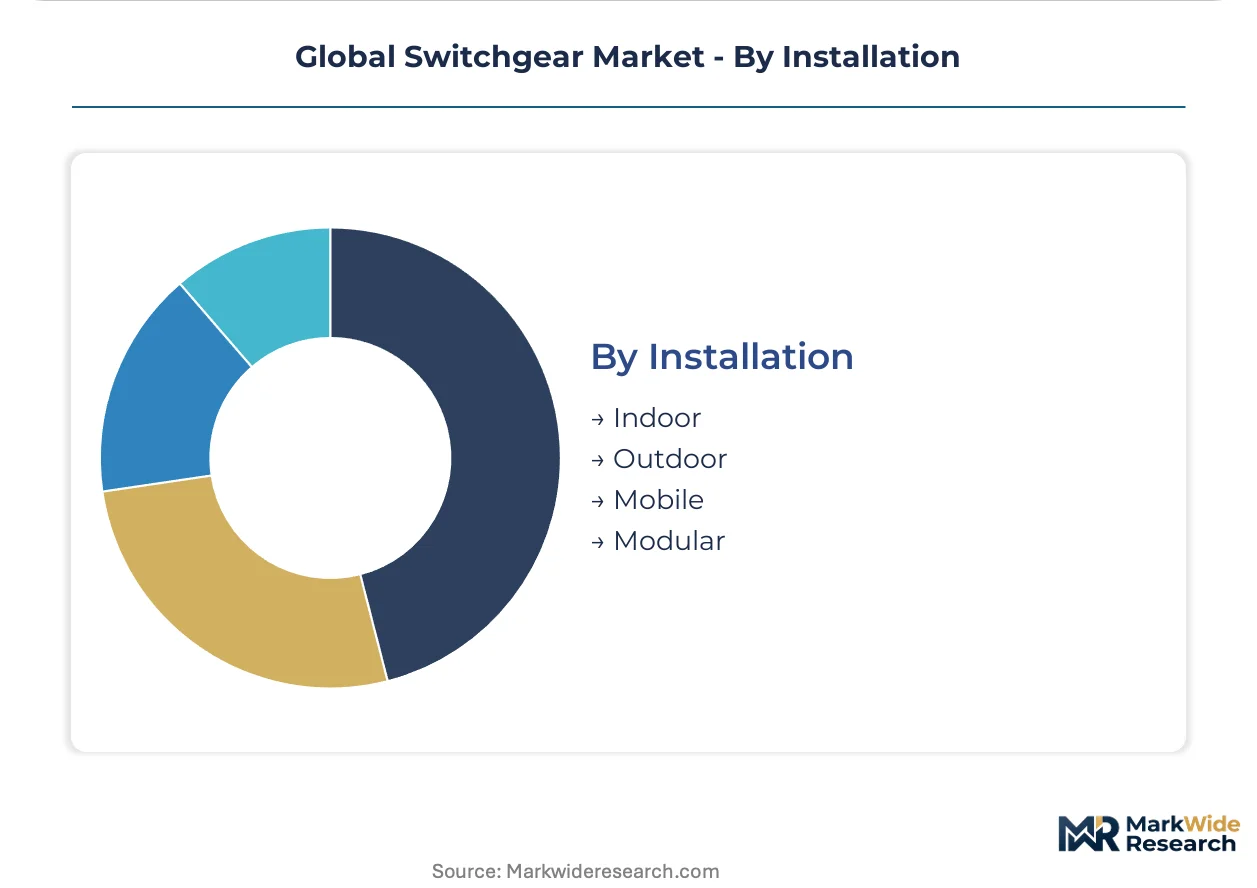
Switchgear segmentation reveals how insulation physics, installation constraints, and end-use reliability requirements fragment manufacturing capabilities across incompatible technical platforms. Suppliers must anchor portfolio decisions to specific voltage-insulation combinations rather than pursuing horizontal coverage.
Product Type:
Supply concentration in circuit breaker manufacturing reflects the specialized arc-interruption engineering and testing infrastructure required for fault-current containment.
- Circuit Breakers:These devices interrupt fault currents through electromagnetic or thermal tripping mechanisms, with vacuum and SF6 technologies dominating medium-voltage ratings. Demand concentrates in German and French transmission networks where EU F-Gas Regulation timelines are accelerating replacement procurement ahead of original depreciation schedules.
- Switch Fuses:Combining isolation and overcurrent protection in compact assemblies, these units serve distribution transformers and motor control centers. Indian renewable integration projects are driving procurement of fuse-switch combinations for solar farm collector substations where land constraints favor integrated protection.
- Disconnectors:Visible isolation points for maintenance safety, specified in air-insulated substation designs.
- Panel Boards:Low-voltage distribution enclosures for commercial and residential final circuits.
Today's leader: Circuit Breakers. Tomorrow's challenger: Switch Fuses.
Technology:
Cost tier stratification separates premium gas-insulated designs from commodity air-insulated alternatives, with hybrid configurations capturing mid-market substation upgrades.
- Gas Insulated Switchgear:SF6 or fluoronitrile-filled enclosures deliver compact footprints and dielectric reliability at voltages above 72 kV. Japanese and German transmission corridors specify these for dense urban substations where land scarcity overrides first-cost premiums.
- Vacuum Switchgear:Ceramic-enclosed vacuum interrupters eliminate atmospheric contamination risks and enable maintenance-free operation over 30-year service lives. US data center operators in Virginia and Texas are standardizing on vacuum technology for 38 kV campus distribution to minimize outage risks in hyperscale facilities.
- Air Insulated Switchgear:Open-bus designs dominate rural substations and developing markets with lower labor costs and abundant land.
- Hybrid Switchgear:Combines gas-insulated busbars with air-insulated circuit breakers for cost-optimized 145 kV applications.
Current volume anchor: Air Insulated Switchgear. Steepest expansion trajectory: Vacuum Switchgear.
End User:
Application-specific duty cycles and reliability thresholds segment procurement specifications across fundamentally different commercial relationships.
- Utilities:Grid operators specify type-tested equipment with 40-year service lives and integrated digital monitoring for transmission and distribution networks. German TSOs are consolidating procurement toward 15-20 year service agreements covering predictive maintenance and end-of-life gas recovery.
- Industrial:Captive power plants and process industries demand arc-resistant enclosures and high short-circuit withstand ratings. Indian steel and cement producers are expanding captive substation investments to manage grid reliability risks amid renewable intermittency.
- Commercial:Office complexes and retail centers prioritize compact indoor switchgear with integrated energy management interfaces.
- Residential:Low-voltage panel boards and miniature circuit breakers serve single-family and multi-unit buildings.
Revenue concentration: Utilities. Margin expansion zone: Industrial.
Installation:
Customer type and deployment urgency dictate preference between permanent infrastructure and reconfigurable power distribution assets.
- Indoor:Enclosed switchgear assemblies protect equipment from environmental contamination in climate-controlled substations and building electrical rooms. Singapore and Ireland data center clusters specify indoor-rated metal-clad switchgear for 72 kV campus interconnection.
- Outdoor:Weatherproof enclosures withstand temperature cycling and precipitation for transmission substations and renewable collector systems. Indian solar farm developers favor outdoor gas-insulated switchgear for 33 kV collector bus applications.
- Mobile:Trailer-mounted substations enable rapid restoration and temporary power for construction and emergency response.
- Modular:Factory-assembled skid packages accelerate deployment for data center and industrial expansions.
Established standard: Indoor. Gaining share fastest: Modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's transmission operators are replacing SF6-insulated equipment faster than India's utilities are installing new gas-insulated switchgear, revealing how regulatory pressure in mature markets outpaces infrastructure buildout in emerging economies.
United States
Data center operators in Virginia and Texas are procuring medium-voltage vacuum switchgear at 38 kV ratings for hyperscale campus distribution. The EPA's greenhouse gas reporting requirements are tightening SF6 inventory tracking for utilities. Northern Virginia's data center corridor is driving concentrated demand for indoor-rated metal-clad assemblies.
Germany
Transmission system operators are consolidating procurement toward 15-20 year service agreements covering predictive maintenance and gas recovery. The EU F-Gas Regulation's 2030 phase-down steps are accelerating replacement timelines ahead of original depreciation schedules. Industrial regions in Bavaria and North Rhine-Westphalia are piloting fluoronitrile blends at 145 kV ratings.
India
Grid modernization and renewable integration projects are intensifying procurement of gas-insulated switchgear with compact footprints for substation land constraints. The Central Electricity Authority is mandating grid code compliance for solar and wind farms. Gujarat and Rajasthan solar farm developers are favoring outdoor gas-insulated equipment for 33 kV collector bus applications.
China
State Grid Corporation is expanding ultra-high-voltage transmission corridors requiring gas-insulated switchgear above 800 kV ratings. The Ministry of Ecology and Environment is imposing parallel localization and environmental compliance conditions on switchgear imports. Yangtze River Delta manufacturing clusters are absorbing domestic production capacity for medium-voltage vacuum interrupters.
Japan
Utilities are standardizing on vacuum switchgear for metropolitan substation upgrades to eliminate atmospheric contamination risks. METI efficiency standards are driving refurbishment of aging air-insulated installations. Tokyo and Osaka industrial corridors are maintaining specialized plasma physics and material science talent pools for vacuum interrupter design.
Global Switchgear Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across incompatible technical platforms, creating a tiered structure where scale advantages in high-voltage gas-insulated equipment contrast with agility in digital-integrated medium-voltage offerings. European and Japanese incumbents anchor the premium tier through proprietary SF6-free alternatives and vacuum interrupter expertise. Strategic moves concentrate on long-term service agreement anchoring and joint-venture manufacturing for localization compliance.
Within the diversified electrical equipment tier, ABB Ltd., Siemens AG, and Schneider Electric occupy positions exemplifying the convergence toward integrated energy management software layered across hardware portfolios. ABB Ltd. represents the gas-insulated specialization archetype, Siemens AG anchors the digital service contract model, and Schneider Electric exemplifies software-hardware integration. These three European-based entities sit within a competitive set where geographic origin and century-long industrial heritage confer credibility in utility procurement processes.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric |
| Siemens AG |
| Eaton Corporation |
| General Electric |
| Hitachi Ltd. |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Fuji Electric Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation mandates for SF6 phase-out are compressing product development timelines and forcing manufacturers toward fluoronitrile insulation platforms, which elevates input costs and fragments procurement across incompatible technical standards. This demand-side specification shift concentrates pricing power with suppliers holding certified alternative gas formulations and vacuum interrupter expertise.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for medium-voltage vacuum switchgear while premium gas-insulated equipment retains margin insulation through technical scarcity. Three-tier pricing structure across premium fluoronitrile-certified, standard SF6-transitional, and economy air-insulated tiers separates procurement by voltage rating and environmental compliance tier. Cost compression in the standard tier intensifies because European utilities are accelerating replacement timelines ahead of original depreciation schedules. Industrial captive power buyers in India exhibit highest price sensitivity, whereas German transmission system operators prioritize 15-20 year service agreements over unit cost minimization.
Supply Chain Analysis
Vacuum interrupter ceramic enclosures rest on specialized Japanese and German plasma physics manufacturing clusters with limited alternative sourcing. Copper contact assemblies, rare earth magnetic materials, and fluoronitrile gas blends constitute critical input dependencies with concentrated supply origins. Single-source vulnerability runs through Japanese vacuum interrupter foundries where decades of arc interruption expertise have not replicated elsewhere. Distribution runs through authorized OEM service networks for high-voltage equipment, while medium-voltage products flow through electrical distributors and EPC contractor procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's 2030 phase-down steps compound replacement demand across European transmission networks, creating a regulatory-driven demand window that favors prepared incumbents and threatens stranded inventory holders.
For Market Incumbents: Anchor long-term service agreements with 15-20 year performance guarantees covering predictive maintenance and end-of-life gas recovery to lock in German and UK distribution network procurement. Accelerate backward integration into fluoronitrile gas supply and vacuum interrupter ceramic manufacturing to defend margin position against commodity contact material volatility and single-source input risk. Prioritize IEC 62271-200 certification investment for SF6-free alternatives ahead of regulatory deadlines to capture replacement demand pulling forward from original depreciation schedules. For New Entrants and Emerging Players: Launch via joint-venture manufacturing partnerships in Vietnam and Indonesia to satisfy localization requirements in Southeast Asian grid expansion tenders while avoiding pure import penalties. Target India's renewable integration segment for gas-insulated switchgear with compact footprints, where CEA-mandated grid code compliance creates specification entry points absent incumbent relationship lock-in. Pursue digital twin integration as a service-layer wedge, offering predictive maintenance subscriptions that transform capital equipment relationships into recurring revenue streams. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists holding vacuum interrupter design expertise and plasma physics talent concentrated in German and Japanese industrial regions. Long-term viability over the projection horizon favors acquisition targets with certified SF6-free product platforms and established utility service contract relationships rather than pure equipment manufacturers. Monitor IEC standardization progress for fluoronitrile blends at 145 kV ratings as the inflection signal for alternative gas technology market acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Product Certification | EU F-Gas Regulation compliance unlocks replacement demand in German and French transmission networks. |
| Long-Term Service Agreement Anchoring | 15-20 year performance guarantees transform transactional sales into recurring revenue streams with utility TSOs. |
| Joint-Venture Manufacturing Localization | Vietnam and Indonesia tender requirements favor domestic production partnerships over import-dependent supply. |
| Digital Twin Platform Integration | Predictive maintenance subscriptions convert passive protection equipment into grid-edge computing nodes. |
| Vacuum Interrupter Capacity Expansion | Ceramic-enclosed vacuum technology captures medium-voltage share as environmental regulations tighten. |
Study Parameters
Coverage spans North America, Europe, Asia-Pacific, and Middle East-Africa, with primary inputs from each region combining structured interviews with utility planning officers, EPC contractor procurement leads, switchgear OEM technical directors, and aftermarket service heads with secondary validation. Primary fieldwork drew from regulatory filings including EPA greenhouse gas reports, EU F-Gas Regulation implementation documents, and CEA grid code notifications alongside customs trade data and IEC standardization committee records. Bottom-up unit shipment estimates triangulated against top-down transmission and distribution capital expenditure disclosures from major grid operators.
Granularity-level modeling disaggregated volume and value outputs across voltage rating, insulation technology, installation type, and end-user segment throughout the forecast period. Analytical framework approach incorporated arc interruption physics constraints, regulatory phase-out timelines, and data center power density requirements as industry-specific forecast inputs. CAGRs derived from regression analysis of historical replacement cycles overlaid with regulatory acceleration effects and renewable integration project pipelines.
Several conditions sit outside the modeled scope, including unannounced regulatory timeline accelerations, breakthrough solid-state switching technologies, and geopolitical disruptions to rare earth material flows. Forecasts reflect documented assumptions regarding SF6 inventory stranding rates and vacuum interrupter manufacturing yield improvements. A small set of named triggers warrants ongoing watch: IEC 62271-200 revision progress, Indian PLI scheme expansion for electrical equipment, and US IRA domestic content bonus implementation clarity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
Touchpad Market
Switches
Paralleling Switchgear Market
Switches
KVM Switch Market
Switches
China Reed Sensors Switches Market
Switches
Safety Limit Switches Market
Switches
Smart Circuit Breaker Market
Switches
UK Reed Sensors Switches Market
Switches
Dual Power Transfer Switches Market
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
Molded Case Circuit Breaker Market
Switches
Global Light Control Switches Market
Switches
Micro Switch Market
Switches
Miniature-Circuit Breaker Market
Switches
In-Wall Smart Switch Market