
 5G Solid State Switches Market | 2026-2036
5G Solid State Switches Market Size, Share, and Industry Trends Forecast 2026-2036
5G Solid State Switches Market Insights
Modular RF front-end integration is realigning how network equipment manufacturers evaluate switch procurement. Infineon Technologies leverages its GaN HEMT portfolio to anchor high-power base station designs. Qorvo competes through specialized broadband switch architectures for small cell densification. MACOM Technology Solutions dominates in reflective switch configurations for test and measurement applications.
5G solid state switches are semiconductor devices that route RF signals without mechanical movement, typically achieving switching speeds below 50 nanoseconds and isolation exceeding 40 dB across sub-6 GHz and mmWave bands. GaN HEMT technology leads in transmit-path applications where power handling exceeds 10 watts, while PIN diode variants retain cost advantages in receive-chain switching where insertion loss budgets are tighter. Application segmentation shows base station deployments commanding the largest revenue pool, with military communication representing the fastest-growing margin segment due to hardened reliability specifications.
FCC spectrum auctions and the EU AI Act's infrastructure security provisions are tightening traceability requirements across telecom supply chains. ETSI 5G standards and China's GB/T radio regulations mandate specific spurious emission limits that directly determine switch filter integration complexity. Stakeholders must monitor how Open RAN disaggregation alters procurement authority between telecom operators and network equipment manufacturers.
Market Dynamics
GaN-on-SiC substrate maturation is compressing switch insertion loss budgets while MIIT's base station deployment mandates in China pull volume commitments forward, restructuring how network equipment manufacturers allocate procurement across reflective and absorptive switch architectures.
Growth Catalysts
- Sub-6 GHz spectrum densification:FCC reallocation orders in the United States expand addressable channels for macro cell upgrades, forcing equipment refresh cycles that favor solid-state over electromechanical alternatives.
- Open RAN disaggregation:Interface standardization between radio units and distributed units creates procurement entry points for specialized switch suppliers outside incumbent vendor ecosystems.
- Thermal management advances:Diamond heat-spreader integration into GaN HEMT packages extends mean time between failures for outdoor base station deployments in high-temperature climates.
Market Restraints
- Silicon carbide substrate scarcity:Wolfspeed and Coherent control over 6-inch SiC wafer supply creates input cost volatility for GaN epitaxy houses serving the RF switch value chain.
- Electromechanical relay substitution:Hermetically sealed coaxial switches retain cost advantages below 3 GHz in receive-only paths where switching speed requirements stay above 100 microseconds.
- REACH substance restrictions:ECHA candidate list additions for gallium compounds complicate waste handling certifications for European contract manufacturers assembling front-end modules.
Strategic Opportunities
- India telecom infrastructure:TRAI's 5G spectrum allocation framework and BSNL's network modernization create first-mover advantages for suppliers establishing local assembly partnerships.
- Automotive V2X integration:DSRC and C-V2X module proliferation in connected vehicle platforms extends switch demand into transportation electronics beyond traditional telecom verticals.
- EU Chips Act funding:Subsidy pools for compound semiconductor fabrication capacity reduce capital barriers for European GaN foundry expansion serving RF component demand.
Industry Challenges
- Electromagnetic compatibility certification:ETSI EN 301 908 and FCC Part 27 testing timelines extend product qualification cycles by eight to fourteen months for multi-band switch designs.
- Legacy inventory absorption:Network equipment manufacturers face stranded component risk as PIN diode-based designs lose qualification status under revised 3GPP Release 17 specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Solid State Switches Market |
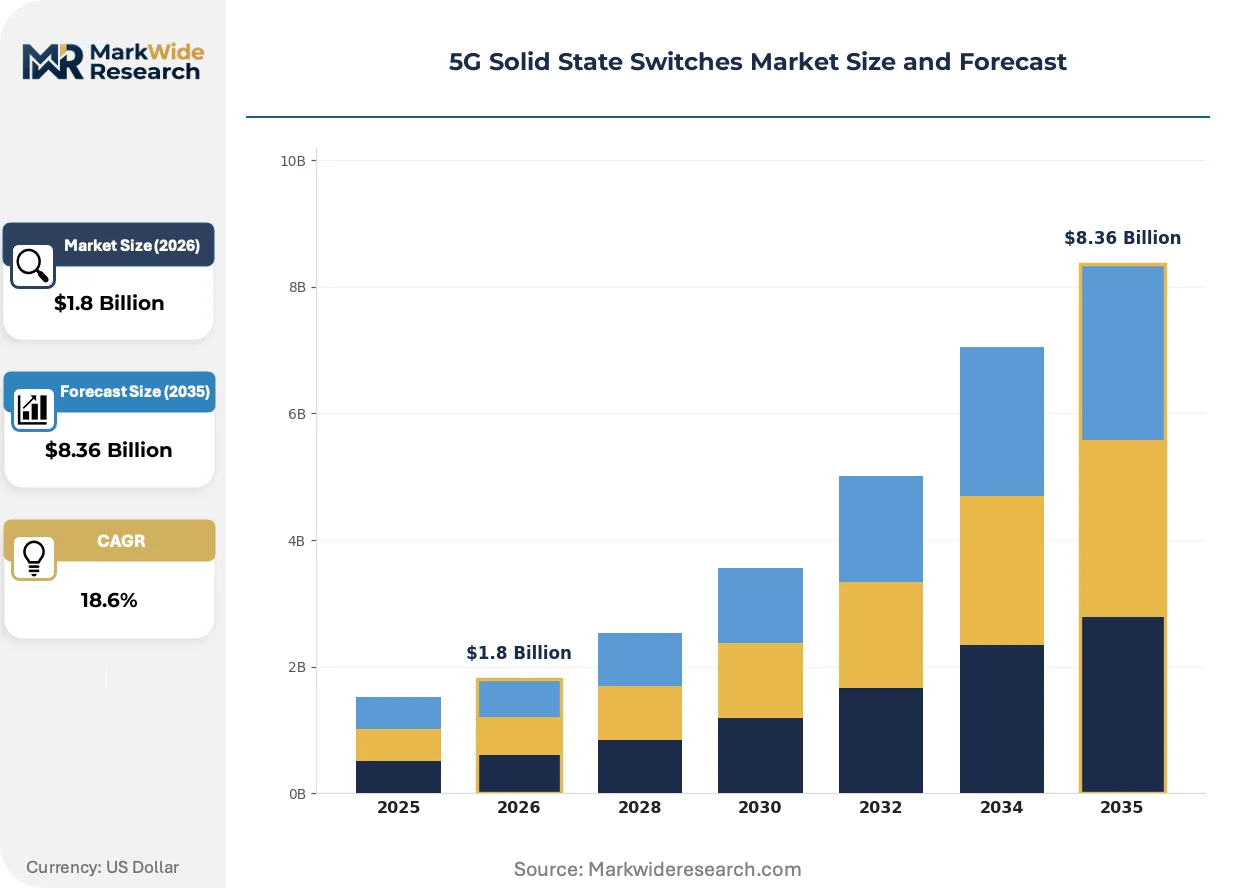
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: PIN Diode, FET, MESFET, GaN HEMT, BiCMOS Product Type: Single Pole Single Throw, Single Pole Double Throw, Double Pole Double Throw, Transfer Switch, Reflective Switch Application: Base Stations, Small Cells, Test Equipment, Military Communication, Satellite Communication End User: Telecom Operators, Network Equipment Manufacturers, System Integrators, Defense Contractors, Satellite Service Providers |
| Companies Covered | Infineon Technologies, Renesas Electronics, Qorvo, Broadcom, Analog Devices, Skyworks Solutions, Murata Manufacturing, MACOM Technology Solutions, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Solid State Switches Market Trends and Innovations
RF front-end modularization is collapsing discrete component boundaries, forcing switch suppliers to validate performance within integrated assemblies rather than as standalone catalog items. This compression demands new co-design methodologies between semiconductor and packaging houses.
GaN-on-diamond thermal interface materials are integrating into high-power transmit-path switches, enabling base station architects to reduce heatsink mass by thirty percent while maintaining junction temperatures below 175°C. Network equipment manufacturers in China's eastern coastal provinces are qualifying these configurations fastest, driven by MIIT-mandated energy efficiency targets for outdoor macro installations. The structural consequence is that thermal performance is integrating into switch selection criteria alongside traditional electrical specifications.
ETSI's cybersecurity certification framework for 5G network equipment is mandating hardware-level tamper evidence in RF subsystems, including switches handling encrypted traffic paths. European network operators now require Common Criteria EAL4+ validation for front-end components deployed in sensitive infrastructure locations. German and French procurement teams are extending these requirements to small cell densification projects, forcing switch suppliers to engage certification laboratories earlier in product development cycles.
Direct sourcing contracts between tower companies and component suppliers are fragmenting traditional distribution channels that previously routed through network equipment manufacturer consolidation points. American Tower and Crown Castle in the United States now issue separate RF component specifications for distributed antenna system upgrades, bypassing Ericsson and Nokia procurement hierarchies. This channel disintermediation concentrates price negotiation leverage with infrastructure owners who optimize for total cost of ownership rather than upfront capital expenditure.
5G Solid State Switches Market Segmentation
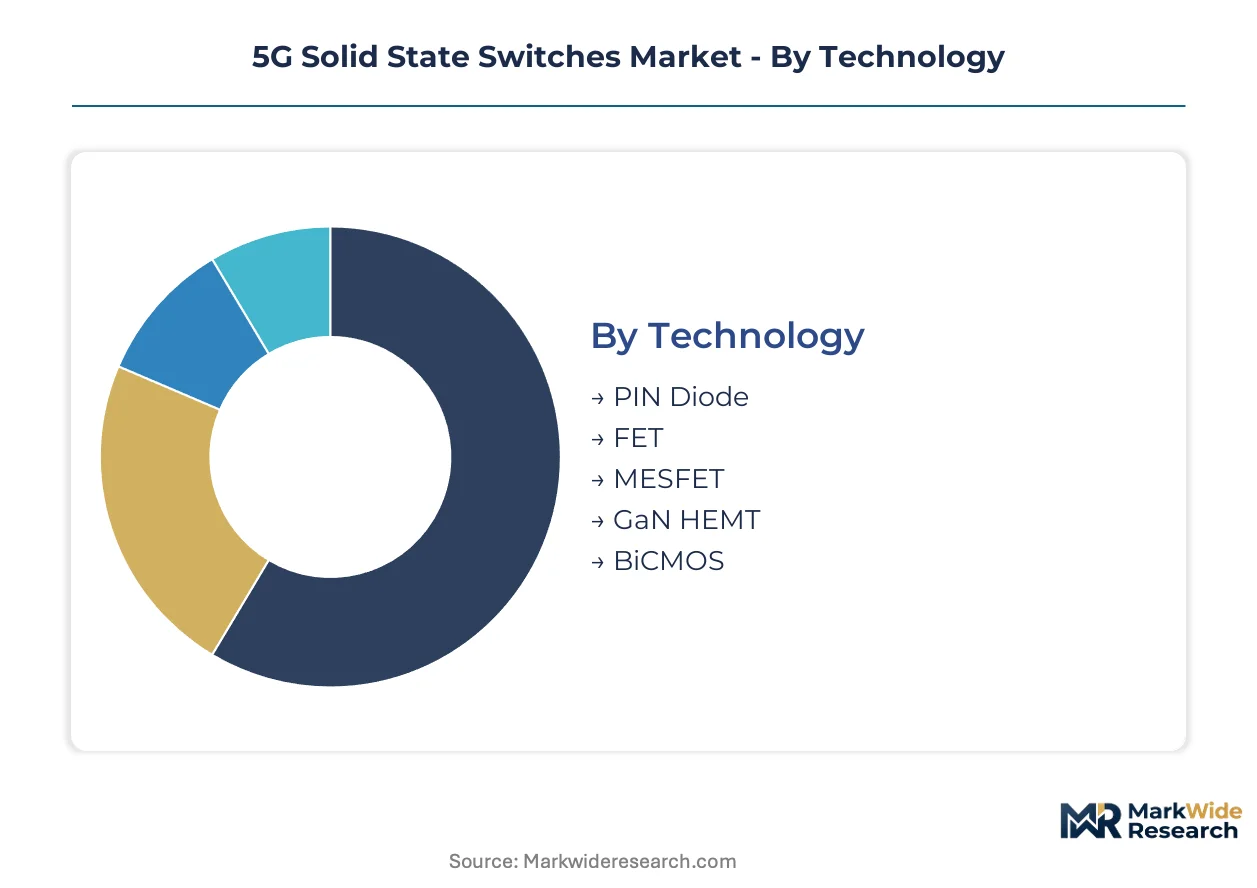
5G solid state switches fragment across technology generations, product architectures, and procurement hierarchies. Each segmentation axis reveals distinct margin structures and supplier concentration patterns that determine competitive positioning.
Technology:
Supply concentration among GaN epitaxy houses and silicon foundries determines which technology nodes achieve cost-competitive scale first.
- GaN HEMT:Gallium nitride high-electron-mobility transistors deliver power handling above 10 watts with switching speeds below 10 nanoseconds. Base station transmit-path demand in China's eastern coastal provinces concentrates procurement with domestic network equipment manufacturers facing MIIT energy efficiency mandates.
- PIN Diode:P-intrinsic-N diode structures achieve insertion loss below 0.5 dB across sub-6 GHz bands through mature silicon processing. Receive-chain applications in small cell densification projects across the United States retain cost advantages where FCC spectrum reallocation forces equipment refresh cycles.
- FET:Field-effect transistor switches leverage CMOS compatibility for low-power control logic integration.
- MESFET:Metal-semiconductor FET variants serve legacy military communication systems requiring radiation-hardened specifications.
- BiCMOS:Bipolar-CMOS integration suits mixed-signal front-end modules demanding precise bias control.
Today's leader: GaN HEMT. Tomorrow's challenger: PIN Diode.
Product Type:
Cost tier differentiation separates catalog switches from application-specific designs requiring co-validation with filter and amplifier assemblies.
- Single Pole Double Throw:SPDT configurations route signals between two output paths with isolation exceeding 40 dB. Small cell deployments in urban India under TRAI's 5G framework concentrate demand for compact surface-mount packages.
- Reflective Switch:Reflective architectures terminate unselected ports internally, eliminating external load requirements. Test equipment manufacturers in Germany and France specify these for automated calibration systems under ETSI cybersecurity certification pressures.
- Single Pole Single Throw:SPST designs provide simplest on-off control for antenna tuning applications.
- Double Pole Double Throw:DPDT structures enable redundant path switching in military communication platforms.
- Transfer Switch:Transfer configurations switch between two complete RF chains for hot-standby base station architectures.
Premium positioning clusters with Reflective Switch. Volume scaling favors Single Pole Double Throw.
Application:
Volume concentration in infrastructure deployment creates procurement leverage that compresses margins for standardized switch configurations.
- Base Stations:Macro cell installations demand switches handling 100-watt transmit power with thermal cycling resistance across -40°C to 85°C operating ranges. China's MIIT-mandated buildout targets pull forward multi-year procurement commitments from domestic equipment suppliers.
- Military Communication:Hardened reliability specifications including MIL-STD-883 screening extend qualification cycles and sustain margin premiums. European defense contractors under EU AI Act infrastructure security provisions now require hardware-level tamper evidence in RF subsystems.
- Small Cells:Dense urban deployments prioritize compact form factors and low power consumption.
- Test Equipment:Calibration-grade switches demand repeatability specifications below 0.1 dB variation across millions of cycles.
- Satellite Communication:Space-qualified variants must survive launch vibration and radiation exposure without performance degradation.
Revenue concentration anchors in Base Stations. Steepest expansion trajectory emerges from Military Communication.
End User:
Customer type determines whether procurement flows through consolidated network equipment manufacturers or fragments toward direct tower company sourcing.
- Network Equipment Manufacturers:Ericsson, Nokia, and Huawei procurement hierarchies traditionally consolidated RF component demand. Open RAN disaggregation in the United States now fragments this channel as American Tower and Crown Castle issue separate specifications for distributed antenna systems.
- Telecom Operators:Carrier technical teams increasingly specify switch performance parameters directly. India's BSNL network modernization creates first-mover opportunities for suppliers establishing local assembly partnerships under TRAI's framework.
- Defense Contractors:Military procurement cycles prioritize traceability and long-term supply assurance over unit cost.
- System Integrators:Third-party integration houses demand flexible sourcing for multi-vendor deployments.
- Satellite Service Providers:Space segment operators qualify switches for orbital replacement unit compatibility.
Procurement authority is concentrating with Telecom Operators. Defense Contractors retain margin protection through specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom infrastructure development in the United States established early 5G solid state switch deployment patterns through FCC spectrum auctions and base station densification mandates. Manufacturing scale subsequently migrated toward Asian semiconductor clusters as substrate processing and packaging capabilities concentrated in specific industrial zones.
United States
FCC spectrum reallocation orders and Open RAN disaggregation are fragmenting procurement channels toward tower companies like American Tower and Crown Castle. Distributed antenna system specifications now bypass traditional network equipment manufacturer hierarchies. Design validation concentrates in Massachusetts and California RF engineering clusters.
China
MIIT-mandated 5G base station buildout targets are pulling multi-year volume commitments from domestic network equipment manufacturers. GB/T radio regulations mandate spurious emission limits that determine switch filter integration complexity. Yangtze River Delta packaging houses are qualifying GaN-on-diamond thermal configurations fastest under energy efficiency directives.
Germany
ETSI cybersecurity certification frameworks now require Common Criteria EAL4+ validation for front-end components in sensitive infrastructure. EU AI Act infrastructure security provisions extend hardware-level tamper evidence requirements to small cell densification projects. Bavarian test equipment manufacturers specify reflective switch architectures for automated calibration systems.
India
TRAI's 5G spectrum allocation framework and BSNL network modernization are creating first-mover opportunities for suppliers establishing local assembly partnerships. CEA power efficiency standards for telecom infrastructure influence thermal management specifications in outdoor deployments. Gujarat and Maharashtra electronics manufacturing clusters are absorbing component assembly for domestic network rollouts.
Japan
METI semiconductor supply chain resilience initiatives are diversifying GaN epitaxy sourcing away from single-region dependencies. JIS standards for RF component reliability influence qualification protocols for base station deployments. Kyushu-based packaging houses are integrating diamond heat-spreader technologies for high-temperature climate installations.
5G Solid State Switches Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal performance and certification complexity tiers. GaN HEMT specialists command pricing power in transmit-path applications above 10 watts, while PIN diode fabricators compete on insertion loss budgets in receive-chain segments. Three archetypes dominate: integrated semiconductor conglomerates with captive foundry capacity, fabless RF specialists outsourcing epitaxy growth, and captive suppliers vertically integrated into network equipment manufacturers. Competitive moves center on substrate supply security through long-term wafer agreements and co-design partnerships with packaging houses for modular front-end integration.
Among European integrated semiconductor conglomerates, Infineon Technologies anchors high-power base station design partnerships through its GaN HEMT portfolio. Qorvo exemplifies the fabless RF specialist archetype competing through broadband switch architectures for small cell densification. MACOM Technology Solutions occupies a position among reflective switch suppliers serving test and measurement applications requiring calibration-grade repeatability specifications.
| Leading Market Players |
|---|
| Infineon Technologies |
| Renesas Electronics |
| Qorvo |
| Broadcom |
| Analog Devices |
| Skyworks Solutions |
| Murata Manufacturing |
| MACOM Technology Solutions |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
GaN-on-SiC wafer costs cascade through three distinct pricing tiers as substrate scarcity at Wolfspeed and Coherent concentrates upstream pricing power, while downstream buyers in China's eastern coastal provinces negotiate volume discounts against MIIT-mandated energy efficiency specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates GaN HEMT transmit-path switches certified for 100-watt base station deployment from PIN diode receive-chain variants and commodity FET alternatives. Price differentiation rests on thermal performance grade and ETSI cybersecurity certification tier, with Common Criteria EAL4+ validation commanding substantial premiums. Cost compression in standard-tier PIN diode configurations is intensifying because FCC spectrum reallocation forces rapid equipment refresh cycles. Tower companies like American Tower and Crown Castle exhibit lowest price sensitivity due to total cost of ownership optimization, while Indian contract manufacturers under TRAI's framework face acute margin pressure.
Supply Chain Analysis
Freight cost volatility from Yangtze River Delta packaging houses to European base station assembly sites compounds lead time uncertainty for diamond heat-spreader integrated modules. Supply concentrates in China, the United States, and Japan, with GaN epitaxy drawing from Wolfspeed's North Carolina SiC substrate fabs and Kyushu-based packaging integration. Raw material dependencies span high-purity gallium, synthetic diamond substrates, and specialized ceramic packages. Single-source vulnerability at 6-inch SiC wafer suppliers creates structural risk. Distribution runs through direct sourcing contracts between tower companies and component suppliers, fragmenting traditional network equipment manufacturer consolidation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's MIIT-mandated volume buildouts and India's emerging TRAI-supervised procurement creates cost advantages for suppliers establishing local assembly partnerships in Gujarat and Maharashtra electronics clusters.
For Market Incumbents: Extend GaN HEMT thermal performance roadmaps to defend against PIN diode cost erosion in receive-chain applications below 3 GHz. Secure long-term wafer supply agreements with Wolfspeed and Coherent to mitigate silicon carbide substrate scarcity. Invest in Common Criteria EAL4+ certification infrastructure ahead of EU AI Act infrastructure security provision expansion into small cell densification projects. For New Entrants and Emerging Players: Tower company procurement teams represent an underserved buyer archetype bypassing traditional network equipment manufacturer hierarchies through direct RF component specifications. Target distributed antenna system upgrade contracts from American Tower and Crown Castle in the United States, and BSNL network modernization opportunities under India's TRAI framework. Pursue co-design partnerships with Yangtze River Delta packaging houses to accelerate GaN-on-diamond thermal configuration qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where fabless RF specialists lack captive epitaxy capacity and face input cost volatility from concentrated SiC substrate suppliers. Long-term viability favors integrated semiconductor conglomerates with backward integration into GaN foundry operations or exclusive wafer supply arrangements. Acquisition target archetypes include reflective switch specialists serving test equipment manufacturers and broadband switch architects for small cell densification. Monitor FCC spectrum auction timelines and MIIT base station deployment mandate revisions as inflection indicators for volume commitment timing.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Capacity Expansion | Reduces dependency on Wolfspeed and Coherent SiC wafer supply for RF switch manufacturers. |
| Common Criteria EAL4+ Certification Investment | Unlocks procurement access to EU AI Act-mandated infrastructure security projects in Germany and France. |
| Diamond Heat-Spreader Integration Partnership | Enables thirty percent heatsink mass reduction for MIIT energy efficiency-targeted base station deployments. |
| Direct Tower Company Sourcing Agreement | Bypasses Ericsson and Nokia procurement hierarchies through American Tower and Crown Castle specifications. |
| India Local Assembly Partnership | Captures first-mover advantage under TRAI's 5G framework and BSNL network modernization procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with RF component procurement managers at network equipment manufacturers, semiconductor packaging engineers in Yangtze River Delta clusters, and regulatory affairs specialists at tower companies with secondary validation against FCC spectrum auction records, MIIT deployment mandate disclosures, ETSI cybersecurity certification databases, and SEC filings from publicly traded GaN epitaxy houses. Bottom-up demand modeling across base station, small cell, and military communication applications triangulated against top-down semiconductor industry revenue estimates.
Comparable-period anchoring established historical reference baselines from sub-6 GHz spectrum densification cycles and mmWave pilot deployments, then extended across the analysis window through technology adoption curve modeling. Segmentation dimensions included switch technology generation, product architecture, application vertical, and procurement hierarchy type. CAGRs derived from installed base replacement rates, FCC reallocation order timing, and MIIT-mandated buildout trajectories. Industry-specific inputs incorporated GaN HEMT power handling roadmaps and PIN diode insertion loss evolution curves.
Underlying measurement precision varies by segment; GaN HEMT base station applications carry tighter precision than emerging automotive V2X integration categories due to established procurement reporting channels. Forecasts reflect documented assumptions regarding spectrum allocation timelines, substrate supply expansion rates, and Open RAN disaggregation velocity. Stakeholders should weight assumptions against their own operating context, particularly regarding REACH substance restriction enforcement trajectories for gallium compound handling certifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Dual Power Transfer Switches Market
Switches
Global Safety Switches Market
Switches
Optical Switches Market
Switches
Global Light Control Switches Market
Switches
Membrane Switch Market
Switches
Australia and New Zealand Medium Voltage Switchgear Market
Switches
Europe Low Voltage Switchgear Market
Switches
Europe Switchgear Market
Switches
Intelligent Power Switches Market
Switches
Asia Pacific Transfer Switches Market
Switches
China Reed Sensors Switches Market
Switches
Italy Reed Sensors Switches Market
Switches
Power Load Switches Market
Switches
Australia Switchgear Market
Switches
Surface Mount Switch Market
Switches
North America MV Switchgear Market