
 Smart Pole-Mounted Switch Market | 2026-2036
Smart Pole-Mounted Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pole-Mounted Switch Market Insights
Multi-source procurement for electronic control modules is hardening across tier-one suppliers as OEMs reduce dependency on single foundries. Siemens sustains R&D intensity in integrated control firmware for European utility deployments. Eaton anchors North American manufacturing scale through dedicated pole-mount assembly facilities. Huawei Technologies competes on wireless communication stacks embedded directly into switch housings.
A smart pole-mounted switch is an electromechanical or solid-state device installed on overhead distribution poles, typically rated for medium-voltage circuits between 15 kV and 38 kV, designed to interrupt, redirect, or monitor electrical flow under remote command. Its primary purpose is to enable automated fault isolation, load balancing, and real-time grid visibility without requiring manual crew dispatch. Automatic switch configurations now capture the dominant share of new installations as utilities prioritize self-healing network architectures. Smart grid applications generate the fastest order growth, though street lighting remains the largest installed base for legacy manual replacements.
FERC Order 2222 in the United States and the EU Green Deal's efficiency directives are accelerating interoperability mandates that shape product roadmaps. IEEE 2030 standards and CE marking requirements under the EU's F-Gas Regulation constrain market access for non-compliant suppliers. Grid operators must weigh capital allocation between full automation retrofits and phased sensor-overlay deployments.
Market Dynamics
Automated fault isolation capabilities are compressing replacement cycles for legacy manual switches as grid operators prioritize self-healing network architectures over incremental sensor overlays.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation mandates in the United States are forcing utilities to deploy intelligent switching infrastructure capable of bidirectional power flow management and real-time telemetry.
- Silicon carbide power electronics:Wide-bandgap semiconductors are reducing switching losses and thermal footprint, enabling more compact pole-mounted housings without sacrificing interrupting capacity.
- German grid digitization:The SINTEG program and subsequent Netze der Zukunft initiatives are channeling utility capex toward automated medium-voltage sectionalizers with embedded communication modules.
Market Restraints
- Copper and rare-earth magnet costs:Price volatility in conductive materials and permanent magnet supply chains is squeezing margins for electromechanical actuator production.
- Single-source foundry dependency:Semiconductor wafer fabrication for control firmware concentrates in East Asian contract manufacturers, exposing OEMs to geopolitical supply interruptions.
- IEC 61850 interoperability gaps:Incomplete implementation profiles across vendor ecosystems force utilities into costly protocol gateway deployments or single-source lock-in.
Strategic Opportunities
- India rural electrification:The Saubhagya scheme and subsequent grid hardening programs create demand for cost-optimized automatic sectionalizers with cellular backhaul in distribution networks below 33 kV.
- Wildfire mitigation mandates:California Public Utilities Commission requirements for enhanced fault detection and rapid isolation are accelerating procurement of arc-fault-sensing pole switches in high-fire-threat districts.
- Edge AI convergence:Integration of machine learning inference engines with switch controllers enables predictive load balancing without centralized SCADA dependency.
Industry Challenges
- Substation automation technician shortage:Utilities face recruitment gaps for field crews capable of commissioning IEC 61850 logical nodes and troubleshooting GOOSE messaging faults.
- Legacy electromechanical integration:Phased retrofits require hybrid architectures that maintain manual bypass capabilities while adding remote operability, doubling commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pole-Mounted Switch Market |
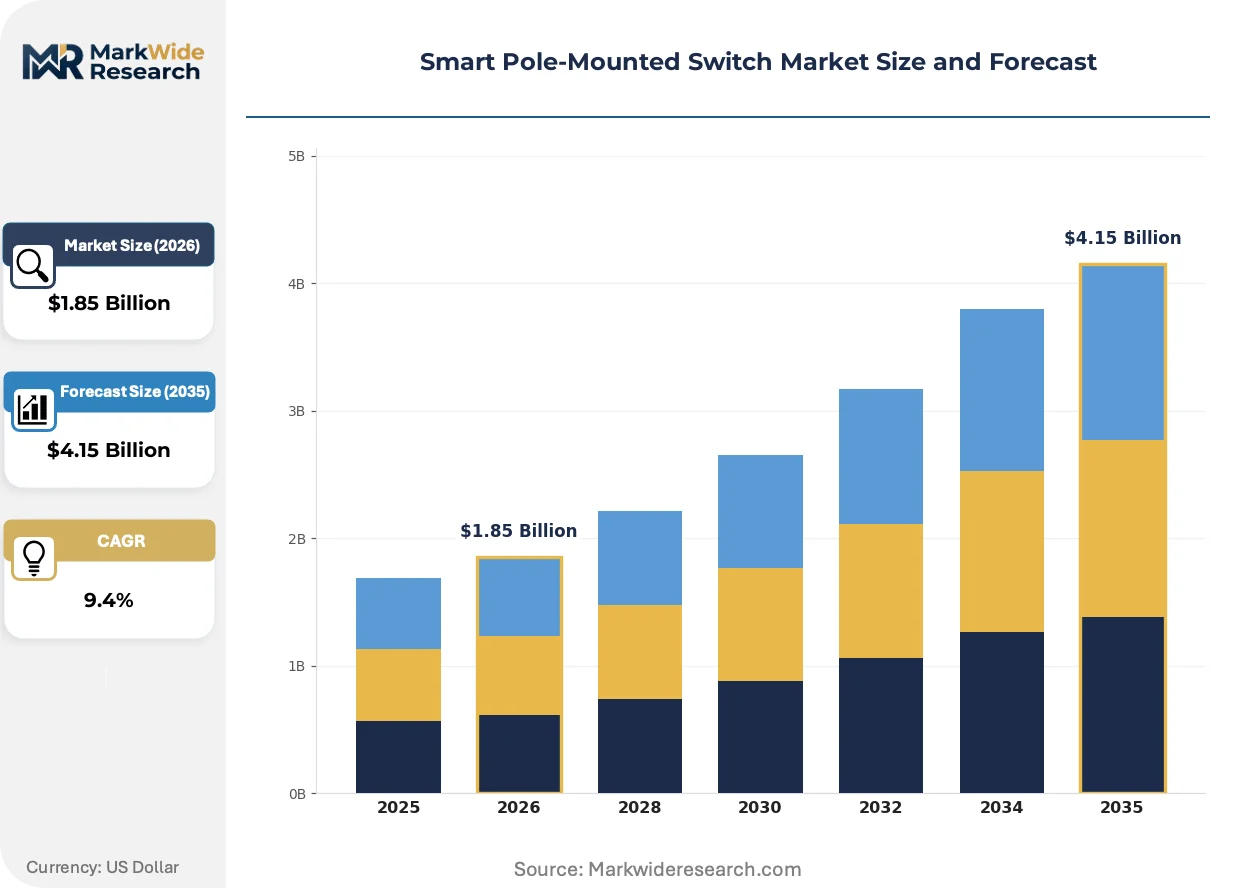
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Switch, Automatic Switch, Smart Switch, Remote Switch Application: Street Lighting, Traffic Management, Environmental Monitoring, Smart Grids End User: Municipalities, Utilities, Transportation Authorities, Private Sector Technology: IoT, Wireless Communication, Sensor Technology, Control Systems |
| Companies Covered | Signify Holding, Siemens, Eaton, Wipro Limited, General Electric, Omniflow, Delta Electronics, Huawei Technologies, Schréder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pole-Mounted Switch Market Trends and Innovations
Solid-state interruption technology and embedded wireless telemetry are converging to eliminate mechanical wear components while enabling sub-cycle fault isolation without crew dispatch.
Vacuum interrupters paired with magnetic actuators are overtaking oil-filled and SF6-insulated switchgear in new pole-mounted installations. European distribution system operators are specifying vacuum technology for urban retrofit programs where footprint constraints prohibit larger housings. This transition is compressing the installed base of maintenance-intensive legacy switches and shortening replacement cycles from twenty-five to fifteen years.
The EU F-Gas Regulation phase-down is accelerating SF6-free insulation development for medium-voltage switchgear. Manufacturers must certify alternative gas mixtures or dry air insulation to maintain CE marking access. German and French utilities are prioritizing procurement of F-Gas-compliant units, creating a two-tier supply landscape where non-compliant products face market exclusion.
Performance-based service agreements are displacing traditional equipment procurement with separate maintenance contracts. Nordic grid operators are piloting availability-guarantee structures where vendors retain ownership and assume uptime risk. This model is most advanced in Denmark and Sweden, where regulatory frameworks permit operational expenditure treatment of infrastructure investments.
Smart Pole-Mounted Switch Market Segmentation
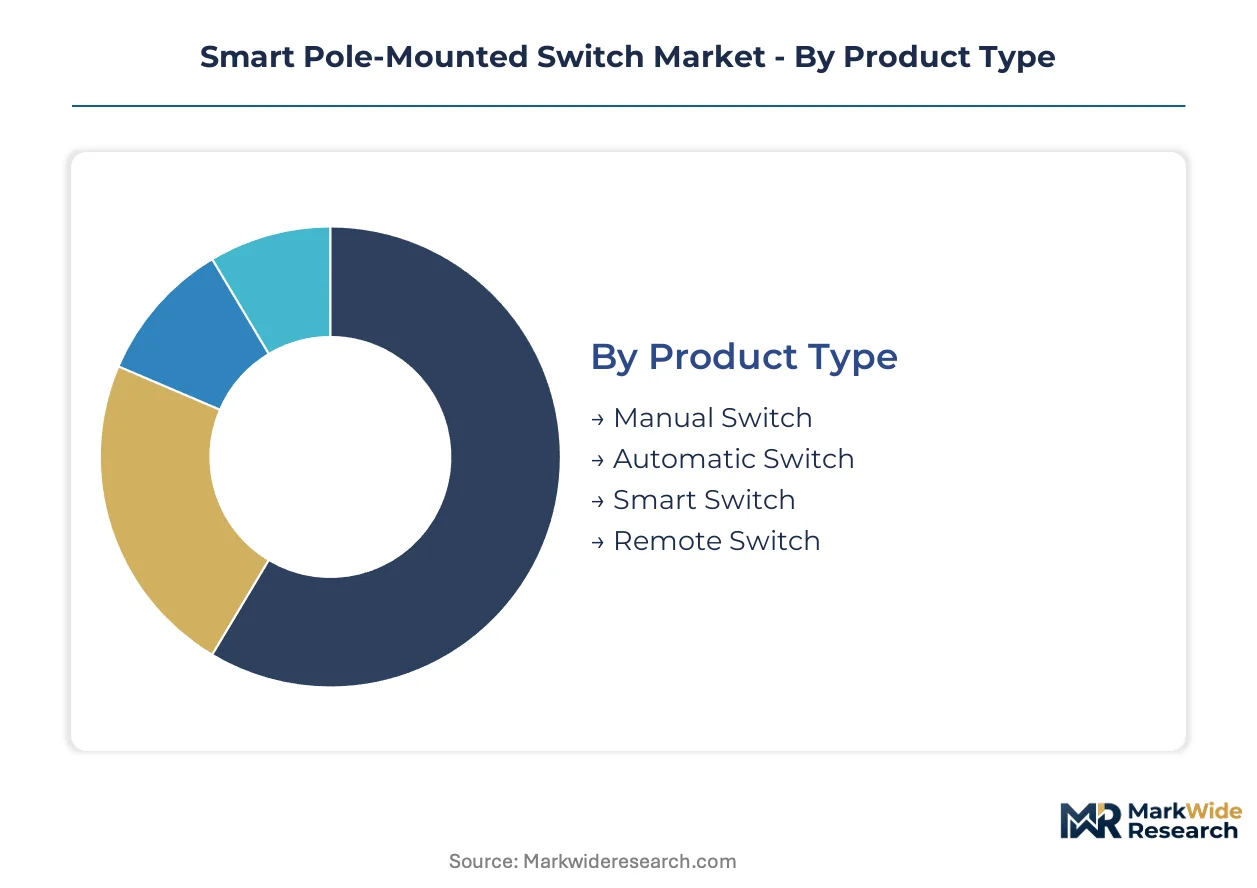
Product differentiation in pole-mounted switching infrastructure tracks directly to grid modernization timelines and crew dispatch economics. Segment boundaries blur as automatic and smart configurations increasingly merge into unified self-healing architectures.
Product Type:
Replacement cycles for legacy manual switches are compressing as utilities prioritize remote operability over incremental sensor retrofits.
- Manual Switch:Electromechanical devices requiring physical crew dispatch for operation, typically rated 15-38 kV with oil-filled or air-break interruption. Demand concentrates in India's rural electrification programs and legacy African distribution networks where capital constraints delay automation.
- Automatic Switch:Self-operating sectionalizers with embedded fault detection and isolation logic, eliminating crew response to routine outages. German DSOs under Netze der Zukunft mandates are standardizing on vacuum interrupter automatic configurations for urban retrofit programs.
- Smart Switch:Bidirectional telemetry-enabled devices with SCADA integration and load-flow optimization algorithms.
- Remote Switch:Radio or cellular-controlled units prioritizing command latency over autonomous intelligence.
Volume placements concentrate in Automatic Switch; the faster expansion belongs to Smart Switch.
Application:
Cost tier separation between lighting retrofits and grid automation creates divergent procurement specifications.
- Street Lighting:Legacy infrastructure replacement commanding the largest installed base, with manual-to-automatic upgrades driven by municipal energy efficiency mandates. California cities are bundling LED conversion with intelligent switching to qualify for CPUC wildfire mitigation incentives.
- Smart Grids:Real-time fault isolation and distributed energy resource integration generating fastest order growth. FERC Order 2222 aggregation requirements are forcing US utilities to deploy telemetry-capable switches for bidirectional power flow management.
- Traffic Management:Signal priority and adaptive intersection control requiring low-latency switching response.
- Environmental Monitoring:Air quality and noise sensor power management with intermittent load profiles.
Street Lighting retains the dominant placement volume; Smart Grids are climbing the fastest.
End User:
Customer type determines procurement channel and service contract structure.
- Utilities:Investor-owned and public power entities with centralized engineering standards and multi-year capital planning cycles. Performance-based availability contracts are displacing traditional equipment procurement among Nordic grid operators.
- Municipalities:City governments bundling street lighting, EV charging, and digital infrastructure under smart city frameworks. German municipalities are accelerating procurement through KfW green bond financing.
- Transportation Authorities:State and regional agencies prioritizing traffic signal reliability over grid integration.
- Private Sector:Industrial campuses and data center operators seeking dedicated medium-voltage control.
Utilities dominate current placements; municipalities are gaining share fastest.
Technology:
Technology stack selection determines interoperability certification requirements and supply chain exposure.
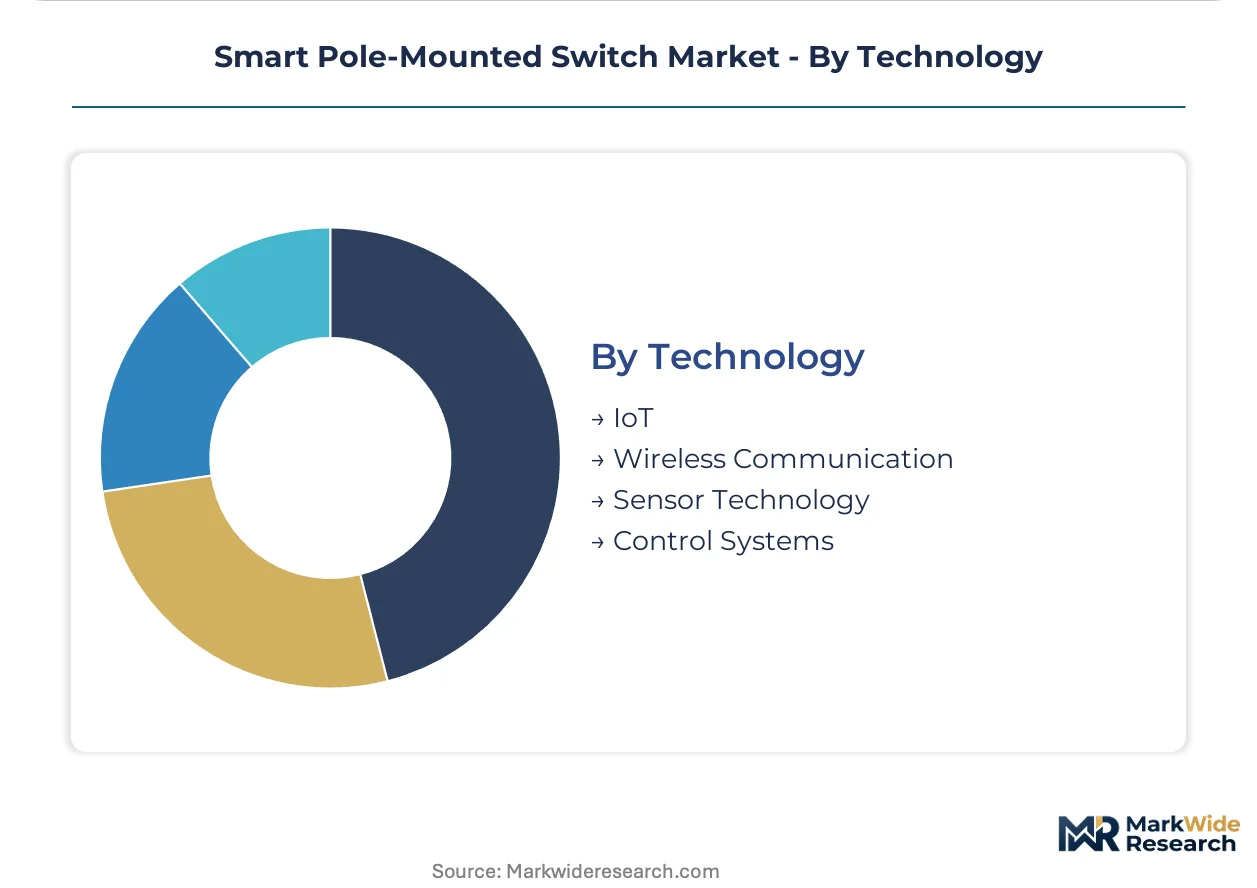
- IoT:IP-enabled device management platforms with cloud-based analytics and over-the-air firmware updates. European deployments are standardizing on IEC 61850 logical node mapping to avoid vendor lock-in.
- Wireless Communication:Cellular, mesh, and private LTE stacks embedded directly into switch housings. Huawei Technologies competes aggressively on integrated wireless modules for Middle East and Southeast Asian tenders.
- Sensor Technology:Current transformers, voltage sensors, and arc-fault detectors for predictive maintenance.
- Control Systems:Edge computing platforms with local decision logic reducing SCADA dependency.
Wireless Communication captures the highest placement volume; IoT shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing facilities in China's Jiangxi province supply permanent magnet actuators for electromechanical switch assemblies worldwide. Copper concentrate from Chilean mines feeds conductive winding production for medium-voltage interrupters. Silicon carbide substrate fabrication concentrates in Japanese and Korean foundries serving power electronics modules.
United States
FERC Order 2222 aggregation mandates and CPUC wildfire mitigation rules are accelerating intelligent switch procurement. The Inflation Reduction Act channels utility capex toward grid hardening in high-fire-threat districts. California utilities are deploying arc-fault-sensing pole switches across the Sierra Nevada foothills and Bay Area corridors.
Germany
The SINTEG program and Netze der Zukunft initiatives prioritize automated medium-voltage sectionalizers with embedded communication. EU F-Gas Regulation phase-down requirements are reshaping insulation technology specifications. Distribution system operators in Bavaria and North Rhine-Westphalia are standardizing vacuum interrupter configurations for urban retrofit density.
Japan
METI grid digitization roadmaps and earthquake-resilience mandates drive solid-state interruption technology adoption. Silicon carbide power electronics from domestic foundries enable compact thermal footprints for pole-mounted housings. Tokyo Electric and Kansai utilities are piloting edge-AI load balancing in the Kanto and Kansai metropolitan belts.
India
The Saubhagya rural electrification scheme and subsequent grid hardening programs create demand for cost-optimized automatic sectionalizers. Central Electricity Authority standards are tightening interoperability requirements for cellular backhaul deployments. Maharashtra and Gujarat state utilities are procuring 33 kV-rated units for agricultural feeder automation.
United Arab Emirates
Smart city frameworks in Dubai and Abu Dhabi bundle intelligent street lighting with EV charging infrastructure. The country's national regulator mandates IEC 61850 compliance for new distribution automation investments. Emirates District Cooling and DEWA are deploying telemetry-enabled switches across Mohammed bin Rashid Al Maktoum Solar Park periphery networks.
Smart Pole-Mounted Switch Market Competitive Landscape
Global majors compete with regional champions across wireless communication integration and vacuum interrupter supply chains. The vendor base organizes into three tiers: integrated electrical conglomerates with captive semiconductor sourcing, specialized pole-mount assembly houses, and communication-stack specialists leveraging cellular module expertise. Dominant competitive moves include strategic partnerships for IEC 61850 certification coverage and geographic expansion through performance-based service contract structures.
Among diversified electrical equipment manufacturers, Siemens and Eaton exemplify the integrated-tier archetype, while Huawei Technologies occupies a position within the communication-embedded specialist tier. Signify Holding and Schréder sit within the lighting-to-grid convergence segment, leveraging street lighting retrofit relationships to access distribution automation procurement channels. General Electric and Delta Electronics represent the multinational industrial conglomerate pattern with cross-regional utility relationships. Omniflow and Wipro Limited exemplify the regional solution-provider archetype targeting smart city bundling opportunities.
| Leading Market Players |
|---|
| Signify Holding |
| Siemens |
| Eaton |
| Wipro Limited |
| General Electric |
| Omniflow |
| Delta Electronics |
| Huawei Technologies |
| Schréder |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate costs from Japanese and Korean foundries cascade through three distinct pricing tiers for power electronics modules, with vacuum interrupter assemblies commanding premium positioning against oil-filled legacy alternatives.
Pricing Analysis
Warranty and service bundling separate capital-equipment procurement from performance-based availability contracts, with Nordic utilities pioneering uptime-guarantee structures where vendors retain ownership risk. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service depth, with F-Gas-compliant vacuum units from German manufacturers sitting at the top tier. Pricing pressure stems from copper and rare-earth magnet volatility squeezing electromechanical actuator margins. Municipal buyers in emerging markets exhibit highest price sensitivity, while investor-owned utilities in fire-threat districts absorb premium positioning for arc-fault-sensing configurations.
Supply Chain Analysis
Container freight rates from East Asian semiconductor hubs to European assembly plants directly impact landed costs for control firmware modules, compressing margins on mid-tier automatic switches. Silicon carbide fabrication concentrates in Japan and South Korea; vacuum interrupter ceramics source from German and Chinese suppliers; rare-earth magnet processing anchors in China's Jiangxi province. Single-source foundry dependency for semiconductor wafers exposes OEMs to geopolitical disruption. Distribution runs through direct utility procurement channels in developed markets and EPC contractor intermediaries in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation phase-down constructs a compliance moat that rewards pre-certified vacuum interrupter suppliers while excluding SF6-dependent competitors from CE-marked procurement pools.
For Market Incumbents: To counter IEC 61850 interoperability gaps that force costly protocol gateway deployments, Siemens and Eaton should deepen backward integration into semiconductor sourcing through captive foundry partnerships in Japan. Certification investment in edge-AI load balancing firmware creates differentiation against communication-stack specialists. For New Entrants and Emerging Players: A 40-60% price-point gap between premium vacuum interrupter units and economy-grade oil-filled alternatives in India's 33 kV agricultural feeder segment opens white-space for cost-optimized automatic sectionalizers with cellular backhaul. Target Maharashtra and Gujarat state utilities through EPC contractor channels, bundling commissioning support to offset technician shortage barriers. For Investors and Strategic Acquirers: California Public Utilities Commission wildfire mitigation mandate acceleration is the leading indicator that arc-fault-sensing pole switch procurement will concentrate deployment budgets in high-fire-threat districts. Mid-tier assembly houses with F-Gas-compliant vacuum technology and existing utility relationships represent prime acquisition targets. Watch for German Netze der Zukunft initiative budget allocations as the signal for European automation capex inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Foundry Capacity | Captive substrate supply from Japanese foundries secures power electronics margin control against East Asian concentration risk. |
| F-Gas Certification Acceleration | Early CE marking for dry air insulation unlocks German and French utility procurement pools ahead of regulatory deadlines. |
| Performance-Based Service Contract Expansion | Availability-guarantee structures shift revenue to operational expenditure treatment favored by Nordic regulatory frameworks. |
| Edge-AI Firmware Development | Predictive load balancing algorithms reduce SCADA dependency for Tokyo Electric and Kansai metropolitan deployments. |
| Cellular Backhaul Partnership | Integrated 4G/5G modules from Huawei Technologies enable cost-optimized rural electrification tenders in India and Southeast Asia. |
Research Methodology
Multi-period observation of utility capital expenditure disclosures, smart grid interoperability certification timelines, and rare-earth magnet price indices anchored the trend analysis, supplemented by interviews with distribution system operator planning officers, pole-mount assembly plant managers, semiconductor procurement leads, and EPC contractor project directors. Secondary validation drew from FERC Order 2222 implementation filings, EU F-Gas Regulation compliance databases, German SINTEG program progress reports, and Central Electricity Authority standards documentation. Bottom-up segment sizing triangulated against top-down grid modernization budget aggregates.
Input-output matrices mapped product type, application, end user, and technology stack dimensions across the projection horizon, with CAGRs derived from utility procurement pipeline analysis and regulatory mandate acceleration curves. Forecast inputs incorporated silicon carbide adoption rates in power electronics, vacuum interrupter replacement cycle compression, and cellular backhaul penetration in rural electrification programs.
Inputs from utility planning departments and OEM engineering teams were available through the study window; gaps in real-time commodity pricing for copper and rare-earth magnets introduce uncertainty bands around electromechanical actuator cost assumptions. Forecasts reflect documented regulatory timelines and technology substitution curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Australia and New Zealand Medium Voltage Switchgear Market
Switches
Off-Road Machine Ruggedized Switch and Indicator Systems Market
Switches
Europe Low Voltage Switchgear Market
Switches
Push Button Dropper Market
Switches
Japan Reed Sensors Switches Market
Switches
DC Circuit Breaker Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Cross Point Switch Market
Switches
North America MV Switchgear Market
Switches
Analog Switches Market
Switches
Static Transfer Switches Market
Switches
Global Safety Switches Market
Switches
Molded Case Circuit Breaker Market
Switches
Smart Dimmer Switch Market
Switches
Global Float Level Switches Market
Switches
Micro Switch Market