
 Global Safety Switches Market | 2026-2036
Global Safety Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Safety Switches Market Foresight
Renewable energy firms is reorganizing procurement priorities across the safety switch value chain, displacing traditional oil and gas buyers as the fastest-growing customer archetype. Schneider Electric leverages its programmable safety controller portfolio to dominate renewable integration projects across Europe and Asia. Siemens AG anchors its position through captive semiconductor production for electronic safety relays, insulating margins from component volatility. Rockwell Automation competes by extending its ArmorBlock Guard I/O platform into compact wireless safety nodes for distributed solar farms.
Safety switches are electromechanical or solid-state devices designed to interrupt power circuits when guard doors open, emergency stops activate, or position thresholds breach, typically rated for IP65-IP67 ingress protection and SIL 3/PLe functional safety integrity. Their primary purpose is to prevent mechanical hazards in automated environments by enforcing fail-safe machine states. Electromechanical switches retain the largest installed base due to proven durability in heavy contamination, though electronic variants are capturing the fastest expansion as semiconductor reliability improves and diagnostic feedback becomes mandatory. Relay-based technology still occupies the majority of legacy manufacturing plants, while programmable logic control integration is displacing hardwired configurations in new chemical processing builds where flexible batch operations demand reconfigurable safety zones.
OSHA mandates lockout-tagout procedures under 29 CFR 1910.147, directly shaping US demand for keyed and trapped-key switch architectures that enforce sequential de-energization. IEC 60947-5-1 and the EU Machinery Directive 2006/42/EC drive European product certification requirements, creating divergence in contact block specifications that vendors must navigate for transatlantic market access. China's GB standards and SAMR enforcement are accelerating domestic substitution pressures for foreign safety component suppliers. Stakeholders must decide whether to localize certification laboratories or partner with domestic manufacturers as compliance fragmentation intensifies across jurisdictions.
Market Dynamics
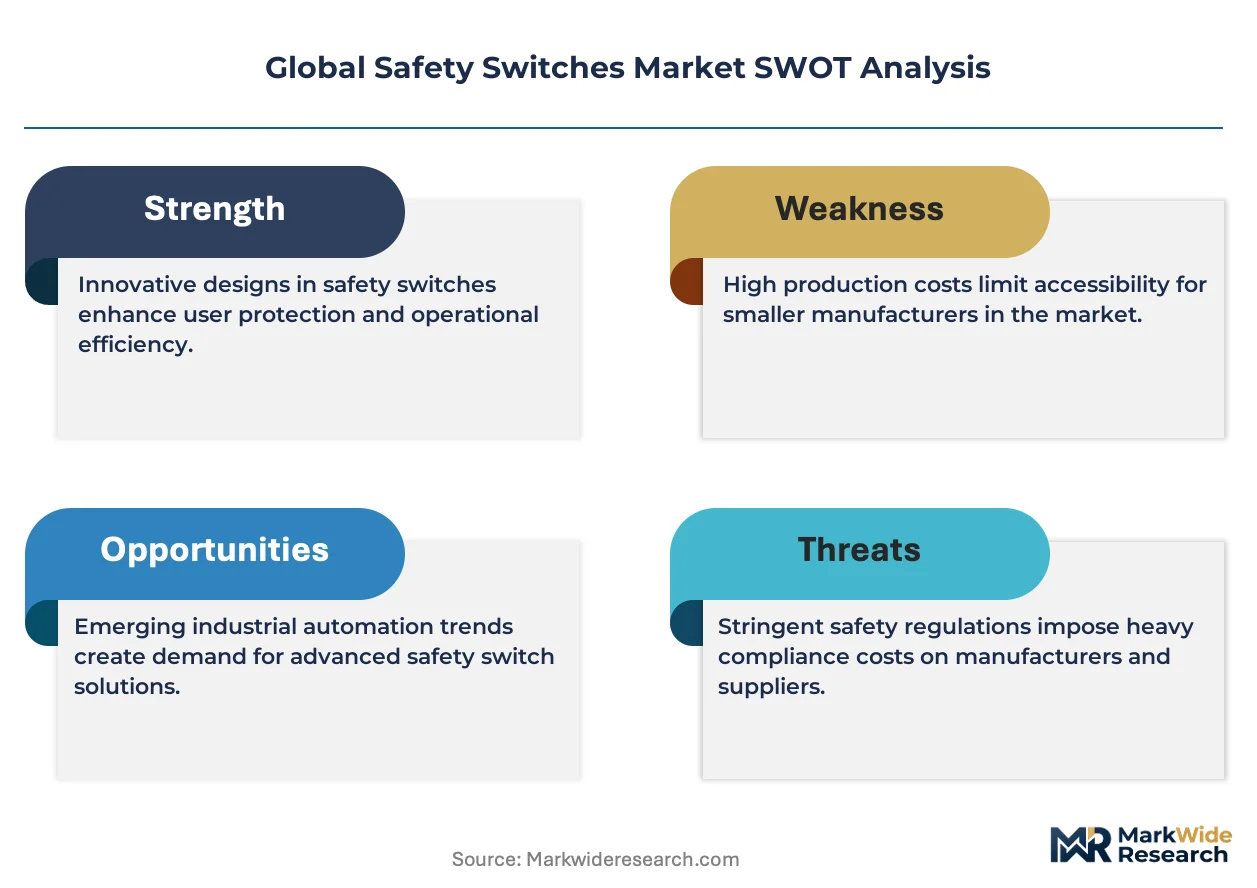
The safety switches market is experiencing structural pressure from semiconductor-enabled diagnostic capabilities that are fragmenting traditional electromechanical architectures into distributed sensor networks. This technological decomposition is forcing vendors to reconfigure R&D allocation between proven relay-based platforms and solid-state alternatives with predictive maintenance integration.
Growth Catalysts
- Wind turbine OEM specifications:Offshore wind developers in the North Sea basin mandate SIL 3-rated interlocks for nacelle access platforms, driving specification upgrades across supplier tiers.
- OSHA 1910.147 enforcement intensity:US manufacturing inspectors are expanding lockout-tagout violation penalties, compelling facility managers to replace aging keyed switches with trapped-key systems.
- EU Machinery Directive 2006/42/EC recertification cycles:European machinery retrofit programs are accelerating replacement demand as legacy equipment faces compliance deadlines.
Market Restraints
- Semiconductor input volatility:Safety relay ASICs and microcontrollers face allocation uncertainty from Taiwan-based foundry concentration, compressing electronic switch margins.
- Electromechanical durability threshold:Heavy contamination environments in mining and steel processing limit solid-state penetration due to thermal cycling failures.
- Certification fragmentation:Divergent contact block specifications between IEC 60947-5-1 and UL 508 create dual-testing burdens for transatlantic vendors.
Strategic Opportunities
- India industrial corridor buildout:Dedicated freight corridors and smart city manufacturing zones under PLI scheme incentives represent underpenetrated demand for safety interlock infrastructure.
- Solar farm wireless integration:Distributed photovoltaic installations require compact wireless safety nodes eliminating trenching costs for hardwired E-stop circuits.
- CE-MDR convergence with functional safety:Medical device machinery safety standards are tightening, opening specification windows for SIL-certified switches in pharmaceutical packaging lines.
Industry Challenges
- Functional safety engineering scarcity:TÜV-certified safety system designers command premium compensation, constraining vendor expansion velocity.
- Legacy PLC integration friction:Brownfield chemical processing plants face reconfiguration costs when retrofitting hardwired safety zones to programmable architectures.
- Multi-jurisdiction certification timelines:Parallel UL, CE, and CCC approval processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Safety Switches Market |
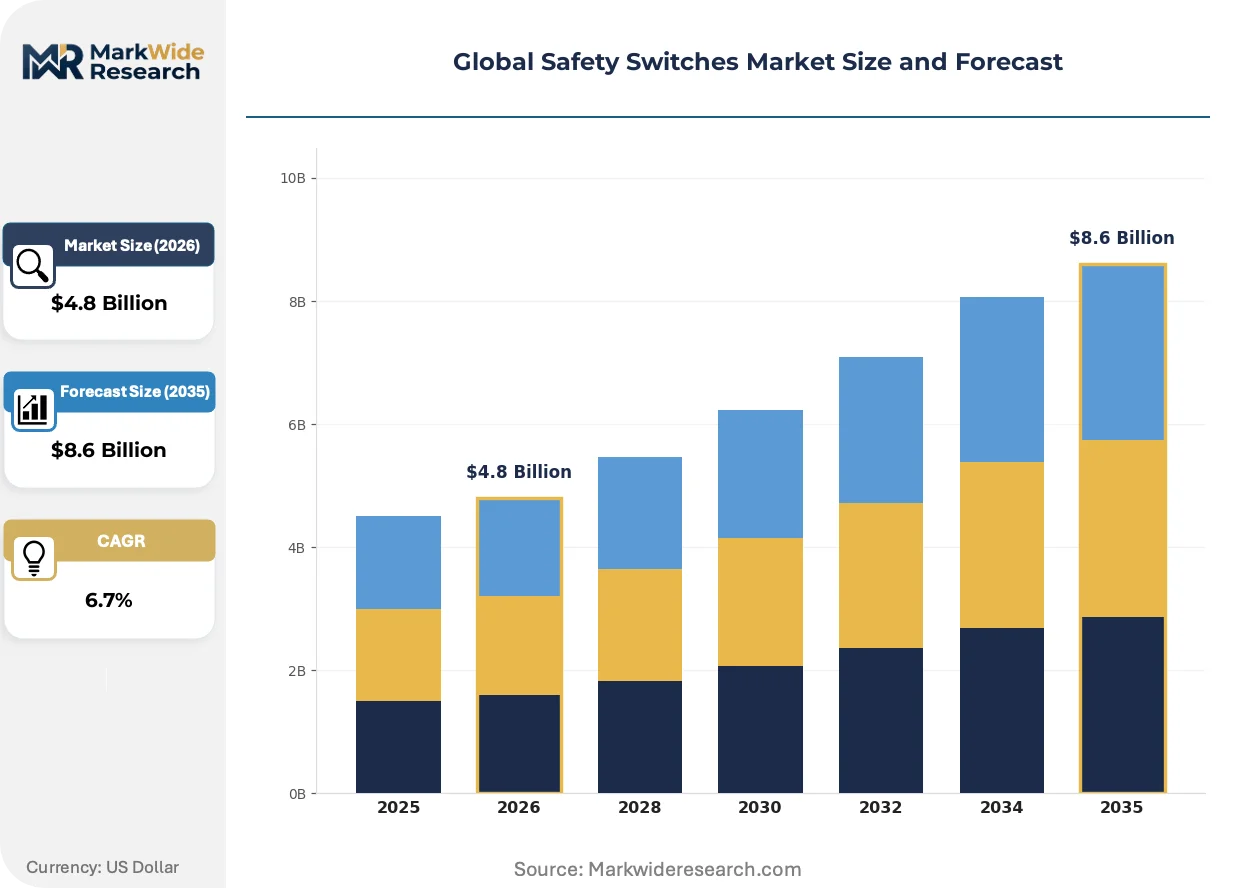
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Electronic, Thermal, Magnetic, Pneumatic Application: Manufacturing Plants, Chemical Processing, Food & Beverage, Mining Operations, Power Plants End User: Oil & Gas Firms, Construction Companies, Heavy Equipment Operators, Renewable Energy Firms, Warehousing Facilities Technology: Programmable Logic Control, Relay-based, Motor Operated, Wireless, Manual |
| Companies Covered | Schneider Electric, Rockwell Automation, Siemens AG, ABB, Omron Corporation, Honeywell International, SICK AG, Eaton, Pilz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Safety Switches Market Shifts & Advancements
Solid-state safety technology is fragmenting established competitive positions by enabling predictive diagnostics that electromechanical platforms cannot replicate. This capability divergence is compressing replacement cycles and redistributing value capture toward semiconductor-integrated suppliers.
Intelligent safety relays with integrated IO-Link connectivity are decomposing traditional hardwired safety architectures into distributed, reconfigurable node networks. Automotive battery gigafactories in Germany and Hungary are specifying these platforms for flexible cell assembly lines. The technology is decomposing the historical premium commanded by dedicated safety PLC systems by embedding logic directly at the sensor level.
China's SAMR enforcement of GB standards is accelerating domestic certification requirements for imported safety components. Foreign suppliers face mandatory in-country testing for electromagnetic compatibility and environmental sealing. European and Japanese vendors are responding by establishing joint venture laboratories in Shanghai to compress approval timelines.
Buyer concentration among renewable energy EPCs is consolidating procurement authority previously dispersed across industrial maintenance departments. Vestas and Siemens Gamesa are centralizing safety component specifications at the corporate engineering level, displacing distributor-led specification influence. This shift is most visible in Danish and Spanish offshore wind supply chains where turbine platform standardization dominates sourcing decisions.
Global Safety Switches Market Segmentation
Safety switch procurement channels vary sharply by segment, with industrial distributors dominating electromechanical volumes while system integrators capture electronic and programmable categories. Understanding these flow patterns exposes where margin pools concentrate and which specifications gate market access.
Product Type:
Channel mix splits between distributor-led stocking for legacy electromechanical units and direct OEM specification for semiconductor-integrated platforms.
- Electromechanical:Spring-actuated contact blocks with mechanical latching mechanisms rated for millions of operations in contaminated environments. German automotive stamping plants and US metal fabrication facilities specify these for their tolerance of coolant mist and metal dust, though replacement cycles are lengthening as predictive maintenance defers swap-outs.
- Electronic:Solid-state switching elements with integrated diagnostic feedback and SIL 3 certification capability. Offshore wind turbine OEMs in Denmark and Spain mandate these for nacelle access platforms where remote monitoring reduces technician dispatch costs.
- Thermal:Bimetallic trip elements responding to temperature thresholds in motor protection circuits.
- Magnetic:Reed switch and Hall-effect configurations for position sensing in explosion-proof enclosures.
- Pneumatic:Air-logic safety interlocks for washdown environments in food processing.
By volume, electromechanical leads. By growth pace, electronic is climbing the fastest.
Application:
Cost tier stratification separates premium-specified chemical and power installations from price-sensitive warehousing deployments.
- Manufacturing Plants:General-purpose interlocks on stamping presses, robotic cells, and conveyor systems across discrete automation. German machinery builders and Japanese automotive suppliers drive specification intensity here, with trapped-key architectures proliferating under OSHA enforcement in US facilities.
- Chemical Processing:Explosion-proof and corrosion-resistant switches for batch reactor access and tank farm perimeter control. US Gulf Coast refineries and German BASF/Lanxess complexes require IECEx-certified platforms with stainless steel housings, creating specification barriers for non-specialist vendors.
- Food & Beverage:Hygienic design interlocks with IP69K washdown ratings for dairy and meat processing lines.
- Mining Operations:Heavy-duty limit switches in dragline and conveyor applications with extended temperature ranges.
- Power Plants:Nuclear-qualified and thermal-cycle-resistant switches for turbine hall and containment access.
Chemical processing commands the highest unit margins. Manufacturing plants generate the largest absolute procurement volumes.
End User:
Customer-type concentration shows renewable energy firms consolidating procurement authority while oil and gas maintenance departments fragment purchasing decisions.
- Renewable Energy Firms:Centralized engineering specifications for wind turbine nacelle interlocks and solar farm wireless E-stop networks. Vestas and Siemens Gamesa procurement teams in Denmark and Spain dictate supplier qualification, displacing distributor influence seen in legacy industrial segments.
- Oil & Gas Firms:Legacy trapped-key and keyed switch installations on offshore platforms and pipeline compressor stations. North Sea operators and US Permian Basin facilities face deferred replacement cycles amid capital discipline, though safety incident penalties are accelerating upgrade timelines.
- Construction Companies:Temporary and portable interlock systems for crane and hoist applications.
- Heavy Equipment Operators:OEM-fit and aftermarket replacement for mining and earthmoving machinery.
- Warehousing Facilities:Cost-optimized limit switches for automated storage and retrieval systems.
Renewable energy firms are gaining share fastest in new specification authority. Oil and gas retains the largest installed base requiring replacement.
Technology:
Maturity gradients separate declining relay-based architectures from ascending programmable and wireless platforms.
- Programmable Logic Control:Safety-certified controllers with configurable logic and network integration for flexible manufacturing. German automotive battery gigafactories and Hungarian cell assembly plants specify these for reconfigurable production lines where batch sizes shift frequently.
- Relay-based:Hardwired safety circuits with electromechanical force-guided contacts in legacy installations. Brownfield chemical plants in the US Rust Belt and European industrial heartland retain these for their simplicity and technician familiarity, though retrofit costs mount as spare parts obsolesce.
- Motor Operated:Electrically actuated switches for remote isolation in hazardous access zones.
- Wireless:Battery-free energy harvesting and mesh-network safety nodes eliminating trenching in distributed solar farms.
- Manual:Direct-actuated emergency stops and guard door switches for basic machinery protection.
Relay-based technology still dominates unit shipments. Programmable logic control is expanding most quickly in greenfield specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German safety switch manufacturers supply wind turbine OEMs across the North Sea basin, while Chinese producers serve domestic solar farm buildouts under GB standard mandates.
Germany
Offshore wind developers in the North Sea and Baltic Sea mandate SIL 3-rated interlocks for nacelle access platforms, tightening specification tiers across supplier networks. The EU Machinery Directive 2006/42/EC drives recertification cycles for legacy industrial equipment. Bavarian automotive battery gigafactories specify programmable safety controllers for flexible cell assembly lines.
United States
OSHA 1910.147 enforcement expansion elevates demand for trapped-key switch architectures in manufacturing facilities across the Rust Belt and Gulf Coast. The EPA coordinates with state regulators on chemical plant safety inspections, indirectly shaping interlock procurement timelines. Houston-area refineries and Permian Basin compressor stations anchor replacement demand for explosion-proof safety systems.
China
SAMR enforcement of GB standards accelerates domestic certification requirements for electromagnetic compatibility and environmental sealing of imported safety components. The MIIT oversees industrial automation safety integration under national smart manufacturing initiatives. Yangtze River Delta solar farm developers specify wireless safety nodes to eliminate trenching costs in distributed photovoltaic installations.
India
PLI scheme incentives for dedicated freight corridors and smart city manufacturing zones generate underpenetrated demand for safety interlock infrastructure. The BIS tightens conformity assessment procedures for industrial electrical equipment imports. Gujarat and Maharashtra industrial corridors attract safety component joint ventures as foreign vendors establish localized testing laboratories.
Denmark
Vestas centralized procurement specifications displace distributor influence in offshore wind supply chains, consolidating vendor qualification authority at corporate engineering levels. The Danish Maritime Authority enforces nacelle access safety standards for North Sea installations. Copenhagen and Esbjerg serve as specification hubs for turbine platform standardization across European markets.
Global Safety Switches Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and semiconductor integration capabilities. The vendor base splits between diversified electrical conglomerates with captive safety divisions and focused component specialists serving niche contamination or wireless applications. Three archetypes dominate: relay-based legacy platforms, solid-state diagnostic-enabled systems, and programmable logic controllers with distributed I/O architectures. M&A activity concentrates on semiconductor-enabled safety relay capabilities, while strategic partnerships target localized certification laboratory access in China and India.
Within the diversified electrical conglomerate tier, Schneider Electric, Siemens AG, and Rockwell Automation occupy positions that exemplify distinct competitive vectors. Schneider Electric represents the European programmable safety controller specialist with renewable integration project concentration. Siemens AG anchors German industrial automation heritage through captive semiconductor production capabilities. Rockwell Automation exemplifies North American factory automation platform extension into compact wireless safety nodes for distributed energy applications.
| Leading Market Players |
|---|
| Schneider Electric |
| Rockwell Automation |
| Siemens AG |
| ABB |
| Omron Corporation |
| Honeywell International |
| SICK AG |
| Eaton |
| Pilz |
| Others |
Supply & Pricing Matrix
Capacity utilization at Taiwanese semiconductor foundries directly shapes component availability and price floors for electronic safety switches, compressing margins for relay-dependent vendors while rewarding captive silicon production. German and Japanese manufacturers leverage in-house fabrication to insulate pricing power from allocation volatility that disrupts fabless competitors.
Pricing Analysis
Electronic-to-electromechanical pricing gaps currently span three generations: legacy relay platforms occupy economy tiers, solid-state diagnostic units command mid-market premiums, and programmable safety controllers with IO-Link integration anchor premium positioning. Price differentiation hinges on SIL certification grade and semiconductor content density. Cost compression in electromechanical tiers is intensifying because Chinese producers are scaling GB-certified output for domestic solar farm demand. Warehousing facilities exhibit highest price sensitivity, while North Sea offshore wind developers show lowest sensitivity due to specification lock-in by Vestas and Siemens Gamesa engineering teams.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for semiconductor-dependent safety relay producers. Manufacturing concentrates in Germany, Japan, and China, with Taiwanese foundries supplying ASICs and microcontrollers. Raw material dependencies include silver-palladium contact alloys, epoxy molding compounds, and rare-earth magnets for Hall-effect sensors. Single-source vulnerability at TSMC and Samsung Foundry nodes creates allocation risk for electronic switch vendors. Distribution runs through industrial distributors for legacy electromechanical volumes and direct OEM specification for programmable platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TÜV-certified functional safety engineers command compensation premiums that constrain vendor expansion velocity, creating a binding capability gap across the value chain. This scarcity reshapes competitive boundaries between semiconductor-integrated suppliers and relay-dependent incumbents.
For Market Incumbents: Consolidate certification depth by acquiring SIL 3 validation capabilities in renewable energy applications, where Vestas and Siemens Gamesa procurement teams are displacing distributor influence. Deepen backward integration into semiconductor fabrication or secure long-term foundry offtake agreements to defend margins against allocation volatility from Taiwan-based concentration. For New Entrants and Emerging Players: Anchor in India's PLI-funded industrial corridor buildout, where dedicated freight corridors and smart city manufacturing zones remain underpenetrated by established safety interlock infrastructure. Target wireless safety node specifications for distributed solar farms in the Yangtze River Delta, leveraging energy-harvesting architectures to eliminate trenching cost disadvantages against hardwired competitors. For Investors and Strategic Acquirers: Semiconductor-enabled safety relay specialists with predictive maintenance integration represent the most defensible acquisition archetype for the projection horizon. Watch for inflection signals in automotive battery gigafactory specification wins, where German and Hungarian cell assembly plants are mandating programmable safety controllers for flexible production lines.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Fabrication | Insulates margin stability from TSMC allocation volatility affecting fabless competitors. |
| TÜV Certification Laboratory Joint Ventures | Compresses 8-14 month approval timelines for China and India market access. |
| Wireless Safety Node Development | Eliminates trenching costs for solar farm E-stop circuits specified by Yangtze River Delta developers. |
| Renewable Energy EPC Partnerships | Secures specification authority as Vestas and Siemens Gamesa centralize procurement decisions. |
| Predictive Maintenance Platform Integration | Captures value from diagnostic capabilities that electromechanical platforms cannot replicate. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with safety system designers, plant engineers at automotive and chemical facilities, renewable energy EPC procurement leads, and industrial distributor category managers; and secondary validation through IEC 60947-5-1 certification databases, OSHA enforcement records, SAMR GB standard filings, and customs trade data for safety component imports. Bottom-up triangulation against top-down market sizing cross-validated segment-level demand estimates.
Across the analysis window, the forecasting framework modeled demand by product type, application severity tier, end-user procurement concentration, and technology maturity gradient. CAGRs were derived from segment-level growth differentials weighted by installed base replacement cycles and greenfield specification velocity. Industry-specific inputs included offshore wind turbine OEM safety specifications, OSHA 1910.147 enforcement intensity indices, and solar farm wireless node adoption curves.
Underlying assumptions cover continued semiconductor allocation constraints, stable IEC and OSHA regulatory enforcement trajectories, and renewable energy capacity expansion plans, with deviation risk concentrated in Taiwan foundry disruption scenarios or Machinery Directive recertification deadline shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
India Reed Sensors Switches Market
Switches
Intelligent Power Switches Market
Switches
Dual Power Transfer Switches Market
Switches
Reed Switches Sensors Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Molded Case Circuit Breaker Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Fusible Switches Market
Switches
Smart Pole-Mounted Switch Market
Switches
Pressure Switch Market
Switches
Global Disconnector Switch Market
Switches
United States Circuit Breaker Market
Switches
Timer Switch Socket Market
Switches
Off-Road Machine Ruggedized Switch and Indicator Systems Market
Switches
DC Circuit Breaker Market
Switches
5G Electromechanical RF Switch Market