
 Sensor Screwdrivers Market | 2026-2036
Sensor Screwdrivers Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Screwdrivers Market Analytics
Specialized industrial distribution is narrowing as direct-to-factory channels gain share in precision tool procurement. Hakko Corporation leverages its soldering-equipment heritage to cross-sell sensor screwdrivers into electronics contract manufacturers. Atlas Copco dominates pneumatic tightening systems through captive distribution in European automotive plants. Wiha Tools sustains premium positioning in hand-tool retail by limiting overlap with automated product lines.
Sensor screwdrivers integrate torque transducers, angle encoders, and microprocessors to deliver closed-loop feedback during fastening operations, with typical accuracy ranging from ±1% to ±5% of set torque depending on sensor class. These instruments verify joint integrity in real time, eliminating post-assembly inspection steps in critical applications. Electric sensor screwdrivers lead unit shipments across automated assembly lines, while Bluetooth-enabled models represent the fastest-growing technology subset as plant-floor data collection requirements intensify. Aerospace maintenance applications command the highest margin pools due to certification burdens and low-volume, high-precision demand.
FDA quality system regulations shape medical device assembly requirements in the United States, while CE marking and the EU Machinery Directive govern market access across European member states. Japan's METI promotes factory automation standards that embed torque traceability into automotive supplier audits. Stakeholders must weigh interoperability standards against proprietary data architectures when selecting connected tooling platforms.
Market Dynamics
Electronics contract manufacturers in East Asia are consolidating their assembly tool specifications around closed-loop feedback systems, forcing precision tool vendors to embed torque transducers and wireless connectivity as baseline features rather than premium upgrades.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for torque-controlled fastening in automotive assembly plants are accelerating sensor screwdriver deployment across German supplier networks.
- Bluetooth-enabled data logging:Real-time joint verification is eliminating post-assembly inspection steps in medical device manufacturing facilities subject to FDA quality system regulations.
- Japan METI factory automation standards:Torque traceability requirements embedded in automotive supplier audits are pulling sensor-equipped tools into tier-2 and tier-3 component factories.
Market Restraints
- Precision sensor cost volatility:Strain gauge and MEMS transducer supply concentrates among Japanese and German component specialists, exposing assemblers to input price swings.
- REACH substance restrictions:ECHA compliance for electronics-grade lubricants and coatings in precision gearboxes is tightening material qualification timelines and limiting qualified supplier pools.
- Pneumatic system installed base:Atlas Copco and Desoutter pneumatic tightening systems in mature European automotive plants create switching friction against full electric sensor screwdriver conversion.
Strategic Opportunities
- Aerospace maintenance, repair, and overhaul:Low-volume, high-precision fastening in aircraft component shops commands margin premiums due to FAA and EASA certification burdens that deter commodity competitors.
- India PLI scheme for electronics manufacturing:Production-linked incentives for mobile phone and component assembly are creating first-mover advantage for tool vendors establishing local calibration and service infrastructure.
- Cloud-native tool management platforms:Convergence of sensor screwdrivers with enterprise asset management software is enabling predictive maintenance contracts that capture recurring revenue beyond hardware sales.
Industry Challenges
- Metrology technician scarcity:Torque calibration and sensor validation require specialized skills that outpace vocational training pipeline output in expanding manufacturing regions.
- ISO 5393 and ISO 6789 certification timelines:Third-party validation for accuracy classes stretches 12-18 months, delaying product launches and freezing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Screwdrivers Market |
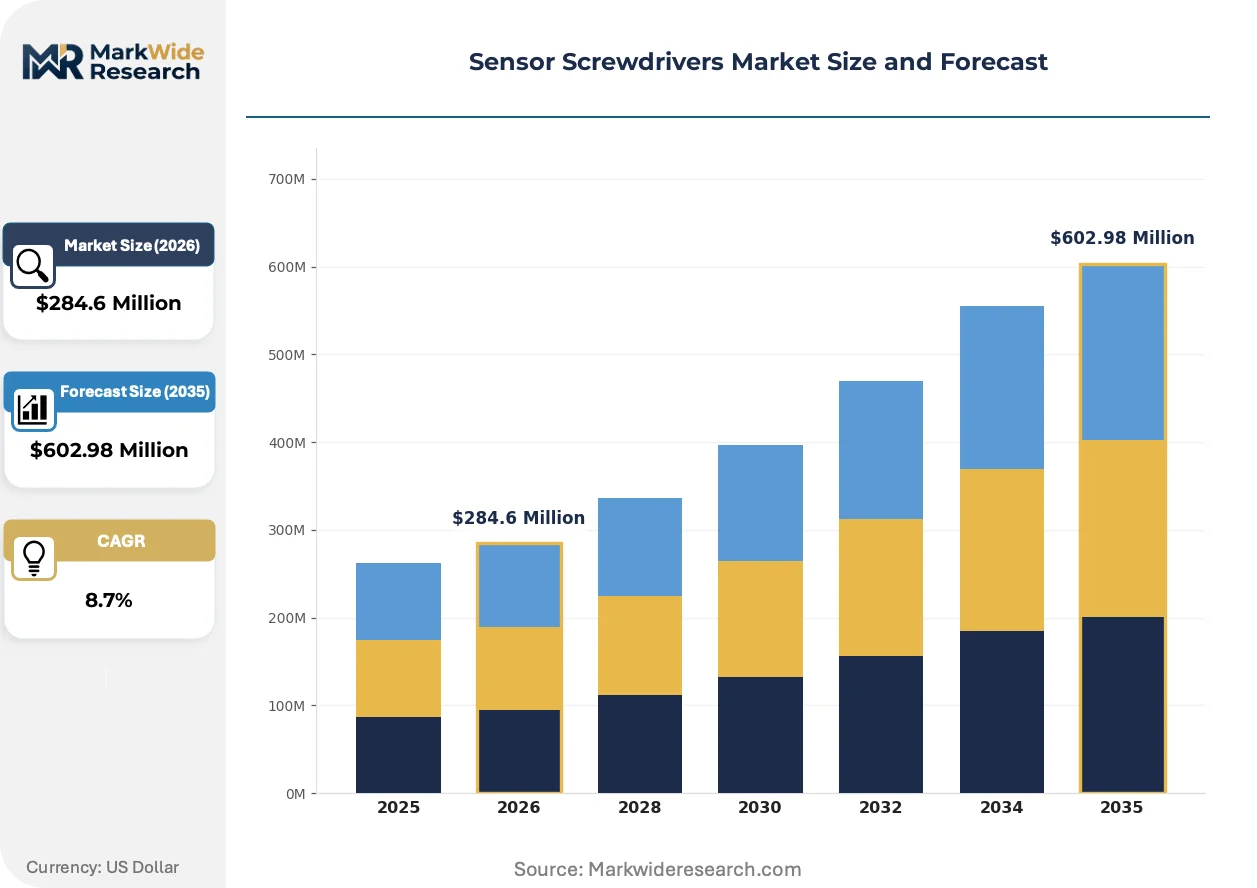
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $602.98 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic, Electric, Hydraulic, Pneumatic End User: Manufacturing, Electronics, Automotive, Aerospace Technology: Smart Sensors, Bluetooth, IoT, Wireless Application: Automated Assembly, Maintenance, Repair, Inspection |
| Companies Covered | Hakko Corporation, Wiha Tools, Desoutter Industrial Tools, Atlas Copco, Mountz Torque, SMAC Corporation, WEBER Screwdriving Systems, DEPRAG SCHULZ, Kilews Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Screwdrivers Market Evolving Landscape
Wireless connectivity protocols and edge computing architectures are compressing the latency between fastening execution and quality system documentation, reshaping how assembly operations integrate precision tooling into digital thread infrastructures.
Multi-axis force-torque sensors with embedded microprocessors are collapsing the distinction between handheld assembly tools and automated tightening stations. Electronics manufacturers in South Korea and Taiwan are adopting these hybrid units for mixed-model lines where batch sizes shift hourly. The technology is collapsing capital expenditure thresholds for small-batch precision assembly, enabling contract manufacturers to compete for aerospace and medical device work previously reserved for dedicated automation cells.
REACH authorization requirements for chromium trioxide in surface treatments are tightening supply chains for precision screwdriver bits and sockets. German automotive suppliers are accelerating qualification of alternative coating chemistries to maintain CE marking compliance. The regulatory pressure is compressing supplier development cycles and favoring tool vendors with captive metallurgical laboratories capable of rapid coating validation.
Direct procurement relationships between sensor screwdriver vendors and tier-1 electronics assemblers are displacing traditional industrial distribution channels. Contract manufacturers in Shenzhen and Suzhou are negotiating enterprise-wide tool standards with preferred vendors, consolidating purchasing authority previously fragmented across plant-level maintenance departments. The channel shift is most visible in consumer electronics assembly, where volume concentration at Foxconn and Luxshare facilities creates negotiating leverage unavailable to smaller regional distributors.
Sensor Screwdrivers Market Segmentation
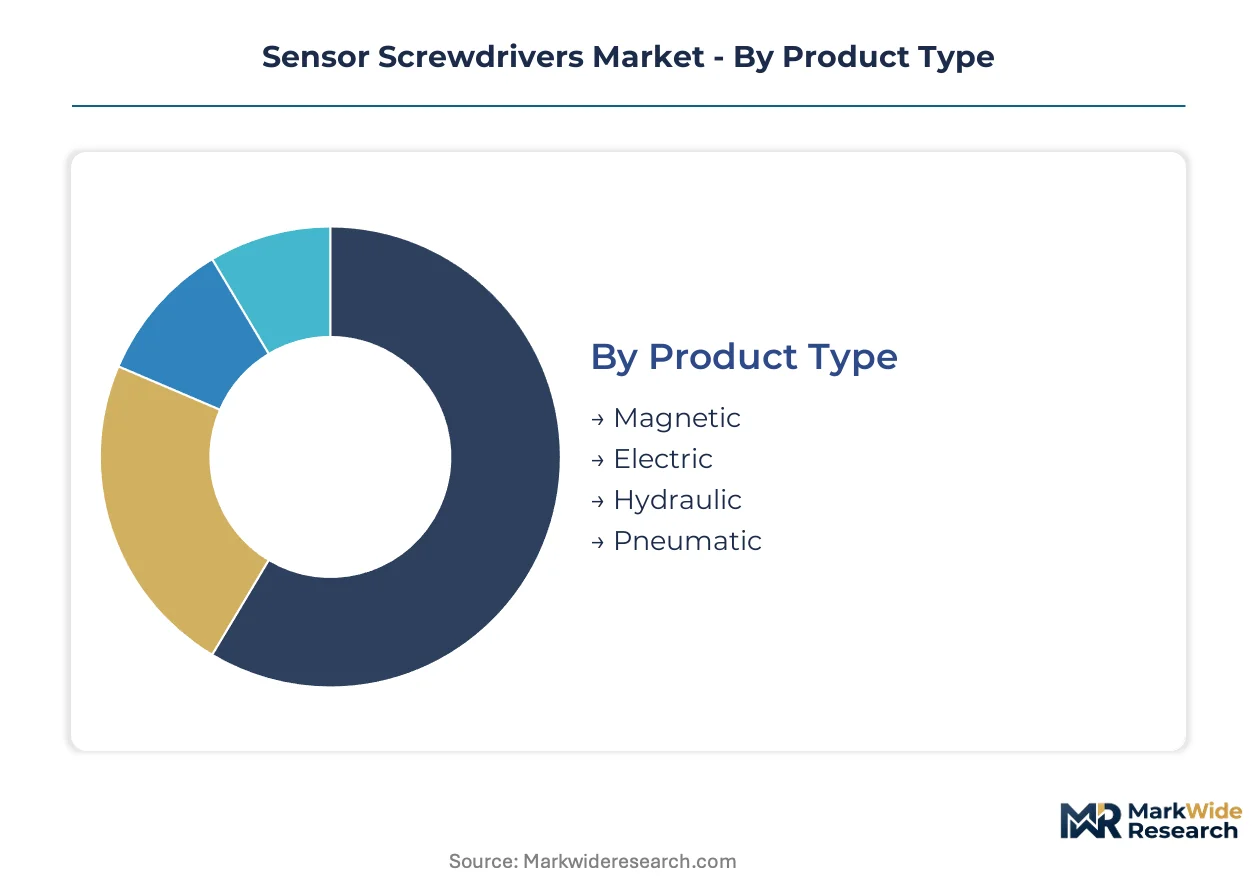
Sensor screwdriver segmentation reveals how torque precision requirements fragment across power sources, connectivity protocols, and operational environments. Each dimension carries distinct margin structures and certification burdens that reshape vendor specialization.
Product Type:
Mature pneumatic systems dominate automotive legacy installations while electric platforms capture electronics automation investments.
- Electric:Brushless DC motors paired with strain gauge transducers deliver ±1% torque accuracy for medical device and consumer electronics assembly. Demand clusters in Shenzhen and Suzhou contract manufacturing campuses where CE marking compliance accelerates replacement of pneumatic legacy systems.
- Pneumatic:Compressed-air tightening systems with basic torque shut-off valves retain installed base across German automotive supplier plants. METI traceability standards in Japan and EU Machinery Directive mandates are forcing gradual displacement despite capital sunk in Atlas Copco and Desoutter fleet infrastructure.
- Magnetic:Rare-earth magnet clutch mechanisms provide cost-effective torque limiting for low-volume assembly operations without sensor feedback loops.
- Hydraulic:Oil-pressure multiplication systems serve heavy fastening applications in construction equipment and agricultural machinery assembly where electric motor torque density falls short.
Electric retains volume leadership; Bluetooth-enabled electric variants hold the steepest expansion curve.
End User:
Customer concentration patterns split between high-volume contract manufacturers and low-volume certified maintenance operations.
- Electronics:Foxconn, Luxshare, and Pegatron facilities in Taiwan and mainland China specify closed-loop torque verification for smartphone and laptop assembly. FDA quality system regulations for medical device subcontractors in Minnesota and Massachusetts pull identical tool specifications into North American electronics manufacturing.
- Aerospace:FAA and EASA certification requirements for torque tool calibration create margin premiums that sustain specialized distributors serving Boeing, Airbus, and tier-1 component shops in Wichita and Toulouse.
- Automotive:German supplier belt operations from Stuttgart to Wolfsburg deploy sensor screwdrivers for powertrain and chassis assembly under KBA type approval frameworks.
- Manufacturing:General industrial assembly across machinery, appliance, and furniture production represents price-sensitive volume requiring basic torque control without data logging.
Electronics commands absolute unit volume; aerospace delivers the highest margin realization per tool.
Technology:
Connectivity architecture choices determine integration depth with factory information systems and predictive maintenance platforms.
- Bluetooth:Low-energy wireless protocols enable real-time torque-angle data streaming to plant-floor MES systems without cable tethering. South Korean electronics manufacturers in Gyeonggi Province deploy these for mixed-model lines where batch sizes shift hourly.
- Smart Sensors:Embedded microprocessors with edge computing capability collapse latency between fastening execution and quality documentation, satisfying FDA 21 CFR Part 11 electronic record requirements for medical device assembly.
- IoT:Cloud-connected tool management platforms aggregate usage telemetry across distributed factory networks, enabling predictive calibration scheduling and spare parts logistics.
- Wireless:Proprietary radio frequency protocols in legacy installations precede Bluetooth standardization and persist in captive automotive plant networks.
Smart Sensors anchor current procurement specifications; IoT-enabled platforms are climbing the fastest as enterprise asset management convergence accelerates.
Application:
Operational context dictates accuracy class requirements and the economic viability of sensor-equipped tooling versus manual alternatives.
- Automated Assembly:Fixed-position electric nutrunners with multi-axis force-torque sensors execute precision fastening in dedicated cells for automotive powertrain and medical device production. CE marking and ISO 5393 accuracy class validation stretch 12-18 month procurement cycles.
- Maintenance:Handheld sensor screwdrivers with data logging support aircraft MRO operations where FAA repair station regulations mandate torque traceability for critical fasteners.
- Repair:Field service applications prioritize portability and battery endurance over absolute accuracy, accepting ±5% torque tolerance classes.
- Inspection:Post-fastening torque audit tools verify joint integrity without driving function, serving quality assurance sampling protocols in electronics contract manufacturing.
Automated Assembly generates the revenue base; Maintenance applications are gaining share fastest as fleet retrofit cycles extend tool service lives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's automotive supplier belt dominance in precision tooling demand. Shenzhen's Yantian International Container Terminal anchors East Asian electronics contract manufacturing concentration. Kobe Port's Ro-Ro facilities support Japan's METI factory automation standards dissemination.
Germany
Stuttgart-to-Wolfsburg automotive supplier networks deploy sensor screwdrivers for powertrain assembly under KBA type approval frameworks. REACH authorization requirements for chromium trioxide in surface treatments compress supplier development cycles. Bavarian precision tool vendors maintain captive metallurgical laboratories for rapid coating validation.
China
Shenzhen and Suzhou contract manufacturing campuses specify closed-loop torque verification for smartphone assembly. MIIT factory automation standards embed traceability requirements into supplier audits. Yangtze River Delta electronics clusters consolidate purchasing authority with preferred tool vendors.
United States
Minnesota and Massachusetts medical device subcontractors pull sensor screwdriver specifications under FDA quality system regulations. FAA repair station regulations mandate torque traceability for aircraft MRO operations in Wichita. Pacific Northwest electronics assembly maintains interoperability standards against proprietary data architectures.
Japan
METI torque traceability requirements pull sensor-equipped tools into tier-2 and tier-3 automotive component factories. Chubu region machine tool builders integrate multi-axis force-torque sensors for mixed-model production lines. Kansai-based strain gauge specialists concentrate transducer supply.
South Korea
Gyeonggi Province electronics manufacturers deploy Bluetooth-enabled screwdrivers for hourly batch-size shifts. MFDS medical device regulations mirror FDA quality system requirements for assembly tool specifications. Seoul Capital Area contract manufacturers negotiate enterprise-wide tool standards.
Sensor Screwdrivers Market Competitive Landscape
On the supply side, the industry is tiered between captive pneumatic system incumbents and emerging electric platform specialists. Consolidation pressure concentrates among Japanese and German component specialists controlling strain gauge and MEMS transducer supply. Two strategic archetypes dominate: soldering-equipment heritage vendors cross-selling into electronics assembly, and pneumatic tightening system incumbents defending installed base through fleet service contracts. Competitive moves center on direct-to-factory channel establishment and cloud-native tool management platform development.
Among Japanese precision equipment specialists, Hakko Corporation exemplifies the cross-selling archetype leveraging soldering-equipment heritage. Atlas Copco anchors the pneumatic incumbent tier with European automotive plant captive distribution. Wiha Tools occupies premium hand-tool positioning by limiting automated product line overlap. These three represent divergent strategic responses to electric platform displacement pressure.
| Leading Market Players |
|---|
| Hakko Corporation |
| Wiha Tools |
| Desoutter Industrial Tools |
| Atlas Copco |
| Mountz Torque |
| SMAC Corporation |
| WEBER Screwdriving Systems |
| DEPRAG SCHULZ |
| Kilews Industrial |
| Others |
Value Network & Pricing Analysis
The Port of Hamburg's container throughput cost dynamics compress margin structures for German precision tool vendors sourcing Japanese strain gauge transducers, while tier-1 electronics assemblers in Shenzhen exploit volume concentration to extract pricing concessions that ripple upstream through captive metallurgical laboratories.
Pricing Analysis
Volume-discount tiering structures separate aerospace maintenance operators paying certification-grade premiums from electronics contract manufacturers negotiating enterprise-wide fleet pricing. Pricing stratifies across FDA-validated medical device tiers, CE-marked automotive supplier specifications, and basic industrial assembly grades. Cost compression in standard electric platforms intensifies as Foxconn and Luxshare consolidate purchasing authority. Electronics contract manufacturers exhibit highest price sensitivity; aerospace MRO operations accept premium positioning due to FAA and EASA calibration burdens.
Supply Chain Analysis
Upstream feedstock dependencies center on Japanese and German strain gauge specialists, Chinese rare-earth magnet suppliers, and Bavarian metallurgical coating laboratories. MEMS transducer fabrication concentrates in Japan's Chubu region and southern Germany. Single-source vulnerability in precision sensor supply exposes assemblers to input price volatility when METI or REACH compliance timelines compress. Distribution runs through direct-to-factory channels displacing traditional industrial distributors in East Asian electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors controlling scarce metrology technician pipelines and captive calibration infrastructure, while punishing pure hardware plays lacking service attachment.
For Market Incumbents: Harden defensive moats by deepening backward integration into strain gauge transducer supply and securing exclusive service contracts with German automotive supplier networks. Atlas Copco and Desoutter pneumatic fleet infrastructure faces displacement pressure from METI traceability mandates; incumbents must accelerate electric platform certification investment to retain KBA type approval positioning. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing presents underpenetrated territory where first-mover calibration infrastructure investment captures production-linked incentive beneficiaries. Target tier-2 automotive component factories in Maharashtra and Tamil Nadu with Bluetooth-enabled tool platforms bundled with predictive maintenance software subscriptions. For Investors and Strategic Acquirers: Precision tool vendors with captive metallurgical laboratories and rapid REACH coating validation capabilities offer durable acquisition value. Long-term viability hinges on cloud-native tool management platform development and recurring revenue attachment rates. Watch for inflection when enterprise asset management software vendors announce native sensor screwdriver integration partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transducer Supply | Captive strain gauge sourcing insulates Japanese and German vendors from MEMS component price volatility. |
| Cloud-Native Tool Management Platform Launch | Predictive calibration scheduling transforms hardware vendors into recurring revenue service providers. |
| REACH Alternative Coating Qualification | Rapid metallurgical validation maintains CE marking access as ECHA chromium trioxide restrictions tighten. |
| Direct-to-Factory Channel Establishment | Shenzhen and Suzhou enterprise-wide tool standards displace fragmented plant-level procurement. |
| Aerospace MRO Certification Investment | FAA and EASA repair station approvals capture margin premiums unavailable to commodity competitors. |
Research Methodology
A spread of perspectives from plant engineers at electronics contract manufacturers, procurement leads at German automotive suppliers, metrology technicians at calibration laboratories, and aftermarket service heads at precision tool vendors converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings, customs and trade data, FDA quality system guidance documents, and METI factory automation standards. Bottom-up unit shipment estimates triangulated against top-down value projections across power source, connectivity protocol, and end-use segmentation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include power source architecture, connectivity technology tier, and end-use industry vertical. CAGRs derived from historical shipment trajectories adjusted for regulatory mandate acceleration and channel structure displacement. Industry-specific forecast inputs incorporated ISO 5393 and ISO 6789 certification timeline assumptions and REACH substance restriction phase-in schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native platform entrants or battery-electric vehicle-driven automotive retooling would shift outcomes. Cross-checking against IHS Markit vehicle production databases and MIIT electronics manufacturing statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Thermistor Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market