
 Africa Dairy Protein Market | 2026-2036
Africa Dairy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Dairy Protein Market Outlook
The gap between premium isolate grades and commodity whole milk powder is rebalancing as African processors upgrade nutritional labeling and export readiness. Fonterra Co-operative Group Limited leverages its New Zealand-Africa shipping lanes to sustain consistent whey volumes into Nigerian and Kenyan ports. Arla Foods Ingredients Group P/S anchors its position through specialized fractionation capabilities that serve pharmaceutical-grade casein demand. Lactalis Ingredients competes aggressively on powder blending services tailored to North African dairy cooperatives.
Africa dairy protein encompasses whey, casein, milk protein concentrates, and whole milk powders extracted through membrane filtration, acid precipitation, or spray-drying, typically standardized to protein contents ranging from 34% to 90% depending on functional application in food fortification, sports recovery, and clinical nutrition. Whey protein isolates command premium positioning due to their leucine density and rapid absorption profiles, while milk protein concentrates occupy expanding mid-tier demand from bakery and confectionery manufacturers seeking emulsion stability without full isolate cost. Casein protein retains structural importance in cheese analog production and sustained-release nutritional supplements, though its slower digestion limits penetration in immediate post-workout formulations.
South Africa's Department of Health enforces mandatory food fortification standards that directly shape protein content claims on packaged goods, while Kenya's Kenya Bureau of Standards and Nigeria's National Agency for Food and Drug Administration and Control administer import testing protocols that filter out substandard concentrate shipments. The African Continental Free Trade Area rules of origin provisions are gradually recalibrating where regional blending versus direct import proves more cost-efficient. Stakeholders must monitor which national regulators adopt harmonized CODEX protein measurement methods versus maintaining idiosyncratic local tests that fragment compliance costs.
Market Dynamics
Membrane filtration infrastructure expansion across East African processing hubs is compressing the cost gap between whey concentrates and isolates, forcing legacy spray-drying operations to upgrade or exit.
Growth Catalysts
- South Africa's food fortification mandate:The Department of Health mandates protein enrichment in maize meal and wheat flour, creating guaranteed offtake for milk protein concentrates among domestic millers.
- Urban fitness culture maturation:Gym chains in Nairobi, Lagos, and Johannesburg are expanding private-label sports nutrition lines, pulling whey isolate volumes through direct procurement channels.
- Membrane filtration scale-up:Reverse osmosis and ultrafiltration installations at Kenyan and Nigerian dairy cooperatives are raising local protein fractionation yields without full isolate plant capital.
Market Restraints
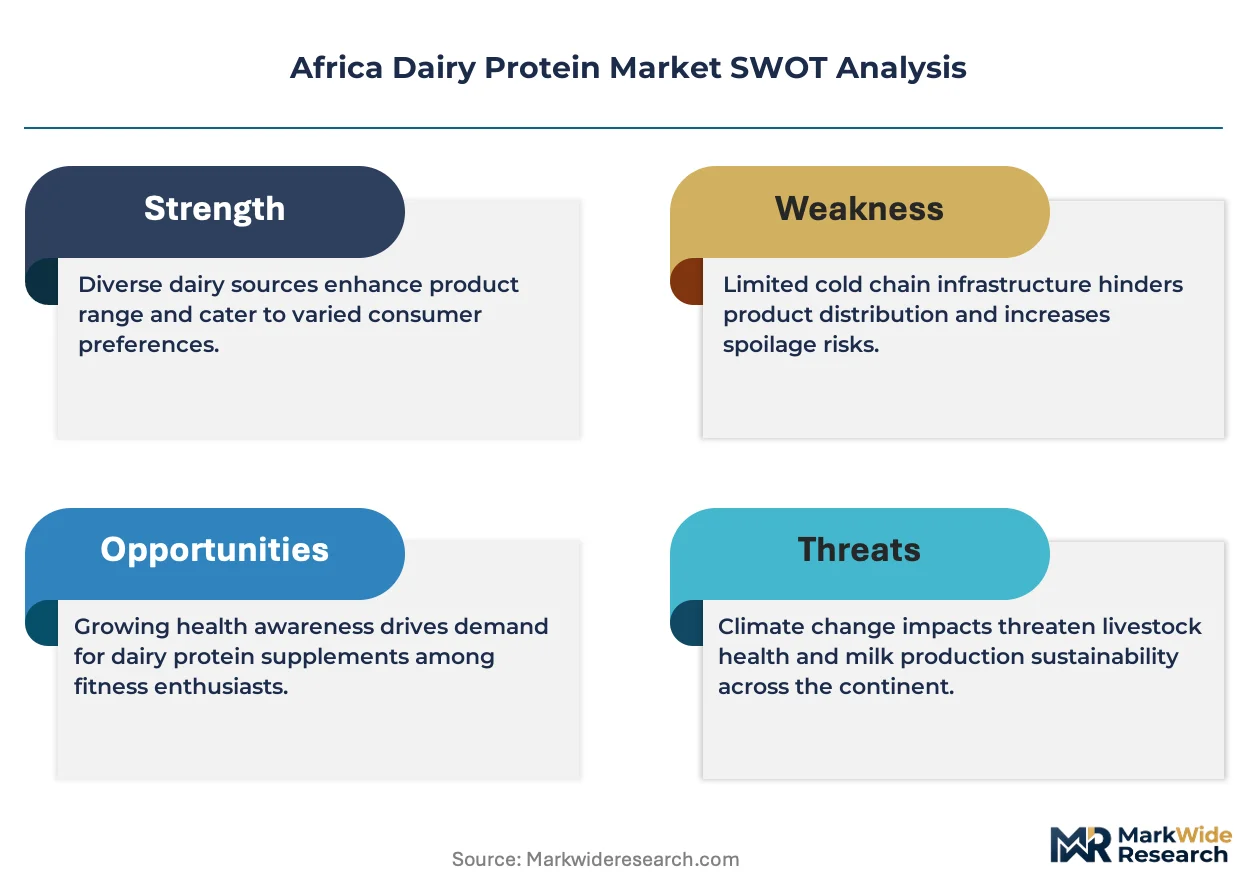
- Import dependency for starter cultures:African processors rely on European and New Zealand suppliers for whey protein isolate feedstock, exposing margins to freight rate volatility and currency fluctuation.
- Technical limitation in casein functionality:Sustained-release properties of micellar casein limit formulation flexibility in immediate-recovery sports drinks, capping penetration in post-workout segments.
- Regulatory fragmentation across the African Continental Free Trade Area:Divergent protein measurement protocols between Kenya Bureau of Standards and Nigeria's National Agency for Food and Drug Administration and Control raise compliance costs for cross-border shipments.
Strategic Opportunities
- Underpenetrated Ethiopian market:Addis Ababa's nascent dairy processing corridor lacks indigenous protein fractionation capacity, creating first-mover positioning for membrane technology licensors.
- Pharmaceutical-grade casein demand:Clinical nutrition manufacturers in South Africa and Egypt are sourcing native micellar casein for enteral feeding formulations, opening premium pricing tiers above commodity food-grade material.
- Direct-to-gym distribution channels:Independent fitness centers in Ghana and Côte d'Ivoire are bypassing traditional wholesale distributors through bulk purchasing cooperatives, compressing margin capture for intermediaries.
Industry Challenges
- Skilled technician scarcity:Membrane filtration system operation and maintenance expertise remains concentrated in South Africa and Kenya, constraining plant uptime at newer Nigerian and Tanzanian installations.
- Certification timeline compression:Hazard Analysis Critical Control Point and ISO 22000 accreditation for export-ready facilities typically requires 18-24 months, delaying market access for greenfield processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Dairy Protein Market |
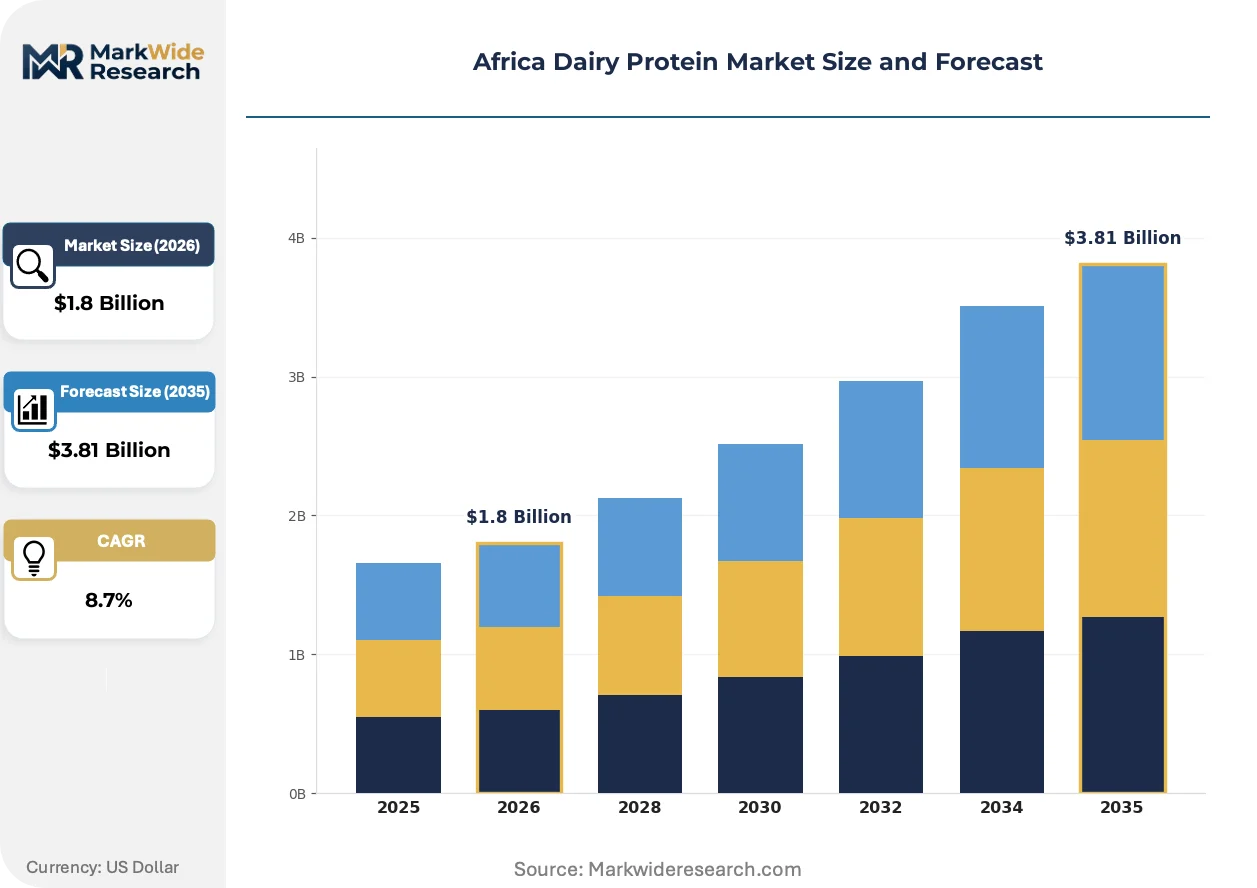
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Milk Protein Concentrate, Whole Milk Powder End User: Food & Beverage, Nutraceuticals, Animal Feed, Sports Nutrition Form: Liquid, Powder, Concentrate, Isolate Application: Beverages, Supplements, Bakery, Dairy Products |
| Companies Covered | Olam International Limited, Lactalis Ingredients, Milk Specialties Global, Epi-ingrédients, Amafu Stock Trading Pty, Arla Foods Ingredients Group P/S, Fonterra Co-operative Group Limited, Royal FrieslandCampina N.V., Nestlé, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Dairy Protein Market Strategic Shifts
Processing technology convergence and regulatory harmonization pressures are reshaping how African dairy protein moves from raw milk to finished ingredient, with implications for capital deployment and competitive positioning.
Ultrafiltration-diafiltration systems are consolidating protein standardization workflows across mid-scale East African processors. Dairy cooperatives in Kenya's Rift Valley and Tanzania's Arusha region are retrofitting existing evaporators with ceramic membrane modules. This hardware convergence is compressing the capital threshold for 80% protein concentrate production, enabling regional players to challenge import-dependent supply chains.
South Africa's Department of Health is tightening enforcement of Regulation R504 on food fortification, mandating third-party protein content verification for all packaged staple foods. Industrial bakeries and milling operations must now submit batch certificates demonstrating minimum protein enrichment levels. Medium-scale processors are responding by pre-qualifying concentrate suppliers against Bureau of Standards test protocols, narrowing the approved vendor list.
Gym operators and fitness influencers are building direct sourcing relationships with protein distributors, bypassing traditional pharmacy and supermarket channels. Lagos-based fitness chains now contract directly with Nigerian importers for container-lot whey isolate purchases. This channel disintermediation is most visible in Nigeria and South Africa, where urban consumer density supports dedicated sports nutrition retail formats.
Africa Dairy Protein Market Segmentation
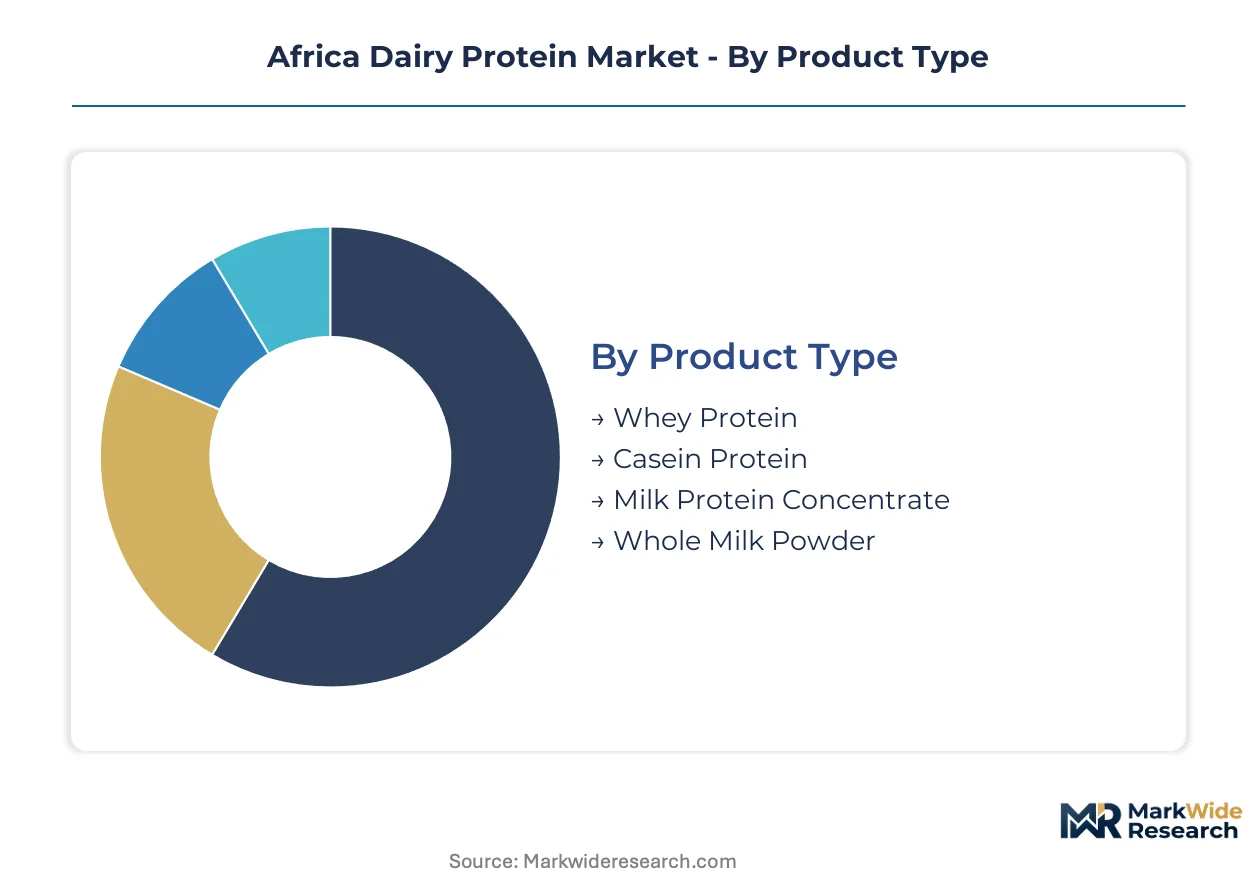
Dairy protein segmentation across Africa reflects divergent supply chain maturity and regulatory pressure points. Whey isolates command premium positioning through import-dependent channels, while milk protein concentrates gain traction via local membrane filtration scale-up.
Product Type:
Supply concentration in New Zealand and European whey processing creates tiered access patterns across African ports.
- Whey Protein:Rapid-absorption protein standardized to 80-90% concentration through ultrafiltration-diafiltration. Demand clusters in South African sports nutrition and Nigerian gym chains where leucine density drives formulation preference. Import dependency exposes margins to freight volatility from Auckland and Rotterdam lanes.
- Casein Protein:Slow-digesting micellar structure sustained through acid precipitation or membrane separation. Egyptian and South African clinical nutrition manufacturers source pharmaceutical-grade material for enteral feeding applications. Sustained-release kinetics limit penetration in immediate-recovery beverage formulations.
- Milk Protein Concentrate:Intermediate protein content (34-85%) achieved through partial membrane filtration without full isolate capital investment. Kenyan and Tanzanian cooperatives are retrofitting evaporators with ceramic modules to compress import reliance.
- Whole Milk Powder:Full-fat spray-dried matrix retaining native protein-lipid complexes. Nigerian and Ethiopian infant formula processors utilize commodity grades, though fortification mandates are pushing specification upgrades.
Today's leader: Whey Protein. Tomorrow's challenger: Milk Protein Concentrate.
End User:
Cost tier stratification separates premium nutraceutical procurement from commodity animal feed volumes.
- Food & Beverage:Industrial bakeries and milling operations across South Africa must comply with Department of Health protein enrichment mandates in maize meal and wheat flour. Pre-qualified concentrate supplier lists are narrowing under third-party verification requirements.
- Nutraceuticals:Clinical nutrition and medical food manufacturers in Egypt and South Africa drive pharmaceutical-grade casein demand. Native micellar specifications command pricing premiums above commodity food-grade material.
- Animal Feed:Calf milk replacer and aquaculture feed compounders in Kenya and Nigeria utilize whey permeate and lower-grade concentrates. Price sensitivity limits specification upgrades despite protein standardization trends in human food.
- Sports Nutrition:Lagos, Nairobi, and Johannesburg gym chains are building direct procurement relationships with importers, bypassing traditional pharmacy and supermarket distribution. Private-label isolate volumes are climbing through container-lot purchasing.
Volume concentrates in Food & Beverage. Margin expansion centers on Sports Nutrition.
Form:
Application requirements and shelf stability demands shape format selection across climatic and infrastructure conditions.
- Liquid:Ready-to-drink protein beverages face cold chain constraints outside South African and Egyptian urban corridors. Aseptic packaging investments remain limited by electricity reliability.
- Powder:Dominant format for whey and milk protein concentrates, enabling ambient storage and flexible reconstitution. Nigerian and Kenyan processors prioritize flowability and instantization for bakery and beverage blending.
- Concentrate:34-80% protein matrices achieved through ultrafiltration without diafiltration capital. East African cooperatives are scaling ceramic membrane installations to capture this mid-tier specification.
- Isolate:90%+ protein purity requiring ion exchange or cross-flow microfiltration. Import dependency from New Zealand and European suppliers persists across all African markets due to fractionation technology gaps.
Powder maintains format dominance. Isolate represents the steepest expansion trajectory.
Application:
Customer type differentiation separates industrial-scale fortification from specialized supplement formulation.
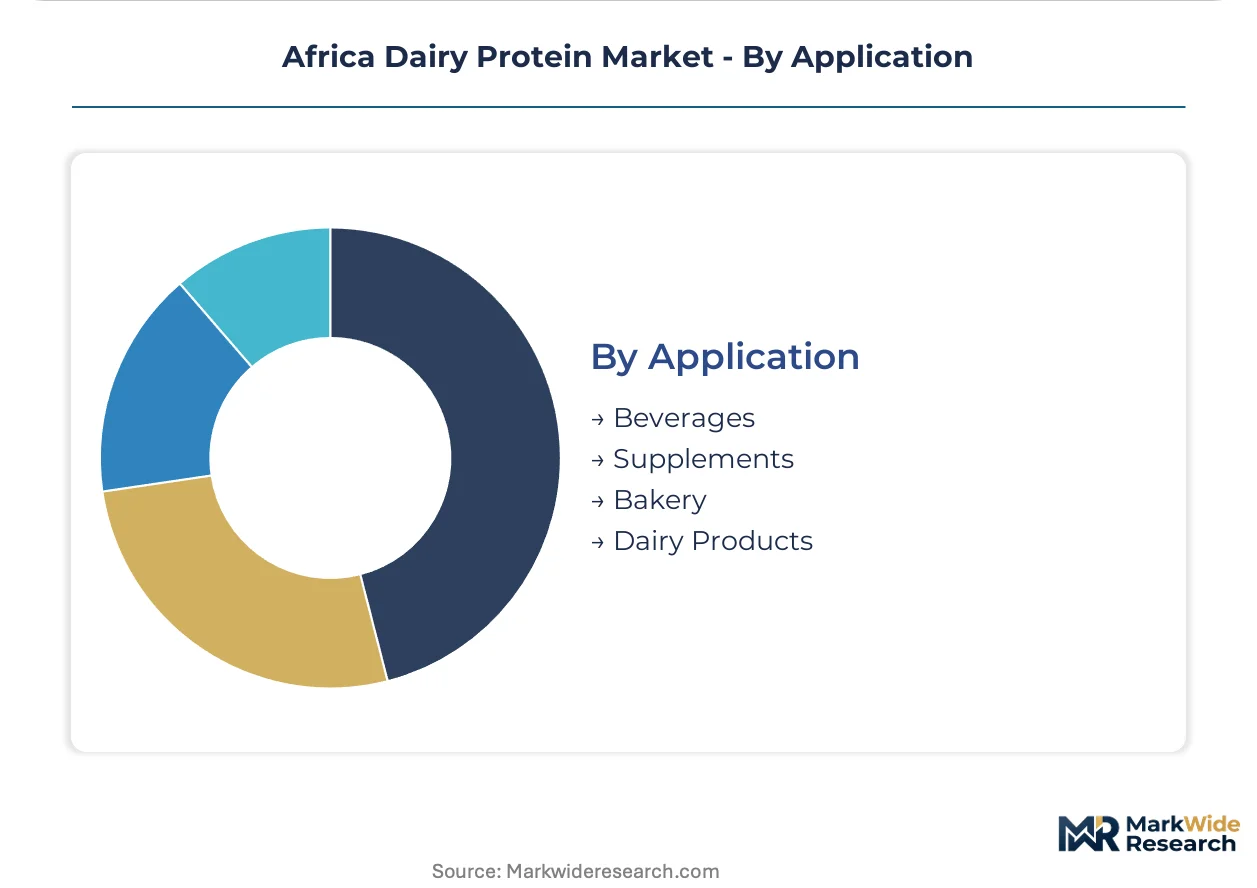
- Beverages:Sports drinks and protein waters in Nigeria and South Africa favor whey isolates for clarity and rapid absorption. Emulsion stability challenges limit casein penetration.
- Supplements:Powder and capsule formats target gym enthusiasts and clinical nutrition patients. Direct-to-consumer channels are compressing traditional pharmacy margins in Ghana and Côte d'Ivoire.
- Bakery:South African industrial bakeries utilize milk protein concentrates for dough conditioning and protein enrichment compliance. Water binding and browning control drive specification selection.
- Dairy Products:Cheese analog production and yogurt fortification in Kenya and Tanzania employ casein and milk protein concentrates for texture and yield optimization.
Beverages anchor volume throughput. Supplements capture value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical talent for membrane filtration operations clusters in South Africa's KwaZulu-Natal and Kenya's Nairobi corridor, anchoring regional processing capabilities while Nigerian and Ethiopian markets scramble to replicate this expertise base.
South Africa
Sports nutrition demand from Johannesburg gym chains and Cape Town clinical nutrition manufacturers pulls whey isolate volumes through Durban port infrastructure. The Department of Health's Regulation R504 mandates third-party protein verification for all fortified staple foods, compressing the approved supplier list for domestic millers. The KwaZulu-Natal processing belt around Pietermaritzburg hosts the continent's most sophisticated ultrafiltration-diafiltration installations.
Nigeria
Lagos fitness chains and Ibadan dairy processors are building direct procurement relationships that bypass traditional wholesale distribution layers. The National Agency for Food and Drug Administration and Control administers import testing protocols that filter substandard concentrate shipments at Apapa port. The Lagos-Ibadan manufacturing corridor is concentrating demand for milk protein concentrates among domestic dairy cooperatives retrofitting evaporator capacity.
Kenya
Nairobi gym operators and Rift Valley dairy cooperatives are driving divergent demand patterns for premium isolates versus mid-tier concentrates. The Kenya Bureau of Standards enforces protein measurement protocols that fragment compliance costs for cross-border shipments into neighboring markets. The Rift Valley processing cluster around Nakuru is retrofitting ceramic membrane modules to raise local fractionation yields.
Egypt
Clinical nutrition manufacturers in Cairo and Alexandria are sourcing pharmaceutical-grade micellar casein for enteral feeding formulations at premium pricing tiers. The country's national pharmaceutical regulator maintains strict import licensing requirements for medical-grade protein ingredients. The Cairo-Alexandria industrial corridor is developing specialized fractionation capabilities to serve North African and Middle Eastern export markets.
Ethiopia
Addis Ababa's nascent dairy processing sector lacks indigenous protein fractionation capacity, creating first-mover positioning for membrane technology licensors. The country's national food safety authority is drafting fortification standards modeled on South African and Kenyan precedents. The Addis Ababa-Adama corridor is attracting greenfield dairy investments seeking proximity to highland milk production zones.
Africa Dairy Protein Market Competitive Environment
Top-tier vendors anchor ocean freight-dependent supply chains, while mid-tier regional blenders compete on powder formulation services and local compliance expertise. The market structure reflects a bifurcation between New Zealand and European fractionators with dedicated Africa shipping lanes, and emerging local processors scaling membrane filtration capacity. Three strategic archetypes dominate: global dairy cooperatives with captive shipping infrastructure, specialized ingredients divisions of multinational food conglomerates, and regional trading houses with port-level logistics control. Competitive moves center on backward integration into milk sourcing partnerships and technology licensing arrangements for membrane system deployment.
Within the cooperative archetype, Fonterra Co-operative Group Limited and Royal FrieslandCampina N.V. occupy positions defined by Southern Hemisphere milk pools and established Africa trade routes. Arla Foods Ingredients Group P/S and Lactalis Ingredients exemplify the specialized ingredients division model, leveraging European fractionation assets to serve pharmaceutical-grade and commodity food-grade demand segments respectively. Olam International Limited represents the regional trading house archetype, anchoring port-level procurement and distribution networks across West and East African markets.
| Leading Market Players |
|---|
| Olam International Limited |
| Lactalis Ingredients |
| Milk Specialties Global |
| Epi-ingrédients |
| Amafu Stock Trading Pty |
| Arla Foods Ingredients Group P/S |
| Fonterra Co-operative Group Limited |
| Royal FrieslandCampina N.V. |
| Nestlé |
| Others |
Value Chain & Pricing Dynamics
South Africa's third-party protein verification mandate under Regulation R504 is forcing industrial bakeries and milling operations to pre-qualify concentrate suppliers against Bureau of Standards test protocols, compressing the approved vendor list and transferring pricing power toward certified fractionators with compliant documentation systems.
Pricing Analysis
The bundled-versus-unbundled service split separates commodity powder transactions from value-added formulation support. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade material reflects certification burden and testing rigor. Price differentiation stems from Bureau of Standards compliance documentation and Fonterra shipping lane reliability. Pricing pressure intensifies in the mid-tier concentrate band as Kenyan cooperatives retrofit ceramic membrane modules. Industrial bakeries exhibit highest price sensitivity; clinical nutrition manufacturers show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Nigerian and South African processors mandate simultaneous qualification of New Zealand and European whey isolate suppliers to mitigate freight rate volatility. Supply concentrates in New Zealand, the Netherlands, and Denmark for premium fractionation; Kenya and South Africa for regional blending. Raw material dependencies span raw milk supply, ceramic membrane modules, and ion exchange resins. Single-source vulnerability persists in pharmaceutical-grade casein where Egyptian clinical nutrition manufacturers rely on limited European micellar casein producers. Distribution runs through Durban, Apapa, and Mombasa port clusters into inland dairy processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade casein and direct-to-gym isolate channels, with membrane filtration cost compression enabling mid-tier processors to capture value previously lost to import markups.
For Market Incumbents: Cement ocean freight contracting advantages through dedicated Africa shipping lane allocations that lock in whey isolate volume commitments. Deepen backward integration into Kenyan and Tanzanian milk sourcing partnerships to secure raw material supply for regional concentrate production. Prioritize Bureau of Standards and National Agency for Food and Drug Administration and Control certification maintenance to defend approved vendor status against emerging membrane-equipped cooperatives.
For New Entrants and Emerging Players: Launch via direct-to-gym distribution cooperatives in Ghana and Côte d'Ivoire where fitness center bulk purchasing bypasses traditional wholesale layers. Target Ethiopian membrane technology licensing opportunities in the Addis Ababa-Adama corridor where indigenous fractionation capacity remains absent. Penetrate the pharmaceutical-grade casein segment through partnerships with Cairo clinical nutrition manufacturers seeking native micellar specifications for enteral feeding formulations.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional trading houses controlling port-level logistics and compliance expertise across West and East African markets. Long-term viability favors acquirers of membrane filtration system operators with established technician training pipelines in Kenya's Rift Valley. Watch for harmonization of CODEX protein measurement methods across the African Continental Free Trade Area as inflection signal for cross-border shipment cost compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Enables Ethiopian and Nigerian cooperatives to raise local protein fractionation yields without full isolate plant capital investment. |
| Direct-to-Gym Distribution Partnership | Compresses intermediary margins by connecting Lagos and Nairobi fitness chains directly with container-lot isolate importers. |
| Pharmaceutical-Grade Casein Capacity Expansion | Serves Cairo and Alexandria clinical nutrition manufacturers sourcing native micellar specifications for enteral feeding at premium tiers. |
| Regulatory Compliance Certification Investment | Secures approved vendor status under South Africa's Regulation R504 third-party verification requirements for fortified staple foods. |
| Backward Integration into Milk Sourcing | Anchors raw material supply for Kenyan and Tanzanian cooperatives retrofitting evaporators with ceramic membrane modules. |
Study Parameters
Coverage spans South Africa, Nigeria, Kenya, Egypt, and Ethiopia, with primary inputs from each market's dairy processing corridors. The analysis combines interviews with membrane filtration plant managers, procurement leads at industrial bakeries, regulatory affairs specialists at National Agency for Food and Drug Administration and Control and Bureau of Standards, and clinical nutrition formulation directors with secondary validation against customs trade data, dairy cooperative production disclosures, and Department of Health fortification enforcement records. Bottom-up volume triangulation from processor capacity utilization rates converges with top-down demand aggregation across food fortification mandates and sports nutrition procurement channels.
Rate-of-change decomposition separates volume drivers from value migration across the projection horizon. The analytical framework models product type, end user, form, and application segmentation alongside regional regulatory cluster differentiation. CAGRs derive from protein content claim enforcement intensity, membrane filtration adoption curves, and gym chain expansion trajectories. Forecast inputs include ceramic membrane installation timelines at Kenyan cooperatives and Lagos-Ibadan corridor manufacturing concentration patterns.
Several conditions sit outside the modeled scope, including abrupt currency devaluations in Nigerian naira or Kenyan shilling, suspension of African Continental Free Trade Area rules of origin implementation, and pandemic-related port congestion recurrence. Deviation in harmonization of protein measurement protocols between national regulators would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
North America Milk Powder Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
GCC Dairy Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
United States Dairy Market
Dairy Products
Canada Casein and Caseinate Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
Textured Butter Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market