
 Dairy Based Dressings Market | 2026-2036
Dairy Based Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Based Dressings Market Outlook
Refrigerated subscription replenishment for food service accounts is expanding as a service-component layer that changes what gets sold in the dairy based dressings category. Kraft Heinz Company leverages its direct-store-delivery infrastructure to control cold-chain placement in grocery delis. Unilever anchors European food service supply through its mayonnaise and dressing co-manufacturing network. Nestlé S.A. specializes in clean-label dairy emulsions for branded retail partnerships.
Dairy based dressings are emulsified sauces containing cultured milk products, vegetable oils, acidulants, and stabilizers, typically held at refrigerated temperatures to maintain microbial safety and functional viscosity. Their primary commercial purpose is to deliver flavor, mouthfeel, and visual coating to salads, proteins, and prepared foods in both retail and food service channels. Ranch and blue cheese variants occupy the largest volume positions due to penetration in quick-service and casual-dining channels. Organic ingredient formulations are gaining fastest in premium retail, though low-fat options face formulation challenges with texture retention. Food service packaging in tubs and portion-control sachets captures the highest margin pools through contract pricing structures.
The FDA enforces Grade A Pasteurized Milk Ordinance standards for dairy ingredient sourcing, while the USDA oversees organic certification claims on dressing labels. The EU's F-Gas Regulation and REACH chemical frameworks constrain certain preservative and propellant options in European production. Stakeholders must monitor evolving clean-label enforcement thresholds and decide whether to invest in regional formulation labs or consolidate recipe platforms across jurisdictions.
Market Dynamics
Clean-label enforcement thresholds are compressing formulation flexibility across refrigerated dressing portfolios, forcing manufacturers to rebuild emulsion stability without synthetic stabilizers or modified starches. This regulatory compression is accelerating consolidation among regional dairy cooperatives that control buttermilk and sour cream base supply.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory ingredient disclosure requirements under the Green Deal are pushing food service operators toward transparent dairy emulsion sourcing, expanding contract volumes for certified clean-label suppliers.
- Quick-service chain expansion:North American casual-dining and fast-casual channels are adding refrigerated dressing wells to salad and protein platforms, driving demand for portion-control sachets and tub formats.
- Cultured dairy fermentation advances:Precision-controlled starter culture technologies are extending refrigerated shelf life without chemical preservatives, enabling broader distribution radius for regional brands.
Market Restraints
- Butterfat and cream input volatility:Dairy commodity price swings directly compress margin structures for emulsion-based formulations, particularly for mid-tier retail private label programs.
- Midwest dairy cooperative concentration:Base ingredient sourcing clusters among a limited number of regional suppliers, creating vulnerability to weather-driven supply interruptions.
- Plant-based dressing substitution:Oat and cashew-based emulsions are capturing shelf space in premium retail, displacing conventional dairy options in flexitarian household baskets.
Strategic Opportunities
- Indian food service penetration:Quick-service chains and cloud kitchens in tier-one cities are introducing Western salad formats, creating first-mover advantage for refrigerated dressing localization.
- Direct-store-delivery channel expansion:Cold-chain control through dedicated delivery fleets enables placement in grocery deli counters previously served by ambient-stable alternatives.
- Organic certification tailwind:USDA organic and EU organic label recognition commands price premiums in specialty retail, rewarding early conversion of conventional production lines.
Industry Challenges
- Emulsion chemistry talent scarcity:Food science programs are producing fewer specialists in dairy lipid stabilization, lengthening R&D cycles for clean-label texture replication.
- Cold-chain capex intensity:Refrigerated tanker fleets and temperature-controlled warehouse expansion require substantial capital deployment, straining mid-scale manufacturer balance sheets.
- Multi-jurisdiction label compliance:Divergent FDA, EFSA, and national dairy board disclosure rules force parallel formulation tracks or costly regional SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Based Dressings Market |
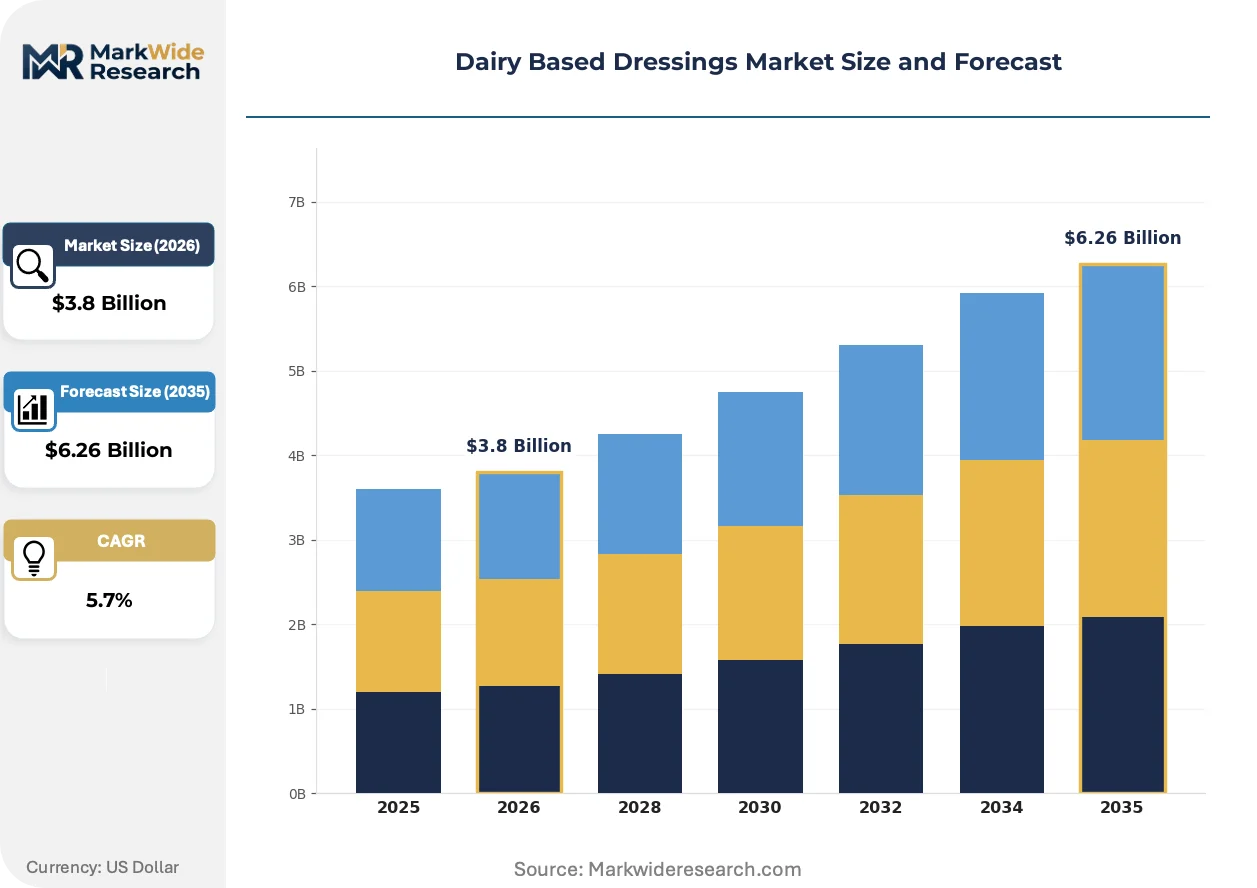
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ranch, Blue Cheese, Caesar, Italian Ingredient Type: Simple, Organic, Low-Fat, Flavored End User: Restaurants, Retailers, Cafes, Food Services Packaging Type: Bottles, Tubs, Sachets, Jars |
| Companies Covered | Kraft Heinz Company, Unilever, Nestlé S.A., General Mills, Inc., Danone S.A., Litehouse Inc., TIC Gums, Inc., DairyChem Inc., Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Based Dressings Market Strategic Shifts
Refrigerated dairy dressing production is pivoting toward fermentation-derived functional ingredients that replace synthetic stabilizers while maintaining pour viscosity and freeze-thaw stability. This shift is redrawing supplier relationships and equipment investment priorities.
High-pressure processing technology is consolidating quality assurance protocols for clean-label dairy emulsions. The non-thermal pasteurization method extends refrigerated shelf life by three to five weeks without chemical preservatives. Mid-scale co-manufacturers in the United States and Germany are retrofitting existing lines with HPP tolling partnerships rather than captive equipment purchases. This capital-light adoption path is consolidating market share among brands with existing cold-chain infrastructure.
The FDA's modernized Nutrition Facts labeling rules and the EU's F-Gas Regulation are tightening simultaneously, forcing dual-compliance investments. Manufacturers must reformulate to reduce saturated fat disclosure thresholds while eliminating hydrofluorocarbon-based refrigeration propellants. European production facilities face the stricter timeline, with German and Dutch plants already converting to mechanical refrigeration and natural acidulant systems.
Food service procurement teams are compressing supplier rosters from multi-source bidding to single-source partnership contracts with guaranteed volume floors. This concentration replaces transactional spot purchasing with integrated category management. The shift is most visible in United States quick-service chains, where procurement directors now mandate direct-store-delivery integration and real-time inventory visibility as table stakes for contract renewal.
Dairy Based Dressings Market Segmentation
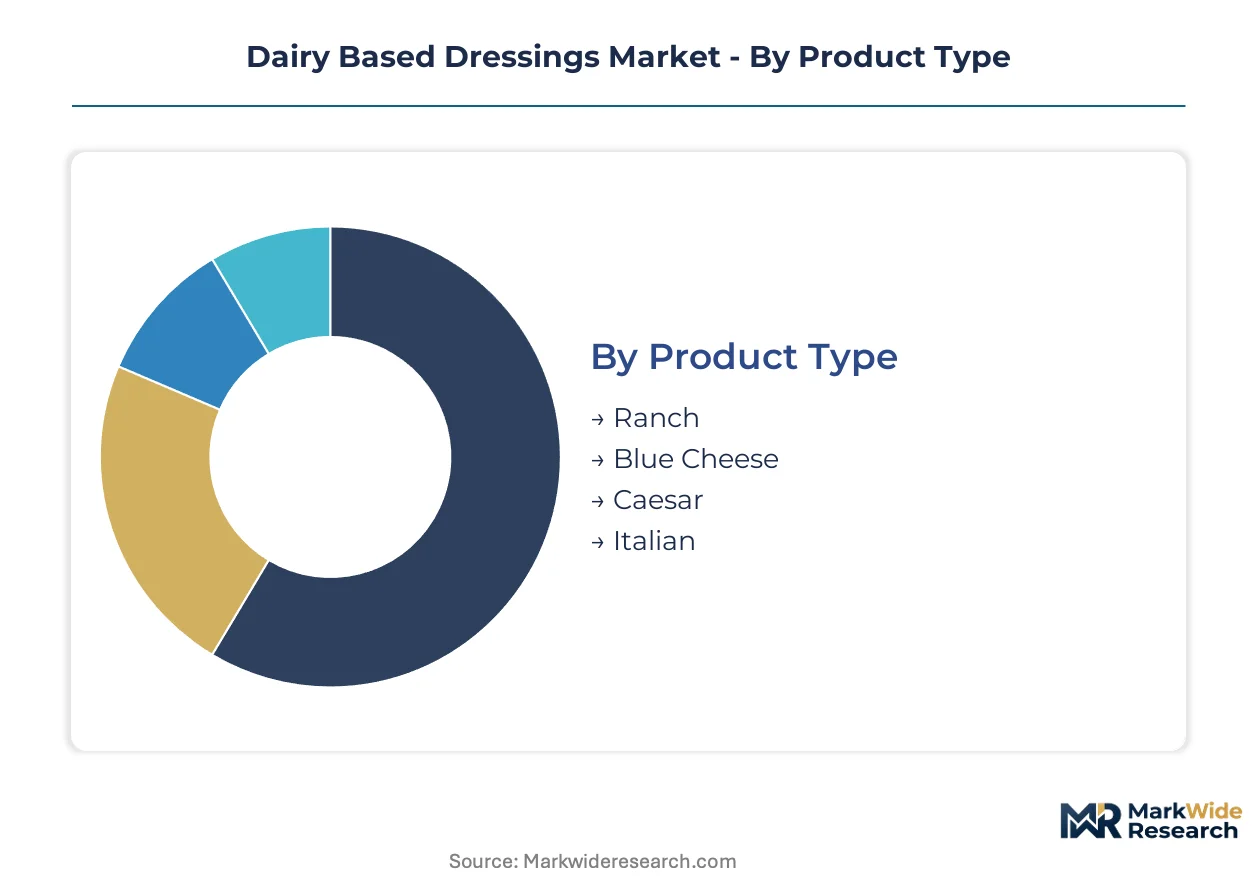
Segmentation in dairy based dressings reveals how formulation chemistry, cold-chain logistics, and procurement specifications fragment commercial opportunity. Buyers prioritize shelf-life stability, clean-label credentials, and portion-control economics differently across channels.
Product Type:
Menu penetration and flavor familiarity drive purchasing decisions for food service operators.
- Ranch:Buttermilk and herb emulsions dominate quick-service salad platforms. Casual-dining chains in the United States specify this variant for 70% of refrigerated dressing wells.
- Blue Cheese:Mold-ripened cheese particulates suspended in sour cream bases deliver signature umami. Steakhouse and wing-bar concepts specify this for protein coating applications.
- Caesar:Anchovy and Parmesan dairy emulsions serve fast-casual Mediterranean formats.
- Italian:Herb-infused buttermilk variants compete with ambient vinaigrettes in retail.
Volume sits with Ranch; growth tilts toward Blue Cheese as premium protein platforms expand.
Ingredient Type:
Regulatory disclosure thresholds and margin structures determine formulation investment priorities.
- Simple:Conventional cultured dairy bases with standard stabilizers serve price-sensitive food service contracts. USDA Grade A sourcing satisfies most institutional procurement specifications.
- Organic:Certified dairy ingredients and non-GMO oils command shelf-space premiums in specialty retail. EU organic recognition accelerates placement in German and French supermarket chains.
- Low-Fat:Reduced butterfat formulations face texture degradation challenges in freeze-thaw distribution.
- Flavored:Smoked, spicy, and regional variants differentiate regional co-manufacturer portfolios.
Simple formulations anchor contract volumes; organic certification gains share fastest in premium retail.
End User:
Cold-chain capability and order frequency separate addressable customer pools.
- Restaurants:Full-service and casual-dining operators purchase gallon tubs through broadline distributors. Temperature-controlled delivery mandates limit supplier eligibility.
- Retailers:Grocery delis and refrigerated cases stock 12-16 ounce bottles for household replenishment.
- Cafes:Limited-menu operators favor portion-control sachets to minimize waste.
- Food Services:Institutional caterers and contract feeders specify USDA-compliant bulk formats.
Restaurants capture the largest tonnage; retailers deliver the steepest expansion trajectory through deli placement.
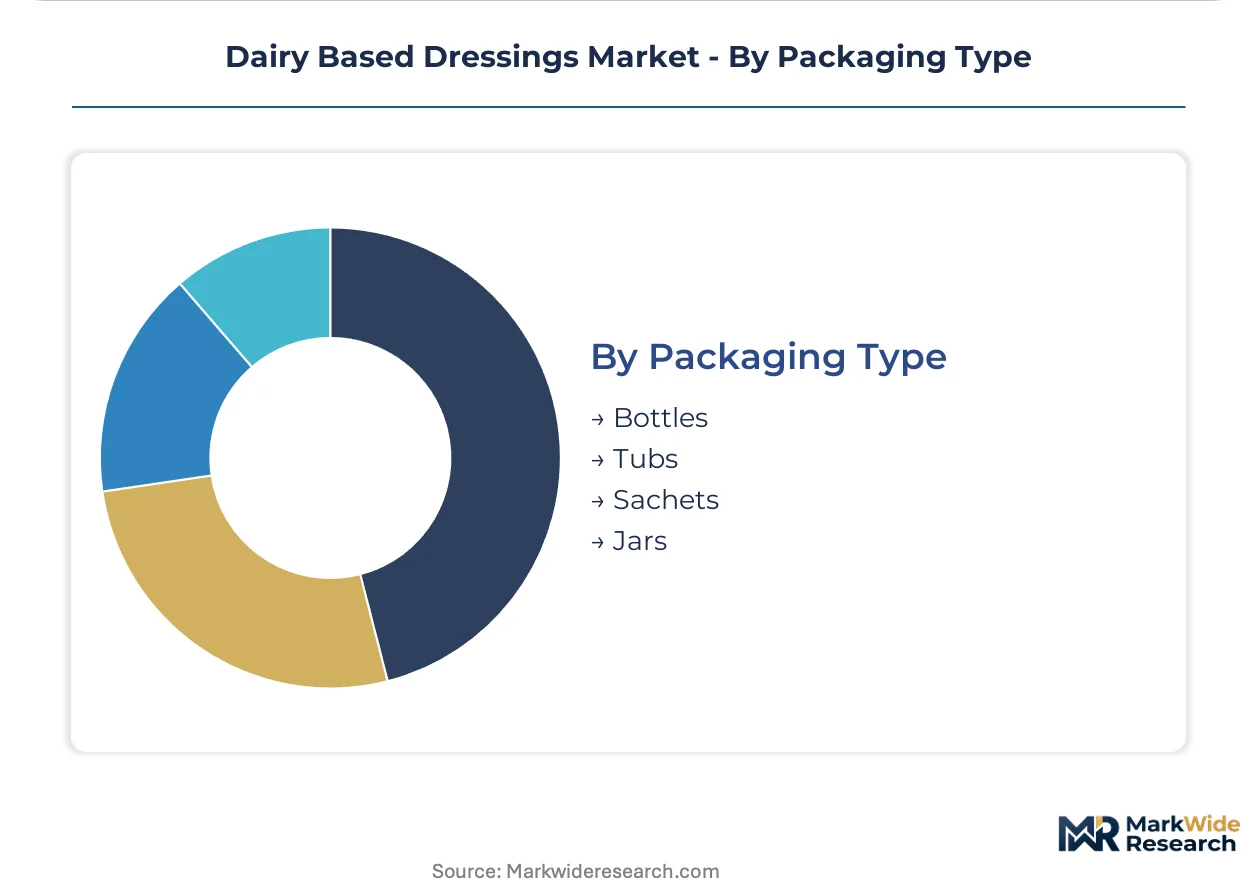
Packaging Type:
Distribution economics and consumption occasion shape format selection.
- Bottles:PET and glass containers dominate retail shelf placement. Pour-spout engineering reduces viscosity-related consumer frustration.
- Tubs:Polypropylene pails serve high-volume food service accounts with pump dispensing.
- Sachets:Single-serve foil packets eliminate cross-contamination risk in quick-service environments.
- Jars:Wide-mouth glass formats persist in specialty and gift-channel positioning.
Tubs generate the highest food service margins; sachets climb fastest as grab-and-go salad formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of cultured dairy bases concentrates in the American Midwest and Northern Europe, while consumption spreads through quick-service chains and retail delis in urban centers worldwide. This geographic split shapes cold-chain investment priorities and regulatory compliance burdens differently across markets.
United States
Quick-service chains and casual-dining operators drive refrigerated dressing volume through salad and protein platform expansion. The FDA enforces Grade A Pasteurized Milk Ordinance standards for dairy ingredient sourcing, tightening microbial safety protocols. Wisconsin and Minnesota dairy cooperatives supply buttermilk and sour cream bases to co-manufacturers serving national restaurant accounts.
Germany
Food service operators are converting to clean-label dairy emulsions under pressure from EU Farm to Fork disclosure mandates. The F-Gas Regulation constrains hydrofluorocarbon-based refrigeration propellants in production facilities, accelerating mechanical refrigeration retrofits. Bavarian and North Rhine-Westphalian processing plants lead conversion to natural acidulant systems for export-compliant formulations.
France
Supermarket chains in Paris and Lyon are expanding refrigerated deli placements for organic-certified dressing variants. EFSA disclosure rules and national dairy board labeling requirements create multi-layer compliance complexity. The Île-de-France region hosts formulation labs serving pan-European retail partnerships seeking EU organic recognition.
India
Quick-service chains and cloud kitchens in Mumbai, Delhi, and Bangalore are introducing Western salad formats, creating first-mover opportunity for localized dressing production. FSSAI food safety standards govern dairy ingredient import and processing certification. Maharashtra and Karnataka are emerging as co-manufacturing hubs for refrigerated sauce adaptation to local palate preferences.
Japan
Convenience store chains and fast-casual operators are adding refrigerated dressing wells to prepared food sections. METI energy efficiency standards and PMDA food additive regulations shape formulation and packaging decisions. The Kanto region around Tokyo concentrates demand for portion-control formats in high-density urban retail.
Dairy Based Dressings Market Competitive Environment
Capital-heavy producers with captive dairy supply compete with asset-light brands that rely on co-manufacturing partnerships for emulsion production. The market structure tilts toward consolidation as clean-label compliance costs squeeze mid-scale operators. Three archetypes dominate: integrated dairy processors with backward control over cultured base supply, multinational CPG conglomerates with direct-store-delivery infrastructure, and regional co-manufacturers specializing in food service contract production. Competitive moves center on cold-chain capacity expansion and strategic partnerships with quick-service procurement teams.
Within the multinational conglomerate tier, Kraft Heinz Company, Unilever, and Nestlé S.A. occupy positions defined by refrigerated distribution reach and retail shelf-space access. Kraft Heinz exemplifies the direct-store-delivery archetype through grocery deli channel control. Unilever anchors European food service supply through co-manufacturing network density. Nestlé S.A. represents the clean-label retail partnership model with branded dairy emulsion specialization.
| Leading Market Players |
|---|
| Kraft Heinz Company |
| Unilever |
| Nestlé S.A. |
| General Mills, Inc. |
| Danone S.A. |
| Litehouse Inc. |
| TIC Gums, Inc. |
| DairyChem Inc. |
| Tate & Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
Family-owned dairy cooperatives in Wisconsin and Minnesota anchor buttermilk and sour cream base supply, translating upstream consolidation into asymmetric pricing power over mid-scale co-manufacturers. Their collective ownership structure insulates base ingredient pricing from short-term commodity volatility while forcing downstream brands to absorb margin compression through contract renegotiation cycles.
Pricing Analysis
Margin tightening in mid-tier retail private label programs reflects butterfat and cream input volatility tracked through Chicago Mercantile Exchange dairy futures. Contract-based long-term offtake agreements dominate food service procurement, with price differentiation hinging on USDA organic certification tier and direct-store-delivery integration depth. Quick-service chains exhibit lowest price sensitivity due to guaranteed volume floors, while independent casual-dining operators face acute cost compression.
Supply Chain Analysis
Single-source vulnerability sits with Midwest dairy cooperative concentration for cultured base supply, compounded by weather-driven feed grain disruptions. Production draws from the United States, Germany, and France for emulsion manufacturing, with raw material dependencies spanning Grade A pasteurized milk, vegetable oil inputs, and natural acidulant systems. Tariff exposure on cross-border dairy ingredient flows constrains European formulation flexibility. Distribution runs through refrigerated tanker fleets and temperature-controlled warehouse networks serving broadline distributors and direct-store-delivery routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
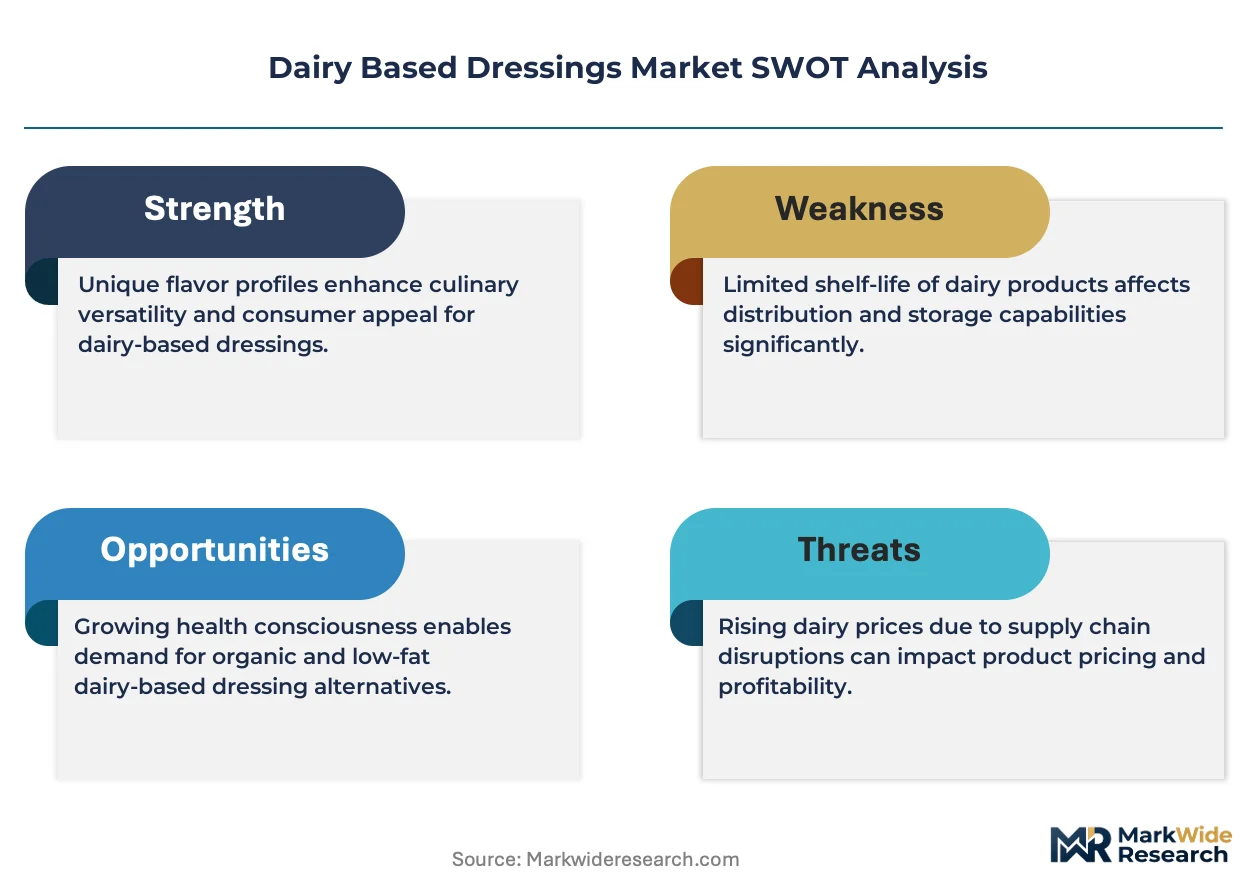
Buttermilk and sour cream base scarcity props pricing discipline across refrigerated dressing portfolios, constraining volume expansion for brands lacking captive dairy supply or long-term cooperative contracts.
For Market Incumbents: Hedge against plant-based substitution by accelerating clean-label certification investments and locking multi-year supply agreements with regional dairy cooperatives before capacity tightens further. Defend food service margins through exclusive direct-store-delivery partnerships that raise rival switching costs. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian tier-one cities offers white-space entry through localized flavor adaptation for quick-service salad formats. Target cloud kitchen supply chains with portion-control sachet formats and FSSAI-compliant co-manufacturing partnerships as the most penetrable beachhead. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale co-manufacturers with existing cold-chain infrastructure in the United States and Germany over asset-light brand plays. Watch for EU Farm to Fork compliance cost spikes as the inflection signal triggering consolidation-driven acquisition windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultured Base Supply | Captive buttermilk sourcing from Wisconsin dairy cooperatives insulates margin structures from commodity volatility. |
| Clean-Label Certification Investment | USDA organic and EU organic recognition commands shelf-space premiums in German and French supermarket chains. |
| Direct-Store-Delivery Channel Expansion | Kraft Heinz-style cold-chain control enables placement in grocery deli counters previously served by ambient alternatives. |
| High-Pressure Processing Technology Adoption | HPP tolling partnerships extend refrigerated shelf life without synthetic preservatives, consolidating clean-label market share. |
| Food Service Single-Source Partnership Conversion | Integrated category management contracts with quick-service procurement teams replace transactional spot purchasing. |
Study Parameters
Document review covered FDA Grade A Pasteurized Milk Ordinance filings, EU Farm to Fork strategy implementation documents, and SEC 10-K disclosures from CPG conglomerates, complemented by interviews with co-manufacturing plant managers, quick-service procurement directors, dairy cooperative supply planners, and refrigerated logistics operators. Secondary validation drew from USDA dairy production statistics, EFSA additive safety assessments, and customs trade data on cross-border dairy ingredient flows. Bottom-up volume modeling and top-down market sizing triangulated across these inputs.
Segment-level projections across product type, ingredient certification tier, end-user channel, and packaging format fed into analytical framework outputs over the projection horizon. CAGRs were derived from regression analysis against dairy commodity price indices and quick-service chain expansion trajectories. Modeled inputs included refrigerated shelf-life extension technology adoption curves and clean-label enforcement threshold escalation patterns.
Inputs from cooperative supply planners and food service procurement directors were available through the study window; gaps in real-time inventory visibility data from direct-store-delivery networks introduce uncertainty bands around channel-share forecasts. Deviation in EU F-Gas Regulation enforcement timing or FDA modernized Nutrition Facts label compliance deadlines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Dairy Foods Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Europe Milk Protein Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
United States Camel Dairy Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
United Kingdom Whey Protein Market