
 Clotted Cream Market | 2026-2036
Clotted Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Clotted Cream Market Outlook
Capital-intensity divergence between artisan copper-pot producers and scaled continuous-flow processors is bifurcating competitive dynamics in clotted cream supply. Langage Farm LLP leverages its Devonshire farmgate heritage and on-site herd control to sustain premium positioning in specialty retail channels. A. E. Rodda & Son Ltd. anchors its Cornwall operations through Protected Designation of Origin certification, dominating heritage-driven export demand. First Milk competes on volume efficiency, extending its cooperative processing network across multiple UK creameries to occupy mid-market supermarket placements.
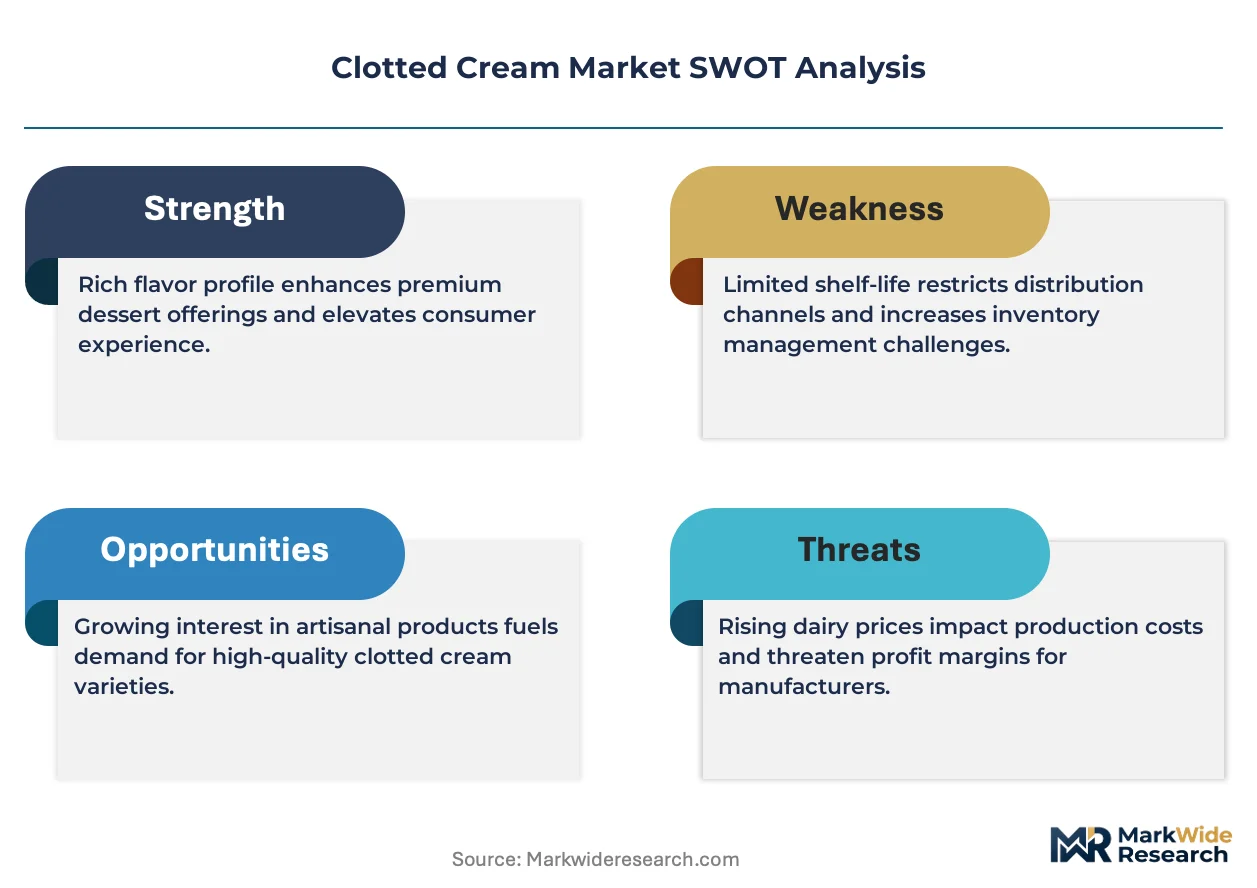
Clotted cream is a high-fat dairy product containing minimum 55 percent butterfat, produced by indirect heating of full-cream milk followed by slow cooling to induce thick crust formation, serving primarily as a spread or topping in foodservice and retail bakery applications. Traditional clotted cream retains the largest revenue share due to its PDO-linked premium pricing in UK and export markets, though organic clotted cream is expanding fastest as clean-label procurement shifts among cafes and catering services. Glass jars command disproportionate margin pools in gifting and specialty retail, while plastic containers dominate volume throughput in supermarkets where cost-per-unit drives purchasing decisions.
The UK's Food Standards Agency enforces dairy fat content and labeling standards that shape product formulation and market access for domestic and imported clotted cream. REACH compliance across EU member states governs food-contact packaging materials, particularly affecting glass jar coatings and sealants used in premium product lines. Stakeholders must monitor evolving PDO enforcement intensity and alternative protein labeling rules that could redefine competitive boundaries between dairy-origin and plant-based clotted cream alternatives.
Market Dynamics
The Food Standards Agency's dairy fat labeling requirements are compressing formulation flexibility and forcing processors toward cleaner ingredient declarations across UK supply chains.
Growth Catalysts
- PDO Certification Expansion:Protected Designation of Origin status for Cornish clotted cream anchors premium pricing power and heritage-driven export demand into specialty retail channels.
- Artisanal Bakery Culture:Premium pastry applications in London and Cornwall absorb higher volumes as farmgate heritage positioning deepens consumer willingness to pay for provenance.
- Clean-Label Procurement:UK cafes and catering services shift toward organic clotted cream variants, pulling processors away from additive-heavy formulations.
Market Restraints
- Input Cost Volatility:Full-cream milk prices fluctuate with UK dairy commodity cycles, compressing margin buffers for mid-market supermarket placements.
- Supply Concentration Risk:England's West Country dominates production gravity, exposing buyers to regional weather disruptions and localized herd health events.
- Plant-Based Substitution:Oat and coconut cream alternatives capture lactose-intolerant and vegan segments in urban foodservice accounts.
Strategic Opportunities
- Export Channel Diversification:Heritage positioning unlocks white space in North American specialty grocers seeking authentic British dairy provenance.
- Glass Jar Gifting Premium:Disproportionate margin pools in specialty retail reward aesthetic packaging innovation for occasion-based purchase.
- On-Farm Processing Integration:Devonshire and Cornwall farmgate operators capture value through direct-to-consumer subscription and visitor center retail.
Industry Challenges
- Skilled Dairy Technician Scarcity:Traditional copper-pot production methods require apprenticeship-trained operators, with aging workforce demographics constraining artisanal scale-up.
- PDO Compliance Timeline:Certification documentation and enforcement intensity create administrative burden for smaller processors seeking protected status.
- Continuous-Flow Capex Requirements:Scaled processors face capital intensity for automated heating and cooling infrastructure to serve supermarket volume contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clotted Cream Market |
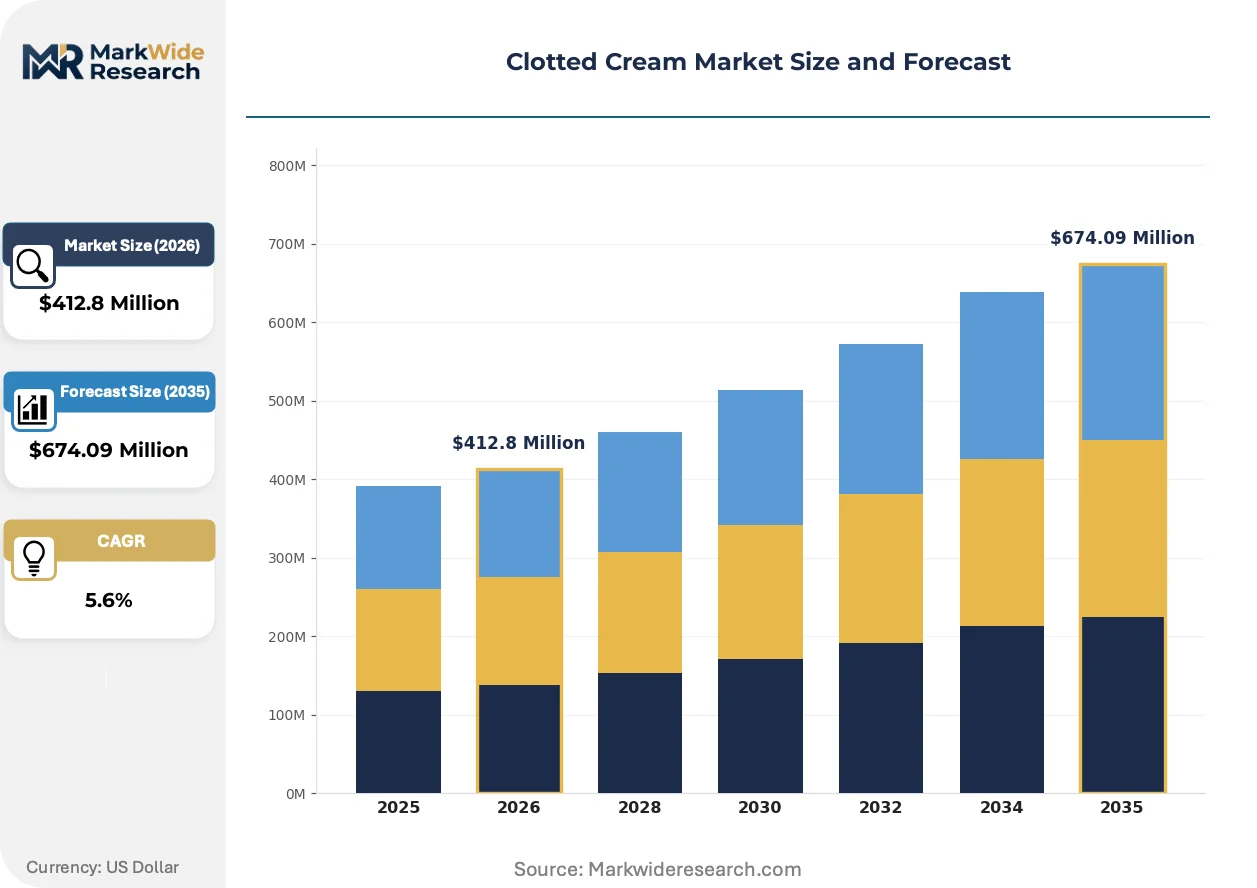
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $674.09 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Clotted Cream, Flavored Clotted Cream, Organic Clotted Cream, Vegan Clotted Cream End User: Cafes, Restaurants, Bakeries, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Packaging Type: Glass Jars, Plastic Containers, Tetra Packs, Pouches |
| Companies Covered | Daffodil Foods, Langage Farm LLP, A. E. Rodda & Son Ltd., First Milk, Jolly Posh Foods, Golden Hooves, Calbourne Classics, Cornish Dairy Company, Graham's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clotted Cream Market Strategic Shifts
Processing technology divergence between heritage methods and automated systems is reshaping competitive boundaries, while regulatory pressure and procurement sophistication compress traditional margin structures.
Small-batch copper-pot heating is fragmenting the production landscape between artisan authenticity and volume efficiency. Farmgate operators in Devonshire and Cornwall adopt this method to sustain premium positioning in specialty retail. The technology is fragmenting competitive tiers, creating distinct margin pools that resist price convergence.
REACH compliance across EU member states governs food-contact packaging materials, particularly sealants and coatings in premium glass jar lines. UK exporters to continental Europe face reformulation costs for compliant adhesives and barrier films. Heritage processors with established EU distribution networks absorb these costs fastest, widening their channel access advantage.
Buyer concentration among UK supermarket chains compresses supplier negotiation leverage and demands private-label production capacity. Mid-market processors face margin pressure as Tesco, Sainsbury's and Waitrose consolidate dairy category management. This pattern concentrates most visibly in England's South East, where retail headquarters procurement centralizes volume allocation decisions.
Clotted Cream Market Segmentation
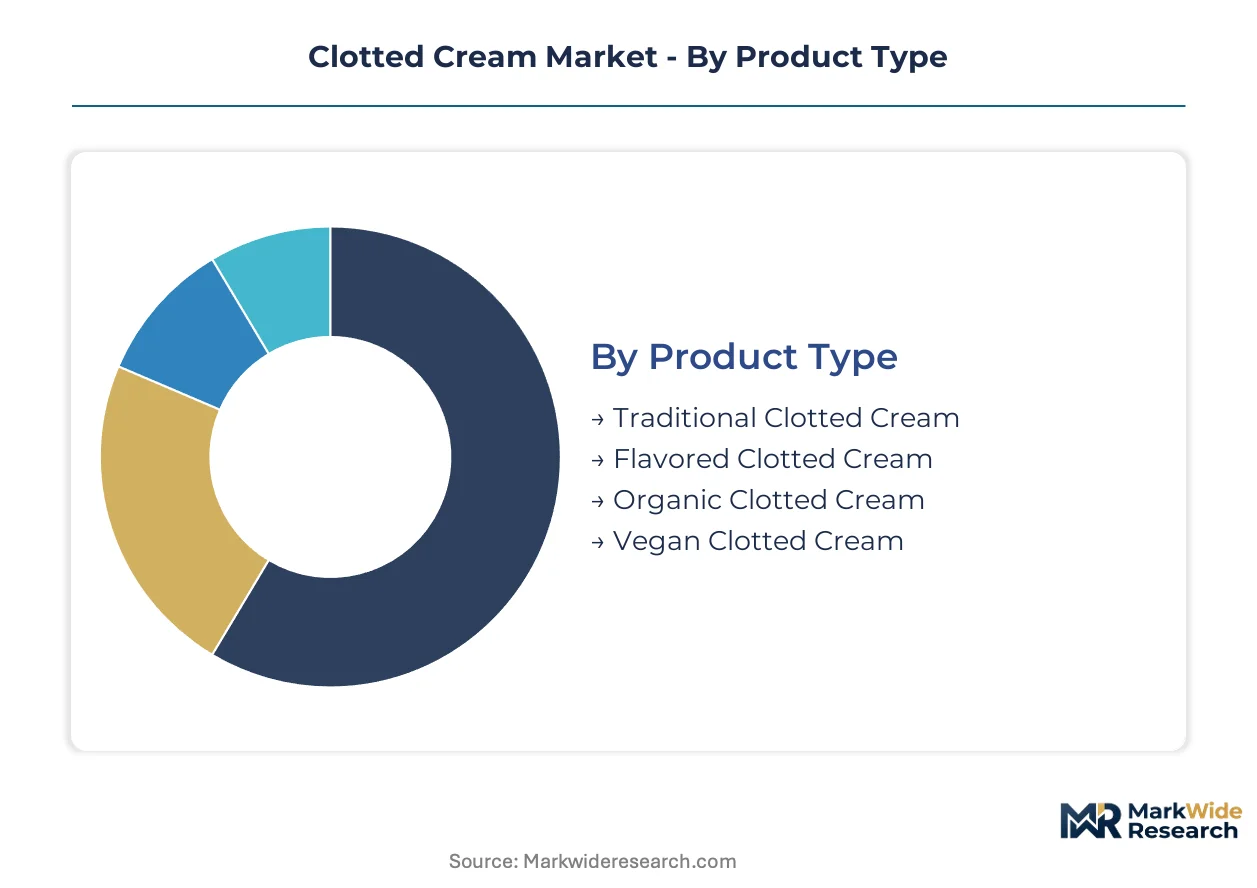
Clotted cream segmentation reveals how heritage authenticity, health positioning, and channel economics split demand across distinct buyer cohorts. Each dimension carries different margin profiles and vulnerability to plant-based substitutes.
Product Type:
Vegan clotted cream faces the most acute substitution pressure as oat and coconut bases capture lactose-intolerant urban consumers, while traditional variants defend through PDO-linked provenance.
- Traditional Clotted Cream:Minimum 55 percent butterfat content produced through indirect heating and slow cooling methods. West Country farmgate operators in Cornwall and Devon supply heritage-driven export demand into North American specialty grocers, with PDO certification anchoring premium pricing power against commodity alternatives.
- Organic Clotted Cream:Sourced from pasture-fed herds without synthetic inputs or additives. UK cafes and catering services in London's artisanal bakery corridor absorb expanding volumes as clean-label procurement shifts away from conventional formulations.
- Flavored Clotted Cream:Infused variants including vanilla, lavender, or citrus profiles targeting gifting occasions. Seasonal demand spikes concentrate in England's South East retail corridors.
- Vegan Clotted Cream:Plant-based formulations using oat, coconut, or cashew bases. Urban foodservice accounts in Manchester and Bristol trial these alternatives for dietary accommodation.
Traditional clotted cream anchors the volume base while organic clotted cream gains share at the steepest rate.
End User:
Margin concentration varies sharply across foodservice tiers, with bakeries capturing heritage premiums while catering services face cost-per-portion compression.
- Bakeries:Artisanal pastry applications in London and Cornwall absorb higher volumes as farmgate heritage positioning deepens. Premium scone and cake formulations specify Cornish PDO-certified inputs for provenance marketing.
- Cafes:Independent coffee shops and tea rooms across England's West Country feature clotted cream as a signature accompaniment. Clean-label procurement shifts pull these accounts toward organic variants.
- Restaurants:Fine-dining and hotel breakfast service in regional tourism hubs. Menu placement depends on consistent supply from cooperative processing networks.
- Catering Services:Event and institutional foodservice requiring volume efficiency. Mid-market processors compete through private-label production capacity for contract catering accounts.
Bakeries command the highest margin per kilogram while catering services drive the largest absolute tonnage.
Distribution Channel:
Channel economics fragment between aesthetic-driven specialty retail and efficiency-driven supermarket procurement.
- Specialty Stores:Curated food halls and farm shops emphasizing provenance storytelling. Glass jar gifting premiums reward packaging innovation for occasion-based purchase in Cotswolds tourism corridors.
- Supermarkets:Tesco, Sainsbury's, and Waitrose consolidate dairy category management. Buyer concentration compresses supplier negotiation leverage and demands private-label production capacity.
- Online Retail:Subscription and direct-to-consumer platforms extending reach beyond traditional retail footprints. Devonshire and Cornwall farmgate operators capture value through visitor center retail integration.
- Direct Sales:On-farm processing and farmers' market presence. Heritage processors leverage established EU distribution networks for continental export compliance.
Supermarkets dominate volume throughput while specialty stores generate disproportionate margin pools.
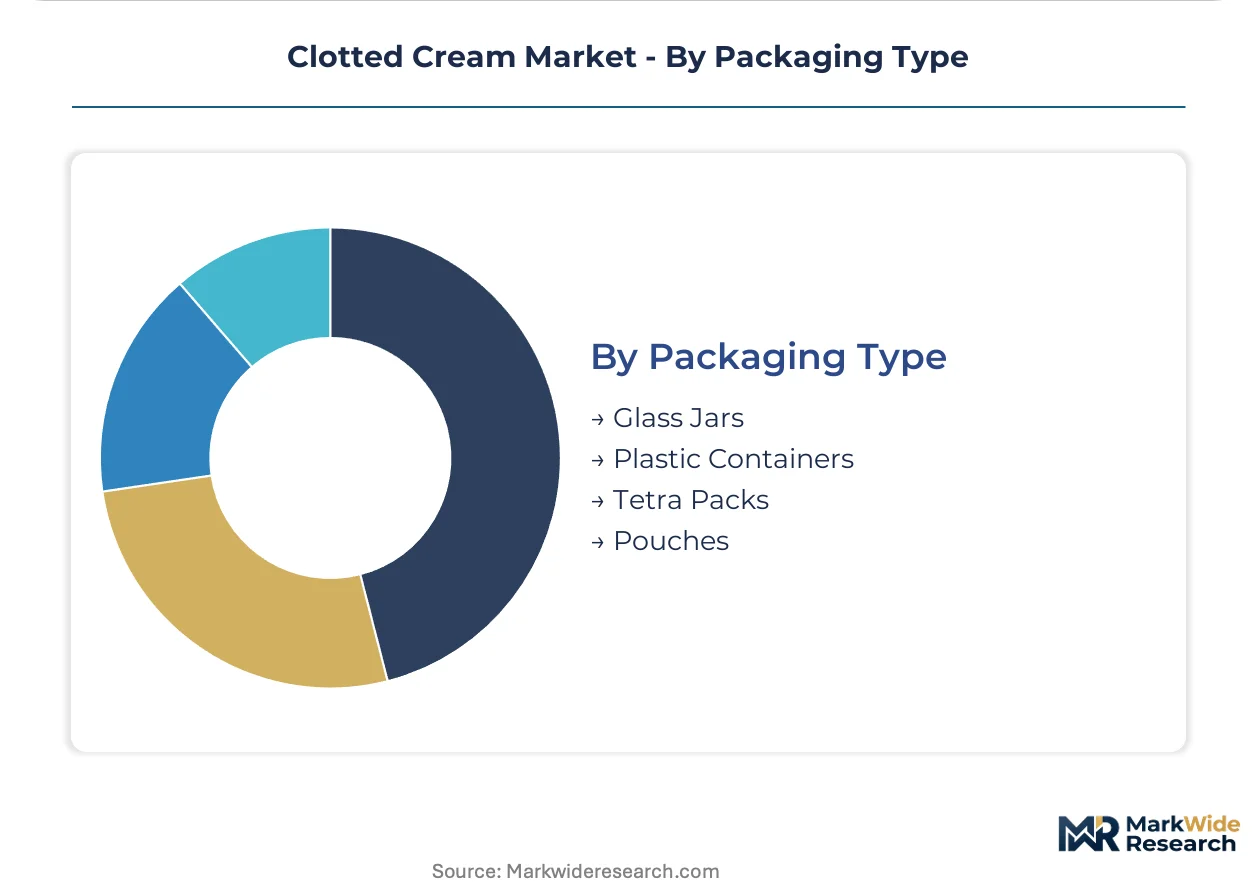
Packaging Type:
Packaging selection reflects trade-offs between shelf presence, cost efficiency, and regulatory compliance for export channels.
- Glass Jars:Premium presentation for gifting and specialty retail segments. REACH compliance governs sealants and coatings for EU export, with heritage processors absorbing reformulation costs fastest.
- Plastic Containers:Volume-efficient formats dominating supermarket placements. Cost-per-unit drives purchasing decisions in mid-market retail channels.
- Tetra Packs:Aseptic processing for extended shelf stability. Limited adoption due to texture degradation concerns in high-fat dairy applications.
- Pouches:Flexible formats for foodservice bulk supply. Emerging presence in catering and institutional accounts prioritizing storage efficiency.
Plastic containers anchor the volume base while glass jars expand most quickly in export and gifting segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The clotted cream trade balance tilts toward surplus in heritage-producing regions while import dependency characterizes markets lacking PDO infrastructure. Export flows concentrate through established EU distribution networks, with regulatory compliance costs filtering channel access.
United Kingdom
England's West Country anchors production gravity through Cornish and Devonshire farmgate operations. The Food Standards Agency enforces dairy fat labeling standards that compress formulation flexibility for domestic processors. London's artisanal bakery corridor absorbs premium volumes, with specialty retailers in the Cotswolds commanding glass jar gifting premiums.
United States
Specialty grocers in metropolitan markets drive import demand for heritage-positioned British dairy provenance. FDA dairy product safety standards govern labeling and import clearance for cream-based products. Northeast corridor foodservice accounts in Boston and New York trial authentic clotted cream for afternoon tea service differentiation.
France
Cross-channel retail procurement concentrates in northern metropolitan areas with British tourism exposure. EFSA dairy standards align with UK formulations, reducing technical barriers for Cornish PDO exporters. Parisian specialty food halls curate provenance-driven dairy selections for occasion-based purchase.
Germany
REACH compliance requirements for food-contact packaging materials filter EU market access for glass jar sealants and coatings. Bavarian and Baden-Württemberg foodservice distributors consolidate volume allocation for British dairy imports. Frankfurt's procurement centralization shapes supermarket placement negotiations.
Australia
Commonwealth heritage positioning supports niche demand in Melbourne and Sydney specialty retail channels. The country's national dairy regulator enforces compositional standards that parallel UK butterfat minimums. Direct-to-consumer subscription platforms extend reach beyond traditional import distribution footprints.
Clotted Cream Market Competitive Environment
Concentration sits with farmgate heritage operators and cooperative processing networks rather than integrated multinationals. The competitive terrain fragments across artisan copper-pot producers and scaled continuous-flow processors serving divergent channel economics. Three archetypes dominate: PDO-certified heritage specialists, volume-efficient cooperative processors, and farmgate direct-to-consumer operators. Capacity expansion and packaging compliance investments represent the dominant competitive moves as REACH adherence widens channel access advantages.
Within the heritage specialist tier, A. E. Rodda & Son Ltd. and Langage Farm LLP occupy positions defined by geographic provenance and protected designation infrastructure. First Milk represents the cooperative processing archetype, anchoring mid-market supermarket placement through volume efficiency. These three exemplify the bifurcation between premium authenticity positioning and scale-driven private-label supply.
| Leading Market Players |
|---|
| Daffodil Foods |
| Langage Farm LLP |
| A. E. Rodda & Son Ltd. |
| First Milk |
| Jolly Posh Foods |
| Golden Hooves |
| Calbourne Classics |
| Cornish Dairy Company |
| Graham's |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between West Country creameries and supermarket chains lock in both supply access and price visibility, insulating PDO-certified processors from spot-market milk volatility while compressing margin flexibility for mid-tier suppliers. The Food Standards Agency's dairy fat labeling requirements add compliance cost layers that concentrate pricing power with heritage operators capable of absorbing documentation burdens.
Pricing Analysis
Supermarket buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with PDO certification and glass jar packaging commanding spreads over private-label plastic formats. Price differentiation hinges on provenance authentication and volume scale, with heritage farmgate operators capturing premiums while cooperative processors face cost compression in contract catering segments. Pricing pressure stems from concentrated buyer leverage among Tesco, Sainsbury's and Waitrose procurement teams. Catering services exhibit highest price sensitivity; specialty retailers demonstrate lowest.
Supply Chain Analysis
Container availability on Southampton-Plymouth coastal routes shapes inbound logistics costs for glass jar sealants and barrier films required for EU export compliance. Production concentrates in Cornwall, Devon and Somerset, with full-cream milk supply drawing from pasture-fed herds across England's West Country. Raw material dependencies include dairy feed inputs, copper-pot equipment, and REACH-compliant packaging coatings. Single-source vulnerability characterizes artisanal technician pools trained in traditional heating methods. Distribution runs through cooperative processing networks for supermarket volume, with direct-to-farm retail capturing specialty margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clotted cream market presents a defensive-moat structure rooted in regulatory entrenchment: PDO certification creates non-replicable geographic barriers that lock out distant competitors regardless of capital deployment.
For Market Incumbents: Secure copper-pot production capacity through apprenticeship pipeline investments, as aging technician demographics threaten artisanal scale-up potential. Anchor supermarket shelf presence via exclusive supply agreements that preempt private-label displacement. Plant-based substitution pressure from oat and coconut alternatives demands accelerated organic certification to defend clean-label positioning. For New Entrants and Emerging Players: Direct-to-consumer subscription gaps in North American specialty retail offer white-space entry with lower buyer concentration risk than UK supermarket channels. Target urban foodservice accounts in Manchester and Bristol with vegan clotted cream formulations, as lactose-intolerant accommodation remains under-served by heritage operators. Pursue farmgate visitor center integration as the primary go-to-market angle, leveraging provenance storytelling unavailable to scaled processors. For Investors and Strategic Acquirers: Farmgate heritage operators with established EU distribution networks represent the priority acquisition archetype, as REACH compliance investments already absorbed widen channel access advantages. Long-term viability centers on regulatory moat durability rather than technology disruption risk. Watch PDO enforcement intensity as the critical inflection signal; weakened protected designation administration would erode premium pricing structures.| Strategic Initiative | Industry Significance |
|---|---|
| PDO Certification Investment | Protected Designation of Origin status anchors premium pricing power in export channels. |
| Copper-Pot Capacity Expansion | Traditional heating methods sustain artisanal authenticity positioning in specialty retail. |
| Organic Herd Conversion | Pasture-fed supply chains capture clean-label procurement shifts in cafe and catering segments. |
| Glass Jar Gifting Line Launch | Aesthetic packaging innovation unlocks disproportionate margin pools in occasion-based purchase. |
| EU Distribution Network Extension | Established continental channel access absorbs REACH compliance costs fastest. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of Food Standards Agency enforcement records, dairy commodity trade data, and PDO certification registries. Primary interviews engaged creamery operations managers, supermarket category buyers, artisanal bakery procurement leads, and foodservice distribution specialists. Secondary validation drew from UK dairy customs records, EU REACH substance databases, and farmgate retail audit data. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Segmentation dimensions modeled include product type tier, end-user application, distribution channel format, and packaging material classification. CAGRs were derived from trend extrapolation of volume absorption patterns and price trajectory assumptions. Forecast inputs incorporated herd size projections, milk fat yield variability, and regulatory compliance cost trajectories.
Forecasts assume regulatory continuity in UK Food Standards Agency enforcement and EU REACH substance restrictions; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Reconstituted Milk Market
Dairy Products
North America Fluid Milk Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Citrus Yogurt Market
Dairy Products
North America Casein Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Low Fat Butter Market
Dairy Products
Butter and Margarine Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Milk Protein Concentrate Market